
 USA Ophthalmic Devices Market | 2026-2036
USA Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
USA Ophthalmic Devices Market Analytics
Outpatient clinics is bifurcating demand away from traditional hospital purchasing committees, creating parallel procurement channels with distinct price sensitivities and service expectations. Alcon Inc. dominates the intraocular lens segment through manufacturing scale and surgeon training ecosystems. Johnson & Johnson Vision Care leverages its contact lens portfolio to sustain recurring revenue streams against capital-intensive surgical competitors.
Ophthalmic devices encompass precision-engineered instruments, implants, and diagnostic systems designed for ocular examination, surgical intervention, and vision correction, typically manufactured to tolerances within micrometers and sterilized for intraoperative use. Optical Coherence Tomography systems now anchor diagnostic workflows with non-invasive cross-sectional retinal imaging at resolutions approaching five micrometers. Cataract Surgery applications occupy the largest revenue pool among procedure types, while Virtual Reality Sequences in vision therapy and surgical planning represent the fastest-growing technology segment as software-enabled care models expand reimbursement pathways.
FDA premarket notification requirements and ISO 13485 quality management standards govern device approval and manufacturing compliance, creating substantial barriers to market entry that favor established players with dedicated regulatory affairs infrastructure. CMS national coverage determinations and state-level Medicaid vision benefits directly shape provider purchasing decisions and patient access thresholds. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled diagnostic devices, as algorithm-based retinal screening tools threaten to restructure referral patterns and capital allocation across the care continuum.
Market Dynamics
CMS reimbursement shifts toward ambulatory surgical centers are redirecting capital flows away from hospital systems, compressing procurement timelines and fragmenting purchasing authority across outpatient networks.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for minimally invasive glaucoma surgery devices compress time-to-market for novel implants. Manufacturers leverage this status to secure earlier CMS coverage determinations.
- Sun Belt Demographics:Florida, Arizona, and Texas concentrate aging populations with elevated cataract and macular degeneration prevalence. Ambulatory surgical center expansion in these states creates dense procedure clusters.
- Optical Coherence Tomography Resolution Advances:Five-micrometer cross-sectional imaging capabilities anchor diagnostic workflows. Retinal specialists now demand these systems as standard-of-care infrastructure.
Market Restraints
- Single-Use Instrument Cost Structure:Premium polymers and precision-machined metals drive per-procedure material costs. Reusable alternatives face sterilization validation burdens that offset savings.
- ISO 13485 Compliance Infrastructure:Dedicated quality management systems require sustained regulatory affairs staffing. Early-stage manufacturers exhaust capital on documentation before commercial traction.
- Phacoemulsification Equipment Concentration:Three dominant suppliers control ultrasonic handpiece and fluidics technology. Pricing power concentrates with incumbent platform ecosystems.
Strategic Opportunities
- AI-Enabled Retinal Screening:Algorithm-based diagnostic tools threaten to restructure referral patterns from optometry to ophthalmology. FDA guidance on software-as-medical-device classification will determine market entry timing.
- Virtual Reality Vision Therapy:Software-enabled rehabilitation protocols expand reimbursement pathways beyond surgical intervention. Payers increasingly cover these modalities for amblyopia and post-surgical recovery.
- Medicaid Vision Benefit Expansion:State-level coverage for adult eye examinations creates access thresholds for previously uninsured populations. Manufacturers can target volume pricing to state procurement authorities.
Industry Challenges
- Surgeon Training Pipeline Constraints:Fellowship programs produce insufficient glaucoma and retina specialists to match device deployment. Manufacturers must absorb training costs through proctoring and simulation infrastructure.
- Interoperability with Legacy EMR Systems:Diagnostic imaging platforms require custom integration with hospital and ambulatory record architectures. Implementation timelines extend revenue recognition cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Ophthalmic Devices Market |
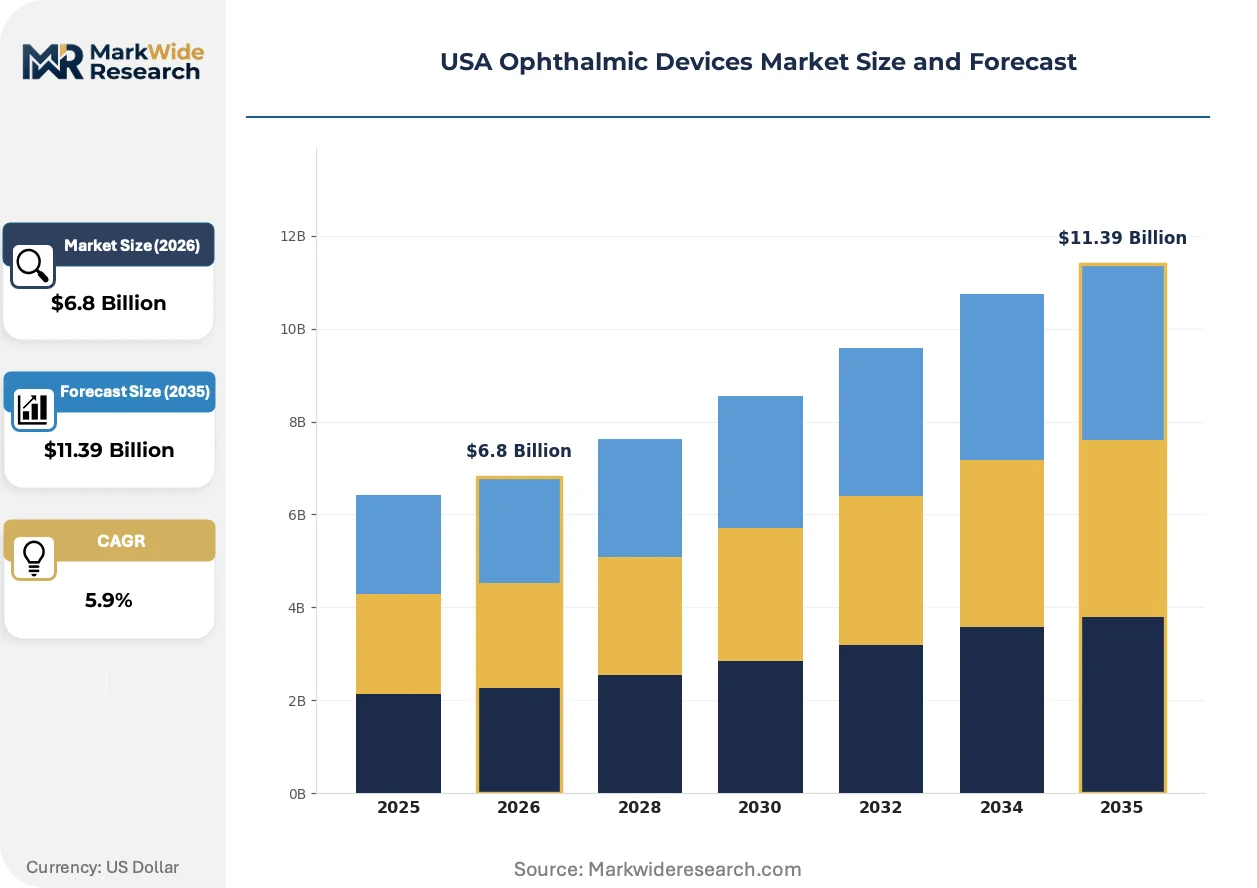
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Lenses, Intraocular Lenses, Surgical Instruments, Diagnostic Devices Application: Cataract Surgery, Refractive Surgery, Glaucoma Treatment, Eye Examinations End User: Hospitals, Outpatient Clinics, Optical Retailers, Research Institutions Technology: Laser Surgery, Optical Coherence Tomography, Phacoemulsification, Virtual Reality Sequences |
| Companies Covered | Carl Zeiss Meditec AG, Glaukos Corporation, Alcon Inc., TOPCON Corporation, CooperVision Inc., Johnson & Johnson Vision Care, EssilorLuxottica, Ziemer Ophthalmic Systems AG, Bausch + Lomb Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Ophthalmic Devices Market Evolving Landscape
Femtosecond laser platforms and extended-depth-of-focus intraocular lenses are compressing traditional procedure boundaries, while artificial intelligence diagnostic tools restructure clinical workflows and capital allocation priorities.
Extended-depth-of-focus intraocular lenses are supplanting monofocal and traditional multifocal designs in premium cataract procedures. Ambulatory surgical centers in Texas and Florida adopt these implants at accelerating rates to differentiate service offerings. The technology is compressing patient out-of-pocket spending on spectacle correction while elevating per-procedure device revenue.
FDA guidance on artificial intelligence-enabled diagnostic devices is reshaping software validation requirements for retinal screening tools. Manufacturers must demonstrate algorithm performance across diverse patient populations to secure premarket authorization. Ophthalmology practices in California and New York are piloting these systems to triage diabetic retinopathy referrals.
Surgeon preference for consolidated supply relationships is compressing distributor margins and elevating direct manufacturer engagement. Outpatient clinics now negotiate device-procurement contracts independently of hospital purchasing committees. This pattern concentrates in Sun Belt states where ambulatory surgical center networks achieve sufficient scale to command volume pricing.
USA Ophthalmic Devices Market Segmentation
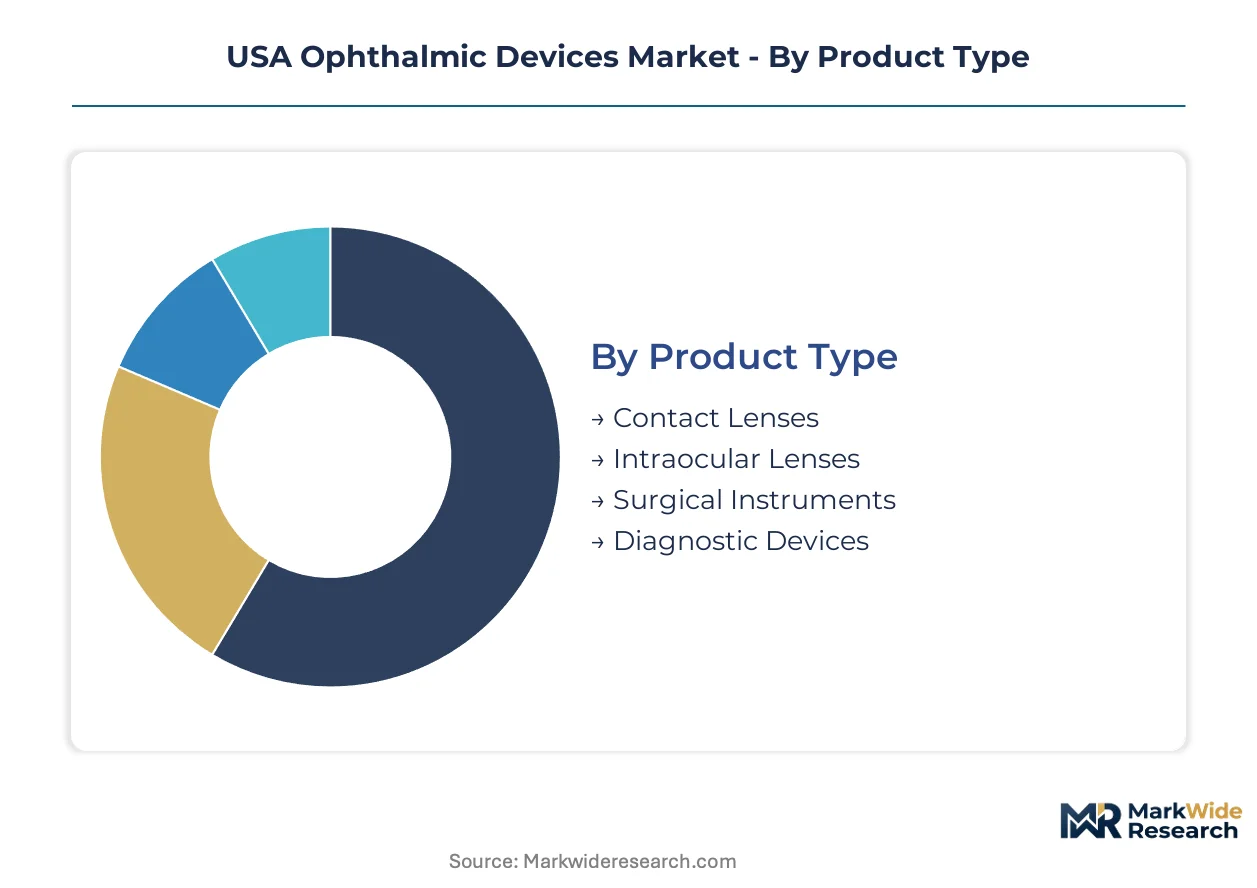
Ophthalmic device procurement patterns diverge sharply across product categories and care settings. CMS reimbursement pathways and FDA device classifications create distinct margin architectures that reward precision targeting.
Product Type:
Margin pools concentrate in implantable segments where surgeon training ecosystems and regulatory barriers protect pricing power.
- Contact Lenses:Hydrogel and silicone hydrogel materials dominate daily disposable and extended-wear formats. Optical retailers in California and Texas drive volume through subscription replenishment models that lock patient loyalty.
- Intraocular Lenses:Precision-molded acrylic and silicone optics with haptic fixation designs enable cataract vision restoration. Ambulatory surgical centers in Florida and Arizona prioritize extended-depth-of-focus variants to differentiate premium service tiers.
- Surgical Instruments:Single-use forceps, cannulas, and viscoelastic delivery systems manufactured to micrometer tolerances. Outpatient clinics absorb per-procedure cost premiums to eliminate sterilization infrastructure.
- Diagnostic Devices:Non-invasive imaging platforms including fundus cameras, tonometers, and aberrometers. Hospital systems in the Northeast anchor capital budgets around Optical Coherence Tomography integration with electronic medical records.
Intraocular lenses hold installed capacity. Contact lenses are rotating up the share rankings.
Application:
Procedure volumes concentrate where aging demographics intersect with ambulatory surgical center expansion.
- Cataract Surgery:Phacoemulsification with intraocular lens implantation constitutes the highest-volume ophthalmic procedure. Texas and Florida surgical networks generate dense procedure clusters through Medicare Advantage contracting.
- Refractive Surgery:Laser-assisted in situ keratomileusis and photorefractive keratectomy reshape corneal curvature. Sun Belt metro areas sustain demand from working-age patients seeking spectacle independence.
- Glaucoma Treatment:Minimally invasive surgical devices and sustained-release drug delivery implants. FDA breakthrough designations are accelerating adoption in outpatient settings previously constrained by reimbursement uncertainty.
- Eye Examinations:Diagnostic screening protocols for diabetic retinopathy and macular degeneration. Medicaid expansion states are extending adult vision benefit coverage to previously uninsured populations.
Cataract surgery commands procedure volume leadership. Glaucoma treatment is climbing the fastest.
End User:
Purchasing authority fragmentation creates parallel procurement channels with divergent price sensitivities.
- Hospitals:Integrated delivery networks with centralized value analysis committees and extended capital cycles. Academic medical centers in the Northeast and Midwest anchor training program procurement.
- Outpatient Clinics:Ambulatory surgical centers and ophthalmology practices with compressed decision timelines. Sun Belt states concentrate independent contracting as networks achieve volume scale.
- Optical Retailers:Chain and independent dispensaries managing contact lens inventory and refractive screening. California and New York host the densest retail footprints.
- Research Institutions:University laboratories and contract research organizations validating novel diagnostic algorithms. FDA premarket submission data originates from these sites.
Outpatient clinics hold installed capacity. Optical retailers are rotating up the share rankings.
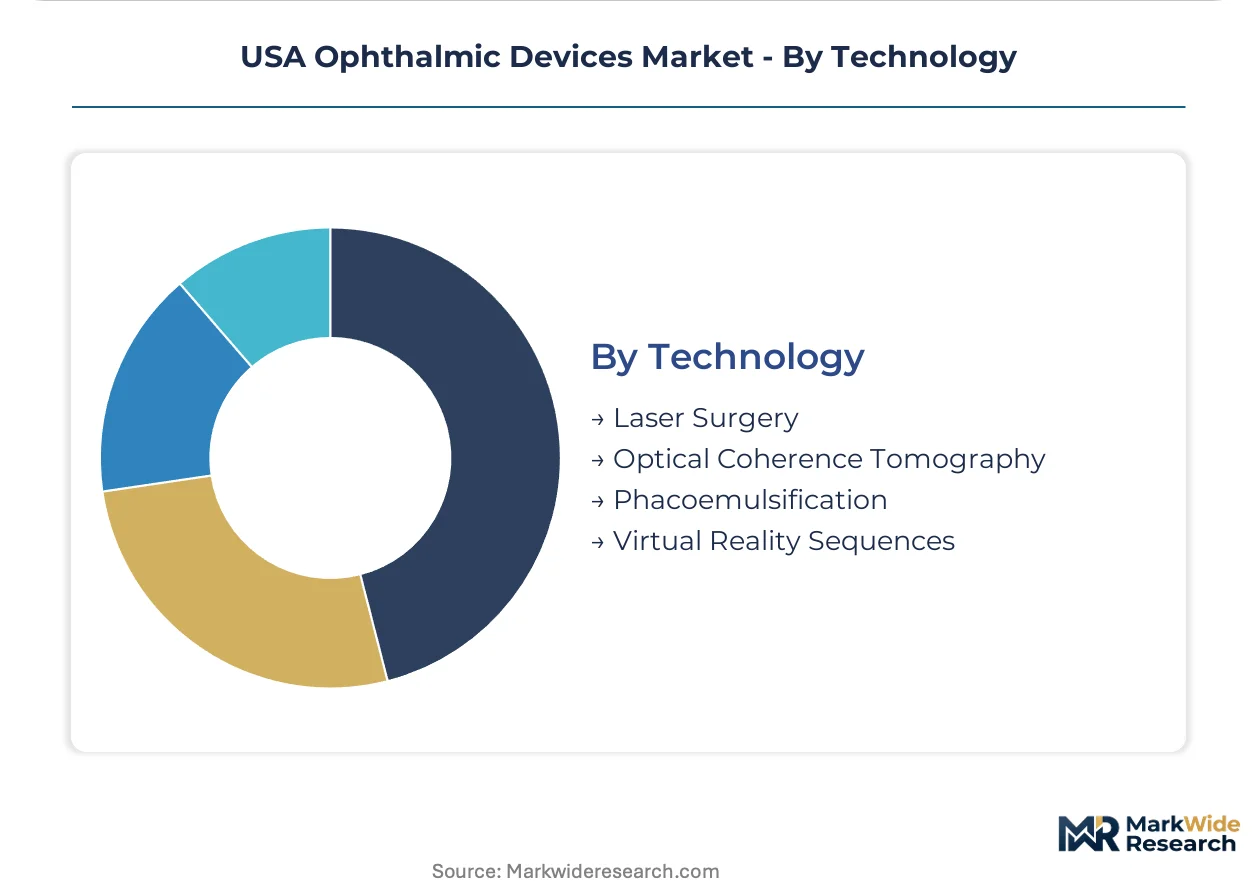
Technology:
Platform ecosystems determine competitive positioning through surgeon training and consumable lock-in.
- Laser Surgery:Femtosecond and excimer platforms for corneal flap creation and stromal ablation. Refractive surgery centers in metropolitan Texas and California compete on technology refresh cycles.
- Optical Coherence Tomography:Spectral-domain and swept-source systems delivering five-micrometer retinal resolution. Retina specialists in academic centers demand these as standard-of-care infrastructure.
- Phacoemulsification:Ultrasonic handpiece and fluidics systems for cataract lens fragmentation. Three dominant suppliers control platform ecosystems through proprietary consumable compatibility.
- Virtual Reality Sequences:Software-enabled vision therapy and surgical simulation protocols. Payers in select states are expanding reimbursement for amblyopia rehabilitation and post-operative recovery.
Phacoemulsification holds installed capacity. Virtual reality sequences are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration varies sharply across US sub-regions. Hospital systems in the Northeast and Midwest retain centralized purchasing authority, while Sun Belt ambulatory surgical centers negotiate directly with manufacturers. This bifurcation creates parallel procurement channels with distinct pricing architectures and service expectations.
California
Optical retailers and refractive surgery centers drive contact lens and laser platform demand. FDA breakthrough device designations accelerate minimally invasive glaucoma surgery adoption in Los Angeles and San Francisco metro areas. AI-enabled retinal screening pilots in academic medical centers are restructuring diabetic retinopathy referral workflows.
Texas
Medicare Advantage contracting concentrates cataract procedure volumes in Dallas-Fort Worth and Houston surgical networks. Ambulatory surgical center expansion creates dense implant clusters with compressed procurement timelines. Extended-depth-of-focus intraocular lens adoption differentiates premium service tiers in metropolitan markets.
Florida
Aging demographics elevate cataract and macular degeneration prevalence across the peninsula. CMS reimbursement shifts toward outpatient settings redirect capital flows from hospital systems to independent surgical centers. Miami and Tampa Bay host the densest concentration of ophthalmology practices negotiating direct manufacturer contracts.
Arizona
Retiree migration patterns sustain high-volume cataract surgery demand in Phoenix and Tucson markets. Sun Belt ambulatory surgical center networks achieve sufficient scale to command volume pricing on phacoemulsification platforms. Surgeon training infrastructure concentrates in academic-affiliated centers serving the Southwest region.
Northeast Corridor
Academic medical centers in Boston and New York anchor training program procurement for diagnostic imaging platforms. Hospital value analysis committees extend capital cycles for Optical Coherence Tomography integration with electronic medical records. Research institutions validate novel diagnostic algorithms for FDA premarket submission data.
USA Ophthalmic Devices Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with dedicated ophthalmology divisions. Three dominant suppliers control phacoemulsification platform ecosystems through proprietary consumable compatibility. Strategic archetypes include scale-driven manufacturers with surgeon training infrastructure, precision optics specialists with diagnostic imaging portfolios, and contact lens incumbents with recurring revenue models. Competitive moves concentrate on direct-to-outpatient contracting and AI-enabled diagnostic software validation.
Within the diversified conglomerate tier, Alcon Inc., Johnson & Johnson Vision Care, and EssilorLuxottica occupy positions defined by manufacturing scale and distribution breadth. Alcon exemplifies the surgical implant archetype through intraocular lens and phacoemulsification platform integration. Johnson & Johnson Vision Care represents the recurring revenue model through contact lens subscription infrastructure. EssilorLuxottica anchors the optical retail integration vector combining lens manufacturing with dispensary network control.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Glaukos Corporation |
| Alcon Inc. |
| TOPCON Corporation |
| CooperVision Inc. |
| Johnson & Johnson Vision Care |
| EssilorLuxottica |
| Ziemer Ophthalmic Systems AG |
| Bausch + Lomb Corp. |
| Others |
Value Network & Pricing Analysis
Extended-depth-of-focus intraocular lenses displacing monofocal designs are simultaneously relocating procurement authority to Sun Belt ambulatory surgical centers and compressing per-procedure margins through volume-based contracting. This substitution dynamic concentrates pricing power with manufacturers possessing surgeon training ecosystems while fragmenting downstream negotiation leverage.
Pricing Analysis
Technology-generation pricing gaps separate femtosecond laser platforms from conventional phacoemulsification systems and from emerging AI-enabled diagnostic tools. Three-tier pricing structure across premium, standard, and economy levels governs intraocular lens segments, with differentiation driven by optical performance specifications and FDA breakthrough device status. Pricing pressure stems from outpatient clinic consolidation demanding volume discounts. Hospital systems exhibit lowest price sensitivity due to extended capital cycles, while independent ambulatory surgical centers negotiate aggressively on per-procedure consumables.
Supply Chain Analysis
Germany and Switzerland anchor precision optics manufacturing for diagnostic imaging platforms, while Ireland and Singapore concentrate contact lens polymer production. Supply chains draw from rare earth elements for laser crystal fabrication, medical-grade silicone for intraocular lens optics, and specialty polymers for single-use surgical instruments. Single-source vulnerability concentrates in ultrasonic handpiece transducer supply. Distribution runs through manufacturer-direct sales organizations serving ambulatory surgical centers alongside GPO-mediated hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across outpatient procurement channels creates specialized entry points for differentiated device categories, as ambulatory surgical center expansion fragments purchasing authority away from consolidated hospital systems.
For Market Incumbents: Fortify surgeon training infrastructure to protect intraocular lens pricing power against emerging minimally invasive glaucoma surgery entrants. Deepen backward integration into precision-machined component manufacturing to offset single-use instrument cost compression. Lock in ambulatory surgical center networks through exclusive consumable compatibility agreements before competitor platform ecosystems achieve critical mass.
For New Entrants and Emerging Players: Lead with AI-enabled retinal screening tools targeting optometry-to-ophthalmology referral workflows in California and New York pilot markets. Exploit reimbursement pathway expansion for virtual reality vision therapy in Medicaid expansion states. Pursue direct-to-outpatient contracting models bypassing GPO infrastructure entirely.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform ecosystem plays over point-solution devices. Long-term viability centers on manufacturers controlling both diagnostic imaging and surgical intervention workflows. Target acquisition archetypes include precision optics specialists with FDA breakthrough device pipelines and software-enabled diagnostic platforms with validated algorithms. Monitor CMS national coverage determinations for minimally invasive glaucoma surgery as inflection signal. Recalibration cycles align with material shifts in reimbursement policy and ambulatory surgical center licensing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated review compresses time-to-market for novel glaucoma implants. |
| Hospital System Partnership | Academic medical centers anchor training program procurement for OCT platforms. |
| Software Companion Development | AI-enabled screening tools restructure diabetic retinopathy referral patterns. |
| Reimbursement Strategy | CMS coverage determinations shape provider purchasing decisions directly. |
| CE Marking Pathway | European regulatory approval enables manufacturing scale efficiencies. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across ophthalmology practices, ambulatory surgical center administrators, hospital purchasing committees, biomedical engineers, and GPO contracts managers. Secondary validation incorporated FDA 510(k) filings, CMS national coverage determinations, hospital procurement databases, and ambulatory surgical center licensing records. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations.
Across the analysis window, forecasts model product type, application, end user, and technology segments with regional resolution to state level. CAGRs derive from procedure volume trajectories, device replacement cycles, and reimbursement elasticity assumptions. Inputs include Medicare Advantage contracting patterns, ambulatory surgical center expansion pipelines, and FDA premarket approval timelines.
Forecasts assume regulatory continuity in FDA and CMS regimes; material policy shifts would require re-modeling. Specific risks include AI-enabled device reclassification, state Medicaid vision benefit retrenchment, and phacoemulsification platform ecosystem lock-in effects. Recalibration cycles align with material shifts in reimbursement policy and ambulatory surgical center licensing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Retinal Vein Occlusion Treatment Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Ophthalmic Eye Drops Market
Ophthalmology
Global Ophthalmology Market
Ophthalmology
Global Ophthalmoplegia Market
Ophthalmology
Global Therapeutic Lenses Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market
Ophthalmology
Bullous Keratopathy Market
Ophthalmology
Optometry/Eye Exam Equipment Market
Ophthalmology
Retina Health Market
Ophthalmology
Orthokeratology Market
Ophthalmology
Ophthalmic Tonometers Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Laser Indirect Ophthalmoscope Market
Ophthalmology
Personalized LASIK Surgery Market