
 Global Tonometer Market | 2026-2036
Global Tonometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tonometer Market Foresight
Buyer concentration among ophthalmic clinics is shifting toward larger multi-site eye care networks that standardize diagnostic platforms across locations. Topcon Corporation leverages its geographic dominance in Asia-Pacific to sustain instrument placement growth in high-volume screening programs. Reichert Technologies differentiates through rebound technology leadership, while Carl Zeiss Meditec anchors the premium aplanation segment with integrated optical coherence tomography workstations.
A tonometer measures intraocular pressure through corneal applanation, air-puff deformation, or rebound indentation, typically operating within a measurement range of 0 to 80 mmHg with precision requirements of plus or minus 0.5 mmHg for clinical validity. Non-contact pneumatic systems dominate high-throughput screening due to reduced infection risk and operator independence, while rebound devices represent the fastest-growing category as handheld portability expands community-based glaucoma detection in underserved regions. Electronic piezoelectric sensors command margin pools in post-operative care settings where continuous pressure monitoring justifies premium pricing.
FDA Class II device controls and EU MDR technical documentation requirements shape product development timelines and market access costs for manufacturers seeking dual-territory approval. ISO 8612 calibration standards and CE marking obligations under the EU Medical Device Regulation enforce traceable measurement accuracy that limits low-cost competitor entry. Stakeholders must monitor evolving reimbursement codes for remote diagnostic interpretation and decide whether software-enabled connectivity investments justify hardware margin compression.
Market Dynamics
Reimbursement compression for diagnostic procedures is forcing tonometer manufacturers to absorb hardware margin erosion while accelerating software-enabled service revenue streams.
Growth Catalysts
- EU MDR technical documentation:Stricter CE marking requirements under the EU Medical Device Regulation are filtering out low-accuracy competitors and consolidating procurement toward validated suppliers in German hospital networks.
- Rebound indentation technology:Handheld rebound devices are penetrating community screening programs in rural Japan where portability enables nurse-led glaucoma detection without specialized ophthalmology infrastructure.
- Post-operative monitoring protocols:Cataract surgery volume expansion in US ambulatory surgery centers is driving demand for continuous pressure monitoring capabilities in premium electronic piezoelectric systems.
Market Restraints
- Optical component supply concentration:Precision lenses and infrared sensors concentrate among Japanese and German optical specialists, exposing manufacturers to input cost volatility and allocation constraints.
- FDA 510(k) pathway friction:Software-as-medical-device classification for AI-enabled tonometry interpretation is extending clearance timelines and inflating regulatory consulting expenditure for dual-territory applicants.
- Goldmann applanation substitution ceiling:Established clinicians in academic medical centers exhibit persistent preference for slit-lamp integrated aplanation systems, limiting penetration of non-contact alternatives in prestige segments.
Strategic Opportunities
- Telemedicine reimbursement codes:Remote diagnostic interpretation coverage expansion in US Medicare Advantage plans creates white space for cloud-connected tonometer platforms with automated pressure trend analysis.
- India community health worker deployment:National blindness control program procurement channels are opening for sub-$500 handheld rebound devices validated under BIS medical electronics standards.
- OCT-tonometry convergence:Integration of rebound sensors into swept-source optical coherence tomography workstations is enabling single-position diagnostic workflows in high-volume Japanese screening centers.
Industry Challenges
- Biomedical calibration technician scarcity:ISO 8612 traceable calibration requirements exceed technician training availability in secondary markets, forcing manufacturers to deploy direct service infrastructure or risk measurement drift liability.
- Legacy EMR integration complexity:DICOM and HL7 FHIR connectivity implementation for hospital information system compatibility demands specialized software engineering capacity that mid-tier manufacturers struggle to staff.
- Patent thickets around corneal biomechanics correction:Disputes over algorithms compensating for corneal thickness and hysteresis are complicating product development roadmaps and inflating licensing negotiation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tonometer Market |
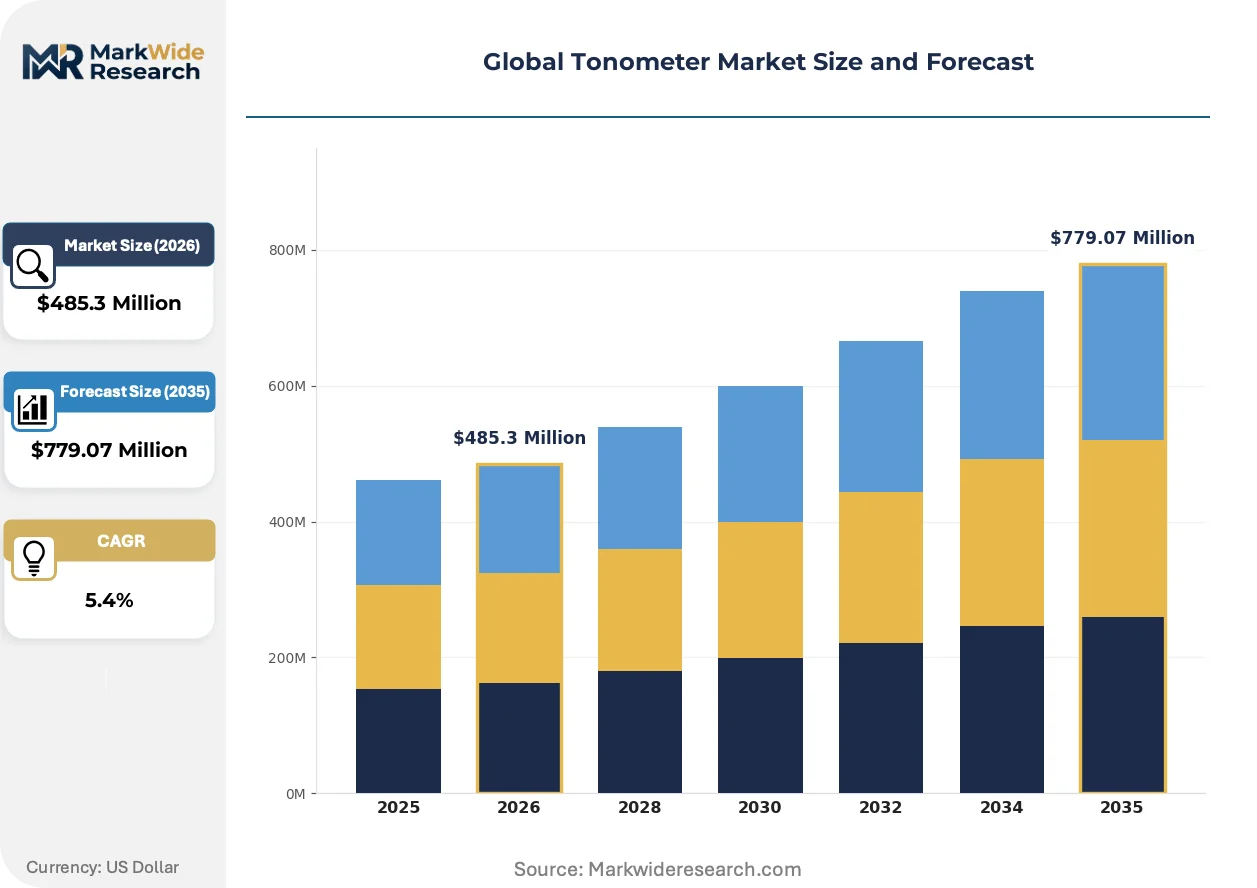
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $779.07 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aplanation, Non-Contact, Tactile, Rebound, Dynamic Contour Technology: Optical, Pneumatic, Electronic, Piezoelectric, Capacitive Application: Glaucoma Screening, Intraocular Pressure Monitoring, Corneal Thickness Measurement, Post-Operative Care, Eye Injury Assessment End User: Ophthalmic Clinics, Eye Research Institutes, Eye Care Specialists, Diagnostic Laboratories |
| Companies Covered | Topcon Corporation, Haag-Streit Group, Reichert Technologies, Revenio Group, Carl Zeiss Meditec, Nidek Co. Ltd., AMETEK Inc., Keeler Ltd., Tomey Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tonometer Market Shifts & Advancements
Software-enabled diagnostic interpretation is displacing standalone hardware value capture, while sensor miniaturization and connectivity protocols are redefining deployment settings across the care continuum.
Rebound indentation technology is consolidating screening market share as handheld iCare and similar devices enable non-specialist operation in community pharmacies and primary care clinics. Hospital systems in Germany and Japan are standardizing on these platforms for high-volume glaucoma detection programs. The structural consequence is compressing demand for traditional slit-lamp mounted aplanation systems in screening applications while expanding addressable market volume.
FDA software-as-medical-device guidance and EU MDR Annex VIII classification rules are tightening validation requirements for AI-enabled pressure interpretation algorithms. Manufacturers must now submit clinical performance studies demonstrating diagnostic accuracy equivalence to predicate devices. This regulatory tightening most affects cloud-connected tonometer platforms targeting US and EU hospital procurement, where cybersecurity documentation and algorithm transparency are becoming gatekeeping criteria.
After-sales service unbundling is emerging as procurement departments in US multi-site eye care networks separate hardware acquisition from calibration contracts and software subscription renewals. Third-party ISO 17025 accredited laboratories are capturing calibration volume previously captive to original equipment manufacturers. This disaggregation is most visible in California and Texas ophthalmology chains, where finance departments favor operational expenditure treatment over capital equipment depreciation.
Global Tonometer Market Segmentation
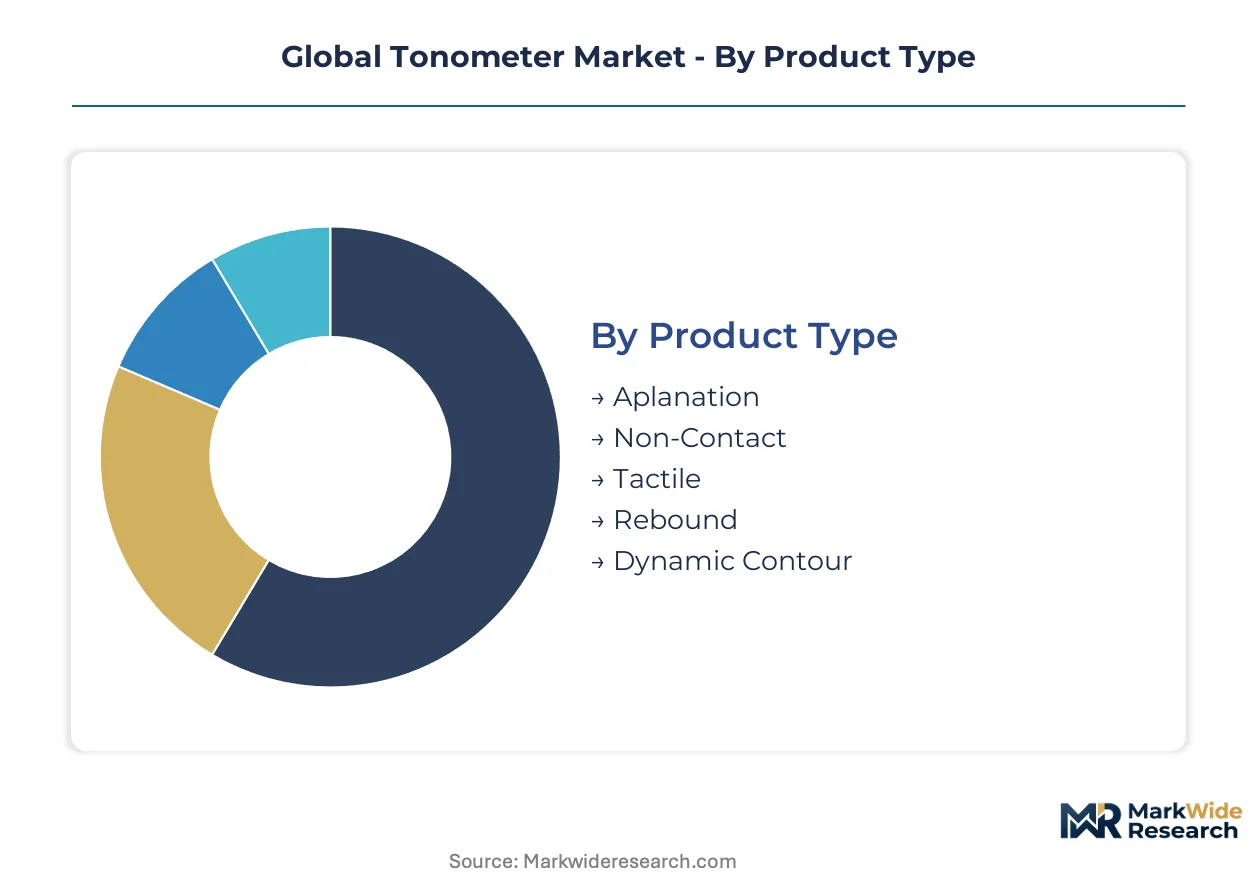
Tonometer procurement decisions hinge on workflow throughput, operator skill availability, and reimbursement structure. Segment boundaries blur as multi-modal platforms enter hospital tenders, yet distinct technology categories retain separate margin pools and service attachment rates.
Product Type:
Standardization dominates high-volume screening contracts, while customization persists in academic medical centers requiring modular slit-lamp integration.
- Aplanation:Goldmann-style devices employ corneal flattening with calibrated force application through slit-lamp mounting. Demand concentrates in German university hospitals where clinician training traditions sustain preference for direct visualization protocols despite longer examination times.
- Rebound:Handheld probes utilize induction-based motion sensing of a magnetized probe contacting the cornea. Expansion is steepest in Japanese community screening programs where nurse-led deployment eliminates ophthalmologist bottlenecks in rural prefectures.
- Non-Contact:Air-puff systems measure applanation timing via Scheimpflug imaging without patient contact. US ambulatory surgery centers favor these for infection control in high-throughput cataract pre-operative workflows.
- Tactile:Digital palpation devices estimate pressure through eyelid compression with force-sensitive resistors. Budget-constrained diagnostic laboratories in India deploy these for triage before specialist referral.
- Dynamic Contour:Contour-matching tonometry maintains constant corneal shape through piezo-controlled applanation. Post-operative care units in Swiss tertiary centers adopt these for continuous monitoring after penetrating keratoplasty.
Most installed capacity flows through Non-Contact systems. Expansion is steepest in Rebound devices.
Technology:
Cost tier separation runs from commodity sensor assemblies to precision optical subsystems requiring Japanese specialist supply chains.
- Optical:Scheimpflug and placido-based imaging systems capture corneal deformation patterns through structured light projection. German hospital networks standardize on these for integrated glaucoma-workflow efficiency combining topography with pressure measurement.
- Piezoelectric:Ceramic transducers convert mechanical strain to electrical signals with microsecond response times. Premium positioning in US post-operative monitoring justifies hardware margins through continuous pressure trending capabilities.
- Electronic:Strain-gauge load cells deliver analog-to-digital conversion for basic pressure quantification. Volume production in Chinese manufacturing clusters supplies price-sensitive screening programs across Southeast Asia.
- Pneumatic:Regulated air-pulse generation systems control pressure application through solenoid valve timing. Japanese OEMs dominate component supply for non-contact platform manufacturers globally.
- Capacitive:Proximity-sensing electrodes detect corneal displacement without mechanical contact. Emerging adoption in telemedicine platforms targets FDA software-as-medical-device clearance for remote interpretation.
Electronic assemblies capture volume share. Piezoelectric platforms command margin concentration.
Application:
Customer type stratification separates episodic screening reimbursement from chronic disease management billing codes.
- Glaucoma Screening:Population-scale detection programs require high-throughput platforms with minimal operator dependence. Japan's prefectural health authorities deploy rebound devices through pharmacy-based screening networks.
- Post-Operative Care:Cataract and corneal transplant recovery protocols demand continuous pressure surveillance. US ambulatory surgery centers generate recurring calibration contract revenue for manufacturers through Medicare reimbursement stability.
- Intraocular Pressure Monitoring:Diurnal variation tracking supports treatment adjustment in established glaucoma patients. German statutory health insurance covers home-monitoring devices with telemedicine connectivity.
- Corneal Thickness Measurement:Pachymetry-integrated tonometry corrects pressure readings for biomechanical properties. Academic medical centers in Switzerland require these for refractive surgery candidacy assessment.
- Eye Injury Assessment:Emergency department triage protocols utilize non-contact methods to avoid pressure on compromised globes. Level I trauma centers in Texas standardize these for chemical and blunt trauma protocols.
Glaucoma Screening absorbs the majority of unit placements. Post-Operative Care generates the highest service attachment rates.
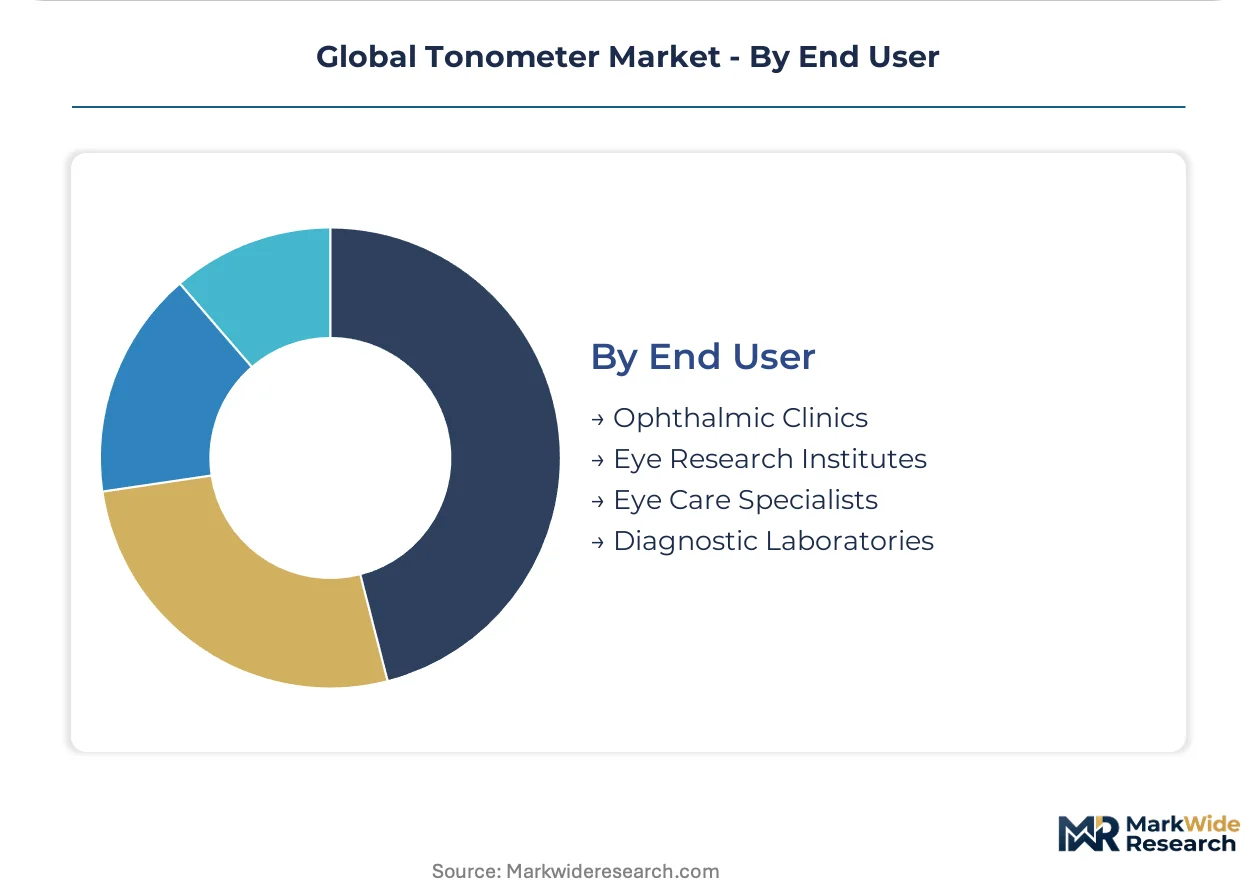
End User:
Geography drives concentration as reimbursement density and specialist availability vary across healthcare systems.
- Ophthalmic Clinics:Multi-site eye care networks in California and Texas pursue platform standardization across locations to reduce training overhead and service contract complexity.
- Eye Care Specialists:Individual practitioners and small group practices prioritize handheld portability for office efficiency and satellite location coverage.
- Eye Research Institutes:Academic centers in Germany and Japan require research-use-only configurations with raw data export for algorithm development.
- Diagnostic Laboratories:Centralized testing facilities in India process high-volume screening referrals from community health workers using basic tactile devices.
Ophthalmic Clinics represent the dominant procurement channel. Diagnostic Laboratories are climbing the fastest as India's national blindness control program scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan demonstrate contrasting procurement philosophies despite comparable aging demographics, with German hospital networks favoring integrated diagnostic workstations while Japanese prefectures prioritize portable screening deployment.
United States
Medicare Advantage reimbursement expansion for remote diagnostic interpretation is accelerating cloud-connected platform procurement among California and Texas multi-site eye care networks. FDA software-as-medical-device guidance for AI-enabled tonometry interpretation is extending clearance timelines for dual-territory applicants. The Dallas-Fort Worth corridor concentrates ambulatory surgery center demand for infection-control-optimized non-contact systems in high-volume cataract pre-operative workflows.
Germany
Statutory health insurance coverage for home-monitoring devices with telemedicine connectivity is expanding intraocular pressure monitoring reimbursement beyond clinical settings. EU MDR technical documentation requirements under CE marking obligations are filtering low-accuracy competitors from hospital procurement tenders. Bavarian university hospitals sustain preference for slit-lamp integrated applanation systems where clinician training traditions prioritize direct visualization protocols.
Japan
Prefectural health authority deployment of pharmacy-based screening networks is driving handheld rebound device volume through nurse-led glaucoma detection programs in rural prefectures. METI industrial standards for medical electronics are shaping domestic manufacturer product development roadmaps. The Kansai region around Osaka concentrates high-volume screening center demand for OCT-tonometry converged workstations enabling single-position diagnostic workflows.
India
National blindness control program procurement channels are opening for sub-$500 handheld rebound devices validated under BIS medical electronics standards. CDSCO medical device registration requirements are formalizing import pathways for international manufacturers targeting community health worker deployment. Diagnostic laboratories in Maharashtra process high-volume screening referrals from basic tactile device triage performed by accredited social health activists in rural districts.
Switzerland
Post-operative care units in tertiary centers are adopting dynamic contour tonometry for continuous pressure monitoring after penetrating keratoplasty procedures. Swissmedic device authorization requirements enforce traceable calibration standards that limit low-cost competitor market entry. The Zurich-Geneva corridor concentrates academic medical center demand for pachymetry-integrated systems correcting pressure readings for corneal biomechanical properties in refractive surgery candidacy assessment.
Global Tonometer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, with optical instrumentation conglomerates leveraging integrated diagnostic platform portfolios against handheld device specialists emphasizing portability and community deployment economics. Market structure concentrates among Japanese and German precision optics manufacturers with captive sensor supply chains, while mid-tier competitors face margin compression from calibration service unbundling and third-party ISO 17025 laboratory competition. Two dominant archetypes emerge: vertically integrated optical conglomerates with multi-modal diagnostic portfolios, and rebound technology specialists with handheld portability positioning. Competitive moves center on strategic partnerships for EMR connectivity integration and geographic expansion through distributor networks in underserved screening markets.
Within the precision optics conglomerate tier, Topcon Corporation and Carl Zeiss Meditec occupy positions anchored in geographic dominance and premium workstation integration respectively. Reichert Technologies exemplifies the rebound technology specialist archetype with handheld portability positioning. These three entities represent the structural poles of competitive positioning: Asia-Pacific instrument placement scale, European premium diagnostic integration, and North American portable screening innovation.
| Leading Market Players |
|---|
| Topcon Corporation |
| Haag-Streit Group |
| Reichert Technologies |
| Revenio Group |
| Carl Zeiss Meditec |
| Nidek Co. Ltd. |
| AMETEK Inc. |
| Keeler Ltd. |
| Tomey Corporation |
| Others |
Supply & Pricing Matrix
Japanese infrared sensor pricing indices cascade through tonometer manufacturing tiers, compressing margins for non-contact platform producers while amplifying pricing power for German and Japanese optical conglomerates with captive piezoelectric component supply. FDA 510(k) clearance costs and EU MDR technical documentation fees stratify procurement thresholds, forcing mid-tier manufacturers toward economy positioning or exit.
Pricing Analysis
Capacity additions in Chinese electronic sensor foundries are reshaping price floors for entry-level rebound devices, yet premium piezoelectric systems retain hardware margins through post-operative care reimbursement stability in US ambulatory surgery centers. Pricing stratifies across premium, standard, and economy tiers defined by ISO 8612 calibration certification and after-sales service bundling. Cost compression in standard-tier non-contact systems intensifies because third-party ISO 17025 laboratories disaggregate calibration revenue from original equipment manufacturers. Diagnostic laboratories in India exhibit highest price sensitivity, while Swiss tertiary centers demonstrate lowest sensitivity due to continuous monitoring protocol requirements.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for medical electronics are reshaping sourcing patterns for handheld rebound device manufacturers targeting community health worker deployment. Precision lens and infrared sensor supply concentrates in Japan, Germany, and South Korea, with tonometer production drawing from ceramic transducer specialists in Nagoya and optical glass foundries in Jena. Single-source vulnerability pervades Scheimpflug imaging subsystems, where Japanese OEMs control solenoid valve timing components for pneumatic platforms globally. Distribution runs through ophthalmic instrument distributors in Texas and California, hospital procurement consortiums in Bavaria, and pharmacy-based screening networks in Osaka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU MDR compliance costs in Germany exceed BIS validation expenses in India by multiples, creating margin expansion opportunities for manufacturers with dual-territory regulatory infrastructure.
For Market Incumbents: Hedge against rebound technology commoditization by deepening backward integration into piezoelectric sensor production and securing exclusive hospital system partnerships in California multi-site eye care networks. Software-enabled service revenue streams offset hardware margin erosion from reimbursement compression. Certification investment in FDA software-as-medical-device pathways preserves premium positioning against emerging cloud-connected competitors. For New Entrants and Emerging Players: Launch via distributor networks targeting India's national blindness control program procurement channels for sub-$500 handheld rebound devices validated under BIS medical electronics standards. Pharmacy-based screening networks in rural Japanese prefectures represent the most penetrable white-space deployment setting. Telemedicine reimbursement code expansion in US Medicare Advantage plans enables cloud-connected platform entry with automated pressure trend analysis capabilities. For Investors and Strategic Acquirers: Asymmetric upside sits with rebound technology specialists possessing handheld portability positioning and established distributor relationships in underserved screening markets. Long-term viability hinges on software companion development capabilities and regulatory pathway execution across dual-territory approval frameworks. Watch FDA software-as-medical-device clearance timelines for AI-enabled tonometry interpretation as the inflection indicator for cloud-connected platform valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation requirements filter low-accuracy competitors from German hospital procurement tenders. |
| Hospital System Partnership | Multi-site eye care networks in California and Texas standardize diagnostic platforms to reduce training overhead. |
| Software Companion Development | FDA software-as-medical-device guidance for AI-enabled interpretation extends clearance timelines for dual-territory applicants. |
| Reimbursement Strategy | Medicare Advantage remote diagnostic interpretation coverage expansion creates white space for cloud-connected platforms. |
| Backward Integration | Captive piezoelectric sensor production insulates margin pools from Japanese infrared sensor price volatility. |
Research Methodology
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, and CMS Medicare reimbursement code records; plus customs trade data for ophthalmic instrument imports — were reconciled through bottom-up and top-down triangulation. Clinician interviews across German university hospitals and Japanese prefectural screening centers informed workflow and procurement behavior assessment. Hospital procurement databases and GPO contracts supplied pricing and volume benchmarks.
Historical shipment data cross-referenced against panel input from instrument manufacturers and distributor networks anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type (applanation, rebound, non-contact), technology tier (piezoelectric, optical, electronic), application setting (glaucoma screening, post-operative care), and end-user category (ophthalmic clinics, diagnostic laboratories). CAGRs were derived from regression analysis against cataract surgery volume expansion, aging demographic projections, and reimbursement policy trajectories. Forecast inputs incorporated EU MDR implementation timelines and India's PLI scheme medical electronics production targets.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA software-as-medical-device reclassification delays or abrupt reimbursement code modifications for remote diagnostic interpretation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Ophthalmology Diagnostics Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Ophthalmic Viscosurgical Devices Market
Ophthalmology
Japan Ophthalmic Devices and Drugs Market
Ophthalmology
Corneal Pachymetry Market
Ophthalmology
Dacryocystitis Treatment Market
Ophthalmology
Global Ophthalmic Equipment Market
Ophthalmology
Global Advanced Ophthalmology Technologies Market
Ophthalmology
Ophthalmic Clinical Trials Market
Ophthalmology
Global Retinal Detachment Treatment Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market
Ophthalmology
PVA Eye Spear Market
Ophthalmology
UAE Ophthalmic Devices Market
Ophthalmology
Herpes Simplex Keratitis Treatment Market
Ophthalmology
Non-Infectious Uveitis Treatment Market
Ophthalmology
Global Ophthalmology Drugs and Devices Market