
 Ophthalmic Ultrasound Systems Market | 2026-2036
Ophthalmic Ultrasound Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Ultrasound Systems Market Analysis
Hospital end-user demand is expanding faster than clinic-based purchasing as health systems consolidate ophthalmology service lines into centralized surgical hubs. Carl Zeiss Meditec AG dominates high-end biometry integration with its optical coherence tomography platforms. NIDEK Co. Ltd. competes across Asia-Pacific through localized manufacturing and region-specific regulatory registrations. Halma plc sustains diversified revenue through its portfolio of diagnostic and surgical subsidiaries serving multiple eye care settings.
Ophthalmic ultrasound systems employ high-frequency acoustic transducers, typically 10-20 MHz for posterior segment B-scan imaging and 20-50 MHz for anterior segment pachymetry, to generate cross-sectional visualizations of ocular structures without optical penetration limitations. These devices serve primary commercial purposes in axial length measurement for intraocular lens power calculation, vitreoretinal pathology detection, and corneal thickness assessment prior to refractive surgery. B-scan systems lead product type revenue due to their indispensability in opaque media cases where direct fundus examination fails, while 3D imaging technology captures the fastest growth trajectory as volumetric rendering improves surgical planning precision. Digital technology platforms anchor the installed base but hybrid architectures are displacing analog systems in mid-tier clinics seeking upgrade pathways without full capital replacement.
FDA 510(k) premarket notification requirements govern acoustic output limits and electromagnetic compatibility for systems entering the United States, while CE marking under the EU MDR demands clinical performance documentation and post-market surveillance protocols for European commercialization. Japan's PMDA applies Japan Industrial Standards for medical electrical equipment safety alongside pharmaceutical and medical device-specific quality management audits. Stakeholders must monitor evolving harmonization between ISO 13485 quality systems and national cybersecurity frameworks as connected diagnostic devices proliferate in hospital networks.
Market Dynamics
Hospital consolidation of ophthalmology service lines into centralized surgical hubs is concentrating procurement authority, shifting purchasing decisions from individual clinics toward health system administrators who prioritize interoperability with electronic health records and surgical planning software.
Growth Catalysts
- Aging Demographics:Populations in the United States, Germany, and Japan are expanding the pool of patients requiring cataract and glaucoma screening, driving installed base expansion for biometry and B-scan systems.
- FDA 510(k) Pathway Efficiency:Streamlined premarket notification processes for acoustic output safety validation are accelerating commercialization timelines for manufacturers with established electromagnetic compatibility documentation.
- Hybrid Architecture Adoption:Mid-tier clinics are upgrading from analog to digital-analog hybrid platforms without full capital replacement, extending product lifecycles and creating aftermarket revenue streams.
Market Restraints
- Transducer Manufacturing Concentration:High-frequency piezoelectric crystal supply chains cluster in specialized East Asian component foundries, creating single-source vulnerability for 20-50 MHz anterior segment probes.
- EU MDR Compliance Burden:Enhanced clinical performance documentation and post-market surveillance protocols under CE marking requirements are extending validation timelines and raising regulatory fixed costs for European market entry.
- Optical Coherence Tomography Substitution:Non-contact OCT systems are capturing posterior segment imaging volumes in transparent media cases, compressing addressable demand for traditional B-scan ultrasound in routine screening.
Strategic Opportunities
- 3D Volumetric Rendering:Volumetric acquisition and reconstruction software is automating surgical planning for complex vitreoretinal procedures, commanding premium pricing in academic medical centers.
- India PLI Scheme:Production-linked incentive frameworks for medical device manufacturing are attracting localized assembly investments to serve South Asian and Middle Eastern distribution networks.
- Telemedicine Integration:Cloud-connected diagnostic platforms with remote image interpretation capabilities are opening ambulatory surgery center and rural clinic segments previously inaccessible to capital-intensive equipment vendors.
Industry Challenges
- Sonographer Training Pipeline:Specialized ocular ultrasound interpretation skills require dedicated fellowship pathways, constraining deployment velocity as health systems expand screening programs.
- Legacy PACS Integration:Digital imaging systems must interface with heterogeneous picture archiving and communication infrastructure across hospital networks, complicating implementation timelines and support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Ultrasound Systems Market |
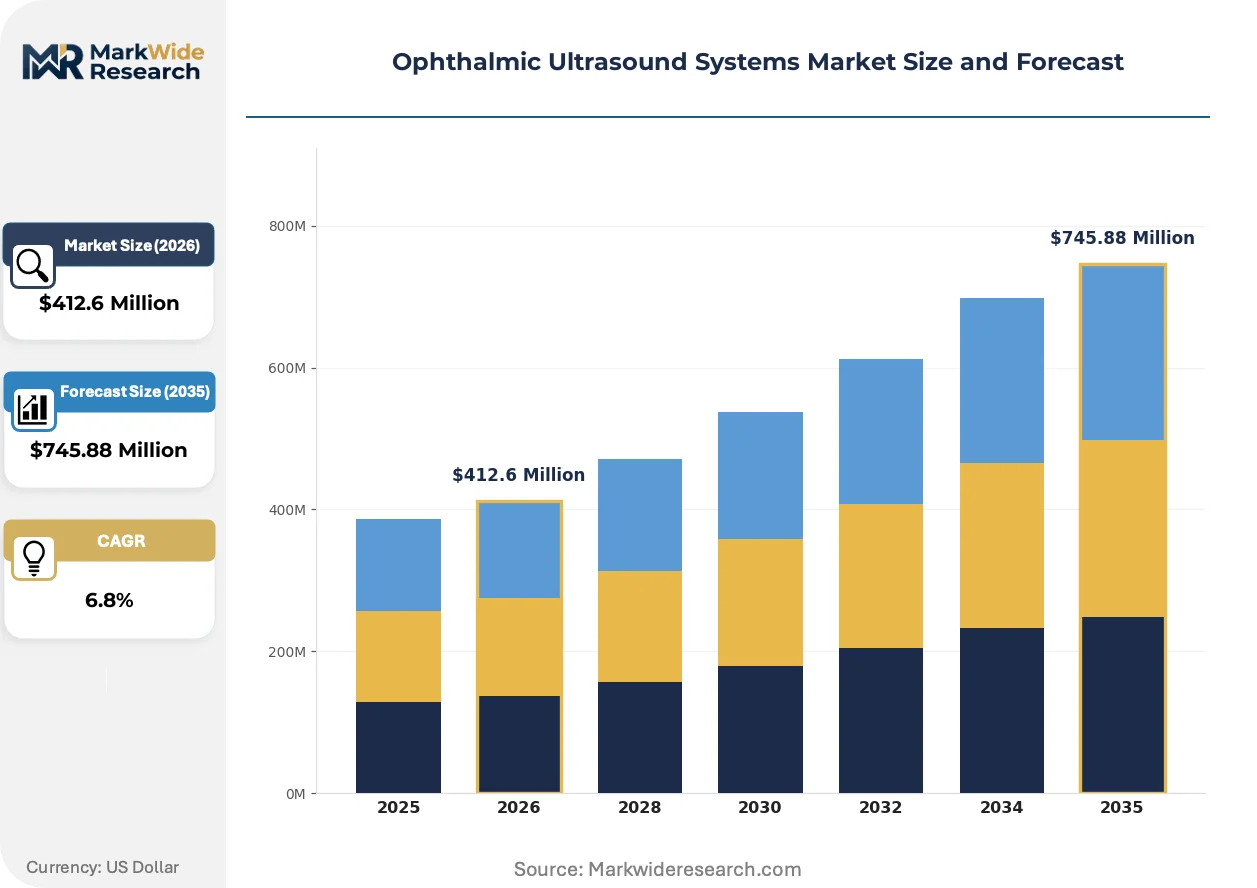
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: A-Scan, B-Scan, Pachymeter, Biometer Technology: Digital, Analog, Hybrid, 3D Imaging End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Application: Glaucoma, Cataracts, Retina Examination, Optical Nerve Assessment |
| Companies Covered | DGH Technology Inc., Appasamy Associates, Carl Zeiss Meditec AG, Optos plc, Halma plc, NIDEK Co. Ltd., Lumibird Medical, Tomey Corporation, Sonomed Escalon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Ultrasound Systems Market Emerging Trajectories
Artificial intelligence integration and connected diagnostic platforms are transforming how ophthalmic ultrasound data is acquired, interpreted, and distributed across care networks. Three developments are restructuring competitive positioning.
Artificial intelligence algorithms embedded in B-scan acquisition software are automating biometric measurement extraction and pathology flagging. Academic medical centers in the United States and Japan are piloting these systems to reduce inter-operator variability in axial length calculation for intraocular lens power determination. The technology is compressing examination duration while standardizing output quality across operator experience levels.
EU MDR post-market surveillance mandates are tightening adverse event reporting requirements for acoustic output safety incidents. Manufacturers serving European markets must now maintain systematic clinical follow-up protocols and periodic safety update reports, increasing compliance infrastructure costs. Mid-sized device firms are responding by narrowing product portfolios to focus on core platforms with established safety profiles.
Health system procurement committees are consolidating vendor relationships through multi-year enterprise agreements spanning ophthalmic diagnostics, surgical equipment, and maintenance services. Independent clinics and smaller hospital networks are losing negotiating leverage as purchasing authority concentrates in regional integrated delivery networks. This pattern is most visible in the United States, where vertical health system integration has accelerated since 2020.
Ophthalmic Ultrasound Systems Market Segmentation
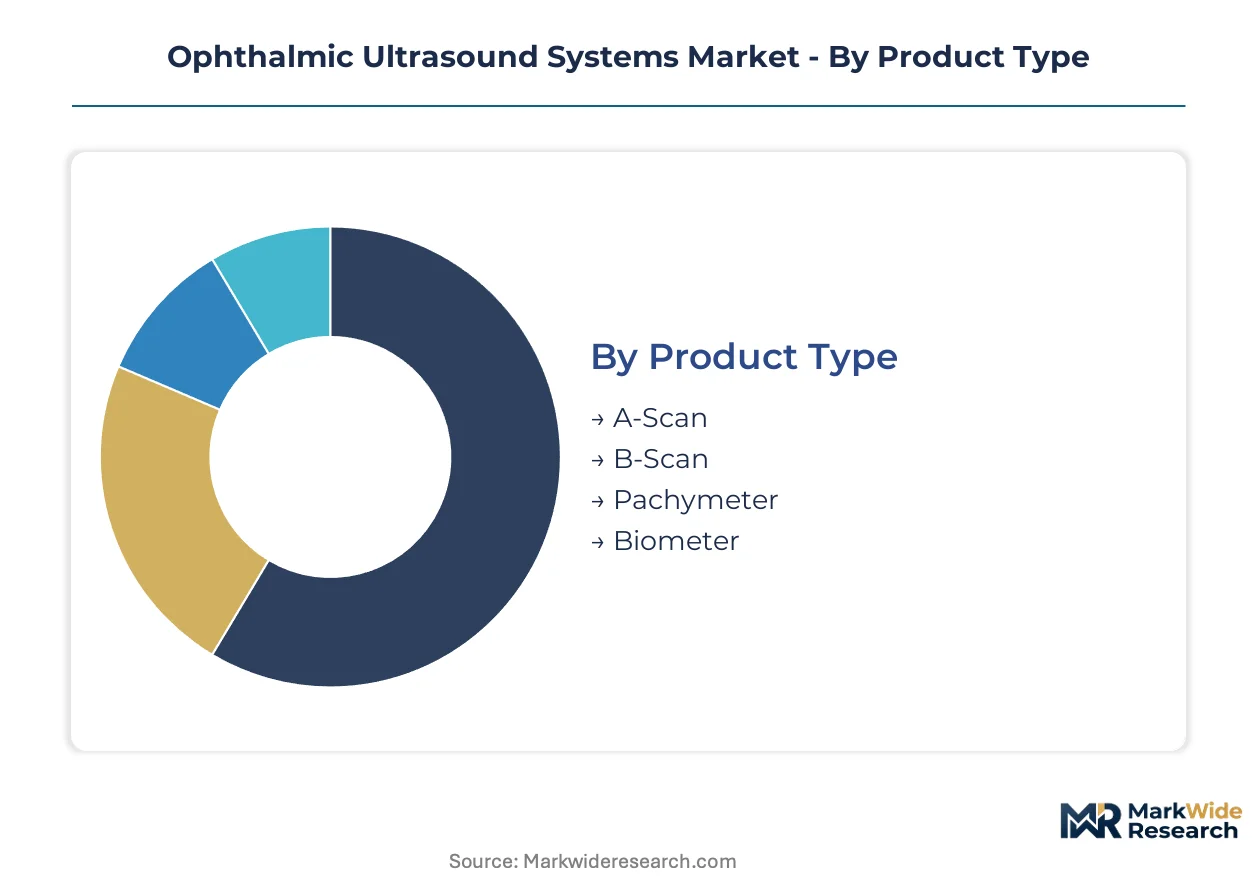
Segmentation in ophthalmic ultrasound systems reveals how procurement authority, clinical workflow requirements, and reimbursement structures fragment demand across care settings. Understanding these divisions exposes where capital deployment concentrates and which technology configurations command premium positioning.
Product Type:
Hospital procurement committees weight capital intensity against surgical throughput when selecting imaging modalities for service line expansion.
- B-Scan:Posterior segment imaging systems utilize 10-20 MHz transducers to visualize vitreoretinal pathology through opaque media where direct fundus examination fails. Demand concentrates in United States academic medical centers expanding trauma and emergency ophthalmology coverage, constrained by sonographer training pipeline bottlenecks.
- Biometer:Axial length measurement systems calculate intraocular lens power for cataract surgical planning with precision reaching 0.01 mm. Germany's statutory health insurance reimbursement structures favor optical biometry, compressing ultrasound biometer volumes to cases with dense cataracts or silicone oil-filled eyes.
- A-Scan:Single-dimensional amplitude scan systems provide basic axial length measurement for resource-constrained settings.
- Pachymeter:Corneal thickness assessment devices support refractive surgery screening and glaucoma progression monitoring.
Volume sits with B-Scan; growth tilts toward Biometer.
Technology:
Mid-tier clinics face upgrade pathway decisions between full capital replacement and incremental digital integration.
- Digital:Fully electronic signal processing platforms deliver real-time image optimization and automated measurement algorithms. United States hospital networks prioritize digital systems for PACS interoperability and electronic health record integration, though legacy infrastructure compatibility extends implementation timelines.
- 3D Imaging:Volumetric acquisition systems reconstruct ocular anatomy from sequential B-scan slices for surgical planning. Japan's PMDA has accelerated clearance pathways for 3D platforms with AI-assisted pathology detection, supporting adoption in high-volume cataract centers.
- Hybrid:Digital-analog architectures preserve existing transducer investments while adding software-based enhancement capabilities.
- Analog:Legacy signal chain systems dominate installed bases in emerging markets and rural clinics with constrained capital budgets.
Digital platforms anchor current revenue; 3D Imaging is climbing the fastest.
End User:
Consolidation of ophthalmology service lines is shifting purchasing authority from individual practitioners to health system administrators.
- Hospitals:Centralized surgical hubs command multi-system procurement packages spanning diagnostics, surgical equipment, and maintenance services. United States integrated delivery networks negotiate enterprise agreements covering 15-20 facilities, extracting volume discounts unavailable to independent clinics.
- Clinics:Independent ophthalmology practices face narrowing vendor leverage as regional health systems absorb referral networks.
- Diagnostic Centers:Specialized imaging facilities serve overflow demand from hospital backlogs and preoperative screening protocols.
- Research Institutions:Academic medical centers pilot AI-integrated platforms and novel transducer frequencies for protocol development.
Hospitals capture procurement volume; Diagnostic Centers are gaining share fastest.
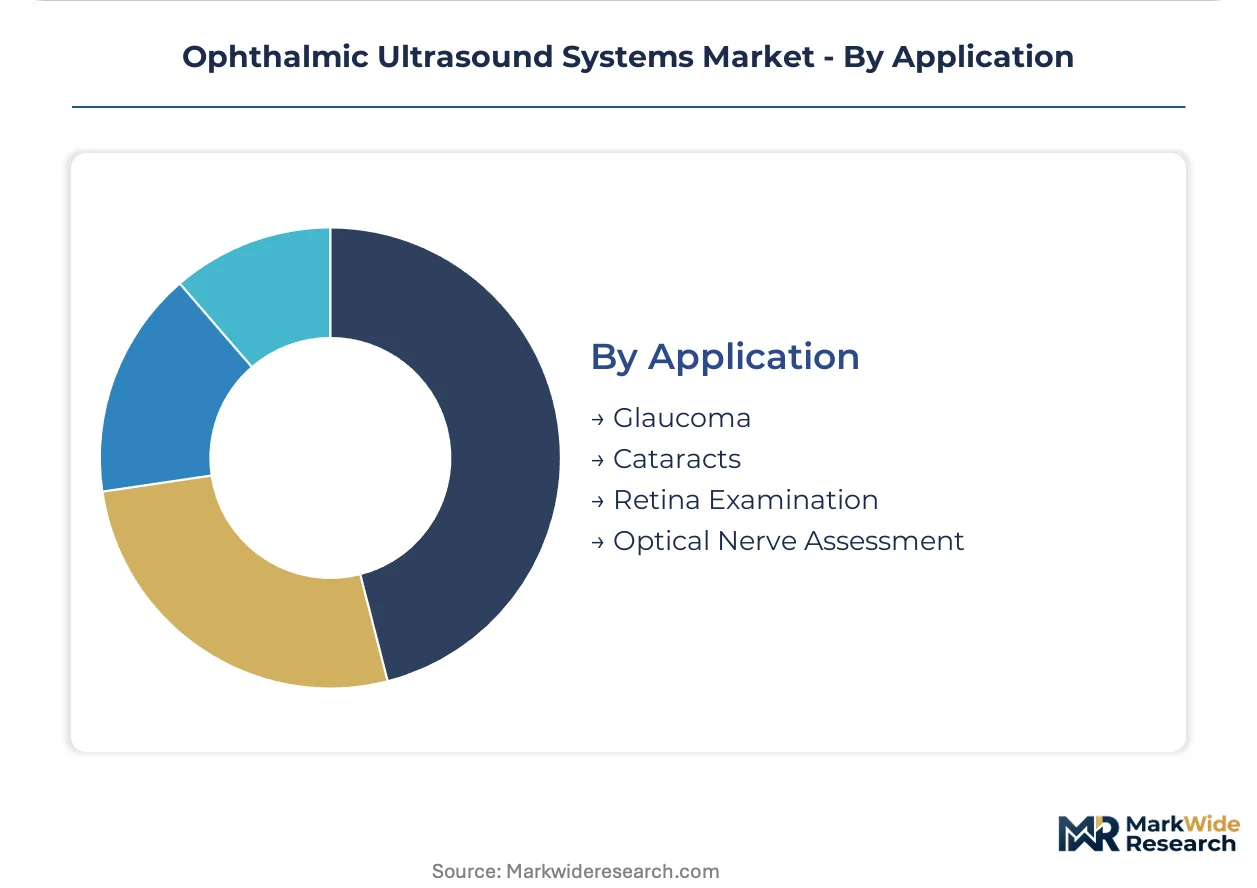
Application:
Reimbursement coding specificity and surgical volume growth determine which clinical indications drive equipment placement.
- Cataracts:Preoperative biometry and IOL power calculation represent the highest-frequency ultrasound application globally. Japan's aging demographic and Germany's statutory cataract surgery coverage create concentrated demand for precision measurement systems.
- Glaucoma:Anterior segment imaging for angle assessment and progression monitoring supports medical management decisions. United States Medicare reimbursement for ultrasound biomicroscopy sustains probe replacement cycles in glaucoma specialty practices.
- Retina Examination:Posterior segment visualization for vitreoretinal pathology detection in media opacity cases.
- Optical Nerve Assessment:Optic nerve head imaging for papilledema and compressive neuropathy evaluation.
Cataracts dominate procedure volume; Glaucoma shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of high-frequency piezoelectric transducers concentrates in East Asian component foundries, while consumption tilts toward aging populations in North America, Europe, and developed Asia-Pacific markets. This production-consumption divide shapes procurement costs and supply chain vulnerability for system integrators.
United States
Hospital consolidation into integrated delivery networks is concentrating procurement authority for multi-system enterprise agreements. FDA 510(k) premarket notification pathways govern acoustic output limits and electromagnetic compatibility validation. Academic medical centers in Boston and the Research Triangle pilot AI-embedded B-scan platforms for automated biometric measurement.
Germany
Statutory health insurance reimbursement structures favor optical biometry, compressing ultrasound biometer volumes to complex cases with dense cataracts. CE marking under the EU MDR demands enhanced clinical performance documentation and post-market surveillance protocols. The medical technology cluster around Stuttgart anchors precision manufacturing for anterior segment imaging probes.
Japan
PMDA accelerated clearance pathways for 3D volumetric platforms with AI-assisted pathology detection support adoption in high-volume cataract centers. Japan Industrial Standards for medical electrical equipment safety apply alongside pharmaceutical and medical device quality management audits. The Kansai region around Osaka hosts specialized foundries for 20-50 MHz anterior segment transducers.
India
Production-linked incentive schemes for medical device manufacturing attract localized assembly investments to serve South Asian distribution networks. CDSCO regulatory frameworks govern import licensing and quality standards for diagnostic equipment. The medical device manufacturing corridor in Gujarat is expanding contract assembly capacity for mid-tier digital-analog hybrid systems.
China
NMPA medical device registration requirements and dual carbon goals shape domestic manufacturing investment and energy efficiency standards. Provincial health procurement platforms consolidate purchasing for public hospital networks. The Yangtze River Delta medical technology cluster in Shanghai-Suzhou generates component supply for regional system integrators.
Ophthalmic Ultrasound Systems Market Vendor Landscape
Top-tier vendors anchor premium-tier positioning through integrated diagnostic-surgical platforms, while mid-tier specialists compete on upgrade pathway flexibility and regional regulatory registration speed. The vendor base stratifies across three archetypes: diversified optical-ophthalmic conglomerates with cross-platform interoperability, specialized ultrasound manufacturers with transducer frequency depth, and regional assemblers leveraging localized cost structures. Dominant competitive moves include vertical integration into high-frequency piezoelectric crystal supply and strategic partnerships with health system procurement committees for multi-year enterprise agreements.
Among diversified optical-ophthalmic conglomerates, Carl Zeiss Meditec AG and NIDEK Co. Ltd. exemplify tier-one positioning through platform breadth and geographic registration density. Halma plc occupies a holding-company archetype, aggregating diagnostic and surgical subsidiaries across multiple eye care settings. Specialized ultrasound manufacturers including DGH Technology Inc. and Sonomed Escalon represent focused technical depth in acoustic imaging modalities. Appasamy Associates and Tomey Corporation anchor regional manufacturing and distribution capabilities in South Asian and Japanese markets respectively.
| Leading Market Players |
|---|
| DGH Technology Inc. |
| Appasamy Associates |
| Carl Zeiss Meditec AG |
| Optos plc |
| Halma plc |
| NIDEK Co. Ltd. |
| Lumibird Medical |
| Tomey Corporation |
| Sonomed Escalon |
| Others |
Supply Flow & Price Mechanics
Performance-grade bifurcation between FDA 510(k)-cleared precision systems and CE-marked clinical workhorses manifests in divergent pricing architectures and sourcing footprints across the ophthalmic ultrasound landscape. Premium-tier digital biometry platforms command substantial markups for validated electromagnetic compatibility and PACS interoperability, while mid-tier hybrid systems compete on upgrade pathway economics that preserve existing transducer investments.
Pricing Analysis
Expedited delivery premiums for 20-50 MHz anterior segment probes drive pricing stratification across premium, standard, and economy tiers. Digital platforms with AI-embedded measurement algorithms extract brand premiums from United States academic medical centers prioritizing surgical throughput standardization. Cost compression in economy-tier analog systems intensifies as Indian contract manufacturers scale hybrid assembly capacity. Hospital procurement committees demonstrate lowest price sensitivity for enterprise agreements bundling diagnostics with maintenance services, while independent rural clinics exhibit acute sensitivity to capital replacement cycles.
Supply Chain Analysis
Dual-sourcing qualification mandates for high-frequency piezoelectric crystals compel system integrators to maintain relationships with Japanese and German precision foundries alongside East Asian component suppliers. Manufacturing draws from specialized Kansai-region transducer foundries, Stuttgart-area precision machining clusters, and Gujarat-based contract assembly facilities. Single-source vulnerability concentrates in 20-50 MHz anterior segment probe supply chains. Distribution runs through health system procurement committees for hospital networks, regional distributors for independent clinics, and direct manufacturer relationships for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-frequency piezoelectric crystal foundry capacity constraints prop pricing power for integrated manufacturers, creating a supply-constrained market structure favoring upstream control.
For Market Incumbents: Extend platform interoperability advantages by deepening EHR integration partnerships and accelerating AI-embedded software companion development. Optical coherence tomography substitution threatens posterior segment B-scan volumes in transparent media cases. Backward integration into captive transducer supply insulates margin structures from East Asian component volatility. For New Entrants and Emerging Players: The mid-tier pricing gap between premium digital platforms and legacy analog systems offers white-space entry for hybrid architecture specialists. India's production-linked incentive schemes attract localized assembly investments serving South Asian and Middle Eastern distribution networks. Telemedicine-integrated cloud platforms represent the most penetrable ambulatory surgery center segment previously inaccessible to capital-intensive equipment vendors. For Investors and Strategic Acquirers: Re-rating potential sits with specialized ultrasound manufacturers possessing established FDA 510(k) clearance pathways given accelerating hospital consolidation into integrated delivery networks. Long-term viability hinges on software recurring revenue attachment rates and transducer replacement cycle monetization. Watch for inflection in health system enterprise agreement penetration as a signal of vendor relationship consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical performance documentation requirements extend validation timelines for European commercialization. |
| Hospital System Partnership | Multi-year enterprise agreements with United States integrated delivery networks extract volume discounts unavailable to independent clinics. |
| Software Companion Development | AI-embedded B-scan platforms automate biometric measurement extraction for axial length calculation standardization. |
| FDA Submission | 510(k) premarket notification for acoustic output safety governs electromagnetic compatibility validation for United States entry. |
| Reimbursement Strategy | Medicare coding specificity for ultrasound biomicroscopy sustains probe replacement cycles in glaucoma specialty practices. |
Methodological Framework
Independent corroboration across hospital procurement committee interviews, biomedical engineer technical assessments, and GPO contracts manager discussions underwrites the qualitative findings in this analysis. Primary fieldwork engaged clinicians, ophthalmology service line administrators, and regulatory affairs specialists at device manufacturers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR clinical performance documentation, CMS Medicare reimbursement schedules, and hospital procurement platform records. Bottom-up installed base modeling and top-down health system capital expenditure triangulation anchored market sizing.
Comparable-period anchoring to historical biometry system placement rates and B-scan replacement cycles structured the forecast window across the analysis window. Segmentation dimensions modeled include product type, technology architecture, end-user setting, and application indication. CAGRs were derived from surgical volume growth trajectories, reimbursement code expansion patterns, and health system consolidation velocity. Forecast inputs incorporated aging demographic screening demand and optical coherence tomography substitution elasticities.
Inputs from hospital procurement databases and GPO contract disclosures were available through the study window; gaps in private health system capital expenditure plans introduce uncertainty bands around installed base projections. Deviation in FDA 510(k) clearance pathway efficiency or EU MDR harmonization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Non-Infectious Macular Edema Treatment Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Panuveitis Treatment Market
Ophthalmology
Non-Infectious Uveitis Treatment Market
Ophthalmology
Artificial Iris Market
Ophthalmology
Uveal Melanoma Treatment Market
Ophthalmology
Keratitis Treatment Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Asia-Pacific Conjunctivitis Treatment Market
Ophthalmology
Ophthalmic Photocoagulator Market
Ophthalmology
Neovascular Age-Related Macular Degeneration Treatment Market
Ophthalmology
United States Dry Eye Syndrome Market
Ophthalmology
Conjunctivitis Market
Ophthalmology
Dacryocystitis Market
Ophthalmology
Keratoconus Treatment Market
Ophthalmology
Astigmatism Market