
 Recycled Concrete Aggregates Market | 2026-2036
Recycled Concrete Aggregates Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Concrete Aggregates Market Analysis
Natural aggregate scarcity in urban construction corridors is hardening the cost advantage of processed demolition debris. Heidelberg Materials AG leverages captive demolition networks across European metropolitan zones to secure consistent feedstock quality. Vulcan Materials Co. anchors its southeastern US operations with dedicated crushing and screening infrastructure near high-growth Sun Belt cities. CRH Plc differentiates through specification-grade coarse aggregate production that meets state DOT structural concrete requirements.
Recycled concrete aggregates consist of processed, crushed, and screened concrete debris with specified gradation limits, typically incorporating Portland cement paste, natural sand, and coarse stone fragments with absorption rates of 3-8% by mass. These materials primarily substitute virgin aggregates in load-bearing and non-load-bearing applications where performance testing confirms compliance with engineering standards. Coarse aggregates dominate volume flows in road construction and pavement base layers where mechanical stability requirements favor larger particle sizes. Fine aggregates compete in non-structural concrete and masonry mortar blends where lower strength thresholds permit higher paste content. Mixed aggregates occupy intermediate specification tiers for general fill and sub-base applications with less stringent grading controls.
The US EPA construction and demolition debris regulations, EU Waste Framework Directive recovery targets, and state-level recycled content mandates in California and Texas collectively reshape material acceptance criteria and project bidding requirements. Germany's KBA and federal building codes enforce performance-based testing protocols that determine market access for recycled aggregate suppliers. Stakeholders must monitor evolving end-of-waste classification thresholds that determine when processed concrete debris transitions from regulated waste to tradable product status.
Market Dynamics
The EU Green Deal's circular economy mandates for construction waste recovery are tightening material specifications across member states, forcing infrastructure developers to requalify supply chains around performance-tested recycled aggregates rather than conventional virgin materials.
Growth Catalysts
- EU Waste Framework Directive recovery targets:Member states must achieve 70% construction and demolition waste recovery, redirecting demolition debris into processed aggregate streams for federal highway and municipal projects.
- Federal highway rehabilitation:Infrastructure developers in Germany are expanding procurement of recycled aggregates for KBA-certified road base applications where structural performance testing confirms compliance with federal building codes.
- Vertical integration of demolition contractors:Paris-region demolition specialists are merging operations with ready-mix suppliers to secure captive feedstock flows and guarantee specification-grade output consistency.
Market Restraints
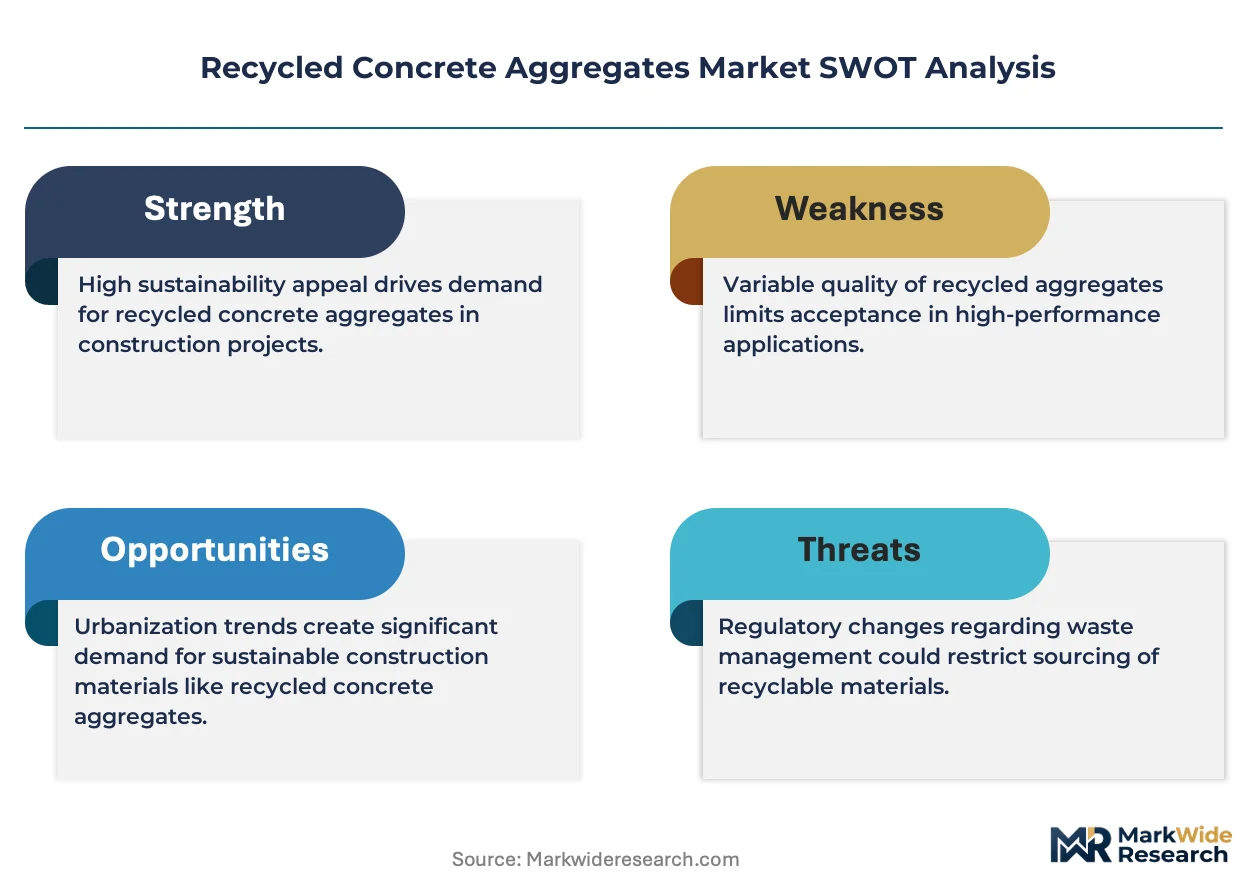
- Natural aggregate price volatility:Fluctuations in virgin limestone and granite extraction costs in urban construction corridors compress margins for recycled material processors competing on cost parity.
- End-of-waste classification uncertainty:Variable thresholds across German Länder and French departments delay the transition of processed concrete debris from regulated waste to tradable product status.
- Performance testing infrastructure gaps:Limited laboratory capacity for absorption rate and mechanical stability verification restricts market access for smaller regional processors.
Strategic Opportunities
- Specification-grade coarse aggregate production:State DOT structural concrete requirements in high-growth Sun Belt cities create demand for premium-tier processed debris with certified gradation limits.
- Carbon accounting integration:Embodied carbon disclosure mandates in California and Texas position recycled aggregates as verified lower-carbon inputs for LEED and BREEAM-certified developments.
- Mobile crushing and screening deployment:Distributed processing units at demolition sites reduce transport costs and enable just-in-time feedstock delivery to metropolitan ready-mix plants.
Industry Challenges
- Quality assurance technician shortage:Qualified personnel for sieve analysis and Los Angeles abrasion testing are scarce in secondary metropolitan markets, delaying batch certification timelines.
- Legacy equipment retrofit costs:Existing crushing infrastructure requires capital-intensive upgrades to achieve the particle shape and gradation precision demanded by structural concrete specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Concrete Aggregates Market |
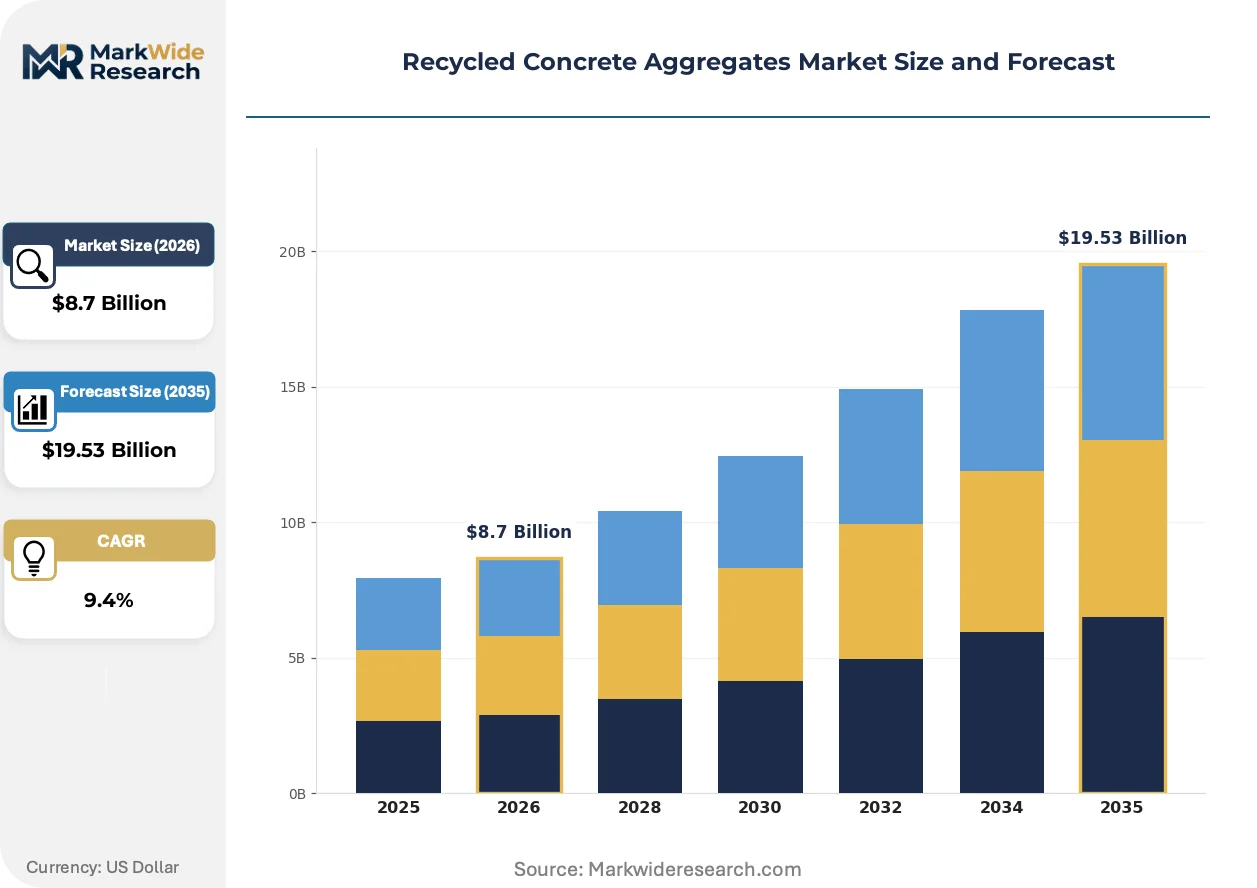
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coarse Aggregates, Fine Aggregates, Mixed Aggregates, Granular Materials Application: Road Construction, Structural Concrete, Non-Structural Concrete, Pavement Base End User: Construction Companies, Infrastructure Developers, Demolition Contractors, Ready-Mix Suppliers Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail Outlets |
| Companies Covered | CEMEX SAB de CV, Breedon Group plc, Heidelberg Materials AG, Martin Marietta Materials Inc., Arcosa Inc., CRH Plc, Vulcan Materials Co., SUEZ SA, Holcim Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Concrete Aggregates Market Emerging Trajectories
Advanced sensor-based sorting and real-time gradation monitoring are compressing quality variability in processed demolition debris, enabling broader substitution of virgin aggregates in load-bearing applications previously reserved for natural stone.
Near-infrared spectroscopy combined with electromagnetic separation is absorbing residual contaminants from mixed demolition streams. German processors are deploying these systems at scale for federal highway feedstock preparation. The technology is absorbing market share from conventional manual pre-sorting operations by delivering consistent 3-5% absorption rate outputs that meet KBA structural base specifications.
The EU Green Deal's construction waste recovery mandates are tightening enforcement timelines across member states. France's national building code is incorporating recycled content minimums for public procurement contracts above specified value thresholds. Infrastructure developers in the Paris metropolitan corridor are responding by pre-qualifying demolition contractors with certified processing capabilities ahead of 2025 tender cycles.
Specification-driven procurement is consolidating buyer power around engineering-certified suppliers. French and German ready-mix producers are bypassing spot-market aggregate merchants to contract directly with demolition networks owning in-house crushing infrastructure. This pattern is most visible in the Ile-de-France and Rhine-Ruhr urban construction corridors where project-scale carbon accounting favors single-source material traceability.
Recycled Concrete Aggregates Market Segmentation
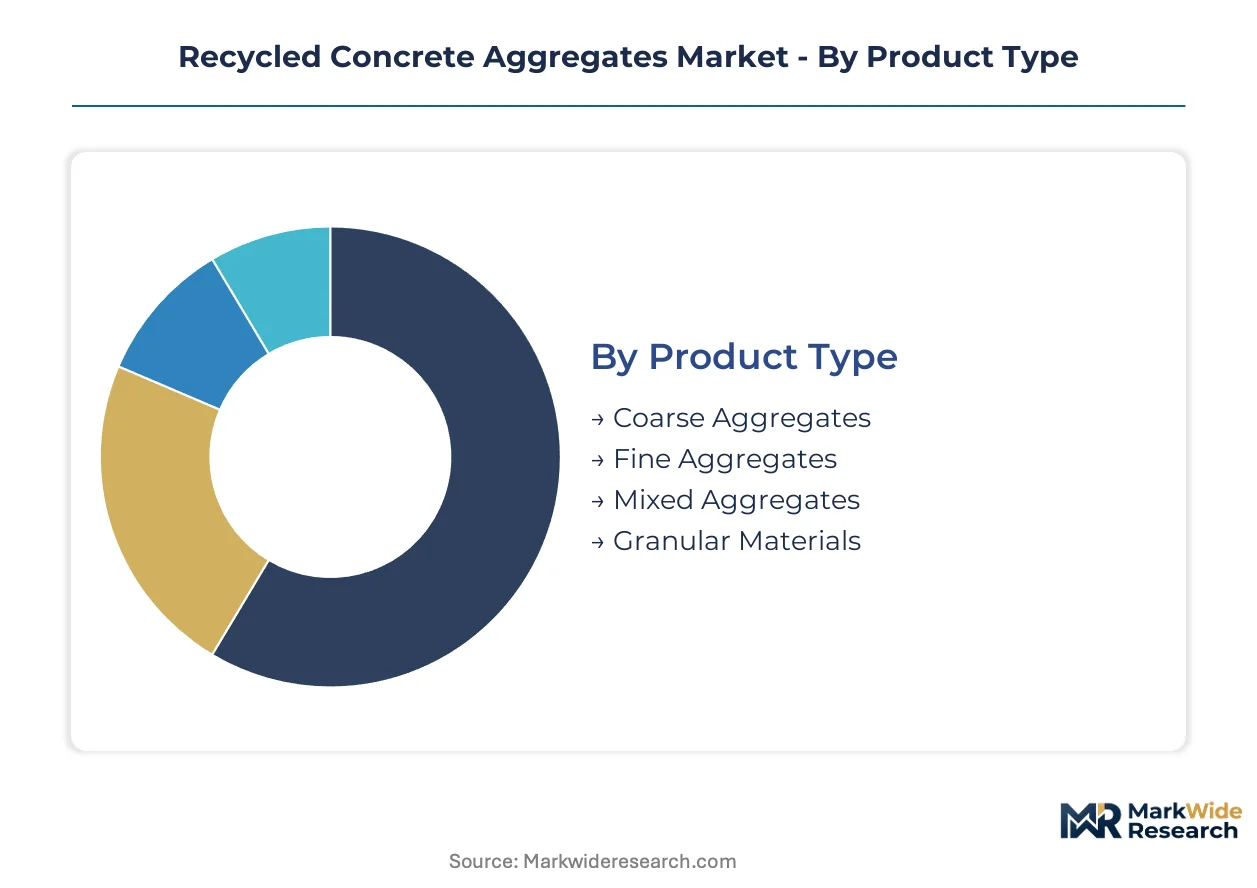
Recycled concrete aggregate processors must align crushing and screening configurations with distinct specification tiers. Product gradation, application load requirements, and end-user quality protocols determine pricing power and batch certification complexity across each segment boundary.
Product Type:
Specification-grade output separates premium structural applications from general fill markets based on absorption rates, Los Angeles abrasion resistance, and gradation precision.
- Coarse Aggregates:Processed particles retained on 4.75mm sieves deliver mechanical stability for load-bearing infrastructure. German KBA-certified road base applications in the Rhine-Ruhr corridor specify these materials for federal highway rehabilitation where structural performance testing is mandatory. Federal building codes enforce performance-based protocols that restrict market access to processors with verified laboratory capacity.
- Fine Aggregates:Material passing 4.75mm sieves incorporates higher Portland cement paste content with 3-8% absorption rates by mass. Paris-region ready-mix suppliers blend these inputs for non-structural concrete and masonry mortar where lower strength thresholds permit paste-rich formulations. Vertical integration between demolition contractors and concrete producers secures captive feedstock flows for specification-grade consistency.
- Mixed Aggregates:Intermediate gradation blends occupy general fill and sub-base tiers with less stringent grading controls.
- Granular Materials:Unprocessed or minimally screened debris serves drainage layers and temporary access roads.
Coarse aggregates lead on scale; fine aggregates lead on momentum as carbon accounting integration accelerates specification-grade procurement.
Application:
Engineering standards and load-bearing requirements stratify demand intensity across construction use cases.
- Road Construction:Pavement base and sub-base layers consume the highest volume flows where mechanical stability favors larger particle sizes. Infrastructure developers in Germany are expanding procurement for federal highway projects under EU Green Deal circular economy mandates. KBA structural base specifications require consistent 3-5% absorption rate outputs that only advanced sensor-based sorting systems can deliver.
- Structural Concrete:State DOT requirements in California and Texas enforce recycled content minimums for public procurement contracts above specified value thresholds. Specification-grade coarse aggregate production with certified gradation limits commands premium positioning. Limited laboratory capacity for mechanical stability verification restricts market access for smaller regional processors.
- Non-Structural Concrete:Precast elements, sidewalks, and architectural applications tolerate higher variability in particle shape and paste content.
- Pavement Base:Unbound granular layers for parking facilities and municipal roads absorb intermediate specification tiers with moderate testing protocols.
Road construction dominates volume absorption; structural concrete commands the steepest expansion trajectory as embodied carbon disclosure mandates tighten.
End User:
Procurement sophistication and quality assurance capabilities determine supplier relationship structures and contract duration.
- Construction Companies:General contractors source spot-market aggregates for project-specific fill and base applications with minimal certification requirements.
- Infrastructure Developers:Federal highway and municipal project sponsors enforce performance-tested material acceptance with extended supplier qualification timelines. German federal building codes and EU Waste Framework Directive recovery targets reshape bidding requirements around verified recycled content.
- Demolition Contractors:Paris-region specialists are merging operations with ready-mix suppliers to guarantee captive feedstock flows and specification-grade output consistency. Mobile crushing and screening deployment at demolition sites reduces transport costs and enables just-in-time delivery.
- Ready-Mix Suppliers:French and German producers bypass spot-market merchants to contract directly with demolition networks owning in-house crushing infrastructure for single-source material traceability.
Infrastructure developers anchor volume demand; demolition contractors are gaining share fastest through backward integration into processing capabilities.
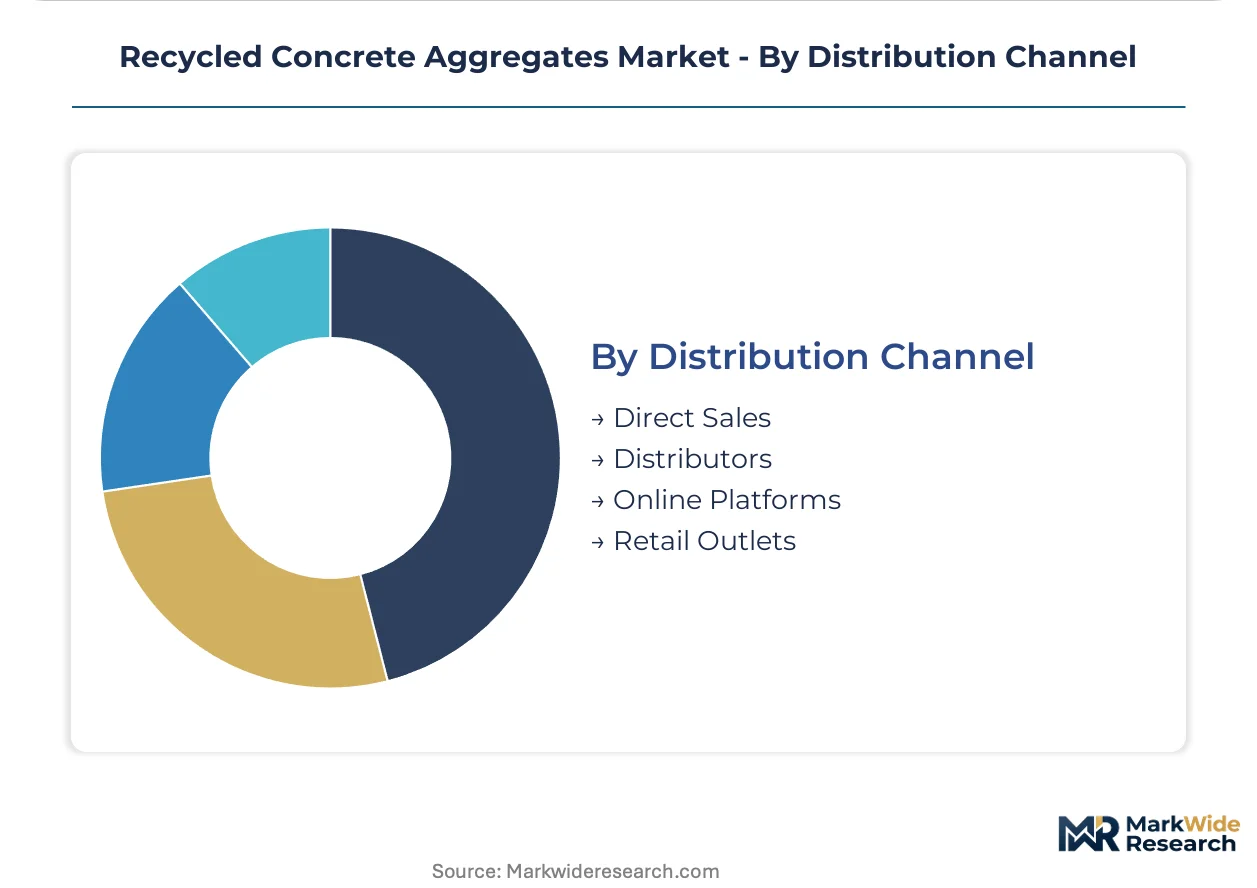
Distribution Channel:
Logistics configuration and customer scale determine channel economics and margin capture.
- Direct Sales:Large-scale infrastructure developers and ready-mix suppliers contract directly with demolition networks for specification-grade output with certified traceability.
- Distributors:Regional aggregate merchants serve construction companies with spot-market availability and mixed-specification blending services.
- Online Platforms:Digital procurement interfaces are emerging for standardized granular materials with basic gradation documentation.
- Retail Outlets:Small-volume landscaping and residential renovation applications access bagged recycled aggregates through building material retailers.
Direct sales capture the premium tier; distributors maintain broadest geographic coverage for general fill applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan corridor anchors European recycled concrete aggregate processing capacity, with demolition networks feeding specification-grade material into federal highway rehabilitation programs.
Germany
KBA-certified road base specifications drive demand for structural-grade recycled aggregates in federal highway projects. The EU Waste Framework Directive mandates 70% construction waste recovery, forcing contractors to requalify supply chains around performance-tested materials. Infrastructure developers in the Rhine-Ruhr corridor are expanding procurement of processed demolition debris for municipal and federal applications.
United States
State DOT recycled content mandates in California and Texas reshape bidding requirements for public infrastructure contracts. The EPA construction and demolition debris regulations establish baseline material acceptance criteria across jurisdictions. Sun Belt metropolitan areas including Atlanta, Dallas, and Phoenix concentrate mobile crushing and screening infrastructure near high-growth construction zones.
France
Paris-region demolition contractors are merging operations with ready-mix suppliers to secure captive feedstock flows and guarantee specification-grade output consistency. The national building code incorporates recycled content minimums for public procurement contracts above specified value thresholds. Ile-de-France infrastructure developers are pre-qualifying demolition contractors with certified processing capabilities ahead of tender cycles.
United Kingdom
Specification-grade coarse aggregate production for structural concrete commands premium positioning in London and Southeast England construction corridors. The Waste Framework Directive recovery targets apply through retained EU law, maintaining pressure on construction waste diversion from landfill. Greater Manchester and Birmingham metropolitan areas host distributed processing units at demolition sites to reduce transport costs.
Netherlands
Randstad urban construction corridors face acute natural aggregate scarcity, hardening the cost advantage of processed demolition debris. National circular economy programs enforce end-of-waste classification thresholds that determine when processed concrete debris transitions to tradable product status. Rotterdam and Amsterdam demolition networks deploy advanced sensor-based sorting systems to meet specification-grade absorption rate requirements.
Recycled Concrete Aggregates Market Vendor Landscape
Global majors compete with regional champions across feedstock security and specification-grade production capacity. The vendor base stratifies into three tiers: integrated building materials conglomerates with captive demolition networks, independent aggregate processors serving spot markets, and demolition contractors backward-integrating into crushing infrastructure. Two dominant competitive moves are reshaping positioning: vertical consolidation between demolition and ready-mix operations, and deployment of mobile processing units at demolition sites to capture transport cost advantages.
Within the integrated materials tier, Heidelberg Materials AG and CRH Plc exemplify archetypes that combine captive feedstock access with state DOT certification capabilities. Vulcan Materials Co. anchors the North American scale-driven segment with dedicated crushing infrastructure near Sun Belt metropolitan zones. Among demolition-specialist integrators, Paris-region operators represent the emerging pattern of backward integration into processing capabilities to guarantee specification-grade consistency.
| Leading Market Players |
|---|
| CEMEX SAB de CV |
| Breedon Group plc |
| Heidelberg Materials AG |
| Martin Marietta Materials Inc. |
| Arcosa Inc. |
| CRH Plc |
| Vulcan Materials Co. |
| SUEZ SA |
| Holcim Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between KBA-certified structural aggregates and general fill materials manifests in both pricing power and supply chain configuration. Premium-tier processors command contract-based long-term offtake agreements with infrastructure developers, while commodity-grade suppliers compete in spot markets with minimal quality assurance overhead.
Pricing Analysis
Input-cost pass-through from demolition debris acquisition and mobile processing deployment shapes margin structures across specification tiers. Three-tier pricing structure across premium, standard, and economy levels reflects absorption rate certification, Los Angeles abrasion testing, and state DOT compliance documentation. Cost compression in the economy tier intensifies because virgin limestone price volatility erodes recycled material cost advantages. Municipal contractors exhibit highest price sensitivity; federal highway developers demonstrate lowest sensitivity due to carbon accounting mandates and EU Green Deal compliance requirements.
Supply Chain Analysis
Certification and qualification gating through KBA protocols, state DOT structural concrete requirements, and end-of-waste classification thresholds determines processor market access. Supply concentrates in Germany, France, and the United States where demolition networks feed metropolitan construction corridors. Raw material flows draw from concrete demolition debris, residual Portland cement paste, and mixed construction waste streams. Single-source vulnerability runs through captive feedstock agreements between Paris-region demolition contractors and ready-mix suppliers. Distribution runs through direct sales to infrastructure developers and ready-mix producers, with regional distributors serving spot-market construction companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in specification-grade production where carbon accounting integration and EU Green Deal mandates shift procurement toward premium-tier certified aggregates. Feedstock security and testing infrastructure investments separate sustainable margin capture from commodity price exposure.
For Market Incumbents: Anchor market position through backward integration into demolition networks and mobile crushing infrastructure deployment at metropolitan demolition sites. Heidelberg Materials AG and CRH Plc demonstrate how captive feedstock access insulates against virgin aggregate price volatility. Invest in laboratory capacity expansion for Los Angeles abrasion and absorption rate certification to maintain KBA and state DOT qualification status against emerging regional processors.
For New Entrants and Emerging Players: Begin with distributed mobile processing units serving secondary metropolitan markets where quality assurance technician scarcity delays incumbent certification timelines. Target the non-structural concrete and masonry mortar segment where lower strength thresholds permit paste-rich fine aggregate formulations with reduced testing overhead. Establish direct supply relationships with mid-sized ready-mix producers seeking alternative feedstock sources outside consolidated demolition networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where laboratory capacity constraints and legacy equipment retrofit costs prevent smaller regional processors from achieving specification-grade certification. Long-term viability favors demolition contractors with in-house crushing infrastructure and established metropolitan feedstock relationships. Acquisition target archetypes include Paris-region demolition specialists with certified processing capabilities and Sun Belt mobile crushing operators near high-growth construction zones. Watch for EU member state end-of-waste classification harmonization as inflection indicator for tradable product status expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Demolition Networks | Captive feedstock access secures consistent quality for KBA-certified road base specifications. |
| Mobile Crushing Infrastructure Deployment | Distributed processing at demolition sites reduces transport costs and enables just-in-time delivery. |
| Laboratory Capacity Expansion | Enhanced testing capability for absorption rate and mechanical stability verification accelerates batch certification. |
| Carbon Accounting Integration | Embodied carbon disclosure positions recycled aggregates for LEED and BREEAM-certified developments. |
| Direct Supply Contracting | Bypassing spot-market merchants guarantees specification-grade traceability for infrastructure developers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand and supply estimates for processed demolition debris. Primary engagement included demolition contractors, ready-mix procurement directors, state DOT materials engineers, and infrastructure project developers. Secondary validation drew from EPA construction debris regulations, EU Waste Framework Directive recovery targets, KBA technical bulletins, and federal highway procurement databases. Bottom-up processor capacity estimates triangulated against top-down construction waste generation forecasts.
Comparable-period anchoring linked historical aggregate consumption patterns to projected infrastructure rehabilitation cycles across the analysis window. Segmentation modeling incorporated product type gradation tiers, application load requirements, end-user procurement sophistication, and distribution channel logistics configuration. CAGRs derived from volume-weighted growth rates across coarse, fine, and mixed aggregate categories. Industry-specific inputs included federal highway rehabilitation backlogs, EU Green Deal enforcement timelines, and metropolitan demolition permit issuance trends.
Caveats apply where end-of-waste classification threshold revisions, virgin aggregate price volatility, or laboratory capacity expansion rates could materially shift the outlook. Forecasts reflect assumptions around regulatory enforcement consistency and infrastructure spending authorization continuity. A model refresh is warranted upon material change in EU member state circular economy mandate implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Steel Products Market
Building Materials
US Facade Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Germany Aluminum Door and Window Market
Building Materials
Thin Brick Market
Building Materials
Construction Stone Market
Building Materials
Ireland Cement Market
Building Materials
Composite Rebar Market
Building Materials
Shotcrete Market
Building Materials
Italy Cement Market
Building Materials
Canada Architectural Coatings Market
Building Materials
Gravity Retaining Wall Market
Building Materials
Cladding Market
Building Materials
North America Concrete Admixtures Market
Building Materials
China Aluminum Door and Window Market
Building Materials
Foam Bricks Market