
 Concrete Aggregate Market | 2026-2036
Concrete Aggregate Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Aggregate Market Analytics
EPA effluent limitation guidelines for construction materials processing is broadening compliance costs for wet-classification operations. Vulcan Materials Company leverages its captive quarry network across the southeastern United States to control feedstock quality and logistics costs. Martin Marietta Materials anchors its position through deep reserves of high-specification granite and limestone in Texas and North Carolina. CRH plc competes via integrated asphalt and ready-mix operations that internalize aggregate demand across multiple downstream channels.
Concrete aggregate encompasses granular mineral material—typically crushed stone, gravel, sand, or slag—graded between 0.075 mm and 75 mm particle size, blended with cement paste to form composite construction material with compressive strength engineered to 20–60 MPa for structural applications. Coarse aggregates dominate volume consumption in infrastructure projects where load-bearing specifications require dense-graded crushed rock with Los Angeles abrasion loss below 40 percent. Recycled aggregates represent the fastest-expanding material source segment as demolition waste processing technology improves contaminant removal and particle shape consistency for non-structural concrete applications.
OSHA silica exposure limits and EPA National Ambient Air Quality Standards constrain dry-crushing operations, compelling capital investment in dust suppression and enclosed processing systems. State departments of transportation enforce aggregate quality protocols through qualified product lists that restrict market access for uncertified producers. Stakeholders must monitor evolving embodied-carbon disclosure requirements from procurement agencies, as environmental product declarations become gatekeeping documents for public infrastructure bids.
Market Dynamics
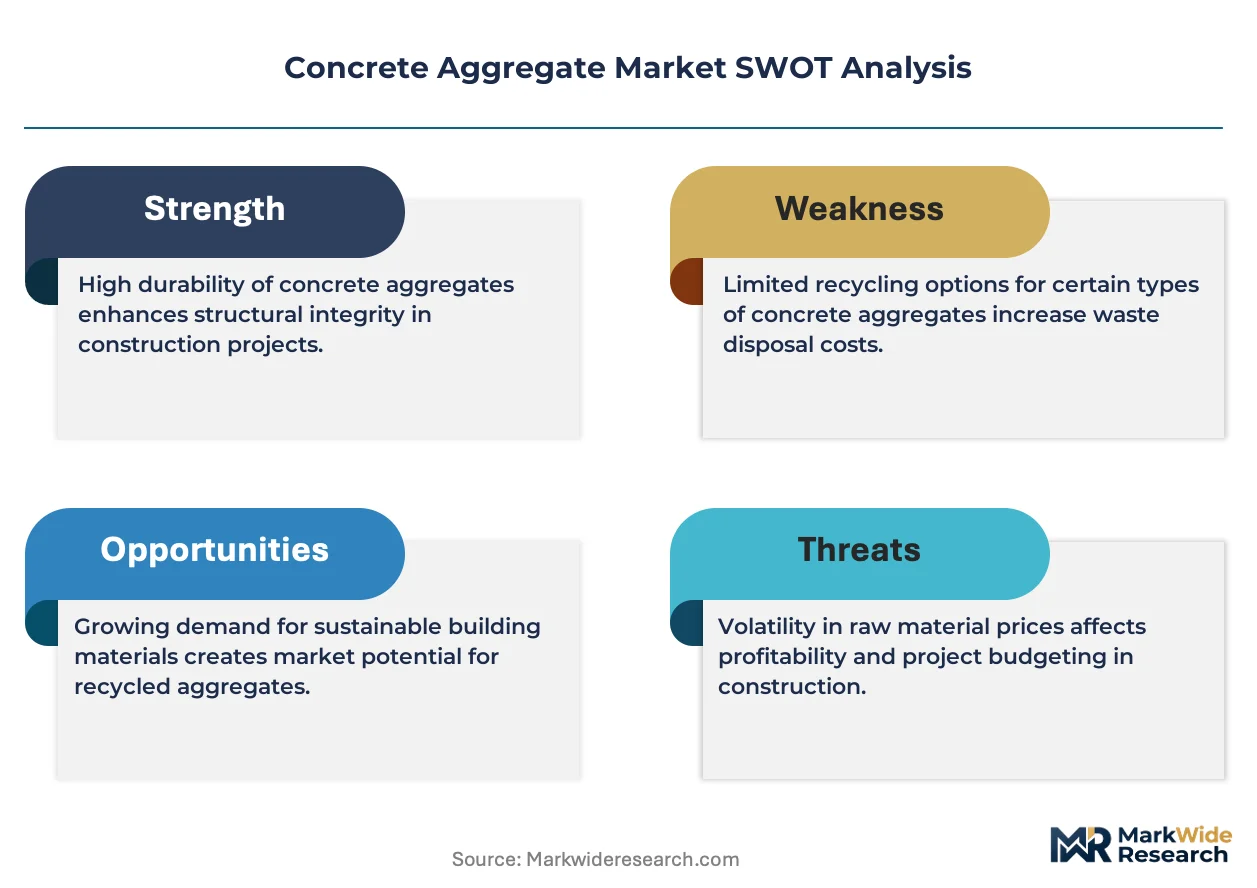
Embodied carbon disclosure mandates from procurement agencies are compressing margins for conventional aggregate producers while rewarding operators with verified environmental product declarations and processed recycled feedstock streams.
Growth Catalysts
- Infrastructure Megaproject Pipeline:Southeast Asian governments are awarding contracts for expressway corridors and deepwater port expansions that specify dense-graded crushed rock for structural concrete.
- EU Green Deal Thresholds:The embodied carbon caps are mandating lower-clinker cement formulations that perform optimally with manufactured sand and processed recycled aggregates.
- Advanced Beneficiation:Optical sorting and density-separation systems are removing contaminants from demolition waste at commercial scale, unlocking new feedstock pools.
Market Restraints
- Licensed Quarry Depletion:Vietnam's Red River Delta corridor is exhausting permitted reserves faster than new extraction licenses are granted by provincial mining authorities.
- Silica Exposure Compliance:OSHA's permissible exposure limits for respirable crystalline silica are forcing capital expenditure on enclosed crushing circuits and dust suppression infrastructure.
- Transportation Cost Burden:Rail and barge capacity constraints in the southeastern United States are inflating delivered costs for specification-grade limestone and granite.
Strategic Opportunities
- Urban Mining Integration:Demolition contractors in Germany and the Netherlands are installing mobile processing trains that convert construction debris into certifiable recycled aggregate on-site.
- Carbon-Capture Concrete:Precast manufacturers are sourcing carbonated recycled aggregates that chemically sequester CO2 during curing, qualifying for green procurement tenders.
- Digital Material Passports:Blockchain-tracked aggregate batches with embedded lifecycle data are commanding premium placement on qualified product lists for public infrastructure bids.
Industry Challenges
- Geotechnical Certification Bottlenecks:State departments of transportation are backlogging aggregate source approvals, delaying quarry commissioning by 18-24 months in high-demand corridors.
- Skilled Operator Scarcity:Wet-classification plant technicians with EPA effluent guideline expertise are concentrated among legacy producers, constraining new entrant scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Aggregate Market |
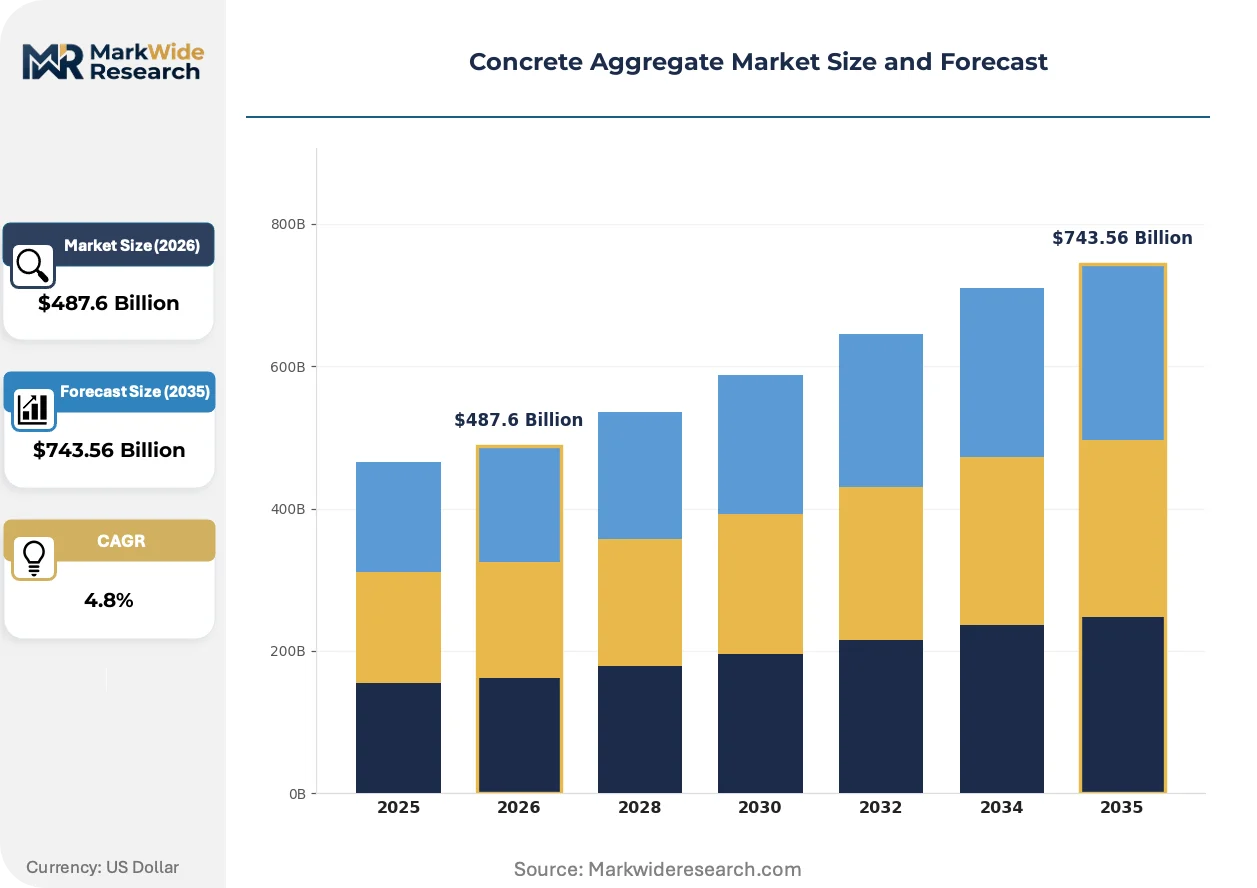
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $743.56 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coarse Aggregates, Fine Aggregates, Recycled Aggregates, Lightweight Aggregates Application: Residential Construction, Commercial Construction, Infrastructure Projects, Road Construction End User: Contractors, Builders, Civil Engineers, Departments of Transportation Material Source: Naturally Occurring, Manufactured, Recycled, Others |
| Companies Covered | Vulcan Materials Company, Martin Marietta Materials, CRH plc, Heidelberg Materials, CEMEX, Holcim, LafargeHolcim, Lehigh Hanson, Summit Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Aggregate Market Evolving Landscape
Processing technology convergence and procurement specification tightening are redrawing competitive boundaries between virgin aggregate incumbents and recycled material specialists.
Sensor-based ore sorting is overtaking traditional washing and screening circuits in high-value specification markets. Hard-rock quarry operators in Texas and North Carolina are retrofitting X-ray transmission sorters that remove deleterious clay and soft stone before crushing, cutting downstream processing energy by one-third. This precision classification is overtaking volume-driven production economics, enabling marginal deposits to meet state DOT qualified product thresholds.
REACH regulation updates on construction product safety are extending hazardous substance screening to imported aggregate streams. The ECHA candidate list expansion is compelling European ready-mix producers to demand full material disclosure from crushed stone suppliers in third countries. Suppliers without certified contaminant testing are losing access to public infrastructure frameworks in France and Germany.
Buyers are consolidating procurement through integrated material management platforms that bundle aggregate, cement, and logistics contracting. General contractors on megaprojects in Vietnam and Indonesia are abandoning spot-market purchasing for multi-year supply agreements with volume guarantees and fixed escalators. This consolidation is most visible in the Red River Delta, where expressway consortia are locking in dedicated quarry output five years ahead of construction commencement.
Concrete Aggregate Market Segmentation
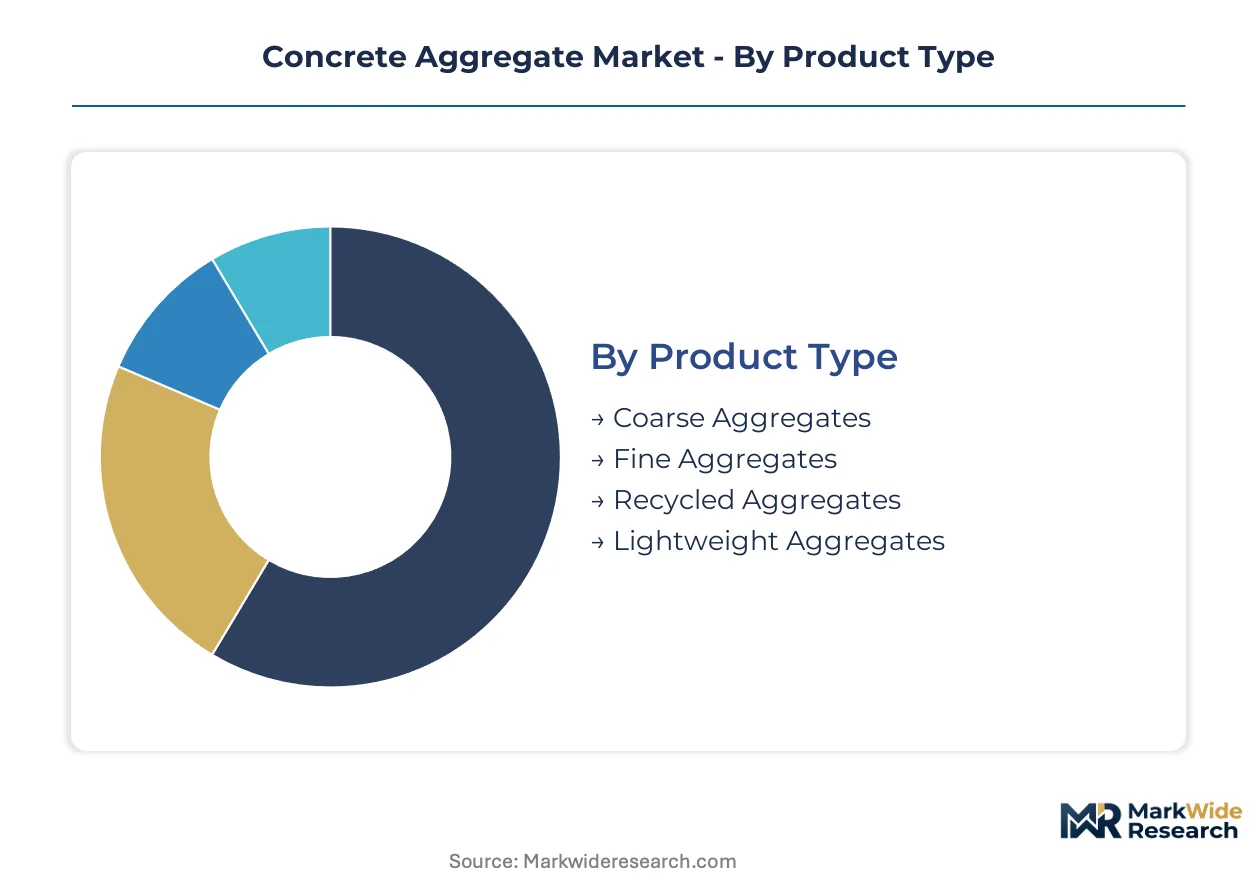
Aggregate specifications vary sharply across load-bearing requirements and environmental compliance tiers. Procurement agencies now mandate material traceability that favors certain segments with certified environmental product declarations. Capital deployment intensity differs fundamentally between virgin extraction operations and processed recycled feedstock streams.
Product Type:
Capital intensity peaks with coarse aggregate production requiring hard-rock quarrying, rail-linked distribution, and Los Angeles abrasion certification infrastructure. Fine aggregate operations demand less upfront plant investment but face escalating silica compliance costs for dry-classification systems.
- Coarse Aggregates:Dense-graded crushed stone between 4.75 mm and 75 mm particle size dominates structural concrete specifications. Vietnam's Red River Delta corridor is absorbing record volumes for expressway expansion and deepwater port construction, depleting licensed quarry reserves faster than provincial mining authorities grant new extraction permits.
- Fine Aggregates:Natural sand and manufactured sand graded below 4.75 mm control workability and finish quality in ready-mix formulations. EU Green Deal embodied carbon thresholds are mandating manufactured sand substitution for dredged river sand in public infrastructure bids across France and Germany.
- Recycled Aggregates:Processed demolition waste with contaminant removal via optical sorting and density separation.
- Lightweight Aggregates:Expanded shale or clay for precast panels and structural lightweight concrete in high-rise construction.
Most installed capacity flows through Coarse Aggregates. Expansion is steepest in Recycled Aggregates.
Application:
Application segments diverge by specification stringency, payment security, and contract duration. Infrastructure projects command the longest offtake agreements while residential construction operates on spot-market volatility.
- Infrastructure Projects:Megaprojects including expressway corridors, deepwater ports, and rail terminals specify dense-graded crushed rock with 40-year design life requirements. Southeast Asian governments are awarding multi-year contracts with volume guarantees and fixed price escalators five years ahead of construction commencement.
- Commercial Construction:High-rise and industrial concrete demands consistent gradation and low alkali-silica reactivity for structural integrity. German and Dutch demolition contractors are installing mobile processing trains that convert construction debris into certifiable recycled aggregate on-site for commercial concrete batching.
- Residential Construction:Single-family and multi-family housing with variable specification tolerances.
- Road Construction:Asphalt and concrete pavement layers with state DOT qualified product list requirements.
Infrastructure Projects anchor procurement volume. Commercial Construction is climbing the fastest as embodied-carbon disclosure mandates reshape material sourcing.
End User:
End user categories separate by technical specification authority and compliance burden. State departments of transportation enforce the most rigid aggregate quality protocols through qualified product lists that restrict market access.
- Departments of Transportation:State and federal agencies with qualified product lists and source approval backlogs extending quarry commissioning by 18-24 months in high-demand corridors. EPA effluent limitation guidelines for construction materials processing are broadening compliance costs for wet-classification operations serving DOT contractors.
- Civil Engineers:Design consultants specifying performance-grade concrete for structural applications with embedded lifecycle data requirements. Blockchain-tracked aggregate batches with material passports are commanding premium placement on qualified product lists for public infrastructure bids.
- Contractors:General construction firms executing residential and commercial projects.
- Builders:Residential developers with spot-market purchasing patterns.
Departments of Transportation control the most stringent specification tiers. Civil Engineers are gaining share fastest through carbon-capture concrete procurement mandates.
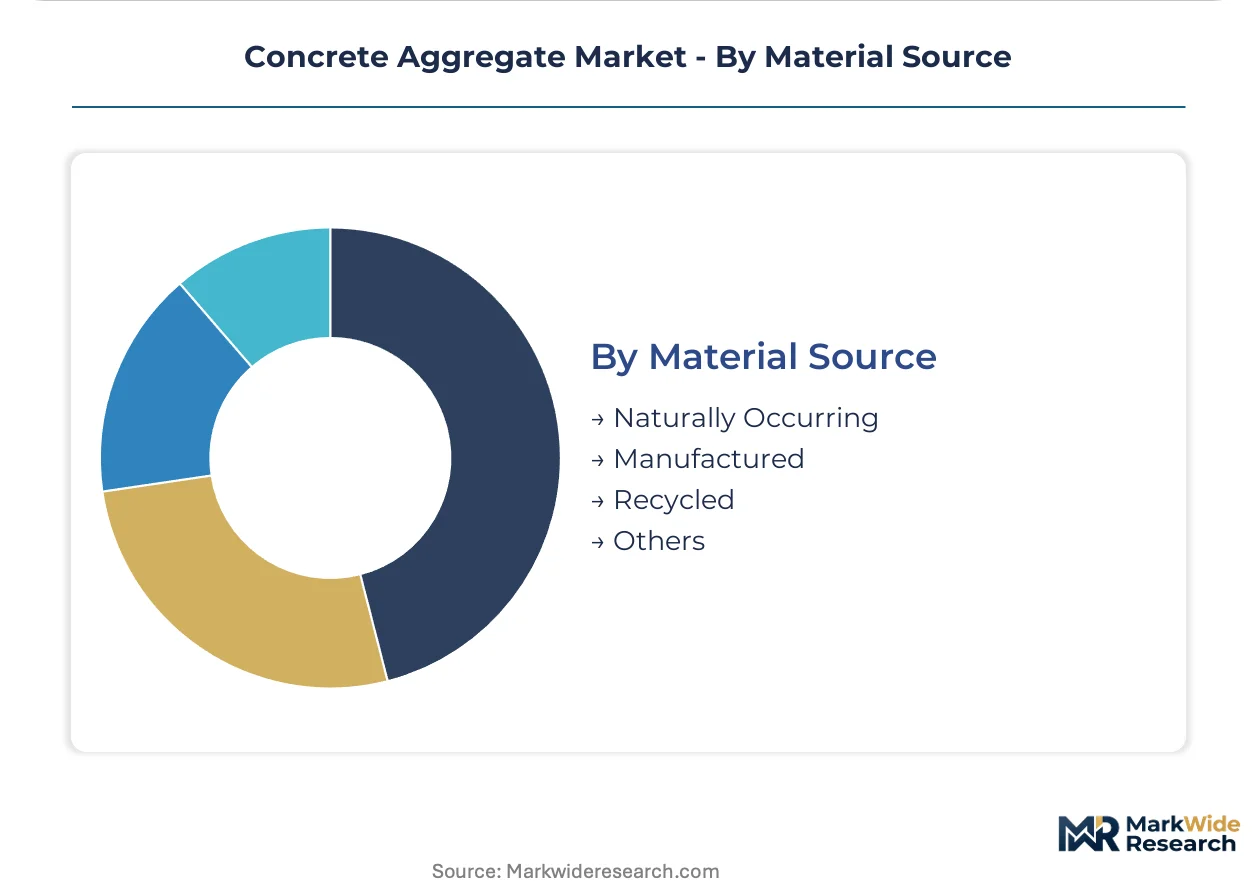
Material Source:
Material source segmentation tracks feedstock origin and regulatory treatment under embodied carbon accounting frameworks. Naturally occurring sources face extraction licensing constraints while recycled streams navigate contaminant removal technology thresholds.
- Naturally Occurring:Virgin crushed stone, gravel, and sand from licensed quarries and dredging operations. Vulcan Materials Company leverages captive quarry networks across the southeastern United States to control feedstock quality and logistics costs for naturally occurring aggregate supply.
- Recycled:Post-demolition concrete and asphalt processed to specification-grade particle shape and contaminant thresholds. Martin Marietta Materials anchors position through deep reserves of high-specification granite and limestone in Texas and North Carolina, competing against recycled feedstock through quality consistency rather than carbon intensity.
- Manufactured:Crushed rock fines and artificial sand from hard-rock quarry byproducts.
- Others:Slag, mining waste, and industrial byproduct aggregates.
Naturally Occurring sources retain dominant installed capacity. Recycled is expanding most quickly as optical sorting technology unlocks commercial-scale demolition waste processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concrete aggregate industry traces its modern scale to post-war reconstruction programs in Europe and North America, where standardized crushed stone specifications enabled mass infrastructure deployment. Today, demand concentrates in corridor economies where megaproject pipelines intersect with quarry licensing constraints.
United States
Southeastern expressway expansions and port modernization are absorbing record volumes of specification-grade limestone. OSHA silica exposure limits are compelling capital investment in enclosed crushing circuits across Georgia and Florida. The I-95 corridor from Virginia to Florida anchors domestic demand, with state DOT qualified product lists restricting market access for uncertified producers.
Vietnam
Hanoi-Haiphong expressway expansion and deepwater port construction are depleting licensed quarry reserves in the Red River Delta. Provincial mining authorities are granting new extraction permits slower than project timelines demand. The Red River Delta corridor faces acute supply bottlenecks as consortia lock in dedicated quarry output five years ahead of construction commencement.
Germany
Demolition contractors are installing mobile processing trains that convert construction debris into certifiable recycled aggregate on-site. REACH regulation updates on construction product safety are extending hazardous substance screening to imported aggregate streams. The Rhine-Ruhr industrial cluster is pioneering carbonated recycled aggregates that chemically sequester CO2 during curing.
China
Yangtze River Delta infrastructure spending is specifying manufactured sand substitution for dredged river sand in public bids. The country's dual carbon goals are mandating lower-clinker cement formulations that perform optimally with processed recycled aggregates. The Pearl River Delta is deploying optical sorting systems to remove contaminants from demolition waste at commercial scale.
India
Maharashtra and Gujarat highway corridors are driving dense-graded crushed rock consumption for concrete pavement. BIS quality protocols are restricting market access for uncertified producers through qualified product lists. The Delhi-Mumbai Industrial Corridor is absorbing record aggregate volumes as state governments accelerate expressway construction timelines.
Concrete Aggregate Market Competitive Landscape
The competitive structure tilts toward vertically integrated materials conglomerates with captive quarry networks and multi-channel downstream operations. Tier-one positions cluster with operators controlling deep reserves of high-specification hard rock and rail-linked distribution infrastructure. Three archetypes dominate: quarry-captive specialists with logistics cost advantages, integrated building materials groups with asphalt and ready-mix internalization, and recycled aggregate processors with optical sorting capabilities. Consolidation through quarry acquisitions and long-term supply agreements with megaproject consortia represent the dominant competitive moves.
Among North American quarry-captive operators, Vulcan Materials Company and Martin Marietta Materials exemplify the reserve-control archetype through southeastern and Texas-North Carolina positioning. CRH plc occupies a position representing the integrated-model archetype with multi-channel downstream internalization. These three anchors illustrate how competitive positioning diverges between feedstock quality consistency and carbon intensity credentials.
| Leading Market Players |
|---|
| Vulcan Materials Company |
| Martin Marietta Materials |
| CRH plc |
| Heidelberg Materials |
| CEMEX |
| Holcim |
| LafargeHolcim |
| Lehigh Hanson |
| Summit Materials |
| Others |
Value Network & Pricing Analysis
EU Green Deal embodied carbon thresholds gate both qualified supply and premium-tier pricing access, compressing margins for conventional aggregate producers while rewarding operators with verified environmental product declarations and processed recycled feedstock streams. Procurement agencies now mandate material traceability that favors certified suppliers with blockchain-tracked batches commanding placement premiums on qualified product lists.
Pricing Analysis
Contract-based long-term offtake agreements with volume guarantees and fixed escalators dominate megaproject procurement in Vietnam and Indonesia, displacing spot-market volatility for infrastructure consortia. Price differentiation rests on certification grade and geographic delivery cost, with state DOT qualified product list status separating premium-tier suppliers from uncertified competitors. Cost compression in standard-grade natural aggregate is intensifying because EU Green Deal thresholds are mandating manufactured sand substitution for dredged river sand. Residential builders exhibit highest price sensitivity, while infrastructure departments of transportation prioritize specification compliance over unit economics.
Supply Chain Analysis
Reverse-logistics flows through demolition contractor mobile processing trains in Germany and the Netherlands are converting construction debris into certifiable recycled aggregate on-site, bypassing traditional quarry-to-batch-plant distribution. Supply concentrates in Vietnam, the United States, and China, with the Red River Delta corridor exhausting licensed reserves faster than provincial mining authorities grant new extraction permits. Raw material dependencies center on hard-rock quarry reserves, manufactured sand feedstock, and processed demolition waste streams. Single-source vulnerability from licensed quarry depletion in high-demand corridors poses structural risk. Distribution runs through rail-linked captive quarry networks and multi-year supply agreements with volume guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's acute supply bottleneck against Germany's surplus recycled aggregate processing capacity creates a geographic-arbitrage play for operators with cross-border logistics capabilities and carbon-credential portability.
For Market Incumbents: Hedge against licensed quarry depletion in Vietnam's Red River Delta by securing backward integration into demolition waste processing technology and optical sorting capabilities. Anchor position through deep reserves of high-specification granite and limestone in Texas and North Carolina where Martin Marietta Materials competes through quality consistency. Prioritize certification investment for environmental product declarations to maintain access to EU public infrastructure frameworks as REACH regulation updates extend hazardous substance screening. For New Entrants and Emerging Players: Begin with urban mining integration targeting Germany and the Netherlands demolition contractor networks where mobile processing trains convert construction debris into certifiable recycled aggregate on-site. The most penetrable segment sits with commercial construction batching plants seeking carbonated recycled aggregates that chemically sequester CO2 during curing. Pursue digital material passport go-to-market positioning with blockchain-tracked aggregate batches embedding lifecycle data for green procurement tenders. For Investors and Strategic Acquirers: Valuations sit cheapest among recycled aggregate processors with optical sorting capabilities and contaminant removal technology thresholds that unlock commercial-scale demolition waste processing. Long-term viability across the analysis window favors operators with integrated asphalt and ready-mix operations that internalize aggregate demand across multiple downstream channels. Watch for inflection signals when state departments of transportation accelerate aggregate source approval timelines from current 18-24 month backlogs.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Capture Concrete Partnership | Precast manufacturers sourcing carbonated recycled aggregates qualify for EU Green Deal procurement tenders. |
| Mobile Processing Train Deployment | German demolition contractors convert construction debris into certifiable recycled aggregate on-site for commercial batching. |
| Digital Material Passport Implementation | Blockchain-tracked aggregate batches with embedded lifecycle data command premium placement on DOT qualified product lists. |
| Deep Reserve Acquisition | Captive quarry networks in Texas and North Carolina control feedstock quality and logistics costs for specification-grade supply. |
| Optical Sorting Technology Retrofit | X-ray transmission sorters remove deleterious clay and soft stone before crushing, cutting downstream processing energy by one-third. |
Research Methodology
Bottom-up infrastructure project modeling reconciled against top-down quarry production tracking forms the analytical core of this study. Primary interviews with quarry operations managers, state DOT materials engineers, demolition contractor executives, and ready-mix procurement directors combined with secondary validation from SEC 10-K filings, customs and trade data, state qualified product list databases, and EPA effluent guideline documentation. Triangulation between stakeholder input and regulatory filing analysis ensures segment-level accuracy.
Historical trendline analysis across the projection horizon incorporates dense-graded crushed rock consumption patterns, manufactured sand substitution rates, and recycled aggregate processing capacity expansion. The analytical framework models product type segmentation by particle size and material source, application segmentation by specification stringency, and end user segmentation by compliance burden. CAGRs derive from volume trajectory analysis against licensed quarry reserve depletion rates and megaproject pipeline announcements. Industry-specific forecast inputs include EPA silica exposure compliance cost curves and EU Green Deal embodied carbon threshold implementation timelines.
Several conditions sit outside the modeled scope, including unforeseen regulatory acceleration of REACH candidate list expansion, abrupt provincial mining authority licensing moratoriums in Vietnam, and breakthroughs in carbon-capture concrete curing chemistry that displace conventional aggregate specifications. Forecasts reflect documented assumptions about megaproject construction commencement schedules and optical sorting technology cost reduction curves. Practitioners should monitor state DOT aggregate source approval backlog durations and EU Green Deal procurement agency disclosure mandate enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Iron and Steel Casting Market
Building & Construction Materials
Railing Market
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
China Oriented Strand Board Market
Building & Construction Materials
Particleboard Market
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
Plumbing Components Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
Japan Concrete Conditioner Market
Building & Construction Materials
Europe Industrial Flooring Market