
 Canada Architectural Coatings Market | 2026-2036
Canada Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Architectural Coatings Market Outlook
Asset-light distribution leasing is fragmenting capital requirements across the Canada architectural coatings sector, enabling regional challengers to secure shelf space without owning manufacturing footprints. Société Laurentide leverages Quebec-based manufacturing to sustain competitive logistics across Eastern Canada. PPG Industries Inc. anchors its position through deep contractor relationships and specification-grade product lines. Benjamin Moore & Co. differentiates via controlled dealer networks that limit price transparency and protect margin pools.
Canada architectural coatings comprise resin-bound pigmented films formulated for adhesion, weather resistance, and aesthetic finish on building substrates, with acrylic emulsions dominating exterior applications due to UV stability and breathability. These materials protect structural surfaces while enabling color customization across residential, commercial, and institutional environments. Acrylic formulations lead the product type landscape, reflecting their compatibility with low-VOC regulatory mandates and broad substrate applicability. The residential application segment generates substantial volume, though institutional projects command premium pricing through extended warranty and certification requirements. DIY enthusiasts represent a growing end user category, driven by digital color-matching tools and direct-to-consumer e-commerce channels.
Health Canada's PMRA regulates biocide content in interior coatings, while Environment Canada enforces VOC concentration limits under the Chemicals Management Plan, compelling manufacturers toward waterborne and zero-VOC formulations. The Canadian General Standards Board and CSA Group certification programs further shape product eligibility for federal and provincial procurement contracts. Stakeholders must monitor evolving federal green building standards and provincial carbon reduction commitments that will progressively favor coatings with verified lifecycle environmental performance.
Market Dynamics
Health Canada's PMRA and Environment Canada's Chemicals Management Plan are tightening VOC limits, forcing manufacturers to abandon solvent-borne formulations and rebuild supply chains around waterborne acrylic systems. This regulatory compression is the dominant structural force reshaping competitive positioning.
Growth Catalysts
- Heritage restoration mandates:Federal and provincial heritage preservation programs in Ontario and Quebec are sustaining specialized coating demand for historic building substrates.
- CSA Group certification expansion:New performance standards for exterior durability are creating procurement eligibility for premium-grade waterborne systems in institutional projects.
- Condominium construction clusters:The Greater Toronto Area's high-rise residential pipeline is generating concentrated specification-grade volume for protective facade coatings.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings compress margin pools for mid-tier waterborne formulations without indexed pricing power.
- Biocide approval delays:Health Canada's PMRA extended review timelines for new interior coating preservatives are freezing product launch schedules.
- DIY substitution pressure:Big-box retail channels are pushing private-label alternatives that erode brand equity in residential renovation segments.
Strategic Opportunities
- Atlantic Canada underpenetration:Maritime provinces lack dedicated manufacturing footprint, creating white space for Quebec-based distributors with refrigerated logistics capability.
- Digital color-matching platforms:Direct-to-consumer e-commerce channels are enabling margin capture previously lost to contractor intermediaries in residential repaint.
- Federal green building procurement:Verified lifecycle environmental performance standards are opening specification pathways for zero-VOC formulations in Crown corporation projects.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in waterborne acrylic stabilization is concentrating among aging technical workforces without pipeline replacement.
- Freeze-thaw stability testing:CSA Group certification requires extended Canadian climate validation that extends commercialization timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Architectural Coatings Market |
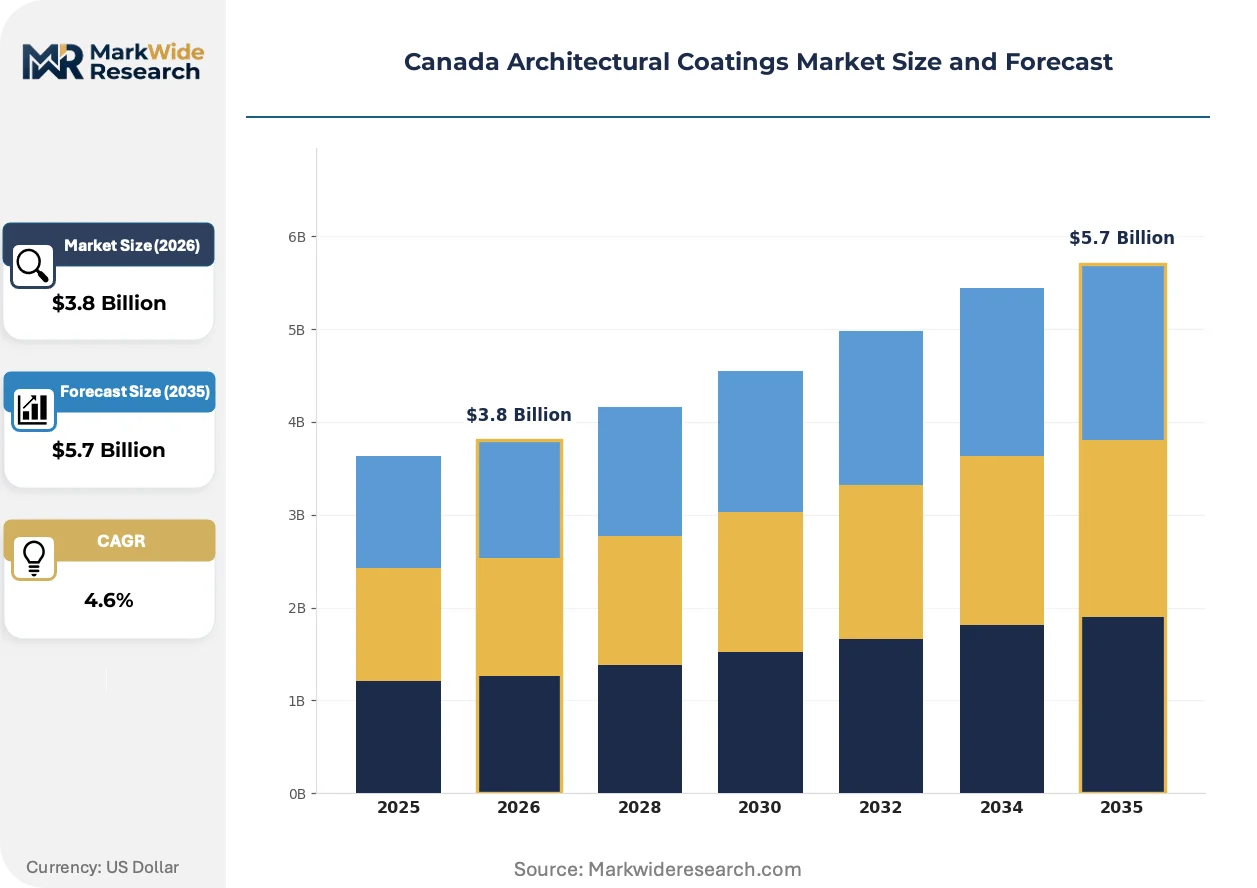
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Alkyd, Polyurethane, Epoxy Application: Residential, Commercial, Industrial, Institutional Form: Liquid, Powder, Gel, Spray End User: Builders, Contractors, Architects, DIY Enthusiasts |
| Companies Covered | Cloverdale Paint Inc., RPM International Inc., Benjamin Moore & Co., Société Laurentide, KelCoatings Limited, The Sherwin-Williams Company, Masco Corporation, Selectone Paints Inc., PPG Industries Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Architectural Coatings Market Strategic Shifts
Reformulation pressure from Environment Canada's VOC limits is accelerating material science investment across Canadian coating laboratories. Three distinct shifts are reshaping product architecture and go-to-market models.
Self-cleaning photocatalytic titanium dioxide coatings are migrating from commercial facade specifications into premium residential exterior segments. Ontario condominium developers are specifying these systems for high-visibility elevations. The technology is migrating from niche architectural prestige projects toward mid-market volume applications as unit economics improve.
Environment Canada's Chemicals Management Plan is phasing solvent-borne alkyd interior trim products from federal procurement eligibility. Manufacturers are retiring legacy oil-based enamel lines ahead of schedule. The institutional segment is responding fastest, with Crown corporations rewriting specifications to mandate waterborne alternatives.
Contractor purchasing behavior is fragmenting across project-scale tiers. Large mechanical coating applicators are consolidating specification influence through direct manufacturer relationships. Small residential painters are shifting toward big-box retail with digital color-matching tools, compressing traditional dealer channel volume in Ontario and British Columbia.
Canada Architectural Coatings Market Segmentation
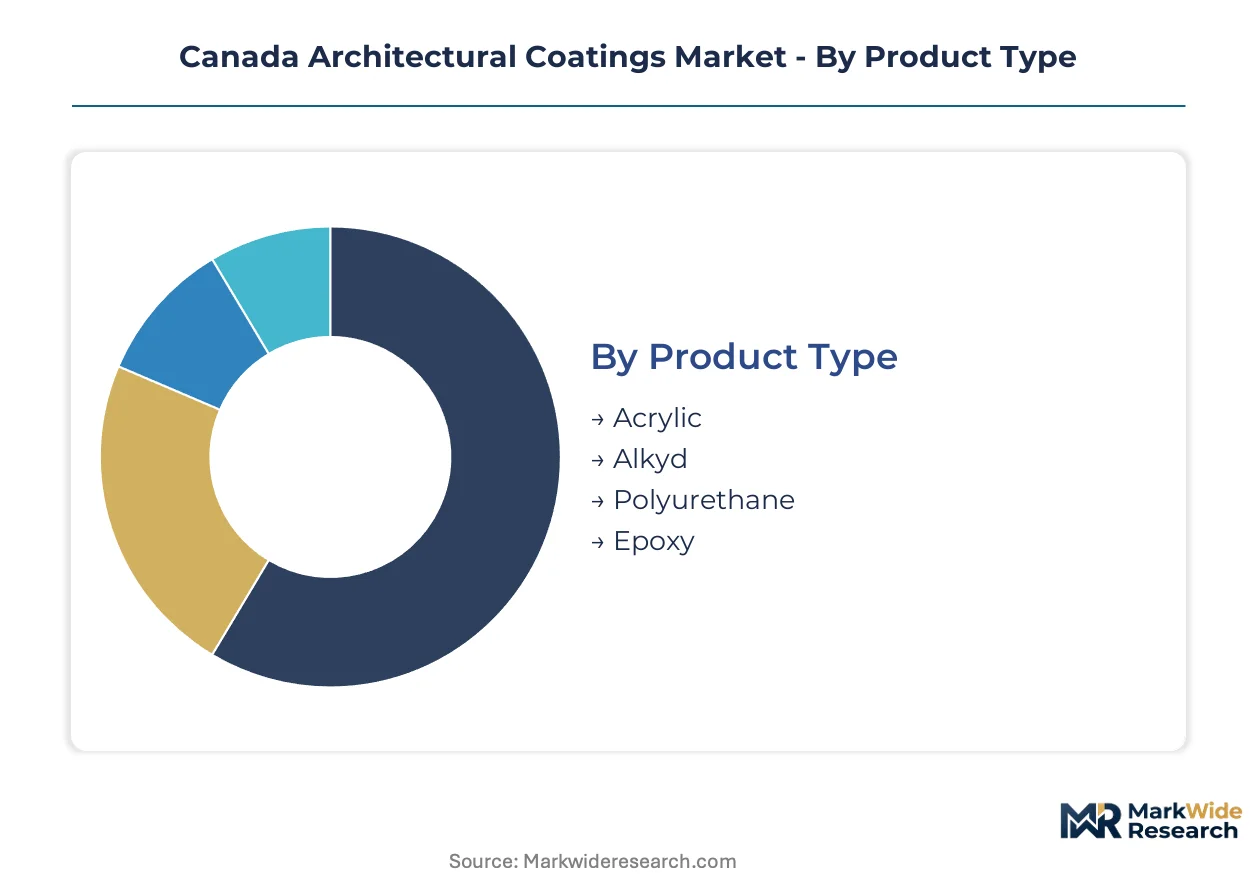
Segmentation in Canada's architectural coatings market reveals how regulatory pressure and application requirements fragment demand across distinct technical specifications. Each dimension—product chemistry, building type, physical form, and purchaser identity—carries unique margin structures and competitive dynamics.
Product Type:
Mature waterborne technologies dominate volume, while emerging high-performance chemistries capture specification premiums in demanding applications.
- Acrylic:Emulsion-based formulations provide UV stability and substrate breathability for exterior facades. Demand concentrates in Ontario's condominium construction sector, where developers specify low-VOC systems to meet Toronto Green Standard requirements.
- Alkyd:Oil-modified polyester resins deliver hard, glossy finishes for interior trim and cabinetry. Heritage restoration projects in Quebec sustain solvent-borne alkyd demand despite Environment Canada's phasedown schedule, as preservation architects prioritize traditional appearance over reformulation.
- Polyurethane:Two-component systems offer abrasion resistance for commercial flooring and high-traffic institutional environments.
- Epoxy:Amine-cured coatings provide chemical resistance for industrial maintenance and healthcare facility wall systems.
Acrylic retains volume leadership; polyurethane holds the steepest expansion curve as commercial flooring specifications tighten durability requirements.
Application:
Cost tier differentiation separates commodity residential repaint from premium institutional procurement with extended warranty demands.
- Residential:Exterior and interior repaint for single-family homes and multi-unit dwellings. Demand clusters in the Greater Toronto Area's renovation market, where homeowners prioritize energy-efficient exterior finishes and digital color-matching tools.
- Commercial:Office, retail, and hospitality spaces requiring coordinated aesthetic specifications. Vancouver's green building mandates are accelerating specification of zero-VOC systems in Class A office developments.
- Industrial:Manufacturing facilities, warehouses, and infrastructure requiring corrosion protection and chemical resistance.
- Institutional:Schools, hospitals, and government buildings with certification requirements and lifecycle performance verification. Federal procurement through Public Services and Procurement Canada increasingly mandates CSA Group-certified durability standards.
Residential commands absolute volume; institutional delivers the highest per-gallon margins through specification-grade certification requirements.
Form:
Application method determines logistics infrastructure, with liquid systems requiring established distribution networks and powder coatings demanding specialized electrostatic equipment.
- Liquid:Conventional brush, roll, and spray application for field-applied architectural finishes. The format dominates Canadian distribution, with Quebec-based manufacturers leveraging established tanker and drum logistics across Eastern provinces.
- Powder:Thermosetting resin systems cured through heat for metal substrates and factory-applied architectural elements. Ontario's curtainwall and aluminum extrusion fabricators are expanding in-house powder coating capacity to capture value from exterior metal finishing.
- Gel:Thixotropic formulations for vertical surface application and repair work on structural substrates.
- Spray:Aerosol and pressure-fed systems for touch-up, maintenance, and specialized contractor equipment.
Liquid maintains distribution dominance; powder coatings are gaining share fastest in prefabricated architectural component manufacturing.
End User:
Purchasing behavior fragments across professional specification authority and direct consumer access, reshaping channel strategy for manufacturers.
- Builders:Production homebuilders and custom residential developers purchasing at volume through distributor relationships. Calgary and Edmonton markets show concentration in large-scale subdivision projects with standardized color palettes.
- Contractors:Professional painting firms with specification influence through direct manufacturer relationships. Large mechanical coating applicators in Ontario are consolidating purchasing power and bypassing traditional dealer networks.
- Architects:Design professionals writing performance specifications for institutional and commercial projects. Health Canada's PMRA biocide regulations increasingly appear as explicit specification clauses in healthcare and school construction documents.
- DIY Enthusiasts:Homeowners purchasing through retail channels with digital color-matching support. British Columbia shows elevated e-commerce penetration in this segment, with direct-to-consumer platforms capturing margin previously lost to contractor intermediaries.
Contractors retain specification authority in commercial volume; DIY enthusiasts are expanding most quickly as digital tools reduce color-matching friction in residential repaint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Environment Canada's Chemicals Management Plan is redistributing manufacturing investment toward provinces with established waterborne coating infrastructure. Provincial building codes and heritage preservation programs create divergent demand profiles across Canadian sub-regions.
Ontario
Condominium construction in the Greater Toronto Area drives specification-grade volume for protective facade coatings. Toronto Green Standard requirements accelerate low-VOC system adoption in new high-rise developments. Hamilton and Ottawa industrial corridors host reformulation laboratories serving federal procurement contracts.
Quebec
Heritage restoration mandates in Montreal and Quebec City sustain solvent-borne alkyd demand for historic building substrates. Société Laurentide leverages provincial manufacturing for Eastern Canada distribution. Provincial preservation architects prioritize traditional appearance over rapid reformulation timelines.
British Columbia
Vancouver green building mandates specify zero-VOC systems in Class A office developments. DIY e-commerce penetration exceeds national averages, with direct-to-consumer platforms capturing contractor-intermediary margins. Victoria heritage districts generate specialized coating demand for coastal climate durability.
Alberta
Calgary and Edmonton production homebuilders standardize color palettes across large-scale subdivision projects. Energy sector maintenance cycles drive industrial coating volume for infrastructure protection. Provincial procurement increasingly references CSA Group certification for institutional durability standards.
Atlantic Canada
Maritime provinces lack dedicated manufacturing footprint, creating white space for Quebec-based distributors with refrigerated logistics capability. Halifax commercial development generates specification demand without local production capacity. Federal infrastructure programs channel coating procurement through established Eastern supply chains.
Canada Architectural Coatings Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement segments. The vendor base stratifies between multinational coating manufacturers with specification-grade portfolios and regional formulators serving contractor relationships. Three archetypes dominate: vertically integrated resin-to-retail operators, asset-light distributors leasing shelf space without manufacturing, and heritage-focused specialists preserving solvent-borne formulations. Competitive moves concentrate on backward integration into resin supply and digital color-matching platform deployment.
Within the regional specialist tier, Société Laurentide and Cloverdale Paint Inc. exemplify Quebec-based and Western Canada-based manufacturing strategies respectively. PPG Industries Inc. occupies a position representing multinational specification-grade presence. These three anchors illustrate the geographic and structural fragmentation shaping procurement patterns across provincial markets.
| Leading Market Players |
|---|
| Cloverdale Paint Inc. |
| RPM International Inc. |
| Benjamin Moore & Co. |
| Société Laurentide |
| KelCoatings Limited |
| The Sherwin-Williams Company |
| Masco Corporation |
| Selectone Paints Inc. |
| PPG Industries Inc. |
| Others |
Value Chain & Pricing Dynamics
Quebec's manufacturing corridor concentrates waterborne acrylic capacity, granting Société Laurentide and regional formulators outsized influence over Eastern Canadian pricing. This geographic clustering enables indexed pigment contracts that buffer margin volatility for established players while forcing Atlantic distributors to absorb logistics premiums.
Pricing Analysis
Certification level creates the primary spread, with CSA Group-certified durability standards commanding substantial premiums over uncertified alternatives in institutional procurement. Three-tier pricing structure across specification-grade, contractor-grade, and retail-grade levels reflects warranty length and VOC compliance tier. Cost compression in mid-tier waterborne formulations is intensifying because titanium dioxide feedstock volatility lacks indexed pricing power for non-integrated players. DIY enthusiasts through big-box channels exhibit highest price sensitivity, while Crown corporation procurement teams prioritize lifecycle performance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Quebec-based toll coaters and Ontario blending facilities serving federal procurement contracts. Geographic supply concentration centers on Canada and the United States, with specialty resin feedstocks drawing from German and Japanese chemical producers. Raw material dependencies hinge on titanium dioxide pigment, acrylic emulsion resins, and EPA-registered biocide preservatives. Single-source vulnerability runs through Health Canada PMRA-approved preservative suppliers facing extended approval timelines. Distribution runs through controlled dealer networks in Ontario and Quebec, with direct-to-consumer platforms gaining share in British Columbia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across provincial regulatory clusters and application tiers creates multiple entry niches for specialized players. Specification-grade institutional demand and heritage restoration mandates reward focused technical capabilities over scale.
For Market Incumbents: Build specification moats through CSA Group certification pre-emption and Toronto Green Standard compliance pathways. Deepen backward integration into acrylic emulsion supply to offset titanium dioxide volatility. Secure exclusive distributor relationships in Atlantic Canada before Quebec-based competitors establish refrigerated logistics footprints. Channel control remains essential as contractor purchasing consolidates around large mechanical applicators. For New Entrants and Emerging Players: Pursue digital color-matching platform deployment to capture DIY enthusiast margins in British Columbia and Alberta. Target Maritime provinces' specification demand without local manufacturing capacity, leveraging toll coating arrangements with Quebec facilities. Heritage restoration in Montreal and Quebec City offers penetrable white space where preservation architects prioritize traditional alkyd appearance over rapid reformulation. Go-to-market through direct specification relationships with Crown corporation procurement officers bypasses entrenched dealer networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors waterborne formulation specialists with Health Canada PMRA registration pipelines over legacy solvent-borne portfolios. Long-term viability hinges on zero-VOC capability and federal green building procurement eligibility. Acquisition targets should demonstrate CSA Group certification infrastructure and established relationships with Public Services and Procurement Canada. Monitor biocide approval timelines at PMRA as inflection signal for product launch velocity and working capital requirements.| Strategic Initiative | Industry Significance |
|---|---|
| CSA Group Certification Investment | Unlocks Crown corporation procurement eligibility through verified durability standards. |
| Backward Integration into Acrylic Emulsions | Captures margin pools exposed to titanium dioxide feedstock volatility. |
| Digital Color-Matching Platform Deployment | Enables direct-to-consumer margin capture in British Columbia DIY segments. |
| Atlantic Canada Distribution Expansion | Addresses white space in Maritime provinces lacking dedicated manufacturing footprint. |
| Zero-VOC Formulation Pipeline | Aligns with Environment Canada's Chemicals Management Plan phasedown schedule. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with coating formulators, contractor purchasing managers, and Crown corporation procurement officers; and secondary validation through Health Canada PMRA registration databases, Environment Canada Chemicals Management Plan filings, and CSA Group certification records. Bottom-up volume modeling triangulated against top-down construction spending data from Statistics Canada and provincial heritage preservation program budgets.
Forecast inputs incorporated product chemistry transitions, application segment growth differentials, and provincial regulatory adoption curves across the projection horizon. Segmentation dimensions modeled include resin technology tier, building type specification requirements, physical form logistics infrastructure, and purchaser identity channel dynamics. CAGRs derived from regression analysis of historical coating consumption against housing starts, renovation spending, and institutional construction pipelines.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting residential renovation financing or federal infrastructure program allocations would shift the trajectory. Forecasts reflect assumptions regarding PMRA biocide approval timelines and Toronto Green Standard adoption velocity. Quarterly review of Crown corporation procurement specifications and provincial heritage restoration funding announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
India Dry Mix Mortar Market
Building Materials
Concrete Admixtures Market
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Composite Rebar Market
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
Cladding Market
Building Materials
Global Building Panels Market
Building Materials
Italy Facade Market
Building Materials
Ductile Iron Pipe Market
Building Materials
Cellular Concrete Market
Building Materials
HDG Steel Pipe Market
Building Materials
Germany Aluminum Door and Window Market
Building Materials
South Africa White Cement Market
Building Materials
Asia-Pacific Shotcrete Market
Building Materials
Fly Ash Bricks Market
Building Materials
Construction Glass Market