
 Steel Products Market | 2026-2036
Steel Products Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Products Market Outlook
India's western industrial corridor is rewriting capacity deployment patterns across flat and long steel products. ArcelorMittal leverages its integrated European-African mining-to-mill network to secure pellet feedstock for high-grade output. Nucor Corporation sustains its electric arc furnace leadership across the US Southeast through scrap optimization and mini-mill scale. JSW Steel anchors Indian flat steel supply with its Vijayanagar complex and downstream coating capabilities.
Steel products encompass rolled, forged, cast, and fabricated metal outputs derived from iron-carbon alloys with controlled manganese, silicon, and trace element content, typically produced through basic oxygen or electric arc furnace routes followed by continuous casting and hot or cold rolling to achieve specified tensile strengths, yield points, and dimensional tolerances for structural load-bearing, forming, or corrosion-resistant applications. Flat steel dominates volume flows into automotive OEM body-in-white and appliance panel stamping, where surface quality and thickness uniformity command premium contract structures. Long steel competes on rebar and structural section specifications tied to seismic-grade construction codes across high-growth urban corridors. Stainless steel within the grade taxonomy captures disproportionate margin pools from chemical processing and medical equipment end users demanding ASTM A240-compliant corrosion resistance.
The US EPA enforces greenhouse gas reporting and effluent limits under Clean Water Act permits that shape blast furnace slag handling and coke oven emission controls across integrated mills. China's MEE implements dual carbon goals through provincial emission caps that redirect investment toward hydrogen-reduced iron pilot programs and scrap-based EAF expansion. India's BIS mandates IS 1786 rebar certification for earthquake-prone zones, creating compliance barriers for uncertified imports. Stakeholders must monitor which regulatory jurisdictions accelerate carbon border adjustments first, as this will determine competitive access for export-dependent producers.
Market Dynamics
China's MIIT emission intensity benchmarks are forcing blast furnace operators to accelerate hydrogen-reduced iron pilot programs while simultaneously constraining domestic capacity expansion, redirecting investment flows toward scrap-based electric arc furnace routes and reshaping global trade flows for high-grade flat steel.
Growth Catalysts
- Seismic-grade construction codes:India's BIS mandates IS 1786 rebar certification for earthquake-prone zones, creating mandatory replacement cycles for substandard structural steel across high-growth urban corridors.
- Automotive lightweighting specifications:Advanced high-strength steel grades above 980 MPa tensile strength enable thinner-gauge body-in-white panels that maintain crashworthiness while reducing vehicle curb weight.
- Scrap optimization technologies:Electric arc furnace operators deploy real-time chemical analysis and automated charge recipes to expand the share of lower-grade scrap in prime-grade output.
Market Restraints
- Iron ore pellet feedstock concentration:Premium-grade direct-reduction pellet supply concentrates among integrated mining-to-mill networks, limiting independent EAF access to high-purity inputs.
- Coke oven emission compliance costs:US EPA Clean Water Act effluent limits and greenhouse gas reporting requirements impose capital-intensive abatement retrofits on integrated blast furnace operations.
- Aluminum substitution in automotive panels:OEMs specify aluminum sheet for hoods and door skins in battery-electric vehicle platforms above 400 km range targets.
Strategic Opportunities
- Western India industrial corridor:Demand concentrates between Mumbai and Pune for coated flat steel serving appliance manufacturing and automotive component stamping.
- Green hydrogen reduction pilots:China's provincial emission caps under dual carbon goals channel state investment toward hydrogen-reduced iron demonstration plants.
- Direct mill-to-project procurement:Construction consortia bypass distributor tiers to negotiate long-term offtake agreements with integrated flat steel producers.
Industry Challenges
- Metallurgical coal sourcing constraints:Blast furnace operators face volatile coking coal import dependencies from concentrated supply origins.
- Skill gaps in hydrogen process engineering:Pilot plant commissioning delays reflect scarcity of process engineers with direct-reduction and hydrogen handling expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Products Market |
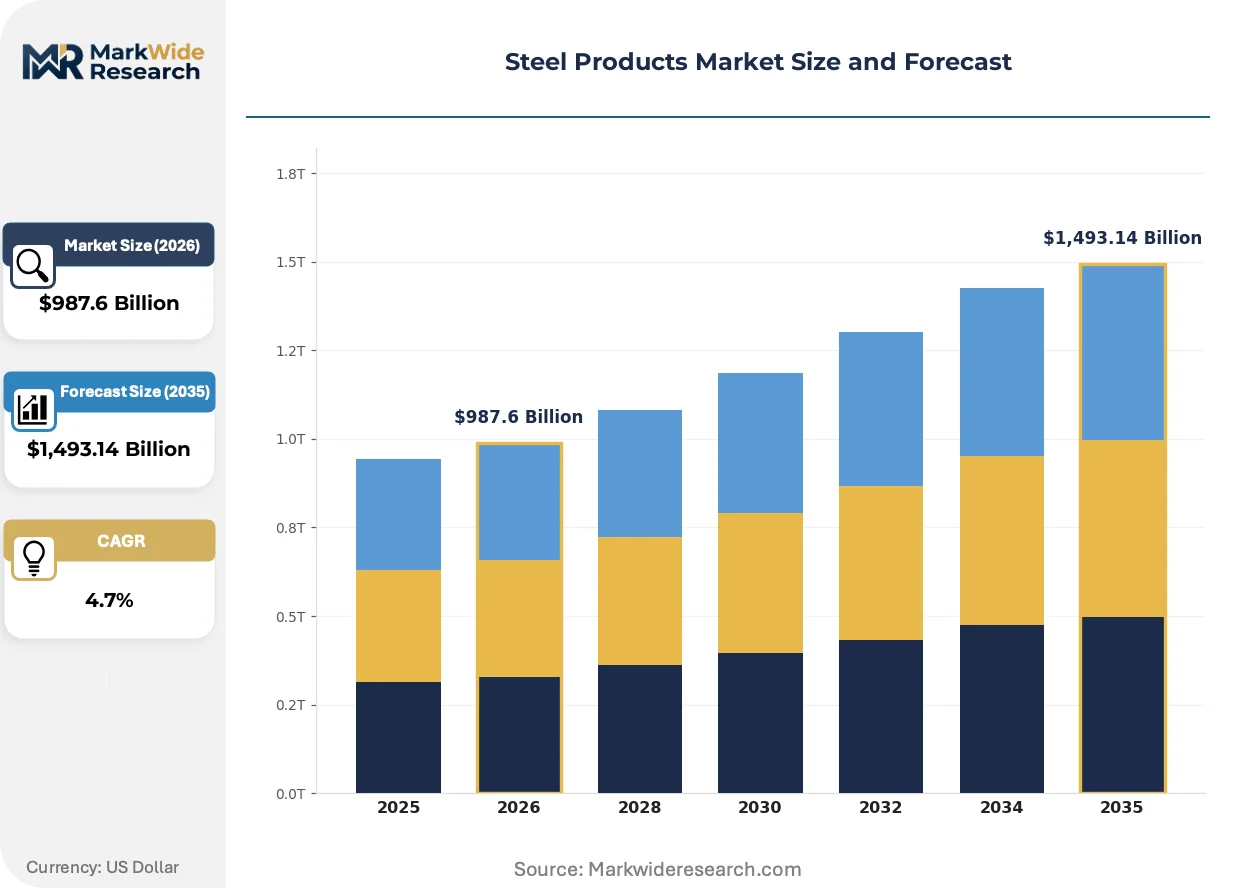
| Market Size in 2026 | $987.6 Billion |
| Market Size in 2035 | $1,493.14 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Steel, Long Steel, Steel Pipes, Steel Bars Application: Construction, Automotive Manufacturing, Shipbuilding, Machinery End User: Construction Firms, Automotive OEMs, Shipbuilders, Industrial Manufacturers Grade: Carbon Steel, Alloy Steel, Stainless Steel, Tool Steel |
| Companies Covered | ArcelorMittal, China Baowu Steel Group, Nippon Steel Corporation, POSCO, Nucor Corporation, Tata Steel, JSW Steel, Steel Dynamics, Thyssenkrupp Steel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Products Market Strategic Shifts
Hydrogen-based reduction pathways, regulatory carbon accounting, and procurement model consolidation are compressing legacy process economics while rewarding early movers with integrated low-carbon supply chains.
Green hydrogen direct reduction is collapsing the cost gap between scrap-based EAF and virgin ore-based steel for automotive OEMs specifying Scope 3 emission targets. European automakers now require mill certificates documenting carbon intensity below 1.5 tonnes CO2 per tonne steel. This specification is collapsing the premium commanded by traditional blast furnace routes in contract negotiations.
China's MEE provincial emission caps under dual carbon goals are redirecting investment toward hydrogen-reduced iron pilot programs and scrap-based EAF expansion. Integrated mills in Hebei and Jiangsu provinces face mandatory capacity swaps requiring 1.5:1 replacement ratios for new blast furnace permits. This regulatory pressure is compressing construction timelines for conventional greenfield integrated mills.
Construction consortia across Southeast Asia are consolidating procurement through direct mill-to-project offtake agreements that bypass traditional distributor networks. Tier-one contractors in Vietnam and Indonesia now negotiate annual volume commitments with flat steel producers for guaranteed slab allocation. This channel compression is displacing regional trading houses from premium-grade structural sections.
Steel Products Market Segmentation
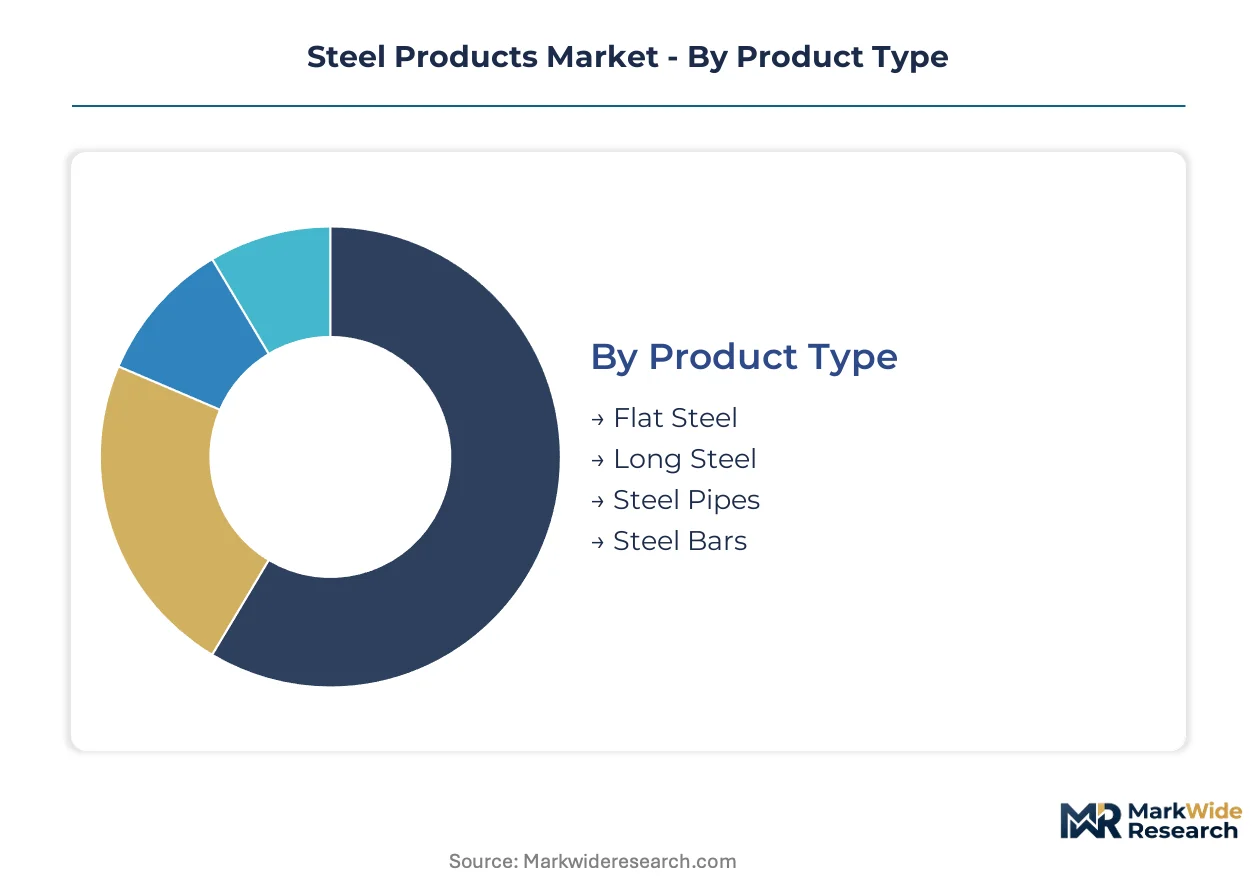
Steel product segmentation reveals how metallurgical specifications, dimensional forms, and end-use performance requirements fragment supply chains into distinct competitive arenas. Each category channels investment toward different furnace technologies, rolling capacities, and certification standards.
Product Type:
Dimensional form dictates rolling mill configuration, surface quality thresholds, and downstream processing intensity across the use-case spectrum.
- Flat Steel:Continuously cast slabs undergo hot and cold rolling to achieve precise thickness tolerances and surface finishes required for automotive body-in-white stamping and appliance panel fabrication. Demand concentrates in India's western industrial corridor between Mumbai and Pune, where coating lines serve appliance manufacturing and automotive component clusters.
- Long Steel:Billets and blooms transform into rebar, structural sections, and wire rod through rolling mills configured for length-to-thickness ratios optimized for load-bearing applications. Seismic-grade construction codes across India's earthquake-prone urban corridors mandate IS 1786 certified rebar, creating specification barriers for uncertified imports.
- Steel Pipes:Seamless and welded tubular products serve pressure-bearing infrastructure in oil, gas, and water distribution networks.
- Steel Bars:Round, square, and hexagonal bar stock feed machining operations and structural bolting applications across industrial manufacturing.
Established volume favors flat steel; emerging adoption favors long steel.
Application:
Performance requirements range from static load-bearing to dynamic crashworthiness, reshaping grade selection and certification burdens.
- Construction:Structural frameworks, reinforcement cages, and facade systems demand tensile strengths calibrated to seismic zone classifications and building height regulations. China's MIIT emission intensity benchmarks are forcing blast furnace operators toward hydrogen-reduced iron pilot programs while constraining domestic capacity expansion.
- Automotive Manufacturing:Body-in-white stampings, chassis components, and powertrain parts require advanced high-strength steel grades above 980 MPa tensile strength for lightweighting compliance. OEMs now require mill certificates documenting carbon intensity below 1.5 tonnes CO2 per tonne steel, collapsing premiums for traditional blast furnace routes.
- Shipbuilding:Plate and section steel for hull construction, bulkheads, and deck structures must meet classification society rules for marine environments.
- Machinery:Precision-machined components, gear blanks, and bearing races depend on uniform metallurgical properties and dimensional consistency.
Construction commands current tonnage; automotive specifications are climbing the fastest.
End User:
Procurement scale and technical sophistication separate project-driven spot buyers from integrated supply chain partners.
- Construction Firms:Tier-one contractors across Southeast Asia now negotiate direct mill-to-project offtake agreements that bypass traditional distributor networks for guaranteed slab allocation.
- Automotive OEMs:Vehicle assemblers specify surface quality, thickness uniformity, and carbon intensity thresholds that command premium contract structures and long-term supply partnerships.
- Shipbuilders:Yard operators concentrate demand in coastal industrial zones with integrated plate rolling and section forming capabilities.
- Industrial Manufacturers:Diverse machinery producers source bar, tube, and specialty grade products through distributor networks or direct mill relationships depending on volume scale.
Direct procurement favors construction firms; technical specification intensity favors automotive OEMs.
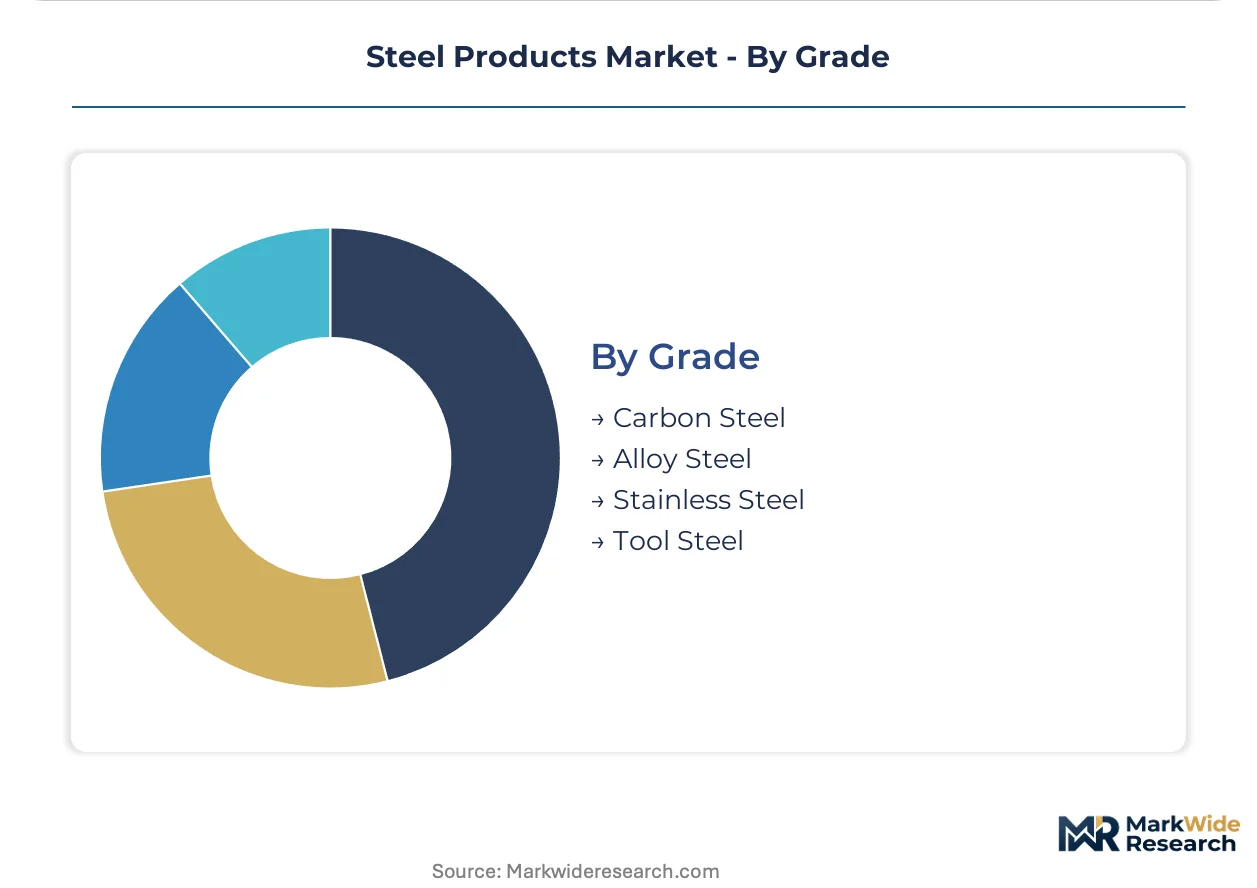
Grade:
Alloy content and heat treatment protocols determine corrosion resistance, hardness, and service temperature ranges.
- Carbon Steel:Iron-carbon alloys with controlled manganese and silicon content deliver cost-efficient strength for structural and general engineering applications dominating volume flows.
- Alloy Steel:Deliberate additions of chromium, nickel, molybdenum, and vanadium enhance hardenability, wear resistance, and high-temperature performance for powertrain and tooling applications.
- Stainless Steel:Minimum 10.5% chromium content forms passive oxide layers delivering ASTM A240-compliant corrosion resistance for chemical processing and medical equipment end users commanding disproportionate margin pools.
- Tool Steel:High carbon and alloy formulations optimized for hardness retention, wear resistance, and dimensional stability under cutting and forming stresses.
Carbon steel anchors volume; stainless steel captures premium margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated blast furnace capacity concentrates in China, India, and the United States, while scrap-based electric arc furnace expansion accelerates across North America and select European markets. Regulatory emission caps and carbon border mechanisms are redirecting investment flows toward low-carbon production routes.
China
Hebei and Jiangsu provinces host the dominant share of blast furnace capacity facing mandatory MIIT emission intensity benchmarks. Provincial authorities enforce 1.5:1 replacement ratios for new permits, compressing conventional greenfield timelines. Hydrogen-reduced iron pilot programs in Tangshan and Zhangjiagang channel state investment toward decarbonization pathways.
India
Construction firms across Maharashtra and Gujarat drive rebar and structural steel consumption tied to seismic-grade building codes. BIS mandates IS 1786 certification for earthquake-prone zones, creating compliance barriers for uncertified imports. The Mumbai-Pune industrial corridor concentrates demand for coated flat steel serving appliance manufacturing and automotive stamping clusters.
United States
Electric arc furnace operators across the Southeast optimize scrap charge recipes through real-time chemical analysis systems. EPA Clean Water Act effluent limits and greenhouse gas reporting requirements impose capital-intensive abatement retrofits on remaining integrated mills. Mini-mill scale in states like Alabama and Mississippi sustains cost leadership in long products.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify mill certificates documenting carbon intensity below 1.5 tonnes CO2 per tonne steel. EU Green Deal carbon border adjustments reshape competitive access for import-dependent fabricators. Thyssenkrupp's Duisburg complex anchors flat steel supply to premium-tier vehicle assemblers.
Japan
Shipbuilders in Nagoya and Kobe concentrate demand for plate and section steel meeting classification society rules. METI industrial policy channels investment toward hydrogen reduction pilot programs and scrap-based capacity expansion. Kansai region mills serve precision-machined component demand from machinery producers in Osaka and Kyoto.
Steel Products Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on feedstock and processing technology. The vendor base stratifies across three tiers: multinational mining-to-mill networks with captive ore supplies, regional integrated producers with downstream coating capabilities, and scrap-dependent mini-mill operators optimizing localized logistics. Dominant competitive moves include backward integration into pellet feedstock and direct mill-to-project procurement partnerships that bypass distributor networks.
Among European-anchored mining-to-mill networks, ArcelorMittal exemplifies the integrated archetype with transcontinental ore sourcing. Nippon Steel Corporation and POSCO occupy positions within the premium flat steel tier serving automotive specification intensity. JSW Steel represents the emerging market integrated model with downstream coating infrastructure tied to industrial corridor demand concentration.
| Leading Market Players |
|---|
| ArcelorMittal |
| China Baowu Steel Group |
| Nippon Steel Corporation |
| POSCO |
| Nucor Corporation |
| Tata Steel |
| JSW Steel |
| Steel Dynamics |
| Thyssenkrupp Steel |
| Others |
Value Chain & Pricing Dynamics
Premium-grade direct-reduction pellet supply concentrates among integrated mining-to-mill networks in Brazil and Australia, anchoring margin pools in automotive-grade flat steel contracts while constraining independent electric arc furnace operators to lower-purity scrap feedstock tiers.
Pricing Analysis
China's MIIT emission intensity benchmarks dictate the pricing tier structure across blast furnace and electric arc furnace routes. Pricing stratifies across premium, standard, and economy tiers based on carbon intensity certification and surface quality grade. Cost compression in standard-grade long products is intensifying because construction consortia negotiate direct mill-to-project offtake agreements that bypass distributor markups. Tier-one automotive OEMs exhibit the least price sensitivity due to Scope 3 emission compliance requirements, while regional construction firms in Southeast Asia demonstrate highest sensitivity to delivered cost fluctuations.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supply-chain finance facilities offered by integrated mills to construction consortia across Vietnam and Indonesia. Geographic supply concentration centers on China, India, and the United States for integrated blast furnace capacity, with scrap-based expansion accelerating across North America. Raw material dependencies rest on metallurgical coal from Australia and Canada, iron ore pellets from Brazil, and ferrous scrap from domestic collection networks. Single-source vulnerability in premium pellet feedstock creates structural risk for high-grade flat steel output. Distribution runs through direct mill-to-project procurement partnerships that displace regional trading houses from premium structural sections.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum substitution in battery-electric vehicle hood and door skin applications threatens steel's share in automotive body-in-white panels, forcing incumbents to defend through lightweighting grade innovation and carbon intensity certification.
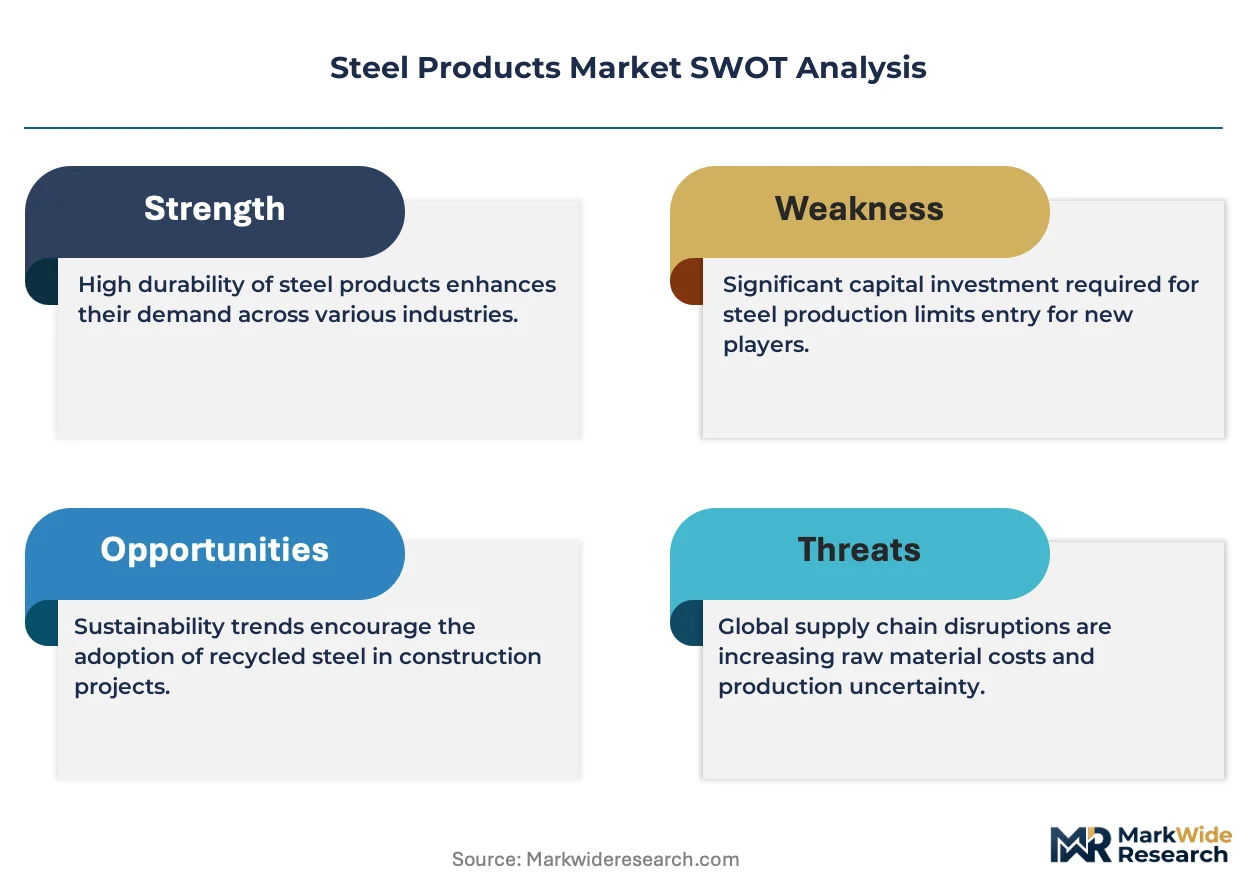
For Market Incumbents: Harden blast furnace competitiveness through hydrogen-reduction pilot deployment and captive pellet feedstock integration. Secure IS 1786 certification for seismic-grade rebar to exploit India's mandatory replacement cycles. Channel control through direct mill-to-project partnerships insulates margin pools from distributor disintermediation. For New Entrants and Emerging Players: Scrap-optimized electric arc furnace capacity in India's western industrial corridor between Mumbai and Pune represents the most penetrable entry point for coated flat steel serving appliance manufacturing clusters. Target tier-two automotive component stampers with flexible volume commitments and rapid qualification timelines. Position through real-time chemical analysis systems that expand lower-grade scrap utilization in prime-grade output. For Investors and Strategic Acquirers: Capital is best deployed toward hydrogen-reduction technology licensors and scrap logistics platform operators with regional density in Southeast Asia. Long-term viability hinges on carbon border adjustment readiness across EU and prospective Asian markets. Monitor MIIT provincial emission cap enforcement velocity as inflection indicator for conventional blast furnace stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Reduced Iron Pilot Deployment | MIIT emission benchmarks in Hebei and Jiangsu provinces channel state investment toward decarbonization pathways. |
| Direct Mill-to-Project Procurement Partnership | Construction consortia in Vietnam and Indonesia bypass distributor tiers for guaranteed slab allocation. |
| Scrap Optimization Technology Investment | Real-time chemical analysis systems expand lower-grade scrap share in prime-grade electric arc furnace output. |
| Seismic-Grade Certification Acquisition | BIS IS 1786 compliance creates specification barriers for uncertified imports across India's earthquake-prone urban corridors. |
| Backward Integration into Pellet Feedstock | Captive mining-to-mill networks secure high-purity inputs for automotive-grade flat steel contracts. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with steel procurement directors at automotive OEMs, blast furnace operations managers, electric arc furnace charge optimization engineers, and construction consortium supply chain leads; and secondary validation through customs trade data, SEC 10-K filings from listed producers, MIIT emission disclosure databases, and BIS certification registries. Bottom-up volume modeling across product type, application, and grade segments triangulated against top-down macroeconomic steel consumption indicators.
Forecast inputs considered capacity utilization rates across integrated and electric arc furnace routes, regulatory emission cap enforcement trajectories, and automotive lightweighting specification adoption curves. Segmentation dimensions modeled encompassed dimensional form, end-use performance requirements, procurement scale sophistication, and alloy content grade tier. CAGRs were derived through regression analysis of historical production data against projected demand drivers across the analysis window.
Macroeconomic conditions sit as an overlay; deviation in construction investment cycles, coking coal price volatility, or carbon border adjustment implementation timing would shift the trajectory. Forecasts reflect documented assumptions regarding technology adoption rates and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
India Construction Ornamental Stone Market
Building Materials
Composite Decking and Railing Market
Building Materials
Australia Architectural Coatings Market
Building Materials
Dry Mix Mortar Market
Building Materials
Block Paving Market
Building Materials
Ireland Cement Market
Building Materials
Construction Materials Market
Building Materials
Ductile Iron Pipe Market
Building Materials
Composite Rebar Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Timber Frames Market
Building Materials
Polymer-Modified Cementitious Mortar Market
Building Materials
Exterior Doors Market
Building Materials
Italy Facade Market
Building Materials
Light Gauge Steel Framing Market
Building Materials
Polymer Concrete Market