
 US Facade Market | 2026-2036
US Facade Market Size, Share, and Industry Trends Forecast 2026-2036
US Facade Market Analytics
Modular unitized curtain wall systems is consolidating buyer preference across large-scale commercial projects by reducing field labor exposure and accelerating enclosure schedules. Oldcastle BuildingEnvelope leverages vertically integrated glass fabrication to control lead times for complex glazing packages. YKK AP America anchors its position through thermal break technology leadership in window and door integration. Kawneer North America specializes in high-rise aluminum framing systems that compete on wind-load performance in hurricane-prone zones.
A facade constitutes the exterior envelope system of a building, comprising curtain walls, cladding, windows, and structural support elements engineered to manage thermal transfer, air infiltration, moisture resistance, and structural loads while meeting specified U-values and pressure ratings. Its primary purpose is to protect interior conditioned space while maximizing daylight penetration and minimizing energy consumption for heating and cooling. Curtain wall systems command the largest installed base among product types due to their dominance in Class A office towers, while rainscreen systems represent the fastest-growing segment as designers prioritize pressure-equalized drainage and cladding longevity. Metal and glass materials together occupy the highest-value share of specification activity, though composite panels are gaining traction where weight reduction and thermal performance converge.
The International Energy Conservation Code and ASHRAE Standard 90.1 establish minimum thermal performance thresholds that directly shape glazing specification and insulation requirements across US jurisdictions. OSHA fall-protection mandates and local amendments to the National Building Code further constrain installation methodologies, favoring prefabricated panelized and unitized approaches that reduce elevated-work exposure. Stakeholders must monitor evolving federal efficiency incentives and municipal electrification ordinances that will determine which envelope technologies qualify for accelerated depreciation and tax credits.
Market Dynamics
The Inflation Reduction Act's efficiency incentives are compressing specification cycles for thermally advanced envelope assemblies across commercial construction, forcing faster technology adoption than traditional building procurement timelines allow.
Growth Catalysts
- ASHRAE 90.1 thermal mandates:Jurisdictions adopting the 2022 standard are triggering wholesale glazing upgrades in existing Class A office stock. Building owners face compliance deadlines that accelerate envelope replacement schedules.
- Unitized curtain wall prefabrication:Field labor shortages in Sun Belt construction markets are driving specification of factory-sealed modules. General contractors report 40% schedule compression on enclosure milestones.
- Electrification ordinances:Municipal mandates in Austin, Denver, and Seattle are disqualifying fossil-fuel-dependent heating systems, increasing thermal performance requirements for envelopes to compensate.
Market Restraints
- Aluminum billet price volatility:Extrusion feedstock costs fluctuate with Midwest premium indices, compressing fabricator margins on fixed-price contracts. Smaller regional suppliers lack hedging capacity.
- Float glass supply concentration:Domestic production clusters along the Ohio River corridor create hurricane and flood exposure. A single plant outage disrupts coated glass availability for six-week windows.
- Curtain wall weight penalties:Structural steel tonnage requirements for stick-built systems limit retrofit feasibility in 1960s-1970s building stock. Owners abandon full-envelope replacement for window-only upgrades.
Strategic Opportunities
- IRA 179D deduction expansion:The accelerated depreciation pathway now covers envelope improvements meeting 25% energy cost reduction thresholds. Tax equity investors are structuring lease-leaseback vehicles for retrofit projects.
- Photovoltaic-integrated glazing:BIPV curtain wall units combining generation with enclosure function are penetrating net-zero commercial mandates. First costs remain elevated but lifecycle accounting shifts procurement criteria.
- Mass timber hybrid structures:Cross-laminated timber commercial buildings require specialized rainscreen attachment systems. European clip manufacturers are establishing US distribution partnerships.
Industry Challenges
- Glazier apprenticeship gaps:Unitized system installation demands certified rigging and sealant application skills. Union training programs in Texas and Florida report 18-month waitlists.
- NFRC certification backlogs:Novel coating stacks and warm-edge spacer configurations face 14-week thermal performance testing queues. Product launches miss specification deadlines.
- Legacy building integration:Pressure-equalized rainscreen retrofits on 1980s masonry structures require structural assessment and moisture remediation. Scope creep erodes project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Facade Market |
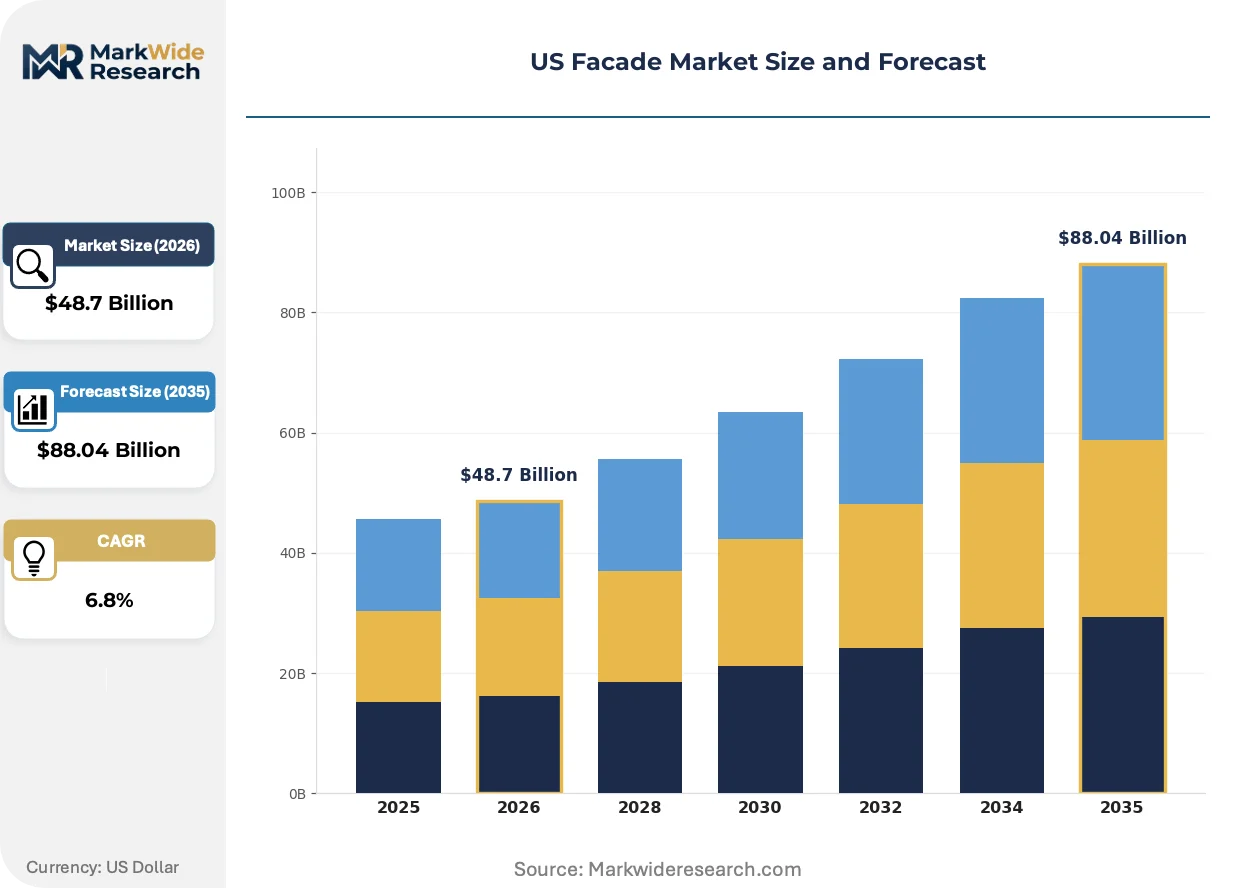
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Curtain Walls, Rainscreen Systems, Cladding Panels, Window Systems Material: Glass, Metal, Wood, Composite Installation Method: Panelized, Unitized, Stick-Built, Precast End User: Commercial Buildings, Residential Projects, Institutional Facilities, Mixed-Use Developments |
| Companies Covered | Oldcastle BuildingEnvelope, YKK AP America, Kawneer North America, Permasteelisa North America, Apogee Enterprises, Enclos Corp., Walters & Wolf, Benson Industries, EFCO Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Facade Market Evolving Landscape
Facade engineering is pivoting from passive thermal barriers to active energy-generating surfaces, with specification criteria expanding to include embodied carbon accounting and grid-interactive capabilities.
Vacuum-insulated glazing is overtaking conventional triple-pane units in high-performance commercial towers. The technology achieves R-12 center-of-glass values in sub-1-inch profiles. Developers in Boston and Chicago are specifying VIP for curtain wall retrofits where floor plate loss from thicker glazing is unacceptable. The structural consequence is that unitized module weights are dropping 30%, enabling faster installation cycles and reduced crane time.
OSHA's updated fall-protection standards for construction above 24 feet are mandating permanent anchor systems on new commercial envelopes. The regulation forces curtain wall designers to integrate stainless steel davit sleeves and horizontal lifeline tracks into million extrusions. High-rise projects in Miami and Houston are seeing specification of pre-engineered anchor-integrated framing from Kawneer and Oldcastle to avoid field modification delays.
Design-build envelope procurement is consolidating authority under single-source contractors who carry performance warranties for air infiltration, thermal bridging, and condensation risk. General contractors are ceding enclosure scope to specialized facade integrators who control glazing, framing, and air barrier continuity. The shift is most visible in Phoenix and Dallas medical office construction, where humidity control and infection-prevention requirements demand guaranteed envelope performance.
US Facade Market Segmentation
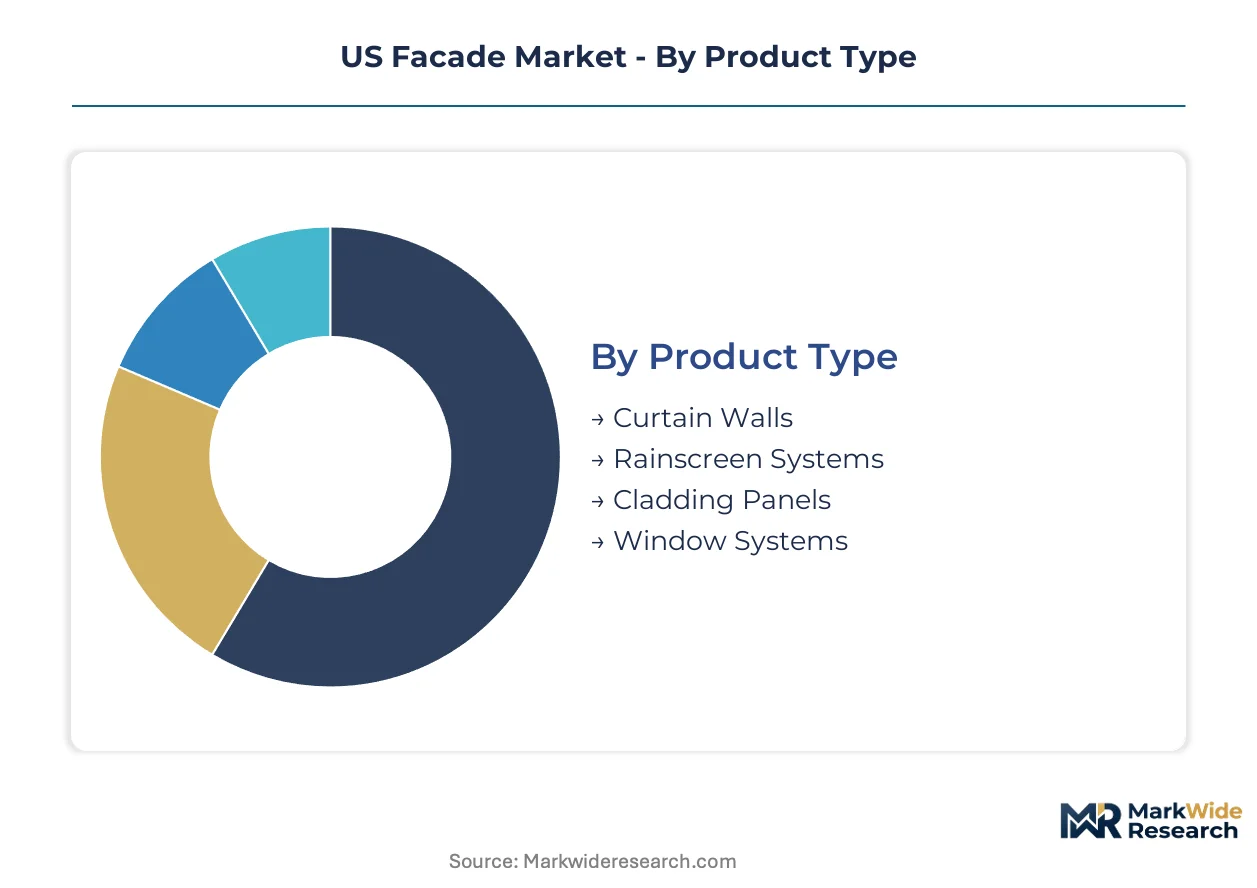
Facade specification in the US construction market fragments across multiple technical and commercial dimensions. Each segmentation axis carries distinct procurement workflows, code compliance burdens, and margin structures that shape vendor positioning.
Product Type:
Capital intensity varies sharply across envelope systems, with factory-sealed unitized modules requiring the heaviest upfront tooling investment.
- Curtain Walls:Non-structural aluminum-framed glazing systems engineered for wind-load resistance and thermal bridging control. Demand concentrates in Dallas and Houston Class A office towers where ASHRAE 90.1 compliance deadlines compress replacement cycles. Stick-built variants dominate retrofits while unitized systems capture new construction.
- Rainscreen Systems:Pressure-equalized cladding assemblies with ventilated cavities that manage moisture drainage and thermal expansion. Expansion is steepest in Seattle and Denver institutional projects where electrification ordinances drive envelope performance upgrades. Attachment engineering varies by substrate—masonry, steel stud, or mass timber.
- Cladding Panels:Rigid facade elements spanning metal composite, fiber cement, and phenolic formulations. Sun Belt distribution centers specify lightweight panels for speed-to-enclosure.
- Window Systems:Operable and fixed fenestration integrated into punched openings or ribbon configurations. Residential and mixed-use developers in Phoenix prioritize thermally broken aluminum frames.
Most installed capacity flows through Curtain Walls. Expansion is steepest in Rainscreen Systems.
Material:
Raw material procurement patterns segment the supply base into glass-dependent fabricators, metal extruders, and emerging bio-based specialists.
- Glass:Float, heat-treated, and coated glazing products governed by NFRC certification protocols. Boston and Chicago high-performance retrofits specify vacuum-insulated profiles where floor plate preservation overrides first-cost concerns. Ohio River corridor production concentration creates hurricane exposure risk.
- Metal:Aluminum extrusions, steel panels, and zinc alloys dominating commercial specification. Midwest premium indices on aluminum billet compress fabricator margins during volatile commodity cycles.
- Wood:Mass timber-compatible rainscreen attachments and preservative-treated cladding. Cross-laminated timber commercial buildings in Pacific Northwest markets drive specialized fastener demand.
- Composite:Fiber-reinforced polymer and aluminum composite panels where weight reduction intersects with thermal performance. Airport and healthcare projects specify fire-rated formulations.
Glass commands the highest-value specification activity. Composite materials are climbing fastest on embodied carbon accounting criteria.
Installation Method:
Field labor exposure and schedule risk distribute unevenly across fabrication approaches, with implications for insurance, bonding, and general contractor risk allocation.
- Unitized:Factory-assembled modules craned into place with minimal field sealing. Sun Belt general contractors report 40% schedule compression on enclosure milestones. OSHA fall-protection mandates accelerate adoption for work above 24 feet.
- Panelized:Large-format wall sections incorporating insulation, air barriers, and cladding in controlled conditions. Medical office construction in Phoenix and Dallas favors guaranteed performance warranties.
- Stick-Built:Component-by-component field assembly requiring elevated rigging and sealant application. Union glazier apprenticeship waitlists in Texas and Florida constrain capacity.
- Precast:Concrete-based envelope elements with integral insulation and finishes. Parking structures and institutional projects specify for durability and speed.
Unitized systems capture the majority of new Class A commercial volume. Panelized methods are expanding most quickly in healthcare and life science construction.
End User:
Procurement authority and performance warranty requirements diverge across building typologies, from institutional owner-operators to speculative commercial developers.
- Commercial Buildings:Class A office, retail, and hospitality assets where IRA 179D deductions accelerate envelope improvement decisions. Tax equity investors structure lease-leaseback vehicles for retrofit compliance with energy cost reduction thresholds.
- Residential Projects:Multifamily and single-family developments governed by IECC residential chapters. Window-to-wall ratio optimization drives glazing specification.
- Institutional Facilities:Healthcare, education, and government buildings with extended ownership horizons and infection-prevention requirements. Humidity control mandates in Dallas medical offices demand guaranteed envelope performance.
- Mixed-Use Developments:Vertical combinations of residential, commercial, and hospitality programming. Complex zoning transitions require specialized thermal bridging solutions at floor plates.
Commercial Buildings account for the dominant share of curtain wall and rainscreen demand. Institutional Facilities are expanding fastest on IRA efficiency incentive capture and electrification ordinance compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US facade industry traces its commercial-scale origins to postwar aluminum extrusion capacity expansion in the Midwest and Ohio River corridor, where float glass production and metal fabrication first converged to supply the modern curtain wall systems that transformed American skylines from the 1950s onward.
Southwest
Phoenix and Dallas-Fort Worth metro areas drive unitized curtain wall demand as Class A office construction outpaces national averages. ASHRAE 90.1 thermal compliance deadlines compress specification cycles for high-performance glazing. General contractors report 40% schedule compression on enclosure milestones through factory-sealed module adoption.
Southeast
Miami and Houston high-rise development prioritizes wind-load performance in hurricane-prone zones. OSHA fall-protection mandates above 24 feet accelerate specification of pre-engineered anchor-integrated framing systems. Florida and Texas union glazier apprenticeship programs face 18-month waitlists constraining field labor capacity.
Pacific Northwest
Seattle electrification ordinances disqualify fossil-fuel-dependent heating systems, elevating thermal performance requirements for envelope assemblies. Mass timber commercial construction drives specialized rainscreen attachment demand. European clip manufacturers are establishing US distribution partnerships to serve cross-laminated timber projects.
Northeast
Boston and Chicago high-performance retrofits specify vacuum-insulated glazing where floor plate preservation overrides first-cost concerns. IRA 179D deduction expansion structures tax equity investment in envelope improvements meeting 25% energy cost reduction thresholds. NFRC certification backlogs for novel coating stacks delay product launches.
Mountain West
Denver municipal electrification mandates increase envelope thermal performance requirements to compensate for displaced fossil-fuel heating. Healthcare and life science construction favors design-build envelope procurement with guaranteed performance warranties. Humidity control requirements drive specialized facade integrator authority.
US Facade Market Competitive Landscape
The competitive structure tilts toward vertically integrated glass fabricators with captive aluminum extrusion supply. Market concentration is moderate, with national-scale envelope specialists commanding premium specification in Class A commercial towers while regional fabricators compete on retrofit project economics. Three archetypes dominate: integrated glass-metal systems houses, specialized high-rise framing engineers, and design-build facade integrators carrying performance warranties. Competitive moves center on backward integration into aluminum billet supply and strategic partnerships with European rainscreen attachment technology licensors.
Among US-based envelope specialists, Oldcastle BuildingEnvelope, Kawneer North America, and YKK AP America occupy positions across the integrated systems spectrum. Oldcastle exemplifies the vertically integrated archetype through captive glass fabrication capacity. Kawneer represents high-rise aluminum framing specialization with wind-load engineering focus. YKK AP America anchors thermal break technology positioning in window and door integration. These three fabricators illustrate how control over critical material inputs and specialized engineering capabilities determine specification access in thermally advanced commercial construction.
| Leading Market Players |
|---|
| Oldcastle BuildingEnvelope |
| YKK AP America |
| Kawneer North America |
| Permasteelisa North America |
| Apogee Enterprises |
| Enclos Corp. |
| Walters & Wolf |
| Benson Industries |
| EFCO Corporation |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up glass fabricators now control the mid-market envelope supply base, concentrating pricing power among vertically integrated specialists while compressing margins for regional extruders lacking captive billet supply. This ownership consolidation directly shapes procurement behavior, as general contractors face take-it-or-leave-it terms on coated glass packages during volatile Midwest premium cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the specification market, with ASHRAE 90.1 thermal performance tiers and NFRC certification grades driving differentiation. Premium vacuum-insulated glazing commands substantial spreads over conventional triple-pane units in Boston and Chicago retrofits where floor plate preservation outweighs first-cost sensitivity. Cost compression in standard-tier unitized modules is intensifying because aluminum billet volatility erodes fabricator margins on fixed-price contracts. Speculative commercial developers in Dallas and Phoenix exhibit the highest price sensitivity, while institutional healthcare owners in Denver prioritize guaranteed performance warranties over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from general contractors now mandate qualified secondary suppliers for both float glass and aluminum extrusion feedstock, forcing fabricators to maintain redundant production relationships. Supply concentrates along the Ohio River corridor for coated glass and across the Midwest for aluminum billet, creating hurricane and flood exposure that disrupts six-week availability windows. Raw material dependencies center on soda ash, natural gas for float furnace operations, and Midwest premium aluminum ingot. Tariff exposure on Canadian primary aluminum creates margin volatility for non-hedged regional suppliers. Distribution runs through design-build facade integrators who consolidate glazing, framing, and air barrier scope under single-source performance warranties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Facade Market represents a late-cycle quality story as electrification ordinances and IRA efficiency incentives displace commodity specification toward thermally advanced envelope assemblies. Demand is concentrating among owners willing to pay performance premiums for guaranteed U-value and air infiltration outcomes.
For Market Incumbents: Cement specification authority through captive aluminum extrusion supply and in-house low-E coating capacity, insulating against Midwest premium volatility while locking out regional competitors on ASHRAE 90.1 compliance deadlines. Prioritize certification investment in NFRC warm-edge spacer configurations to bypass 14-week testing backlogs that delay product launches. Defend against European rainscreen attachment specialists by establishing exclusive distribution partnerships with cross-laminated timber fabricators in Seattle and Denver. For New Entrants and Emerging Players: Photovoltaic-integrated glazing technology offers a technology-first wedge into net-zero commercial mandates where lifecycle accounting shifts procurement criteria away from first-cost metrics. Target mass timber hybrid structures in Pacific Northwest markets, where European clip manufacturers lack established US distribution and specialized attachment engineering creates specification barriers. Pursue design-build envelope procurement relationships with Phoenix and Dallas medical office developers who cede enclosure scope to performance-warranty integrators. For Investors and Strategic Acquirers: Valuations sit cheapest among regional aluminum extruders lacking backward integration into billet supply, presenting consolidation targets for private equity roll-up strategies. Long-term viability hinges on exposure to IRA 179D deduction capture and municipal electrification ordinance compliance, with institutional healthcare and Class A office retrofits offering the most durable demand visibility. Monitor glazier apprenticeship program waitlists in Texas and Florida as an inflection indicator for field labor capacity constraints that accelerate unitized system adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Billet Supply | Captive extrusion feedstock insulates margin compression during Midwest premium volatility cycles. |
| NFRC Certification Fast-Track Investment | Warm-edge spacer pre-qualification bypasses 14-week thermal testing queues that delay specification. |
| European Rainscreen Attachment Licensing | Exclusive distribution partnerships capture mass timber commercial construction in Seattle and Denver. |
| Design-Build Facade Integrator Acquisition | Single-source performance warranties consolidate enclosure authority from general contractors. |
| Photovoltaic-Integrated Glazing Development | BIPV curtain wall units penetrate net-zero mandates where lifecycle accounting displaces first-cost procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with envelope fabricator executives, general contractor procurement leads, commercial glazing subcontractor operations managers, and municipal building code officials with secondary validation. Primary sources included SEC 10-K filings from publicly traded envelope specialists, US Census construction spending data, and NFRC certified product directory analysis. Bottom-up project pipeline tracking across Dallas, Houston, Phoenix, Seattle, and Denver metro areas was triangulated against top-down construction forecast models.
Comparable-period anchoring linked the projection horizon to historical reference periods spanning pre-IRA baseline conditions through current electrification ordinance implementation phases. The analytical framework modeled segmentation across product type (curtain wall, rainscreen, cladding, window systems), material composition (glass, metal, composite, wood), installation methodology (unitized, panelized, stick-built, precast), and end-user category (commercial, institutional, residential, mixed-use). CAGRs were derived from installation volume trajectories correlated with ASHRAE 90.1 adoption timelines and IRA incentive uptake curves.
The model holds under sustained federal efficiency incentive authorization and municipal electrification ordinance expansion; deviation in aluminum billet price volatility or glazier apprenticeship capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Door Frame Metal Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
North America Cement Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
GCC Concealed Cistern Market
Building Materials
Fiber Reinforced Concrete Market
Building Materials
North America Architectural Coatings Market
Building Materials
Foam Concrete Market
Building Materials
East Africa Cement Market
Building Materials
Cladding Market
Building Materials
Bolt (Fastener) Market
Building Materials
Italy Architectural Coatings Market
Building Materials
East Africa White Cement Market
Building Materials
Dry Mix Mortar Market
Building Materials
Sanded Grout Market
Building Materials
Sprayed Concrete Market