
 India Dry Mix Mortar Market | 2026-2036
India Dry Mix Mortar Market Size, Share, and Industry Trends Forecast 2026-2036
India Dry Mix Mortar Market Insights
Small contractors and mid-size builders is bifurcating demand away from large project developers across India's construction chemicals landscape. UltraTech Cement Ltd leverages its captive cement capacity to control raw material costs across plaster and grout lines. Pidilite Industries Ltd anchors the adhesives segment through decades of brand equity with applicator networks. Sika AG competes on polymer-modified formulations for high-performance commercial specifications.
Dry mix mortar comprises pre-blended binders, aggregates, and functional additives manufactured under controlled conditions to eliminate on-site proportioning errors, with typical formulations specifying particle size distribution below 2.36 mm and binder content ranging from 15% to 40% by weight depending on end-use performance requirements. Cement-based formulations dominate volume flows across residential plastering applications, while polymer-modified adhesives claim the fastest expansion trajectory tied to tile and natural stone installation standards. The contractor channel occupies the deepest volume pools, though architect-specified projects yield superior margin capture for specialized render systems.
BIS mandates under IS 15477 govern dry mix mortar composition and performance testing, compelling domestic manufacturers to upgrade quality assurance infrastructure or surrender specification-grade opportunities. The CEA's building energy codes and state-level RERA enforcement together elevate demand for standardized, documented construction materials over informal site-mixed alternatives. Stakeholders must track how BIS expands its compulsory certification list and whether state public works departments adopt centralized pre-qualification for approved mortar suppliers.
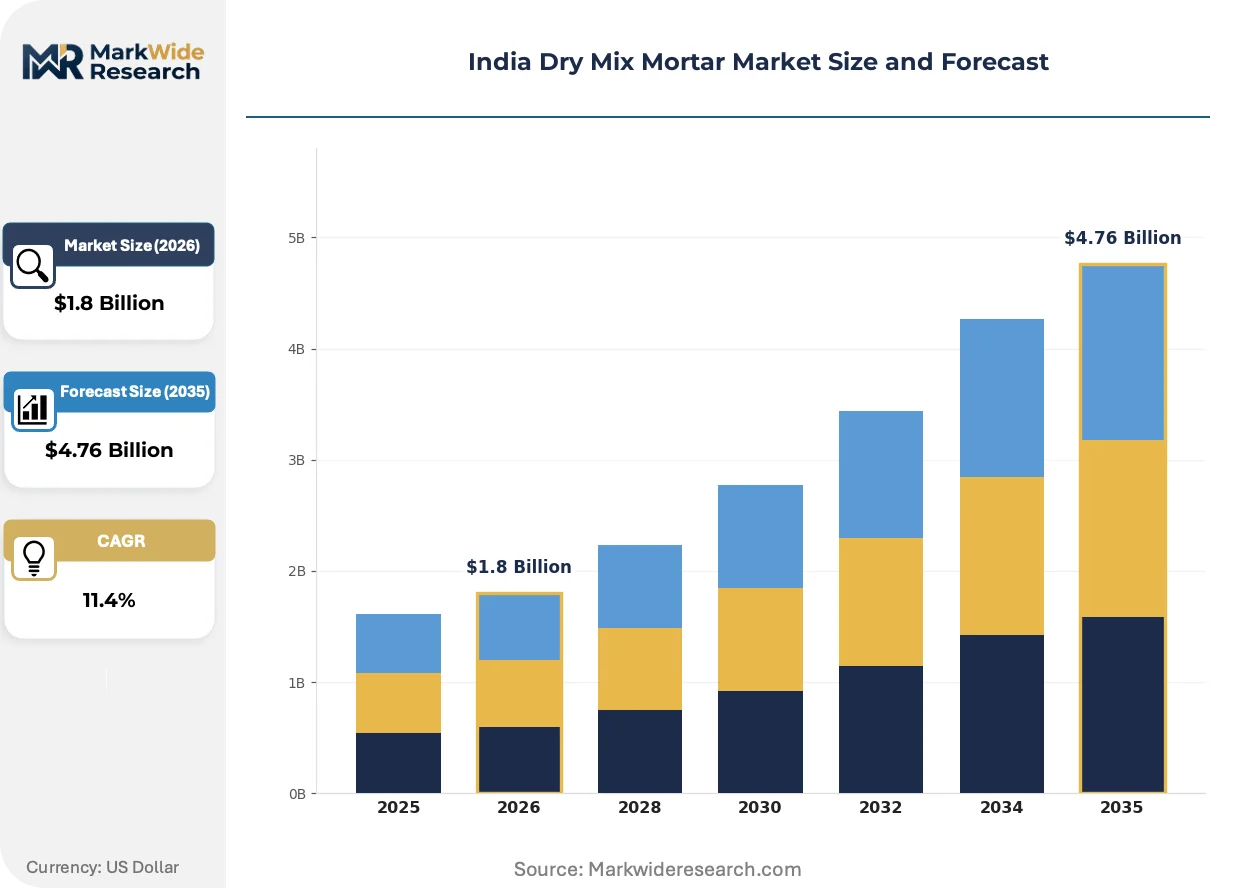
Market Dynamics
BIS certification mandates under IS 15477 are compressing informal supply chains while concentrating procurement authority among pre-qualified manufacturers with laboratory infrastructure.
Growth Catalysts
- Affordable Housing for All:Central government allocation targets are pulling small contractors into formal procurement channels for standardized plaster and tile adhesive systems.
- CEA Building Energy Codes:Thermal performance specifications for wall assemblies are elevating documented mortar systems over site-mixed alternatives in commercial construction.
- Maharashtra-Gujarat Infrastructure Corridor:Metro rail and industrial park construction is concentrating demand for high-strength grouting formulations in western India.
Market Restraints
- White Cement Supply Concentration:Domestic production capacity constraints in decorative render formulations force dependence on volatile import flows from Vietnam and Thailand.
- Redispersible Polymer Powder Import Dependence:Formulation-grade VAE and EVA polymers originate from a narrow supplier base in Germany and South Korea, exposing margins to freight and currency volatility.
- IS 15477 Testing Infrastructure Gap:BIS-mandated performance verification requires capital-intensive rheology and durability labs that exclude smaller regional blenders from specification-grade tenders.
Strategic Opportunities
- Tier-2 City Penetration:Lucknow, Indore, and Coimbatore municipal corporations are adopting centralized material pre-qualification for smart city infrastructure, opening specification access beyond Mumbai-Delhi corridors.
- Polymer-Modified Adhesive Expansion:Large-format porcelain tile installation standards are driving specification migration from conventional cement paste to flexible, deformable adhesive systems.
- RERA Compliance Documentation:State-level real estate regulator enforcement is mandating batch-traceable construction materials, favoring packaged dry mix over undocumented site blending.
Industry Challenges
- Applicator Skill Standardization:Tile fixing and render application trades lack formal certification pathways, creating quality variance between trained contractor networks and informal labor pools.
- Batch-to-Batch Consistency:Regional sand sourcing variability complicates automated blending controls, requiring real-time particle size adjustment that strains quality assurance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Dry Mix Mortar Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Plasters, Grouts, Renders Application: Residential, Commercial, Industrial, Infrastructure End User: Contractors, Builders, Architects, Engineers Formulation: Polymer-Based, Cement-Based, Gypsum-Based, Others |
| Companies Covered | UltraTech Cement Ltd, Pidilite Industries Ltd, Asian Paints, Sika AG, Adani Group, The Ramco Cements Ltd, Saint-Gobain, MAPEI S.p.A, MBCC Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Dry Mix Mortar Market Trends and Innovations
Formulation chemistry and procurement digitization are compressing traditional supply hierarchies while elevating performance-verified systems over commodity alternatives.
Self-leveling underlayment compounds with extended open times are displacing semi-dry screed applications in commercial flooring specifications. Large-format retail and hospitality developers in Bengaluru and Hyderabad are specifying these systems for accelerated construction schedules. The shift is compressing demand for conventional sand-cement screeds in premium commercial segments while expanding polymer-modified product volumes.
BIS has expanded compulsory certification to include tile adhesives and grouts under revised IS 15477 schedules, compelling domestic manufacturers to upgrade testing infrastructure or exit specification channels. State public works departments in Gujarat and Tamil Nadu are now requiring BIS license numbers in tender documentation. This regulatory compression is accelerating consolidation among blenders with captive laboratory capacity.
Builder procurement teams are consolidating vendor lists around integrated mortar-admixture suppliers capable of single-source accountability for performance outcomes. Mid-size residential developers in Pune and Ahmedabad are shifting from fragmented material sourcing to annual framework agreements with certified manufacturers. This concentration pattern is most visible in RERA-registered projects where documentation requirements favor supplier integration over price-driven fragmentation.
India Dry Mix Mortar Market Segmentation
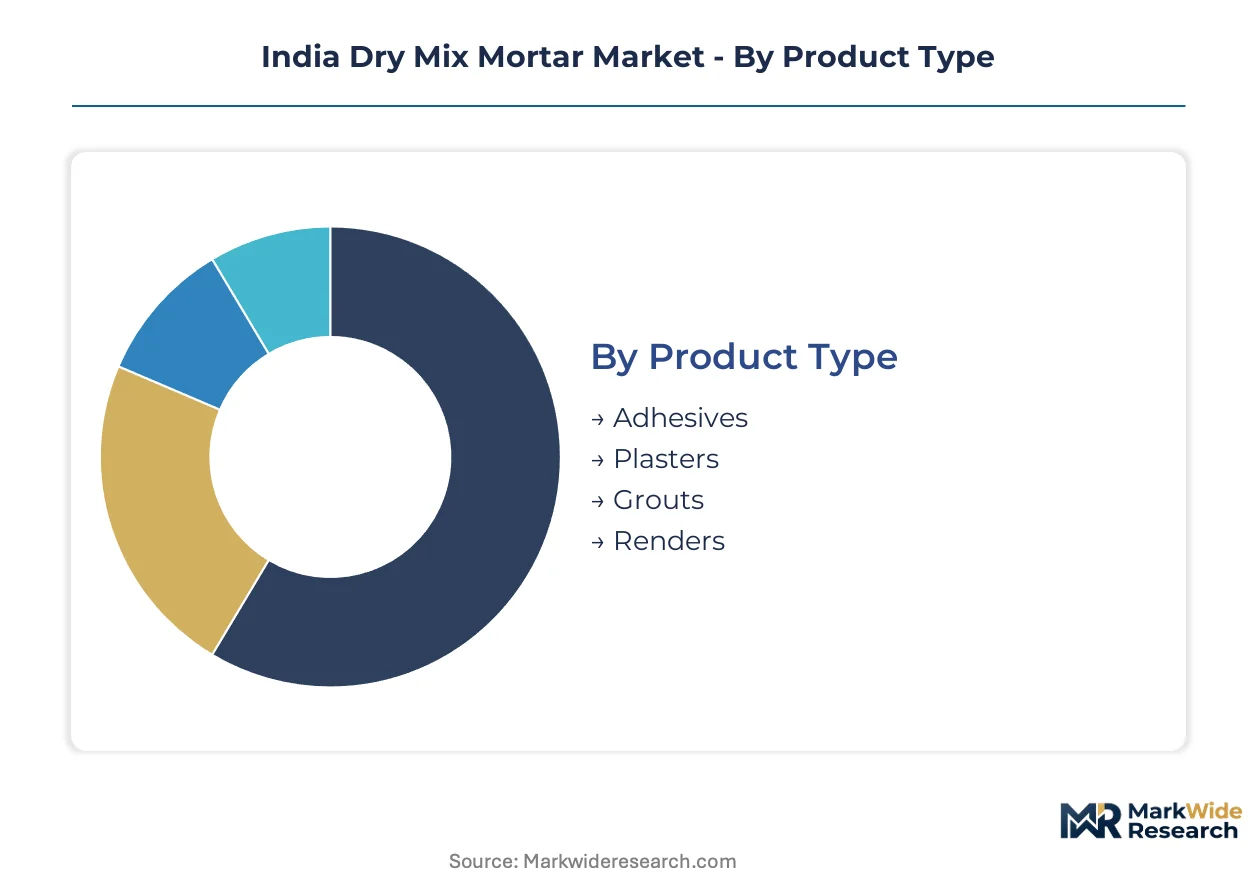
Dry mix mortar segmentation in India reflects divergent technical requirements across regulatory regimes. BIS certification under IS 15477 splits the market between specification-grade products with laboratory traceability and commodity alternatives serving informal construction channels.
Product Type:
BIS mandates under IS 15477 differentiate product categories by performance testing protocols and compulsory certification schedules.
- Adhesives:Polymer-modified formulations incorporating redispersible polymer powders enable deformability for large-format tile and natural stone installations. Demand concentrates in Maharashtra and Gujarat metro corridors where commercial flooring specifications are migrating from conventional cement paste to flexible systems.
- Plasters:Cement-based formulations with controlled particle size distribution below 2.36 mm dominate residential volume flows. Affordable housing programs in tier-2 cities are pulling small contractors toward packaged plaster systems over site-mixed alternatives.
- Grouts:High-strength formulations serve industrial and infrastructure anchoring applications with specified compressive strength requirements.
- Renders:Decorative finish systems dependent on white cement supply chains face import volatility from Vietnam and Thailand.
Established volume favors plasters; emerging adoption favors adhesives.
Application:
End-use differentiation tracks construction cycle intensity and documentation requirements under state-level RERA enforcement.
- Residential:Affordable housing allocations are formalizing procurement channels for standardized plaster and tile adhesive systems across municipal smart city projects.
- Commercial:Self-leveling underlayment compounds with extended open times are displacing semi-dry screed applications in Bengaluru and Hyderabad retail developments.
- Industrial:High-performance grouting specifications concentrate in western India industrial park construction.
- Infrastructure:Metro rail projects in Maharashtra and Gujarat are driving specification-grade adhesive and grout volumes.
Residential channels anchor current volume; commercial applications are climbing the fastest.
End User:
Customer segmentation reflects procurement authority concentration and technical specification influence.
- Contractors:The deepest volume pools flow through contractor networks, though quality variance persists between trained applicators and informal labor pools.
- Builders:Mid-size residential developers in Pune and Ahmedabad are consolidating vendor lists around integrated suppliers capable of single-source accountability.
- Architects:Specification influence yields superior margin capture for specialized render systems in premium commercial segments.
- Engineers:Technical validation requirements favor batch-traceable materials with documented performance testing.
Contractor channels dominate volume throughput; architect-specified projects command premium positioning.
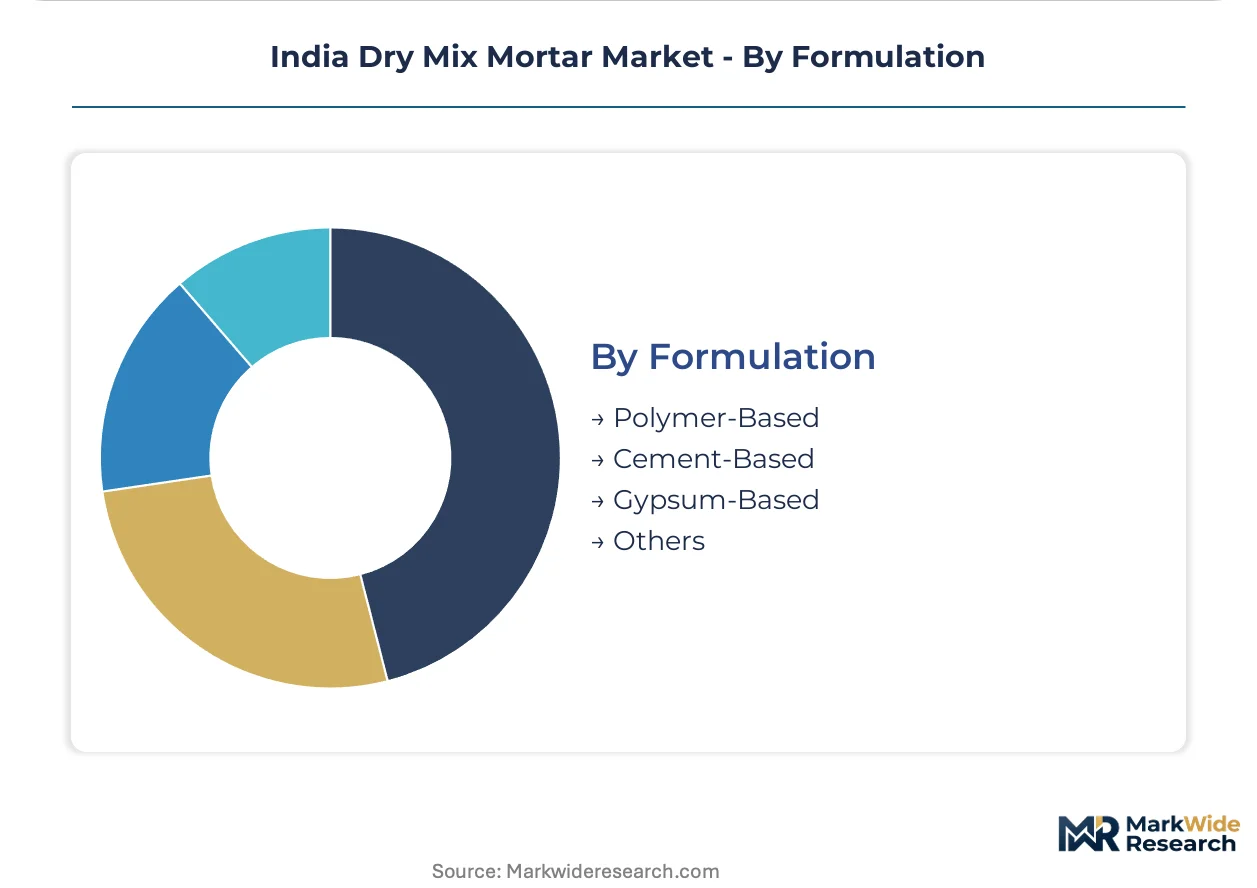
Formulation:
Raw material sourcing geography and supply concentration define formulation economics and margin exposure.
- Polymer-Based:VAE and EVA redispersible polymer powders originate from German and South Korean supplier bases, exposing formulations to freight and currency volatility.
- Cement-Based:Captive cement capacity at integrated manufacturers enables cost control across plaster and grout lines.
- Gypsum-Based:Lightweight interior applications serve specific commercial drywall specifications with regional supply constraints.
- Others:Specialized formulations including epoxy and silicate-based systems address niche high-performance requirements.
Cement-based systems retain volume leadership; polymer-based formulations are gaining share fastest in specification-grade channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in western and southern India where infrastructure corridors and industrial park construction are accelerating formal procurement channels. Maharashtra and Gujarat together absorb the dominant share of specification-grade adhesive and grout volumes. State-level pre-qualification requirements are compressing informal supply chains in tier-2 municipal markets.
Maharashtra
Mumbai Metro rail expansion and Pune-Ahmedabad industrial corridor projects are driving high-strength grouting specifications. BIS license requirements in state public works tenders exclude non-certified regional blenders. Thane and Pune municipal corporations now mandate batch-traceable dry mix materials for smart city infrastructure.
Gujarat
Dholera Special Investment Region and GIFT City construction are pulling polymer-modified adhesive volumes for large-format commercial flooring. CEA building energy codes elevate documented thermal performance systems over site-mixed alternatives. Ahmedabad and Surat builder markets are consolidating vendor lists around integrated suppliers with captive laboratory infrastructure.
Karnataka
Bengaluru retail and hospitality developers are specifying self-leveling underlayment compounds for accelerated construction schedules. State RERA enforcement mandates documented construction materials with batch traceability. Whitefield and Electronic City commercial clusters are displacing conventional sand-cement screeds in premium segments.
Tamil Nadu
Chennai metro expansion and Coimbatore smart city infrastructure are concentrating demand for specification-grade plaster and tile adhesive systems. State public works departments require BIS license numbers in tender documentation. Sriperumbudur industrial belt construction is formalizing procurement channels for standardized mortar systems.
Telangana
Hyderabad pharmaceutical and IT campus construction is elevating architect-specified render systems with documented performance testing. Municipal corporations in tier-2 cities are adopting centralized material pre-qualification beyond traditional Mumbai-Delhi corridors. Gachibowli and HITEC City commercial developments favor integrated mortar-admixture suppliers for single-source accountability.
India Dry Mix Mortar Market Competitive Landscape
Concentration sits with integrated cement manufacturers and specialized construction chemical multinationals that control laboratory infrastructure for BIS compliance. The market structure splits between captive-cement players with raw material cost advantages and polymer-formulation specialists competing on high-performance specifications. Three archetypes dominate: integrated cement majors, adhesive-focused chemical specialists, and regional blenders serving commodity channels. Competitive moves center on backward integration into white cement sourcing and strategic partnerships with applicator training networks.
Among integrated cement-based manufacturers, UltraTech Cement Ltd and The Ramco Cements Ltd exemplify the captive-raw-material archetype with cost control across plaster and grout lines. Pidilite Industries Ltd occupies a distinct position anchoring brand equity with contractor applicator networks in the adhesives segment. Sika AG represents the multinational polymer-formulation specialist competing on specification-grade commercial projects. These three players illustrate the competitive tension between volume-driven cement integration and margin-focused chemical specialization.
| Leading Market Players |
|---|
| UltraTech Cement Ltd |
| Pidilite Industries Ltd |
| Asian Paints |
| Sika AG |
| Adani Group |
| The Ramco Cements Ltd |
| Saint-Gobain |
| MAPEI S.p.A |
| MBCC Group |
| Others |
Pricing and Supply Chain Analysis
BIS certification under IS 15477 gates both supply qualification and price differentiation simultaneously, compressing informal blenders from specification-grade tenders while enabling certified manufacturers to command premiums for laboratory-traceable performance. The regulatory anchor splits procurement into documented systems versus commodity alternatives, with price stratification tracking certification investment rather than raw material cost alone.
Pricing Analysis
IS 15477 dictates the pricing tier structure across India's dry mix mortar landscape, separating BIS-licensed manufacturers from regional commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, captive laboratory infrastructure, and volume scale. Cost compression in the economy tier is intensifying because small contractors face working capital constraints for packaged systems. Small contractors exhibit highest price sensitivity, while architect-specified commercial projects show least.
Supply Chain Analysis
Germany and South Korea anchor redispersible polymer powder production for India's polymer-modified formulations, with VAE and EVA grades feeding specification-grade adhesive lines. Domestic cement sourcing draws from captive capacity at integrated manufacturers, while white cement for decorative renders hinges on import flows from Vietnam and Thailand. Single-source vulnerability concentrates in polymer additives, where freight and currency volatility transmit directly to formulation margins. Distribution runs through contractor networks and builder procurement teams with increasing consolidation around integrated suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laboratory infrastructure scarcity constrains specification-grade participation, with BIS-mandated rheology and durability testing capacity concentrated among integrated cement majors and multinational chemical specialists. This capability gap defines competitive moats and acquisition premiums.
For Market Incumbents: Secure captive white cement sourcing through backward integration into import partnerships or domestic production investments, insulating decorative render margins from Southeast Asian supply volatility. Expand BIS laboratory capacity into tier-2 municipal markets ahead of state public works pre-qualification expansion, preempting regional blender consolidation.
For New Entrants and Emerging Players: Applicator training networks represent an under-served service layer where incumbents rely on informal labor pools with quality variance. Target tier-2 smart city corridors in Lucknow, Indore, and Coimbatore where centralized material pre-qualification is newly adopted. Lead with certified training partnerships and batch-traceability documentation as the go-to-market anchor.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across polymer-modified adhesive segments as BIS expands compulsory certification schedules. Long-term viability favors blenders with captive laboratory infrastructure and integrated cement supply. Acquisition target archetype: regional certified manufacturers with municipal pre-qualification access but sub-scale polymer formulation capability. Watch BIS expansion of compulsory certification to additional product categories as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into White Cement | Reduces import dependence from Vietnam and Thailand for decorative render formulations. |
| BIS Laboratory Capacity Expansion | Captures specification-grade opportunities as state public works tighten pre-qualification. |
| Applicator Training Network Development | Addresses quality variance between trained contractors and informal labor pools. |
| Polymer Formulation Partnership | Secures VAE and EVA supply from German and South Korean supplier bases. |
| Tier-2 Municipal Pre-Qualification Entry | Opens specification access beyond Maharashtra-Gujarat corridors in smart city projects. |
Research Methodology
The analysis maps adhesives, plasters, grouts, and renders, each validated through plant managers at blending facilities, procurement leads at mid-size residential developers, distribution channel partners, and technical R&D directors at construction chemical specialists. Primary interviews combined with secondary validation from BIS certification registers, CEA building energy code notifications, state public works tender documentation, and customs import data for white cement and polymer powders. Bottom-up volume modeling triangulated against top-down construction spending allocation across residential, commercial, and infrastructure segments.
Consistency checks validated volume and value outputs against external benchmarks including cement consumption patterns, construction chemical trade flows, and state-level RERA project registrations. Segmentation dimensions modeled include product type, application, end user, and formulation chemistry across the projection horizon. CAGRs derived from regression analysis of historical penetration rates and forward projection of regulatory enforcement intensity, affordable housing allocation trajectories, and infrastructure corridor development timelines.
Underlying assumptions cover BIS certification expansion schedules, affordable housing program continuity, and polymer import cost stability, with deviation risk concentrated in white cement supply disruptions and state-level pre-qualification adoption timing. Recalibration cycles align with material shifts in regulatory enforcement intensity and infrastructure project award momentum.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Construction Repair Composites Market
Building Materials
Blind Bolts Market
Building Materials
Europe Aluminum Door and Window Market
Building Materials
Spain Cement Market
Building Materials
Steel Products Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Cribbing Blocks Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
North America Cement Market
Building Materials
Fiber Reinforced Concrete Market
Building Materials
Italy Facade Market
Building Materials
France Architectural Coatings Market
Building Materials
Global White Cement Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
North America Dry-Mix Mortar Market