
 Singapore Architectural Coatings Market | 2026-2036
Singapore Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Architectural Coatings Market Analytics
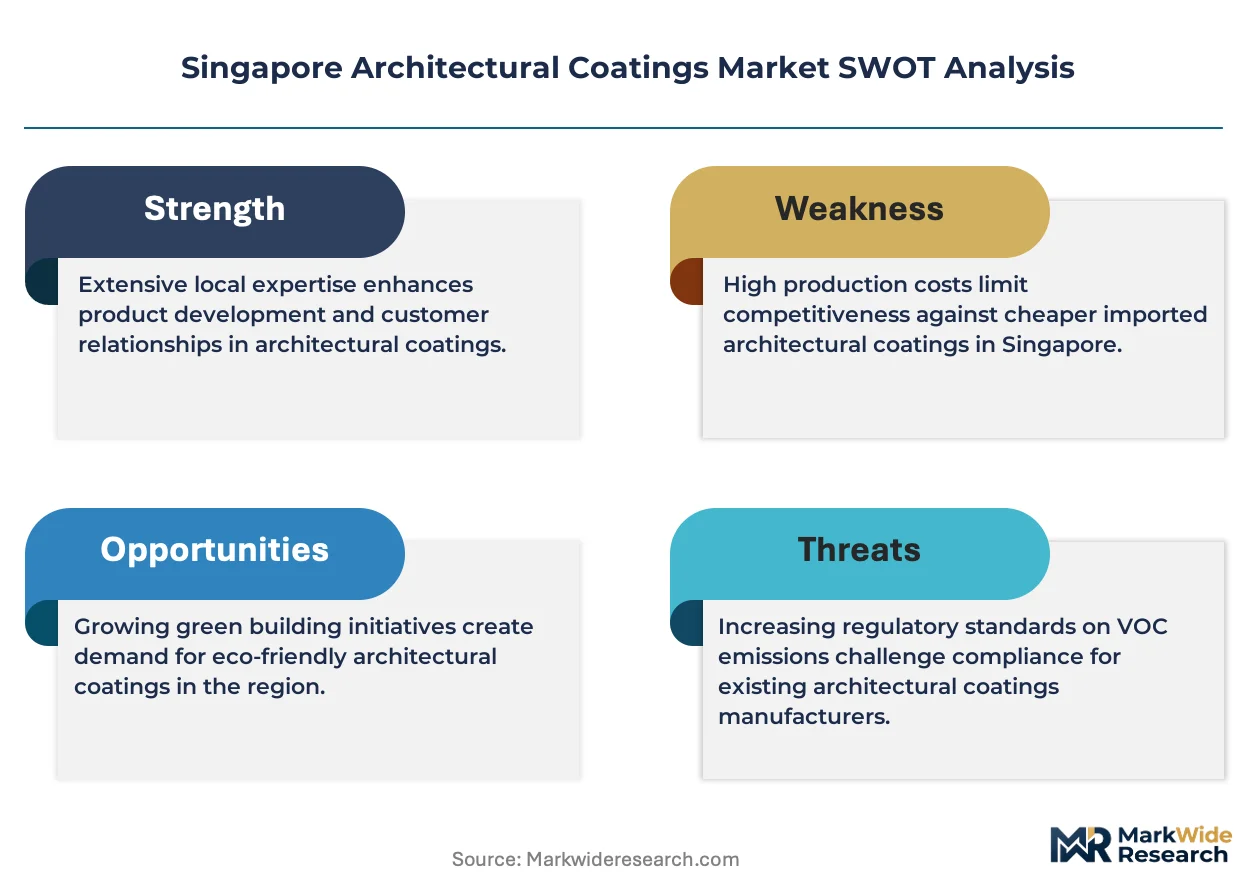
The capital-intensity divergence between multinational and local players is reorganizing competitive dynamics in Singapore's architectural coatings sector. AkzoNobel N.V. leverages its global R&D infrastructure to dominate premium water-based formulations. Raffles Paint Pte Ltd anchors its position through deep channel control across local contractor networks. Jotun differentiates via specialized marine-grade technology crossover into high-performance exterior applications.
Singapore architectural coatings encompass liquid and powder formulations applied to building substrates for protection, decoration, and functional enhancement, with water-based emulsions typically containing 30-60% solids by volume and VOC levels below 50 g/L for green-certified projects. Emulsions lead volume due to their dominance in interior wall applications across residential buildings. Water-based coatings represent the fastest-expanding category as Singapore's Green Mark certification tightens environmental compliance. Specialty coatings command the strongest margin pools, particularly anti-fungal formulations addressing the city-state's tropical humidity challenges in commercial spaces.
Singapore's Building and Construction Authority enforces Green Mark standards that mandate low-VOC and low-formaldehyde coatings for new developments, while the National Environment Agency regulates hazardous substance thresholds in imported formulations. These frameworks compel manufacturers to reformulate product lines and secure third-party eco-labeling for market access. Stakeholders must monitor evolving BCA sustainability tiers and NEA chemical restriction schedules to anticipate compliance-driven procurement shifts.
Market Dynamics
Green Mark certification tiers from Singapore's Building and Construction Authority are compressing formulation cycles and forcing raw material substitutions across the architectural coatings supply base.
Growth Catalysts
- BCA Green Mark 2021:Mandatory low-VOC thresholds for new commercial developments are accelerating water-based coating procurement in the central business district.
- Marina Bay and Greater Southern Waterfront:Large-scale mixed-use redevelopment is concentrating high-performance exterior coating demand in signature districts.
- Self-cleaning nanocoatings:Titanium dioxide photocatalytic formulations are gaining specification traction for high-rise facades facing persistent tropical soiling.
Market Restraints
- Titanium dioxide feedstock:Concentrated global supply from sulfate-process Chinese producers creates margin volatility for local formulators.
- Specialty resin imports:Dependence on Malaysian and Thai petrochemical corridors exposes coating manufacturers to cross-border logistics friction.
- Humidity-cure limitations:Ambient moisture interference constrains polyurethane exterior application windows during monsoon periods.
Strategic Opportunities
- Tampines and Jurong Lake District:Decentralized commercial hub development outside the CBD is dispersing specification authority to regional project clusters.
- Direct-to-contractor digital platforms:B2B procurement portals are disintermediating traditional distributor layers for mid-scale renovation projects.
- NEA carbon pricing alignment:Upcoming Scope 3 disclosure requirements for building materials create first-mover advantage for verified low-carbon coating portfolios.
Industry Challenges
- Green Mark assessor certification:Limited BCA-accredited professionals are extending project approval timelines for sustainable coating specifications.
- Legacy solvent-based inventory:Contractor stockpiles of pre-2020 high-VOC products complicate compliance enforcement on renovation sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Architectural Coatings Market |
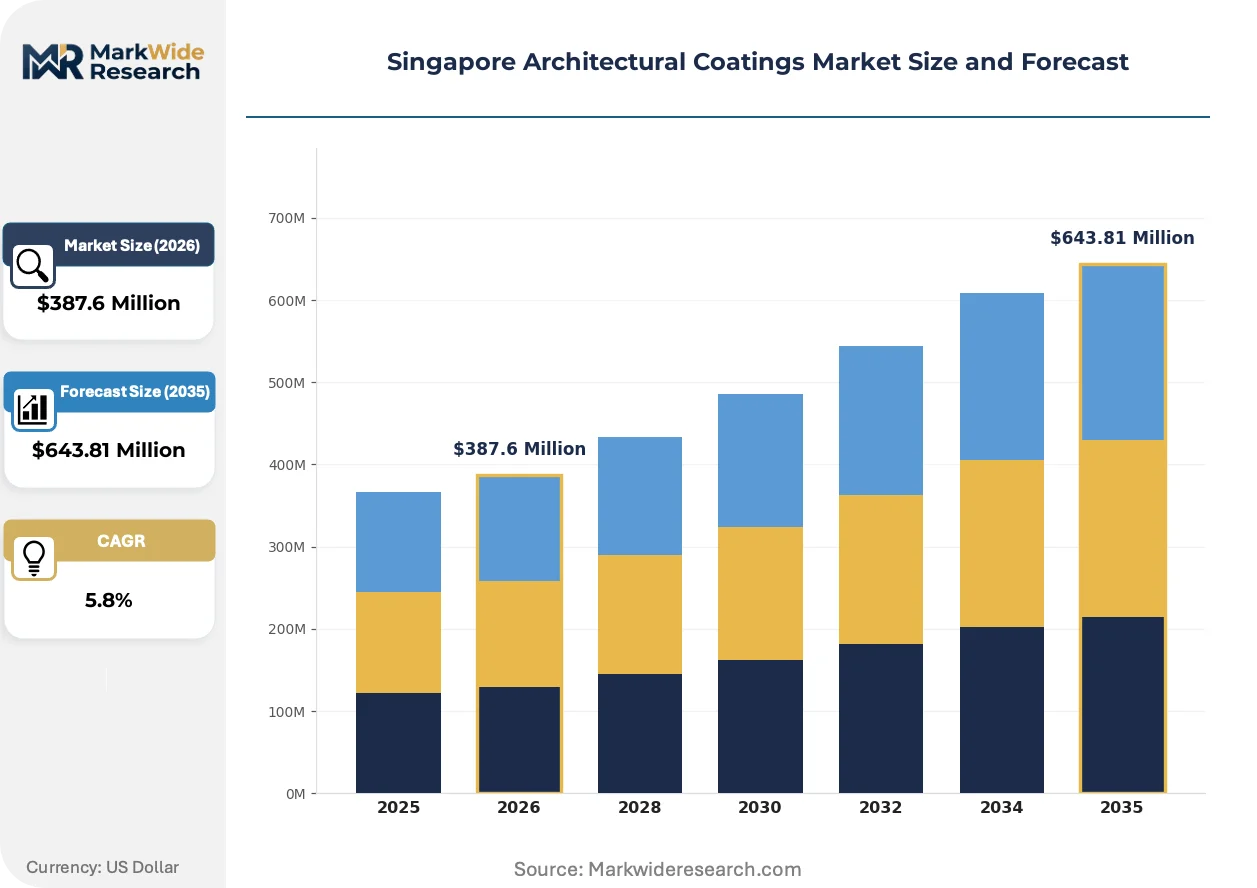
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsions, Solvent-based Coatings, Water-based Coatings, Powder Coatings End User: Residential Buildings, Commercial Spaces, Institutional Facilities, Industrial Structures Application: Interior Walls, Exterior Walls, Ceilings, Floors Technology: Eco-friendly Solutions, Fast-drying Technology, Anti-fungal Coatings, Specialty Coatings |
| Companies Covered | Kansai Paint Co.,Ltd., Raffles Paint Pte Ltd, AkzoNobel N.V., Axalta Coating Systems, DAI NIPPON TORYO CO., LTD., Jotun, Seamaster Paint (Singapore) Pte Ltd, SKK(S) Pte. Ltd, Nippon Paint Holdings Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Architectural Coatings Market Evolving Landscape
Formulation chemistry is pivoting toward bio-based binders and smart-functional surfaces as Singapore tightens embodied carbon tracking across the built environment.
Photocatalytic titanium dioxide coatings is miniaturizing particle architectures to sub-50 nanometer scales, enabling transparent self-cleaning films that preserve aesthetic substrates in heritage conservation projects. Conservation architects at National Gallery Singapore and Peranakan shophouse restorations are specifying these formulations at triple the rate of conventional anti-carbonation treatments. The technology is miniaturizing equipment footprints for on-site application, reducing scaffolding duration and labor cost exposure for high-rise maintenance contractors.
BCA's Green Mark 2021 sustainability tiers have tightened formaldehyde emission limits for interior coatings, compelling reformulation of conventional acrylic-urethane hybrids used in commercial fit-outs. Manufacturers must now submit third-party SGS or TÜV test reports for VOC content and heavy metal screening before project tender qualification. Premium-grade anti-fungal emulsions for healthcare and F&B spaces face the steepest compliance ramps, with lead times extending for certified batch production.
Facility managers at integrated resorts and airport terminals are consolidating coating procurement under five-year performance-based maintenance contracts, displacing transactional spot purchasing. Bundled application-and-warranty agreements from approved contractor panels are capturing 60 percent of commercial maintenance spend, squeezing independent applicator margins. This consolidation is most visible in the Marina Bay Sands and Changi Airport precincts, where asset longevity guarantees now override unit cost minimization in vendor selection.
Singapore Architectural Coatings Market Segmentation
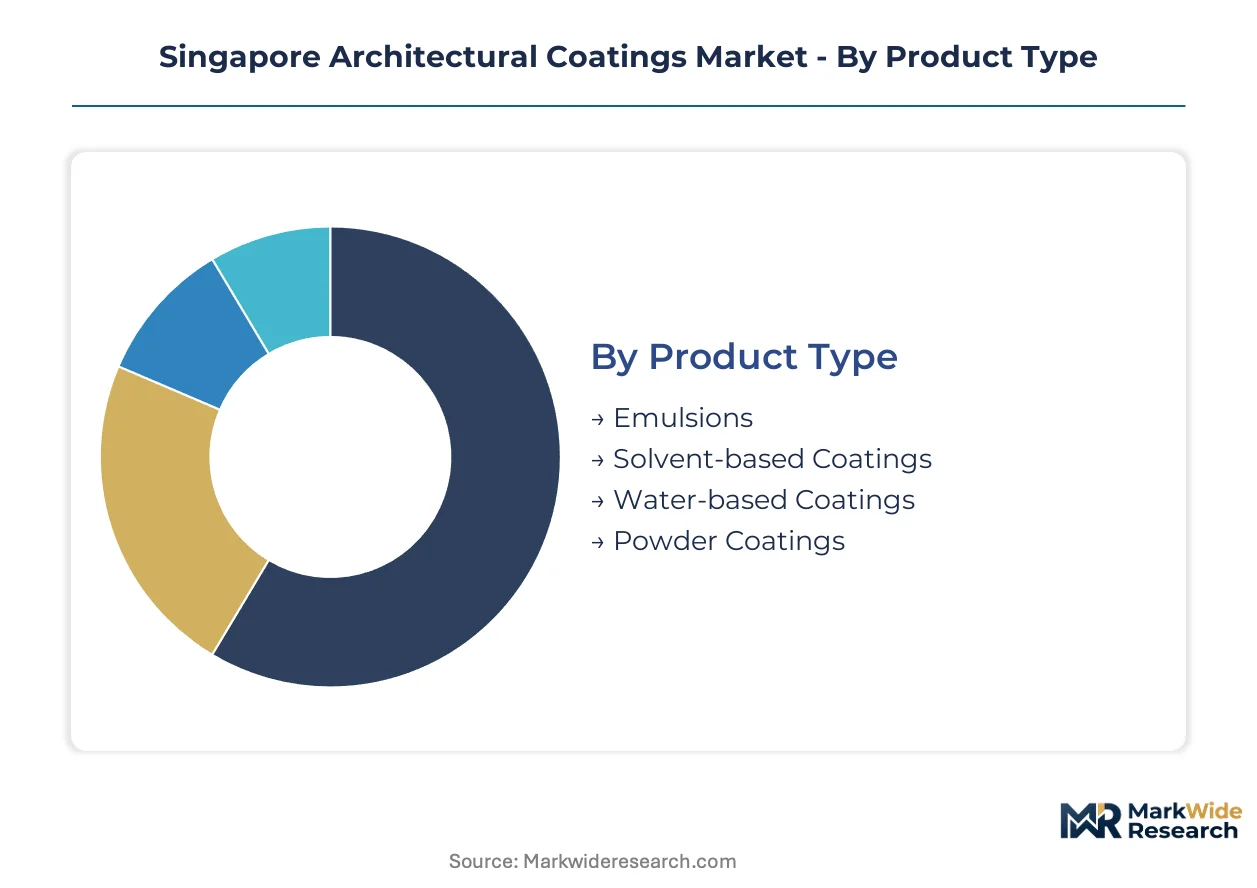
Architectural coatings in Singapore fragment across formulation chemistry, building typology, substrate application, and functional technology. Each dimension carries distinct margin profiles and regulatory exposure under BCA Green Mark tiers.
Product Type:
Premium margin pools concentrate in low-VOC water-based formulations as Green Mark certification tightens procurement specifications.
- Emulsions:Acrylic and vinyl-acetate copolymer dispersions with 30-60% solids content dominate interior wall specifications across HDB estates and private condominiums. Residential renovation contractors specify these for rapid recoating cycles in aging estates.
- Water-based Coatings:Alkyd and polyurethane dispersions with VOC levels below 50 g/L command specification priority in Marina Bay commercial developments. BCA Green Mark 2021 mandates are accelerating procurement displacement of legacy solvent systems.
- Solvent-based Coatings:High-solids alkyd and epoxy formulations retain niche use in industrial structures and exterior metal substrates where humidity resistance overrides VOC constraints.
- Powder Coatings:Thermoset polyester and epoxy-polyester hybrids serve architectural aluminum cladding and window frame applications with zero VOC emissions.
The dominant share belongs to emulsions, while water-based coatings are closing the gap fastest.
End User:
Volume concentration tracks building stock age and renovation intensity across Singapore's urban districts.
- Commercial Spaces:Office towers, retail podiums, and integrated resorts in the CBD and Orchard Road corridor drive high-performance exterior coating demand. Asset owners specify 10-year durability warranties for facade maintenance contracts.
- Residential Buildings:HDB upgrading programs and private condominium refresh cycles generate steady emulsion volume for interior wall recoating. Aging estates in Tampines and Jurong West concentrate renovation contractor activity.
- Institutional Facilities:Schools, hospitals, and government buildings face strict formaldehyde emission limits under NEA indoor air quality guidelines.
- Industrial Structures:Warehousing and logistics facilities in Tuas and Changi North prioritize corrosion-resistant epoxy systems for structural steel protection.
Commercial spaces capture the largest value pool, with residential buildings expanding most quickly on renovation intensity.
Application:
Substrate exposure conditions determine formulation specification and re-coating frequency across tropical building envelopes.
- Interior Walls:Anti-fungal emulsions address humidity-driven mold proliferation in residential and hospitality spaces. Healthcare and F&B operators specify SGS-certified low-formaldehyde systems.
- Exterior Walls:High-rise facades in the CBD and Marina Bay demand photocatalytic self-cleaning coatings to combat tropical soiling. Titanium dioxide nanocoatings reduce scaffolding costs for maintenance contractors.
- Ceilings:Flat and low-sheen emulsions serve acoustic tile and concrete soffit applications in commercial fit-outs.
- Floors:Epoxy and polyurethane screeds protect concrete substrates in industrial and institutional heavy-traffic zones.
Interior walls retain volume leadership, though exterior walls show the steepest specification upgrade trajectory on performance contracting trends.
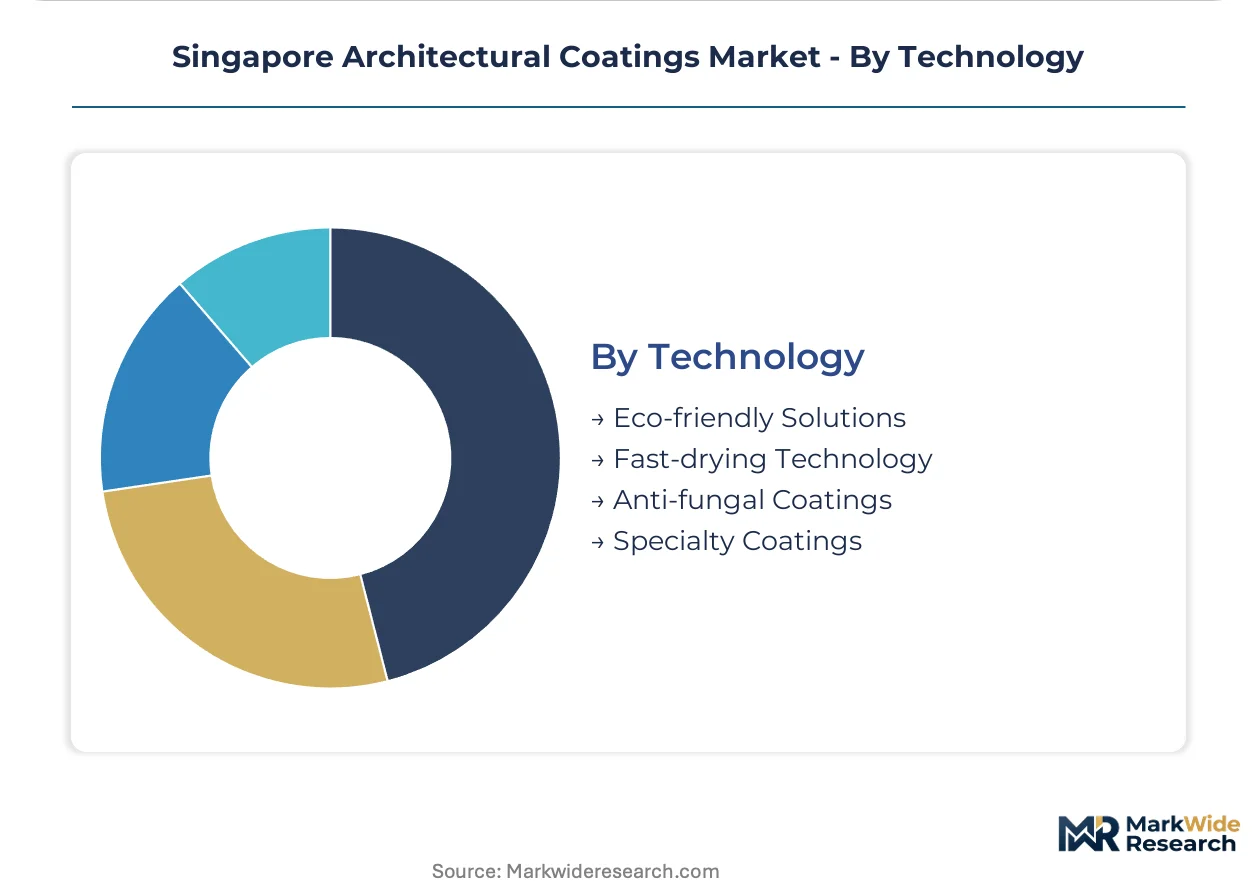
Technology:
Innovation premiums cluster around functional performance and environmental compliance verification.
- Eco-friendly Solutions:Bio-based binders and recycled content formulations align with NEA carbon disclosure requirements for building materials. Third-party eco-labeling from SGS or TÜV qualifies products for Green Mark projects.
- Specialty Coatings:Anti-carbonation and chloride-resistant systems protect concrete infrastructure in coastal exposure zones. Conservation architects specify these for heritage shophouse restorations.
- Fast-drying Technology:Accelerated cure formulations compress application windows for commercial renovation projects with tight handover schedules.
- Anti-fungal Coatings:Isothiazolinone and silver-ion biocide systems inhibit mold growth in high-humidity interiors. Healthcare and childcare facilities mandate these for infection control protocols.
Eco-friendly solutions command expanding share, while specialty coatings deliver the strongest margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Renovation contractors in Singapore's aging HDB estates show the highest price elasticity, while asset owners in Marina Bay and Changi Airport precincts prioritize performance warranties over unit cost. This divergence compresses margins for commodity emulsion suppliers while expanding premiums for certified low-VOC formulations.
Central Business District
Office tower facade maintenance contracts drive specification of photocatalytic self-cleaning coatings with 10-year durability guarantees. BCA Green Mark 2021 mandates accelerate displacement of legacy solvent systems in new commercial developments. Marina Bay Sands and Raffles Place clusters concentrate demand for high-performance exterior applications with bundled warranty terms.
Tampines Regional Centre
Decentralized commercial hub development disperses procurement authority away from traditional CBD specification channels. HDB upgrading programs generate steady interior emulsion volume for residential renovation contractors. The Tampines and Simei estate clusters concentrate aging stock requiring anti-fungal formulations for humidity-driven mold remediation.
Jurong Lake District
Mixed-use redevelopment around the second central business district creates new construction coating demand outside established supply corridors. Industrial logistics facilities in Tuas prioritize corrosion-resistant epoxy systems for structural steel protection. NEA carbon pricing alignment pressures project developers to specify verified low-carbon coating portfolios for compliance disclosure.
Orchard Road Corridor
Integrated resorts and luxury retail podiums consolidate procurement under five-year performance-based maintenance contracts. Asset longevity guarantees override unit cost minimization in vendor selection for high-traffic hospitality spaces. The ION Orchard and Tanglin clusters exemplify specification concentration where premium-grade anti-fungal emulsions face steep BCA compliance ramps.
Singapore Architectural Coatings Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Singapore's architectural coatings sector. Multinational formulators leverage global R&D infrastructure to dominate premium water-based segments, while local players anchor positions through channel control across contractor networks. Three archetypes define the competitive map: technology-led multinationals, regionally rooted specialists, and marine-grade crossover operators. Capacity expansion and portfolio diversification toward eco-certified formulations represent the dominant competitive moves as Green Mark tiers tighten.
Within the multinational tier, AkzoNobel N.V. and Kansai Paint Co.,Ltd. exemplify integrated leaders with access to global formulation libraries. Raffles Paint Pte Ltd occupies a position among locally rooted specialists with established contractor network relationships. Jotun represents the marine-grade crossover archetype, translating shipyard coating expertise into high-performance exterior building applications. These three anchors illustrate how competitive positioning stratifies across technology access, channel depth, and application specialization.
| Leading Market Players |
|---|
| Kansai Paint Co.,Ltd. |
| Raffles Paint Pte Ltd |
| AkzoNobel N.V. |
| Axalta Coating Systems |
| DAI NIPPON TORYO CO., LTD. |
| Jotun |
| Seamaster Paint (Singapore) Pte Ltd |
| SKK(S) Pte. Ltd |
| Nippon Paint Holdings Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Five-year performance-based maintenance contracts lock in supply access for premium coating manufacturers while anchoring price visibility for asset owners across Marina Bay and Changi Airport precincts. These bundled application-and-warranty agreements compress spot-market exposure and elevate certified low-VOC formulations above commodity alternatives.
Pricing Analysis
After-sales service revenue through extended warranty and recoating maintenance drives lifetime value for coating suppliers in Singapore's commercial segment. Three-tier pricing structure across premium Green Mark-certified, standard-compliant, and economy-grade formulations segments buyers by certification tier and volume scale. Cost compression in economy emulsions is intensifying because renovation contractors in aging HDB estates show acute price sensitivity. Asset owners in integrated resorts and airport terminals demonstrate minimal price sensitivity, prioritizing decade-long durability guarantees over unit cost.
Supply Chain Analysis
Strategic stockpiling of titanium dioxide feedstock dominates inventory strategy among Singapore formulators seeking insulation from sulfate-process Chinese supply volatility. Raw material sourcing draws from Malaysian and Thai petrochemical corridors for specialty resins, Chinese sulfate-process producers for TiO2 pigment, and regional ASEAN hubs for acrylic monomers. Single-source vulnerability concentrates in titanium dioxide supply from Chinese producers using the sulfate process. Distribution runs through authorized contractor panels and direct-to-contractor digital platforms disintermediating traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BCA-accredited Green Mark assessor certification represents the critical capability gap constraining project approval velocity, with limited professional supply extending timelines for sustainable coating specifications across commercial developments.
For Market Incumbents: Compound channel control advantages by securing exclusive contractor panel relationships in Tampines and Jurong Lake District decentralized hubs before specification authority fragments further. Deepen backward integration into bio-based binder development to anticipate NEA Scope 3 disclosure requirements. Anchor position through captive supply of certified low-carbon formulations that emerging entrants cannot replicate without third-party eco-labeling infrastructure. For New Entrants and Emerging Players: Lead with digital procurement platforms targeting mid-scale renovation contractors in aging HDB estates where price elasticity exceeds brand loyalty. White-space concentration sits in direct-to-contractor B2B portals disintermediating traditional distributor layers. Anti-fungal emulsions for healthcare and childcare facilities offer penetrable entry given steep compliance ramps extending lead times for incumbent certified batch production. For Investors and Strategic Acquirers: Regional specialist formulators with established BCA relationship networks and Green Mark pre-qualification status represent the most defensible acquisition archetype. Long-term viability hinges on portfolio positioning ahead of embodied carbon tracking expansion across Singapore's built environment. The signal to watch is NEA carbon pricing alignment implementation timing for building materials Scope 3 disclosure thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Green Mark Certification Investment | BCA pre-qualification unlocks Marina Bay and CBD commercial tender access. |
| Backward Integration into Bio-Binders | In-house production of plant-based resins anticipates NEA carbon disclosure mandates. |
| Direct-to-Contractor Platform Launch | Digital procurement disintermediates distributor layers in Tampines renovation clusters. |
| Performance-Based Maintenance Contracts | Bundled warranty terms capture 60 percent of commercial maintenance spend at Changi Airport. |
| Titanium Dioxide Strategic Stockpile | Inventory buffer insulates margin volatility from Chinese sulfate-process supply concentration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BCA regulatory filings, NEA hazardous substance schedules, customs import data, and contractor procurement databases. Primary interviews engaged formulation chemists at multinational coating producers, procurement leads at integrated resort operators, technical directors at local specialist manufacturers, and project managers at HDB upgrading contractors. Secondary validation drew from Building and Construction Authority Green Mark certification records, National Environment Agency chemical restriction updates, and trade flow documentation through Singapore Customs. Bottom-up volume estimates from substrate application rates triangulate against top-down market value reconstructions.
Segmentation dimensions modeled span formulation chemistry, building typology, substrate application, and functional technology tiers across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating BCA regulatory phase-in schedules and renovation cycle intensity patterns. Industry-specific forecast inputs include HDB estate age profiles, Marina Bay development pipeline tracking, and Green Mark certification tier adoption curves.
The analysis sits within stated boundaries; outcomes outside BCA regulatory implementation timelines or NEA carbon pricing alignment schedules would require recalibration. Forecasts reflect assumptions on contractor certification velocity and feedstock supply continuity. Revision becomes warranted when titanium dioxide supply concentration or cross-border logistics friction crosses thresholds disrupting formulation cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Europe Building and Construction Sheets Market
Building Materials
Global Facade Market
Building Materials
Thin Brick Market
Building Materials
North America Engineered Stone Market
Building Materials
Ireland Cement Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Granite Market
Building Materials
Fiber Reinforced Concrete Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
Cement Board Market
Building Materials
Recycled Construction Aggregates Market
Building Materials
Polymer Concrete Market
Building Materials
Ductile Iron Pipe Market
Building Materials
Italy Facade Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Steel Sleepers Market