
 Runway Pavement Grade Asphalt Market | 2026-2036
Runway Pavement Grade Asphalt Market Size, Share, and Industry Trends Forecast 2026-2036
Runway Pavement Grade Asphalt Market Analytics
Modular specification packages for runway resurfacing is shifting procurement behavior across major aviation authorities. Exxon Mobil Corporation leverages its integrated refinery network to secure consistent binder supply for high-performance grades. Royal Dutch Shell competes through specialized polymer modification capabilities that meet stringent rutting resistance requirements. Total SA anchors its position in European airfield projects with formulations certified under multiple national standards.
Runway pavement grade asphalt denotes bituminous binder systems engineered to specified penetration, softening point, and viscosity parameters for aircraft load-bearing surfaces, typically manufactured through controlled air-blowing or polymer modification to achieve superior deformation resistance under jet tire stress. Polymer modified asphalt commands premium positioning due to extended service intervals under thermal cycling, while warm mix asphalt gains traction as airports pursue lower-temperature placement to reduce energy intensity and emissions during construction windows. Reclaimed asphalt pavement technology matures as a cost-optimization lever, though its penetration in primary runway surfaces remains constrained by structural performance thresholds.
FAA Advisory Circulars and EPA emissions guidelines jointly shape formulation choices and placement protocols for U.S. airfield contractors. EASA certification requirements and EU Green Deal carbon benchmarks drive parallel compliance investments across European airport authorities. Stakeholders must weigh binder grade selection against evolving lifecycle carbon accounting and emerging performance-based contractor specifications that transfer long-term pavement liability to construction firms.
Market Dynamics
FAA performance-grade specifications for high-shear runway surfaces are compressing formulation choice sets while Southeast Asian greenfield airport construction accelerates polymer-modified asphalt procurement. This regulatory-demand tension is redistributing competitive advantage toward integrated binder suppliers with captive polymer modification capabilities.
Growth Catalysts
- Polymer modification technology:Airport operators in Indonesia, Vietnam, and the Philippines specify SBS-modified binders for new runways to meet extended service interval requirements under tropical thermal cycling.
- FAA Advisory Circular 150/5370-10G:Updated rutting resistance thresholds for high-traffic airfields are disqualifying conventional penetration-grade asphalts from primary runway contracts.
- Warm mix asphalt placement protocols:European airport authorities under EU Green Deal carbon benchmarks are mandating reduced-temperature construction to cut energy intensity during resurfacing windows.
Market Restraints
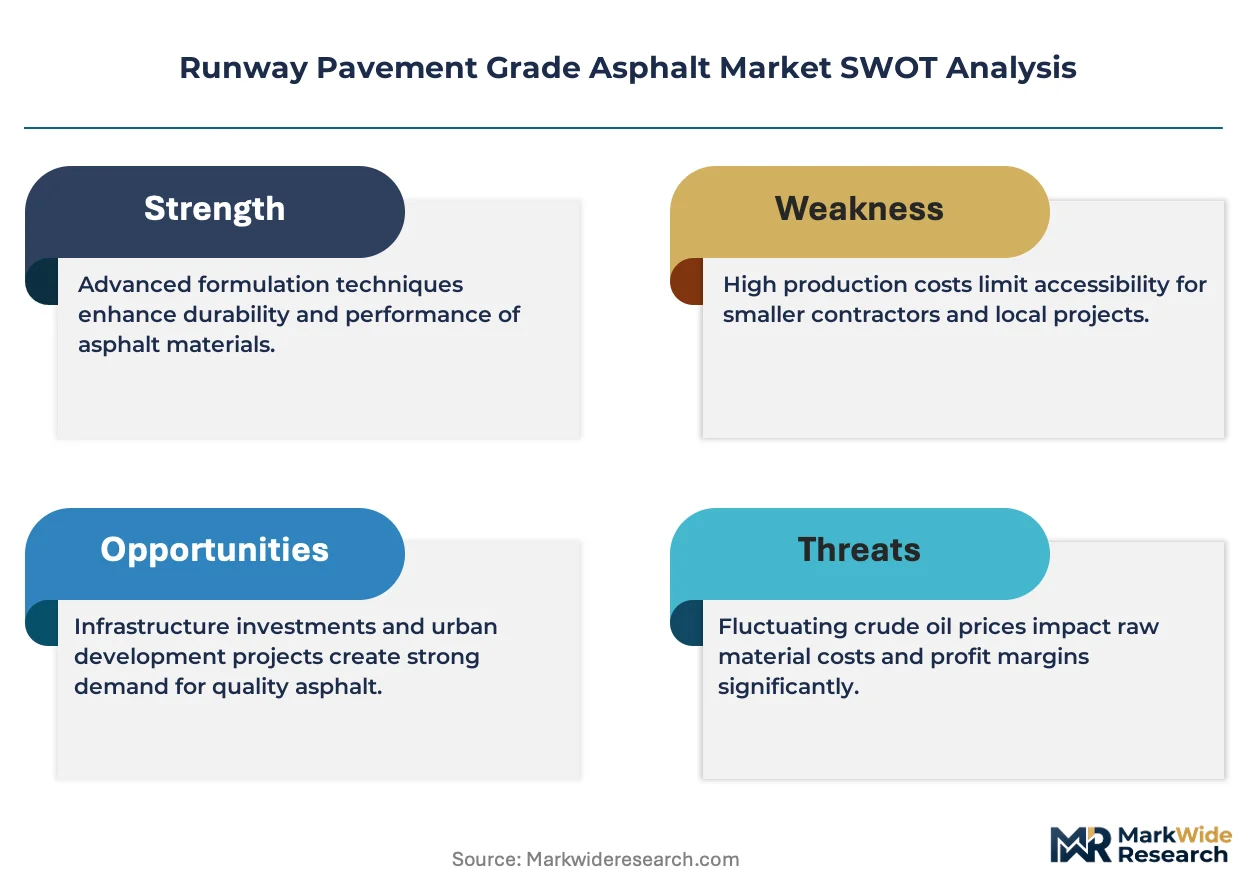
- Crude-derived binder cost volatility:Vacuum residue feedstock prices track Brent crude movements, compressing margin predictability for specialized airfield grade producers without upstream integration.
- Reclaimed asphalt pavement performance thresholds:FAA and EASA structural specifications limit RAP content in primary runway surfaces to sub-20% blends, constraining circular economy cost optimization.
- Specialized polymer supply concentration:SBS and SBR modifier production clusters in Northeast Asia create geographic single-point-of-failure exposure for Western formulators.
Strategic Opportunities
- Bio-based binder formulations:EASA certification pathways for lignin-modified asphalts are opening compliance-compatible routes to lifecycle carbon reduction in European airfield projects.
- Performance-based contractor specifications:UK and Australian airport authorities are piloting 20-year pavement liability transfers to construction firms, creating demand for predictive modeling services.
- Modular specification packages:Digital tender platforms in Southeast Asia are standardizing polymer-grade selection criteria, reducing transaction friction for qualified international suppliers.
Industry Challenges
- Polymer modification technician scarcity:Blending plant operations require specialized rheology expertise that outpaces vocational training pipeline output in emerging aviation hubs.
- Multi-jurisdiction certification timelines:Simultaneous FAA, EASA, and national standard compliance for export-grade formulations extends product development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Runway Pavement Grade Asphalt Market |
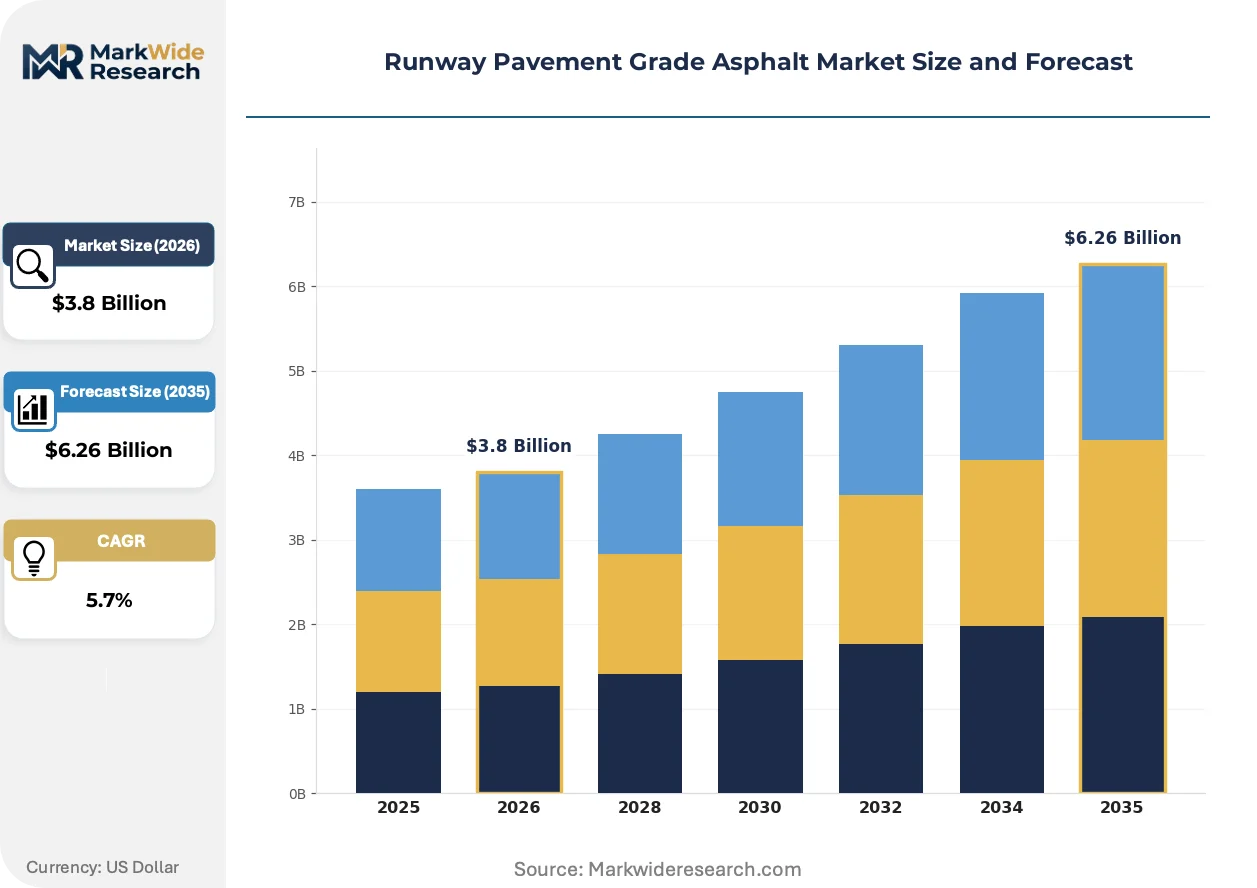
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Mix Asphalt, Cold Mix Asphalt, Warm Mix Asphalt, Polymer Modified Asphalt End User: Aviation Authorities, Airport Operators, Construction Firms, Maintenance Contractors Application: Runway Surface, Taxiway Surface, Apron Surface, Airfield Pavements Technology: Standard Design, Reclaimed Asphalt Pavement, Super Pave, Thin Overlay |
| Companies Covered | Exxon Mobil Corporation, Royal Dutch Shell, Total SA, LafargeHolcim, Colas Limited, Vinci SA, Granite Construction Incorporated, Boral Limited, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Runway Pavement Grade Asphalt Market Evolving Landscape
Warm mix additive chemistry is compressing placement temperature windows without sacrificing deformation resistance, enabling construction season extension in temperate climates. This thermal efficiency pivot intersects with polymer modification advances and digital quality assurance protocols to reshape airfield pavement engineering.
Phase-change microencapsulation in polymer modified asphalt is consolidating temperature susceptibility management into single-binder systems. Airport authorities in Germany and Japan specify these formulations for runways experiencing extreme diurnal thermal swings. The technology is consolidating what previously required seasonal grade switching into year-round single-source procurement.
EU Green Deal carbon benchmarks are forcing lifecycle emissions disclosure across airfield construction supply chains. EASA certification requirements now incorporate embodied carbon thresholds for runway resurfacing materials. European airport operators in France, Netherlands, and Scandinavia are responding by mandating environmental product declarations in tender documentation.
Long-term pavement performance warranties are displacing conventional unit-price contracting in major aviation hubs. Construction firms in Australia and the United Kingdom now carry 15-20 year structural liability for runway surfaces. This risk transfer compresses contractor margins while elevating demand for predictive pavement management systems and accelerated loading test protocols.
Runway Pavement Grade Asphalt Market Segmentation
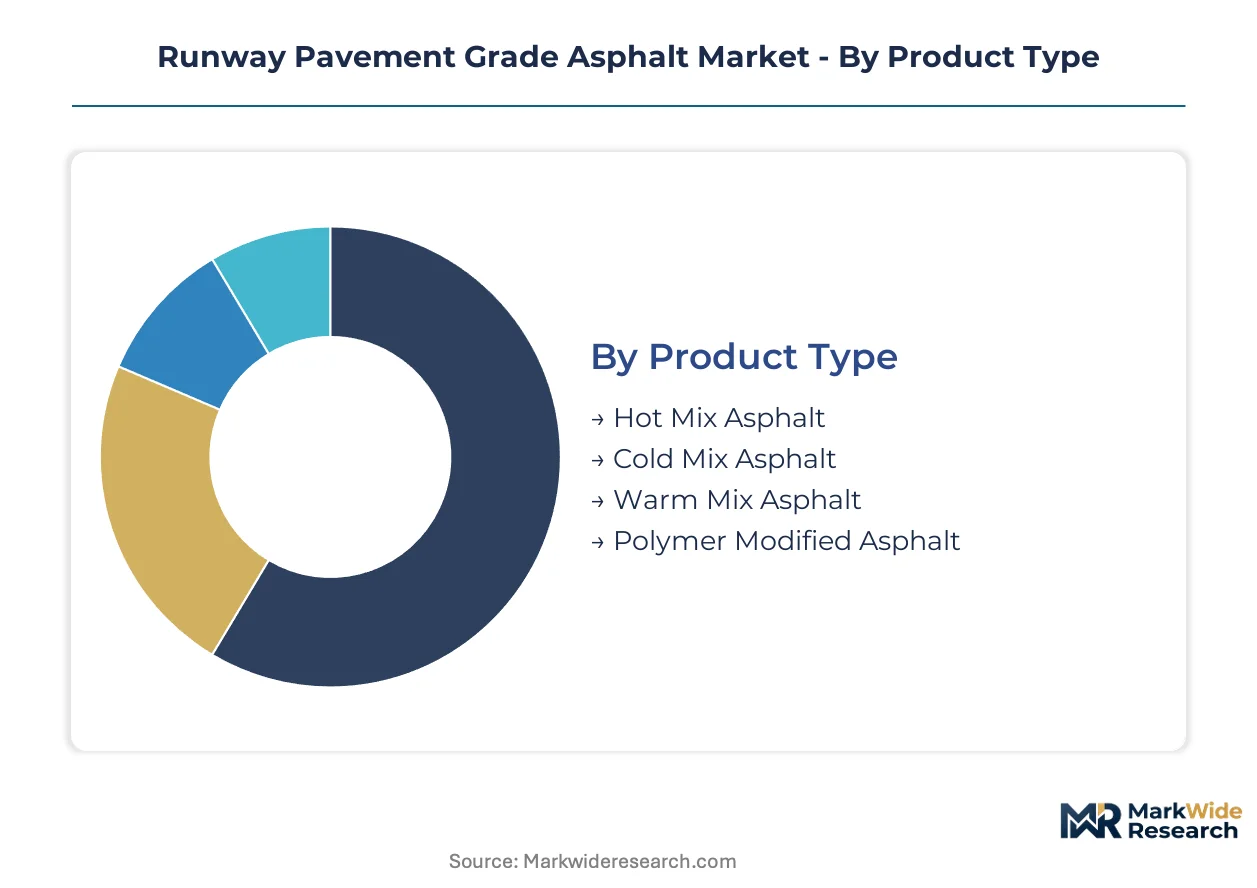
Runway pavement grade asphalt procurement hinges on matching thermal performance, load-bearing capacity, and regulatory certification to specific airfield infrastructure demands. Segmentation reveals how polymer modification depth, placement temperature protocols, and end-user risk allocation reshape supplier positioning across aviation construction value chains.
Product Type:
Formulation sophistication spans from commodity penetration-grade binders to engineered polymer systems with multi-decade service warranties.
- Hot Mix Asphalt:Conventional air-blown binders placed above 150°C remain dominant for secondary taxiway resurfacing in temperate climates. Indonesian and Vietnamese airport authorities specify HMA for cost-constrained apron expansions where thermal cycling stress is moderated by canopy shading.
- Polymer Modified Asphalt:SBS-modified systems engineered to PG 76-22 or higher grades deliver deformation resistance under Boeing 777 and A350 tire loading. German and Japanese airport operators mandate PMA for primary runways experiencing extreme diurnal temperature swings exceeding 40°C.
- Warm Mix Asphalt:Chemical additive systems enable placement 20-40°C below HMA temperatures, cutting fuel consumption during European resurfacing windows constrained by EU Green Deal emissions benchmarks.
- Cold Mix Asphalt:Emulsion-based formulations serve emergency repairs and temporary access routes where hot plant mobilization is economically unfeasible.
Most installed capacity flows through Hot Mix Asphalt. Expansion is steepest in Polymer Modified Asphalt.
End User:
Risk-bearing capacity and technical specification authority determine procurement complexity across the aviation construction ecosystem.
- Airport Operators:Direct procurement by facility owners concentrates in Southeast Asian greenfield developments where 20-year performance warranties are becoming standard contract terms. Philippine airport authorities now require predictive pavement management system integration from construction partners.
- Aviation Authorities:FAA and EASA certification bodies indirectly shape demand through performance-grade specifications that disqualify conventional binders from high-shear runway contracts.
- Construction Firms:UK and Australian contractors increasingly carry 15-20 year structural liability, forcing upstream integration into polymer modification capabilities or captive supply partnerships.
- Maintenance Contractors:Reactive procurement for crack sealing and localized repairs favors cold mix and thin overlay solutions with minimal plant mobilization requirements.
Procurement volume concentrates with Airport Operators. Technical specification authority rests heaviest with Aviation Authorities.
Application:
Structural load intensity and thermal exposure severity create tiered performance requirements across airfield surfaces.
- Runway Surface:Primary load-bearing zones under jet aircraft tire stress demand PG 76-22 or higher polymer modified grades with rut depth specifications below 4mm. FAA Advisory Circular 150/5370-10G rutting thresholds are compressing formulation choice sets toward high-shear-capable binders.
- Taxiway Surface:Moderate speed operations permit warm mix placement protocols that reduce construction window emissions without sacrificing deformation resistance.
- Apron Surface:Stationary aircraft loading and fuel spill exposure drive specification toward polymer modified systems with superior chemical resistance.
- Airfield Pavements:Perimeter roads and service access routes accommodate higher reclaimed asphalt pavement content where structural performance thresholds are less stringent.
Specification stringency peaks at Runway Surface. Volume deployment is broadest across Airfield Pavements.
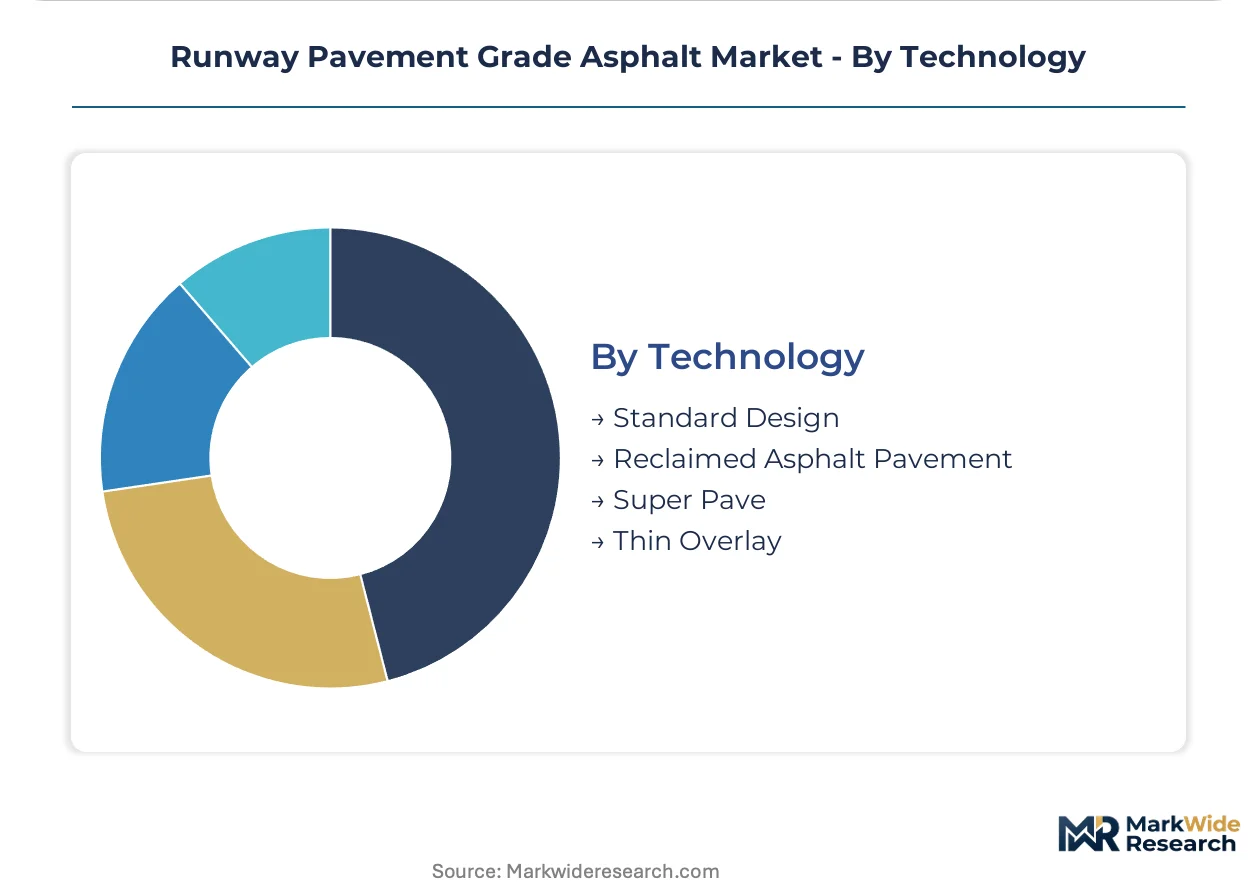
Technology:
Lifecycle cost optimization and circular economy mandates are redistributing investment across design methodologies.
- Super Pave:Performance-grade binder selection protocols developed under the Strategic Highway Research Program now dominate FAA-specified airfield projects. The volumetric mix design framework enables precise matching of binder grade to climatic conditions and traffic loading.
- Reclaimed Asphalt Pavement:FAA and EASA structural specifications constrain RAP content to sub-20% blends in primary runway surfaces, limiting circular economy penetration where performance thresholds are most demanding.
- Thin Overlay:Mill-and-replace strategies extend surface life with minimal structural intervention, gaining traction in European maintenance budgets constrained by carbon accounting disclosures.
- Standard Design:Conventional Marshall mix design persists in secondary markets where laboratory infrastructure for Super Pave gyratory compaction remains limited.
Technical adoption concentrates in Super Pave. Environmental pressure is mounting fastest against Standard Design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Runway pavement grade asphalt originated from post-war airfield engineering in the United States, where military specifications for jet aircraft load-bearing surfaces established the foundational performance-grade protocols now adopted worldwide. This technical lineage continues to shape procurement standards across aviation construction markets.
United States
FAA Advisory Circular 150/5370-10G rutting resistance thresholds now disqualify conventional penetration-grade binders from high-traffic runway contracts. The EPA emissions guidelines further constrain formulation choices and placement protocols for domestic airfield contractors. Texas and California aviation clusters concentrate polymer-modified asphalt demand where extreme diurnal thermal cycling exceeds 35°C.
Germany
Frankfurt and Munich airport authorities mandate polymer modified asphalt for primary runways experiencing temperature swings exceeding 40°C. EASA certification requirements incorporate embodied carbon thresholds under EU Green Deal benchmarks. The Bavarian industrial corridor anchors specialized blending plant capacity serving Central European airfield projects.
Indonesia
Greenfield airport construction in Jakarta and Bali drives SBS-modified binder procurement for tropical thermal cycling conditions. National infrastructure programs prioritize extended service interval specifications to minimize maintenance disruption. Java-based construction consortia are integrating predictive pavement management systems into 20-year performance warranties.
United Kingdom
Heathrow and Gatwick operators pilot 20-year pavement liability transfers to construction firms under performance-based contracting frameworks. UK aviation authorities align with EASA certification pathways while adding national carbon accounting disclosure requirements. The Southeast England construction cluster specializes in warm mix placement protocols for reduced-temperature resurfacing windows.
Australia
Sydney and Melbourne airport operators require 15-20 year structural warranties from runway contractors, elevating demand for accelerated loading test protocols. National infrastructure standards incorporate lifecycle emissions disclosure alongside performance-grade specifications. The Eastern Seaboard blending plant network serves domestic demand while exporting technical expertise to Southeast Asian aviation hubs.
Runway Pavement Grade Asphalt Market Competitive Landscape
The competitive structure tilts toward integrated energy majors with captive refinery networks and specialized polymer modification capabilities. Tier-one positions concentrate among petroleum refiners controlling vacuum residue feedstock supply, while mid-tier construction firms compete through performance-based warranty offerings. Strategic differentiation runs through backward integration into binder production, geographic expansion into Southeast Asian greenfield markets, and portfolio diversification into predictive pavement management services.
Among integrated petroleum refiners, Exxon Mobil Corporation and Royal Dutch Shell occupy positions exemplifying the upstream-integrated archetype with controlled feedstock access. Total SA represents the multi-standard certification specialist serving European airfield projects under concurrent FAA, EASA, and national compliance frameworks. These three anchors demonstrate how regulatory complexity favors players with dedicated certification resources and established relationships with aviation authorities across multiple jurisdictions.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Royal Dutch Shell |
| Total SA |
| LafargeHolcim |
| Colas Limited |
| Vinci SA |
| Granite Construction Incorporated |
| Boral Limited |
| Sika AG |
| Others |
Value Network & Pricing Analysis
FAA Advisory Circular 150/5370-10G rutting resistance thresholds are compressing formulation choice sets toward polymer-modified grades, forcing binder suppliers to absorb SBS modifier cost volatility or cede share to integrated refiners with captive polymer capabilities. This specification tightening redistributes pricing power upstream while squeezing margin predictability for non-integrated formulators.
Pricing Analysis
Three-tier pricing structure across premium polymer-modified, standard warm-mix, and economy penetration-grade levels dominates procurement frameworks, with differentiation driven by FAA/EASA certification tier and volume scale of greenfield airport contracts. Cost compression in standard warm-mix tiers is intensifying because European carbon accounting disclosures mandate lower-temperature placement protocols. Construction firms carrying 20-year performance warranties show least price sensitivity, while maintenance contractors executing reactive repairs exhibit highest elasticity.
Supply Chain Analysis
Multi-jurisdiction certification gating extends product development cycles by 18-24 months, favoring established suppliers with dedicated compliance resources. Vacuum residue feedstock draws from United States, Saudi Arabia, and Russian refinery complexes, while SBS and SBR modifier production clusters in Northeast Asia and South Korea. Single-source vulnerability concentrates in specialty polymer supply chains. Distribution runs through long-term offtake agreements with airport authorities and construction consortia rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratchet effects, with FAA performance-grade specifications and EU Green Deal carbon benchmarks jointly accelerating premium formulation substitution across aviation construction procurement.
For Market Incumbents: To counter feedstock cost volatility and margin compression from Brent crude tracking, integrated refiners should deepen backward integration into SBS modifier production and secure long-term offtake agreements with Southeast Asian greenfield airport authorities. Certification investment in concurrent FAA-EASA compliance frameworks preserves pricing power in export-grade formulations. For New Entrants and Emerging Players: Bio-based binder formulations leveraging lignin modification technology offer white-space entry into European airfield projects where EASA certification pathways are opening compliance-compatible carbon reduction routes. Target predictive pavement management services bundled with 20-year performance warranties as the most penetrable value-add segment, using accelerated loading test protocols as the go-to-market differentiator. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized blending plant operators in Southeast Asia possessing established relationships with Indonesian and Vietnamese aviation authorities. Long-term viability over a multi-year horizon hinges on exposure to greenfield airport construction pipelines rather than mature-market resurfacing cycles. Watch for EASA certification pathway acceleration for bio-based formulations as the inflection signal warranting portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Modification | Captive SBS supply secures margin stability against Northeast Asian supply concentration risks. |
| Multi-Jurisdiction Certification Investment | Concurrent FAA-EASA compliance opens procurement access to UK and Australian performance-based contracting frameworks. |
| Predictive Pavement Management System Development | Software-enabled lifecycle modeling supports 20-year warranty offerings demanded by Philippine and Indonesian airport authorities. |
| Warm Mix Additive Chemistry Advancement | Reduced-temperature placement protocols satisfy EU Green Deal carbon benchmarks for European resurfacing contracts. |
| Long-Term Supply Agreement Structuring | Offtake commitments with Southeast Asian greenfield developers de-risk capacity utilization across tropical thermal cycling specifications. |
Research Methodology
Coverage spans United States, Germany, Indonesia, United Kingdom, and Australia, with primary inputs from each market's aviation construction ecosystem. The research combines structured interviews with airport procurement directors, construction firm technical leads, binder blending plant operators, and regulatory affairs specialists at aviation authorities with secondary validation from FAA Advisory Circulars, EASA certification databases, customs trade data on vacuum residue imports, and SEC filings from integrated petroleum refiners. Bottom-up project pipeline analysis triangulates against top-down market sizing from national infrastructure budget disclosures.
Granularity-level modeling operates at product-type, end-user risk-bearing capacity, application intensity, and technology adoption dimensions. Volume and value outputs reflect segment-specific CAGRs derived from greenfield airport construction timelines, resurfacing cycle frequencies, and polymer modification penetration curves across tropical versus temperate climatic zones. Forecast inputs incorporate Super Pave adoption rates, reclaimed asphalt pavement content constraints, and performance-based warranty penetration in UK and Australian contracting frameworks.
The model holds under steady regulatory enforcement of FAA and EASA performance-grade specifications; deviation in crude price volatility or polymer supply disruption would shift margin distribution toward upstream-integrated suppliers. A model refresh is warranted upon material change in EASA bio-based binder certification pathways or Southeast Asian greenfield airport construction acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Watertight Doors Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
Europe Construction Repair and Rehabilitation Chemicals Market
Building & Construction Materials
Structural Insulated Panels (Sips) Market
Building & Construction Materials
Japan Prefab Wood Building Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
Global Cool Roofs Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
Insulated Metal Panels Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Plastic Roofing Tiles Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market