
 Fiber Reinforced Polymer Composites (FRP) Market | 2026-2036
Fiber Reinforced Polymer Composites (FRP) Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Reinforced Polymer Composites (FRP) Market Analysis
China's carbon fiber precursor manufacturing base is consolidating as domestic producers scale acrylonitrile-to-carbon-fiber conversion lines. Toray Industries leverages its integrated precursor-to-prepreg chain to sustain margin control across aerospace qualification tiers. Owens Corning anchors North American glass fiber supply through its Texas and South Carolina melting operations. Hexcel Corporation specializes in thermoset prepregs for Boeing and Airbus tier-one contracts, while Jushi Group dominates E-glass roving output from its Egyptian and Chinese plants.
Fiber reinforced polymer composites are engineered materials combining high-strength fibers with thermoset or thermoplastic polymer matrices, typically achieving specific tensile strengths exceeding 1,500 MPa while remaining 60-70% lighter than comparable steel structures. These materials serve primarily to reduce mass in load-bearing applications where corrosion resistance and fatigue tolerance outweigh raw material costs. Glass fiber products occupy the volume-dominant position in construction and marine applications due to cost accessibility, while carbon fiber commands premium positioning in aerospace and performance automotive segments where stiffness-to-weight ratios determine design feasibility. Aramid fiber maintains niche defensive applications despite limited growth, and bio-based fiber variants are attracting R&D allocation from European OEMs facing EU Green Deal embodied-carbon accounting requirements.
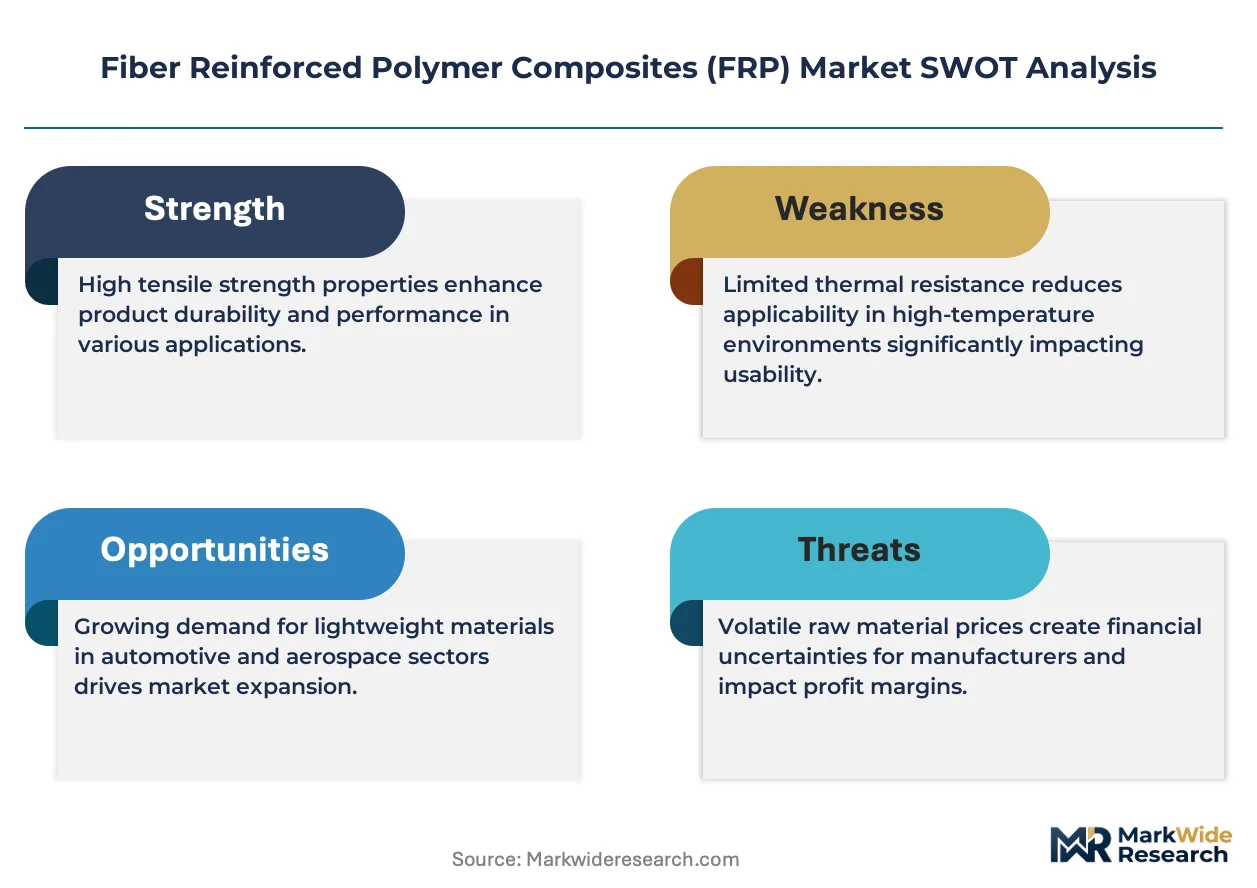
REACH registration obligations govern chemical constituent disclosure across European composite supply chains, while the FAA's material qualification protocols dictate airframe certification timelines for US aerospace applications. China's GB standards and MEE environmental inspections are raising compliance thresholds for domestic phenolic and epoxy resin formulation plants. Stakeholders must monitor divergence between EU carbon-border adjustment mechanisms and US Inflation Reduction Act domestic content bonuses as these frameworks reshape competitive access for imported prepreg materials.
Market Dynamics
EU REACH chemical disclosure mandates and the EU Green Deal's embodied-carbon accounting are forcing composite manufacturers to requalify resin formulations and fiber sourcing, compressing supplier margins while opening certification premiums for low-carbon prepregs.
Growth Catalysts
- EU Green Deal embodied-carbon rules:Tier-one automotive OEMs in Germany now require cradle-to-gate carbon declarations for all structural composite inputs, pulling bio-based fiber R&D into commercial procurement cycles.
- Wind turbine blade scaling:China's offshore wind installation targets above 60GW by 2030 are absorbing multi-ton carbon fiber spar cap volumes, concentrating demand in Jiangsu and Guangdong manufacturing zones.
- Thermoplastic tape laying:Automated fiber placement systems are cutting aerospace cycle times by 40% versus thermoset autoclave curing, with Boeing and Airbus tier suppliers qualifying PEEK and PPS matrices for next-generation narrow-body programs.
Market Restraints
- Acrylonitrile price volatility:Carbon fiber precursor costs track propylene and ammonia feedstock swings, exposing margin compression when oil benchmarks exceed $85 per barrel.
- Japanese precursor concentration:Toray, Teijin, and Mitsubishi Chemical control 70% of global PAN precursor supply, creating single-source risk for qualified aerospace material streams.
- Aluminum-lithium substitution:Airbus A350 wing skins use Al-Li 2195 alloy in select panels where FRP repair protocols remain uneconomical for high-cycle routes.
Strategic Opportunities
- India civil aviation MRO:Bangalore and Hyderabad maintenance hubs lack qualified composite repair stations, creating first-mover advantage for certified prepreg distributors.
- Hydrogen pressure vessel filament winding:Type IV tank demand for heavy-duty fuel cell trucks is converging with automated tow placement and in-situ thermoplastic consolidation.
- US Inflation Reduction Act domestic content bonuses:Wind blade manufacturers sourcing glass fiber from Texas and South Carolina melting operations qualify for production tax credit adders.
Industry Challenges
- Autoclave throughput bottlenecks:Aerospace part qualification requires 8-12 hour cure cycles at 180°C and 7 bar pressure, constraining capacity expansion without $50M+ capital deployment per unit.
- Cross-jurisdiction material equivalency:FAA, EASA, and CAAC maintain non-harmonized qualification test matrices, forcing redundant coupon testing for global platform programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Reinforced Polymer Composites (FRP) Market |
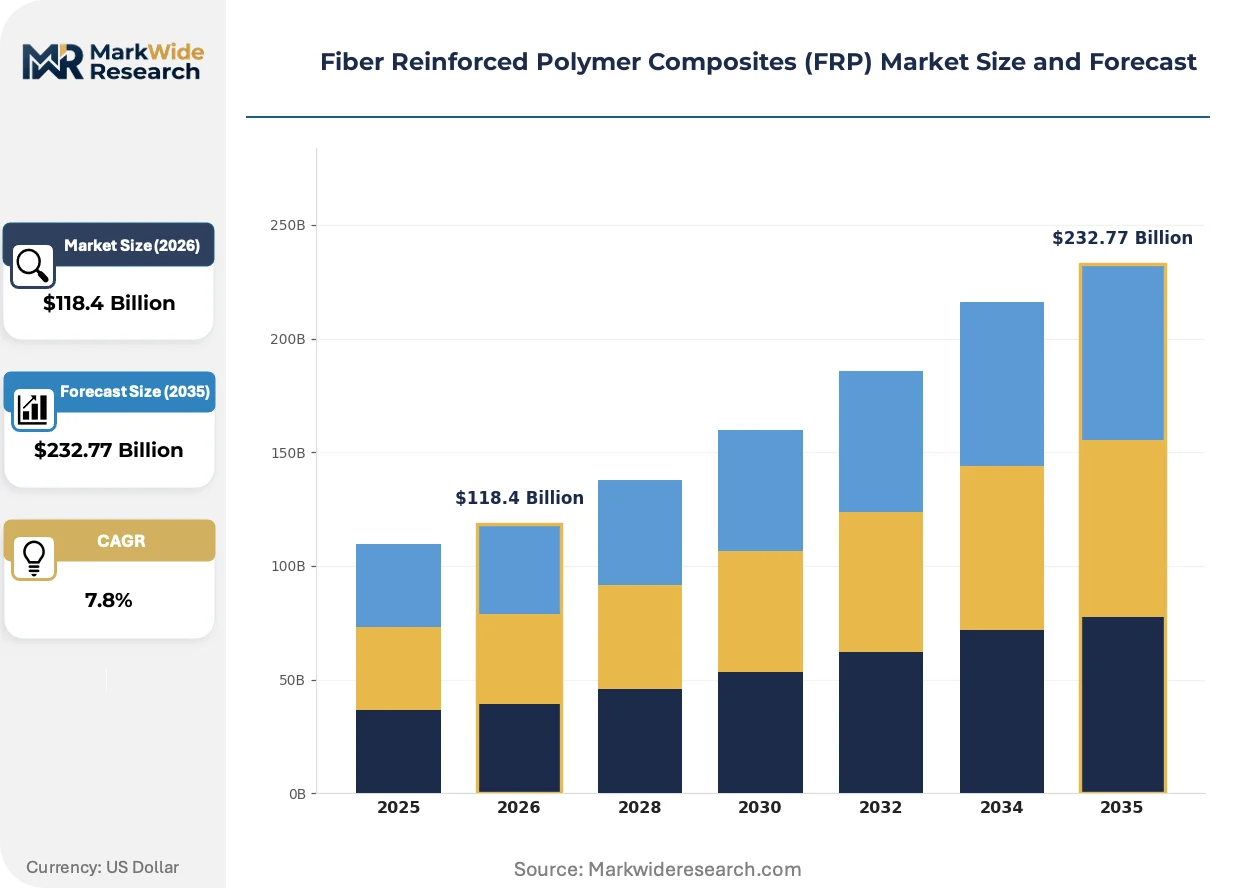
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $232.77 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Fiber, Carbon Fiber, Aramid Fiber, Bio-based Fiber Application: Aerospace, Automotive, Construction, Marine End User: Manufacturers, Contractors, OEMs, Distributors Distribution Channel: Direct Sales, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | Mitsubishi Chemical Group, SGL Carbon, Toray Industries, BASF, Teijin Limited, Hexcel Corporation, Solvay, Jushi Group, Owens Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Reinforced Polymer Composites (FRP) Market Emerging Trajectories
Thermoplastic composites are displacing thermosets in high-rate production environments, while regulatory carbon accounting and automated manufacturing reshape competitive requirements across aerospace, automotive, and wind energy supply chains.
Out-of-autoclave thermoplastic consolidation is unifying prepreg impregnation and in-situ welding into single-pass processing. Automotive structural component suppliers in Germany and the US are adopting this for battery enclosure volumes above 50,000 units annually. The technology is unifying what were separate autoclave, freezer storage, and adhesive bonding operations into continuous lines, collapsing lead times from weeks to hours.
REACH Article 33 disclosure obligations now extend to composite articles containing SVHCs above 0.1% w/w, forcing European manufacturers to map epoxy hardener and flame-retardant additive chains. Formulators are responding with anhydride-cured systems and halogen-free phosphorus chemistries. Wind blade producers face the steepest requalification burden, as brominated flame retardants in lightning strike protection layers trigger downstream notification duties.
Buyers are consolidating qualified supplier lists from 12-15 vendors to 3-4 strategic partners capable of delivering full material pedigree documentation. Tier-one aerospace contractors now mandate blockchain-traceable fiber lot records from precursor polymerization through prepreg slitting. This concentration is most visible in North Carolina's aerospace corridor, where Boeing and Gulfstream procurement teams have reduced carbon fiber tape suppliers from seven to three since 2022.
Fiber Reinforced Polymer Composites (FRP) Market Segmentation
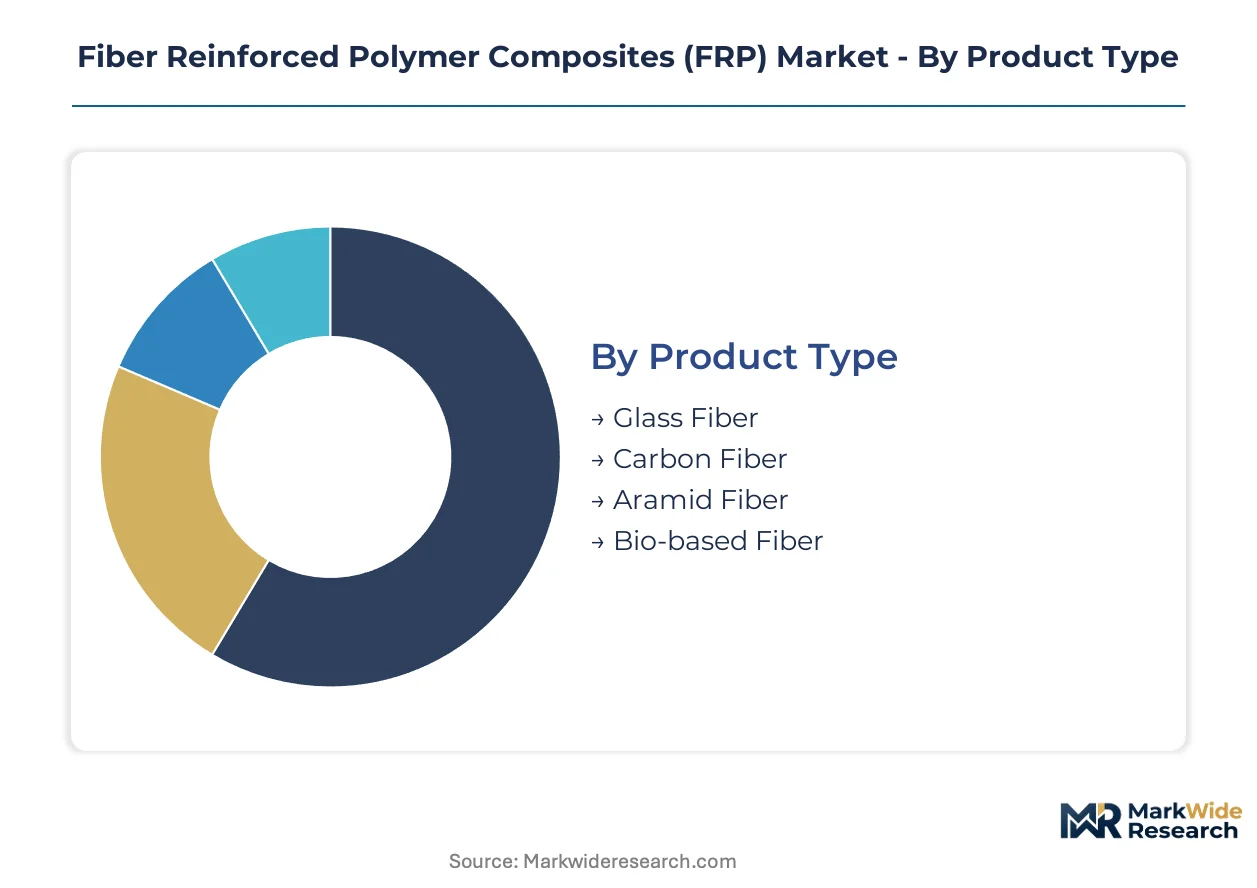
FRP procurement patterns diverge sharply between industries demanding standalone structural members versus those embedding composites within larger assemblies. Segment boundaries determine qualification protocols, margin structures, and supplier consolidation trajectories across aerospace, automotive, and wind energy supply chains.
Product Type:
Glass fiber dominates standalone reinforcement applications where cost thresholds override stiffness requirements, while carbon fiber concentrates in embedded aerospace structures demanding pedigree documentation from precursor through cure.
- Glass Fiber:E-glass and S-glass variants achieve tensile strengths of 3,400-4,600 MPa at raw material costs below carbon fiber by an order of magnitude. Demand concentrates in China's wind turbine blade manufacturing zones and Texas-based pipe rehabilitation contractors serving municipal infrastructure.
- Carbon Fiber:PAN-based precursors yield modulus values exceeding 230 GPa, qualifying for primary airframe structures under FAA certification protocols. Procurement clusters in Germany's automotive supplier corridor and Washington state's Boeing tier-one ecosystem, where REACH-compliant resin systems command certification premiums.
- Aramid Fiber:Kevlar and Twaron grades absorb ballistic impact energy through fibrillation mechanisms, sustaining niche defense procurement despite limited civil aviation adoption.
- Bio-based Fiber:Flax and hemp fiber variants from European cultivation zones meet EU Green Deal embodied-carbon thresholds for interior automotive panels and consumer goods housings.
Volume placements concentrate in Glass Fiber; the faster expansion belongs to Carbon Fiber.
Application:
Application segments stratify by qualification burden — aerospace demands multi-year certification cycles while construction tolerates performance-based specifications without lot-level traceability.
- Aerospace:Primary structures require autoclave-cured thermoset prepregs with fiber volume fractions exceeding 60%, qualified to FAA and EASA damage tolerance protocols. Boeing 787 and Airbus A350 programs anchor demand in Kansas and Hamburg manufacturing corridors.
- Automotive:Battery enclosures and structural members above 50,000 annual units drive thermoplastic tape laying adoption, collapsing cycle times versus thermoset alternatives. BMW Leipzig and Tesla Austin operations specify PEEK and PPS matrix systems for crash-critical components.
- Construction:Glass fiber reinforced polymer rebar and structural profiles substitute for steel in coastal infrastructure, bypassing corrosion inspection regimes. Florida DOT and Netherlands Rijkswaterstaat specify GFRP for bridge deck overlays exposed to de-icing salts.
- Marine:Hull laminates and superstructure panels prioritize blister resistance and osmotic stability, with Mediterranean yacht builders and Louisiana offshore vessel yards driving E-glass multiaxial fabric consumption.
Construction claims the largest absolute tonnage; aerospace commands the steepest value-per-kilogram premium.
End User:
End user categories separate by technical capability — OEMs maintain internal composite engineering teams while distributors carry inventory risk for standardized commodity grades.
- Manufacturers:Tier-one wind blade and airframe producers operate captive prepreg slitting and kitting operations, backward integrating into material handling to control fiber placement automation parameters.
- Contractors:Field application specialists in oil and gas and infrastructure rehabilitation purchase resin and fiber separately, mixing on-site for pipe wrap and column strengthening projects.
- OEMs:Automotive and aviation original equipment manufacturers specify qualified material lists with 3-4 strategic suppliers, mandating blockchain traceability from precursor polymerization through finished component.
- Distributors:Regional stocking locations serve marine repair yards and construction contractors with standardized E-glass roving and woven fabrics, absorbing working capital requirements for commodity grades.
Procurement concentration is tightest among OEMs; distributor networks expand most aggressively in India and Southeast Asia.
Distribution Channel:
Channel selection tracks material complexity — qualified aerospace grades move through direct technical sales while commodity glass fiber tolerates wholesale intermediaries.
- Direct Sales:Technical field engineers from Toray and Hexcel co-develop layup sequences with Boeing and Airbus tier suppliers, embedding within customer facilities for program-specific qualification support.
- Online Retail:Small-batch epoxy resin systems and carbon fiber fabric remnants serve hobbyist drone builders and prototype shops through specialized composites distributors with digital storefronts.
- Wholesale:Glass fiber roving and chopped strand mat move through construction materials wholesalers serving fiberglass tank and boat builders in Turkey and Indonesia.
- Specialty Stores:Marine chandleries and automotive performance retailers stock carbon fiber sheet and vacuum bagging supplies for aftermarket body panel fabrication.
Direct sales capture the highest value-per-transaction; online retail is climbing fastest from a small base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acrylonitrile precursor supply from Japanese petrochemical complexes anchors aerospace-grade carbon fiber qualification chains. German automotive corridors and Chinese wind manufacturing zones absorb the highest composite volumes. Regulatory divergence between EU carbon-border mechanisms and US domestic content bonuses is reshaping supplier access.
United States
Boeing tier-one contracts in Kansas and Washington state drive autoclave-cured thermoset demand for narrow-body programs. FAA material qualification protocols dictate 8-12 hour cure cycles at 180°C. Texas and South Carolina glass fiber melting operations supply wind blade manufacturers qualifying for Inflation Reduction Act production tax credit adders.
Germany
BMW Leipzig and Porsche Zuffenhausen operations specify thermoplastic PEEK matrices for battery enclosures above 50,000 annual units. EU REACH Article 33 disclosure obligations force epoxy hardener chain mapping. Bavaria's automotive supplier corridor concentrates automated fiber placement system adoption.
China
Jiangsu and Guangdong manufacturing zones absorb multi-ton carbon fiber spar cap volumes for 60GW offshore wind targets. MEE environmental inspections raise compliance thresholds for phenolic and epoxy resin formulation plants. GB standards govern domestic qualification protocols diverging from FAA and EASA matrices.
Japan
Toray Industries, Teijin, and Mitsubishi Chemical control 70% of global PAN precursor supply from Chiba and Nagoya petrochemical complexes. METI industrial policy supports acrylonitrile-to-carbon-fiber conversion line scaling. Kansai region melting operations anchor specialty pitch-based fiber output.
India
Bangalore and Hyderabad civil aviation MRO hubs lack qualified composite repair stations, creating first-mover openings for certified prepreg distributors. BIS standards for fiber reinforced polymer rebar are gaining adoption in coastal infrastructure. Gujarat wind energy zones drive E-glass multiaxial fabric consumption.
Fiber Reinforced Polymer Composites (FRP) Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based fiber variants and automated manufacturing equipment. The market structures around three tiers: integrated precursor-to-prepreg operators, regional glass fiber specialists, and thermoplastic system innovators. Competitive moves concentrate on backward integration into acrylonitrile supply and strategic partnerships for wind blade automation.
Among Japanese integrated chemical conglomerates, Toray Industries and Mitsubishi Chemical Group exemplify upstream control over precursor polymerization through qualified aerospace material streams. SGL Carbon occupies a position within the specialty carbon fiber tier serving industrial and automotive applications. These three anchors represent divergent scale strategies: full-chain integration, petrochemical feedstock leverage, and focused carbon conversion specialization.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| SGL Carbon |
| Toray Industries |
| BASF |
| Teijin Limited |
| Hexcel Corporation |
| Solvay |
| Jushi Group |
| Owens Corning |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between aerospace-qualified prepregs and commodity glass fiber products manifests in radically different margin structures and sourcing configurations across the FRP value chain. Premium-tier material streams bundle lot-level blockchain traceability with technical field support, while construction-grade E-glass moves through wholesale intermediaries without pedigree documentation.
Pricing Analysis
Warranty and technical service bundling separates qualified aerospace grades from unbundled commodity offerings. Aerospace prepregs from Toray and Hexcel incorporate on-site qualification support and lot-traceability guarantees within unit pricing, whereas construction glass fiber sells on raw material cost alone. Price differentiation rests on FAA certification tier and fiber volume fraction specifications. Cost compression in wind energy carbon fiber spar caps is intensifying because Chinese offshore installation targets concentrate demand among three domestic suppliers. Tier-one automotive OEMs show lowest price sensitivity due to crash-performance liability exposure; municipal infrastructure contractors remain most price-sensitive.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Charleston anchor hub-and-spoke patterns for qualified aerospace material streams. Supply concentrates in Japan for PAN precursor, China for acrylonitrile conversion and wind blade manufacturing, and Germany for automotive thermoplastic systems. Raw material dependencies include propylene and ammonia feedstocks for precursor polymerization, phenolic and epoxy resin formulations, and specialized sizing chemistries. Single-source vulnerability runs through Japanese precursor concentration where Toray, Teijin, and Mitsubishi Chemical control qualified aerospace supply. Distribution runs through direct technical sales for qualified grades and wholesale intermediaries for commodity construction products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU REACH requalification burdens and blockchain traceability mandates is forcing sub-scale formulators and regional distributors toward exit or acquisition. Smaller players lacking capital for certification infrastructure face margin compression as OEM procurement teams reduce qualified supplier lists.
For Market Incumbents: Anticipate margin erosion from thermoplastic tape laying adoption by securing automated fiber placement partnerships with Boeing and Airbus tier suppliers. Backward integration into acrylonitrile supply through offtake agreements with Chiba and Nagoya petrochemical complexes defends precursor cost position against oil benchmark volatility. Prioritize REACH-compliant anhydride-cured system R&D to capture certification premiums as brominated flame retardants face Article 33 disclosure duties. For New Entrants and Emerging Players: India's civil aviation MRO hubs in Bangalore and Hyderabad present first-mover openings for certified prepreg distributors capable of meeting DGCA repair station qualifications. Hydrogen pressure vessel filament winding for heavy-duty fuel cell trucks offers penetrable white-space as Type IV tank demand converges with automated tow placement. Go-to-market execution should anchor on partnership with German automotive tier suppliers seeking second-source thermoplastic PEEK matrix qualification. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated Japanese chemical conglomerates seeking North American aerospace qualification infrastructure. Long-term viability across the analysis window favors precursor-to-prepreg operators with captive acrylonitrile supply and established FAA certification records. Watch for inflection signals in EU carbon-border adjustment mechanism implementation timelines, which would revalue domestic European prepreg manufacturing assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile Supply | Secures precursor cost position against propylene volatility for qualified aerospace material streams. |
| REACH-Compliant Resin System Qualification | Captures certification premiums as EU Green Deal embodied-carbon rules tighten supplier requirements. |
| Automated Fiber Placement Partnership | Aligns with Boeing and Airbus tier supplier adoption of thermoplastic tape laying for narrow-body programs. |
| India MRO Repair Station Certification | Addresses qualified composite repair capacity gaps in Bangalore and Hyderabad aviation hubs. |
| Hydrogen Pressure Vessel Filament Winding Scale-Up | Positions for Type IV tank demand from heavy-duty fuel cell truck manufacturers. |
Methodological Framework
Multi-period observation of acrylonitrile pricing spreads, wind turbine blade installation rates, and aerospace program delivery schedules anchored the trend analysis, supplemented by interviews with prepreg technical directors, wind blade procurement managers, automotive platform engineers, and FAA certification specialists. Secondary validation drew from customs trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed composite producers, and EASA material qualification bulletins. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the projection horizon.
Segment-weighting approaches modeled fiber type, application qualification burden, end-user technical capability, and regional regulatory cluster divergence. The analytical framework projected volume and value across product type, application, and end-user dimensions over the modeling period. CAGRs derived from regression analysis against named program volumes including Boeing 787 and Airbus A350 delivery schedules, China's offshore wind capacity targets, and German automotive thermoplastic adoption curves.
Revisions become necessary when oil benchmark volatility exceeds historical bands, when FAA-EASA-CAAC qualification harmonization advances or stalls, or when EU carbon-border mechanisms activate ahead of modeled timelines. Forecasts reflect documented assumptions regarding feedstock cost trajectories and program qualification timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
India Construction Ornamental Stone Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Earthen Plasters Market
Building Materials
Cement Board Market
Building Materials
Lightweight Cellular Concrete Market
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Global FRP Rebar Market
Building Materials
Cement Tiles Market
Building Materials
Blended Cement Market
Building Materials
Mass Timber Construction Market
Building Materials
West Africa Cement Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Global White Cement Market
Building Materials
Geocells Market