
 Gravity Retaining Wall Market | 2026-2036
Gravity Retaining Wall Market Size, Share, and Industry Trends Forecast 2026-2036
Gravity Retaining Wall Market Insights
ASTM C1372 qualification for solid concrete interlocking paving units is collapsing the supplier base to producers with certified testing laboratories and documented freeze-thaw performance. Keystone Retaining Wall Systems leverages its national distribution network to sustain project bids across state departments of transportation. Big Block, Inc. anchors its position through proprietary large-format mold technology that reduces installation labor on civil infrastructure sites.
A gravity retaining wall is a freestanding structure that resists lateral earth pressure through its own mass, typically constructed from precast concrete units exceeding 2,000 pounds, quarried stone, or modular block systems with specified minimum compressive strengths of 3,000 psi, and functions primarily to stabilize slopes, create usable grade changes, and protect transportation corridors. Concrete dominates material type selection for highway applications due to predictable engineering properties and long service life, while segmental blocks within construction method categories capture expanding share in residential landscaping because of dry-stack installation speed and reduced equipment requirements. Dry stack methods are maturing in commercial complexes where standardized specifications simplify contractor bidding, whereas modular units represent the fastest-growing construction method segment as municipalities specify them for public infrastructure resilience upgrades.
ASTM International, the Federal Highway Administration, and state-level departments of transportation collectively govern material specifications, installation standards, and project eligibility for gravity retaining wall systems in the United States market. FHWA guidelines for mechanically stabilized earth and gravity structures directly shape contractor procurement decisions and prequalification requirements on federally aided road projects. Stakeholders must monitor evolving state-level resilience codes and stormwater management integration mandates that are redefining wall design height and drainage specifications for public infrastructure bids.
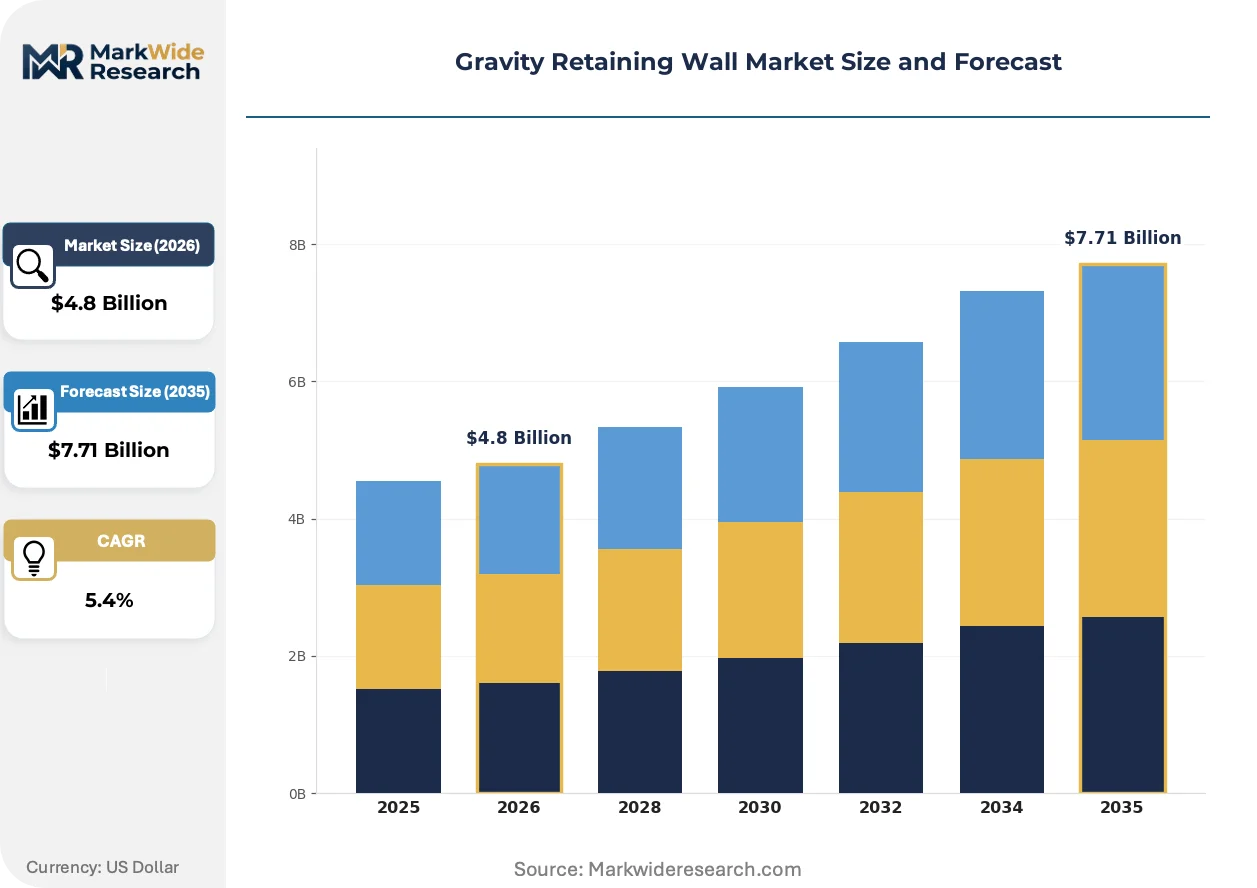
Market Dynamics
ASTM C1372 certification requirements are compressing the supplier base to certified producers with documented freeze-thaw testing, reshaping competitive positioning in highway and commercial segments.
Growth Catalysts
- FHWA Infrastructure Guidelines:Federal Highway Administration standards for mechanically stabilized earth structures are accelerating specification of modular gravity systems on federally aided road projects.
- Southeastern US Coastal Resilience:Storm surge protection mandates in Florida and the Carolinas are driving bulk procurement of large-format precast units for shoreline stabilization.
- Segmental Block Technology:Dry-stack installation methods are reducing equipment requirements and labor hours on suburban commercial developments.
Market Restraints
- Cement Cost Volatility:Input price swings for Portland cement are compressing margins on fixed-price municipal contracts.
- Supplier Concentration Risk:ASTM C1372 laboratory certification requirements have collapsed the qualified producer base to regional testing-capable facilities.
- Mechanically Stabilized Earth Competition:MSE walls with geosynthetic reinforcement are displacing traditional gravity structures in high-load highway applications.
Strategic Opportunities
- IRA-Aligned Resilience Funding:Inflation Reduction Act provisions for climate adaptation infrastructure are opening federal co-financing for coastal protection gravity walls.
- Smart Drainage Integration:Convergence of permeable facing units with subsurface sensor networks is creating premium positioning for stormwater-compliant installations.
- Texas Suburban Expansion:Underpenetrated Dallas-Fort Worth and Houston metro corridors present volume opportunities for residential landscaping segmental systems.
Industry Challenges
- Geotechnical Engineer Scarcity:Licensed soil mechanics specialists with retaining wall design experience are in short supply across state transportation departments.
- ASTM C1372 Certification Timelines:Freeze-thaw durability testing cycles extend supplier qualification periods by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gravity Retaining Wall Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Concrete, Stone, Brick, Asphalt, Timber, Steel Construction Method: Reinforced, Dry Stack, Mortared, Gabion, Segmental Blocks, Modular Units Application: Residential Landscaping, Roadside Embankments, Commercial Complexes, Agricultural Fields, Recreational Parks, Public Infrastructure End User: Contractors, Civil Engineers, Landscape Designers, Municipal Authorities, Property Developers, Environmental Consultants |
| Companies Covered | Stone Strong Systems, Midwest Block and Brick, Cornerstone Wall Solutions, Texas Retaining Systems, York Building Products, Keystone Retaining Wall Systems, Brickworks, Elevate Infrastructure, Big Block, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gravity Retaining Wall Market Trends and Innovations
Material science advances and digital specification tools are fragmenting traditional procurement patterns across transportation and commercial verticals.
Permeable concrete facing units with integrated drainage voids are fragmenting the distinction between structural and stormwater management infrastructure. Municipal engineers in coastal counties are specifying these dual-function systems for resilience projects. The technology is compressing contractor bidding scopes by combining wall and drainage into single pay items.
State departments of transportation are tightening submittal requirements for proprietary retaining wall systems under AASHTO LRFD guidelines. The friction is forcing manufacturers to invest in third-party validation testing before prequalification. Highway contractors in the southeastern United States are responding by consolidating supplier relationships to reduce compliance overhead.
Design-build procurement is displacing traditional design-bid-award sequences on complex civil infrastructure sites. General contractors with in-house geotechnical capability are capturing wall specification authority from consulting engineers. This shift is most visible in Florida DOT alternative delivery projects where single-source accountability reduces interface risk.
Gravity Retaining Wall Market Segmentation
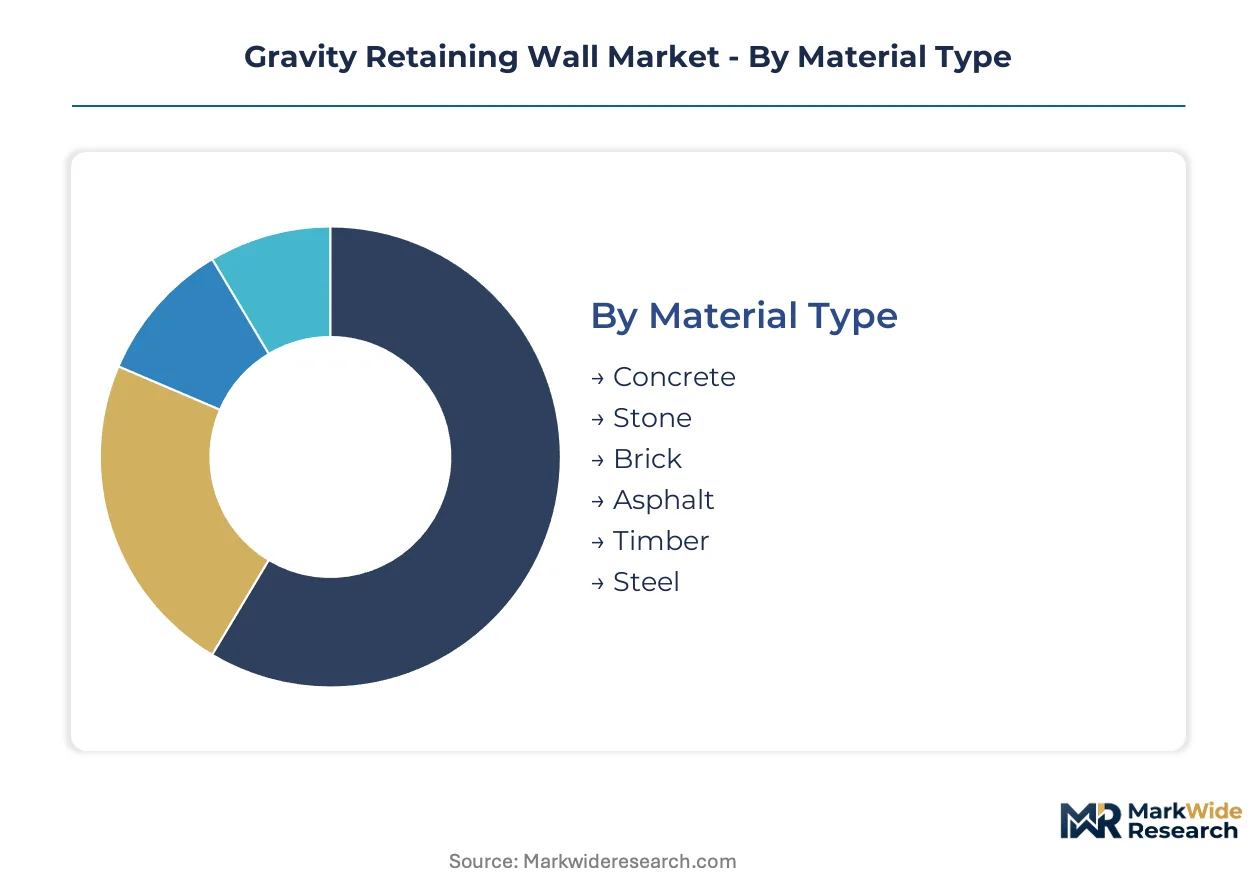
ASTM C1372 certification tiers fragment the supplier base across material categories, while construction method selection determines labor economics and equipment requirements. Specification authority varies sharply by end user, with municipal authorities wielding design control on public infrastructure bids.
Material Type:
FHWA guidelines and state DOT specifications differentiate material eligibility based on compressive strength minimums and freeze-thaw durability documentation.
- Concrete:Precast units with specified 3,000 psi compressive strength dominate highway applications due to predictable engineering properties and documented service life. State departments of transportation in the southeastern United States specify concrete for coastal resilience projects requiring salt-spray resistance.
- Stone:Quarried natural stone retains position in high-aesthetic commercial developments and historic district overlays where architectural review boards mandate traditional materials. Supply concentrates in Pennsylvania and Tennessee quarry districts with rail access to eastern seaboard markets.
- Brick:Fired clay units serve heritage restoration and municipal streetscape projects with strict material continuity requirements.
- Asphalt:Bituminous facing systems appear in temporary roadway applications and rapid-deployment military infrastructure.
- Timber:Pressure-treated wood competes in residential landscaping where homeowners prioritize natural aesthetics over longevity.
- Steel:Sheet pile and bin-type gravity systems deploy in marine bulkhead and heavy industrial applications requiring extreme section modulus.
Established volume favors Concrete; emerging adoption favors Stone in premium commercial segments.
Construction Method:
Installation speed and equipment requirements create three distinct cost tiers that reshape contractor bidding strategies.
- Segmental Blocks:Dry-stack modular units with interlocking geometry eliminate mortar curing time and reduce foundation preparation. Suburban commercial developers in Texas metro corridors specify these systems for accelerated project schedules.
- Modular Units:Large-format precast blocks exceeding 2,000 pounds minimize installation labor on civil infrastructure sites. Florida DOT alternative delivery projects specify modular systems for single-source accountability.
- Reinforced:Steel-reinforced concrete construction maintains position in high-load retaining applications exceeding 20 feet design height.
- Dry Stack:Unmortared stone or block systems serve residential landscaping where equipment access is limited.
- Mortared:Traditional bonded construction persists in historic preservation and architectural wall applications.
- Gabion:Wire-mesh rock cages deploy in erosion control and streambank stabilization projects with irregular foundation conditions.
Contractor procurement concentrates in Segmental Blocks; specification authority is shifting toward Modular Units on public infrastructure bids.
Application:
Stormwater management integration mandates are redefining wall design requirements across verticals.
- Public Infrastructure:Municipal resilience projects combine structural and drainage functions through permeable facing units. Coastal counties in Florida and the Carolinas specify these dual-function systems for storm surge protection.
- Roadside Embankments:FHWA-funded highway expansion programs accelerate procurement of certified segmental block systems. ASTM C1372 qualification requirements compress the supplier base to testing-capable producers.
- Commercial Complexes:Standardized specifications simplify contractor bidding on suburban retail and office park developments.
- Residential Landscaping:Equipment constraints and aesthetic preferences drive specification of dry-stack segmental systems.
- Agricultural Fields:Terrace retention and irrigation channel stabilization utilize lower-cost mortared or gabion construction.
- Recreational Parks:Trail edging and amphitheater construction balance durability with natural material aesthetics.
Funding volume concentrates in Public Infrastructure; design-build procurement is expanding fastest in Roadside Embankments.
End User:
Prequalification requirements and specification authority vary by procurement channel and project delivery method.
- Municipal Authorities:State DOTs and county engineers control material specifications through approved products lists and prequalification registries. AASHTO LRFD guidelines tighten submittal requirements for proprietary systems.
- Contractors:Design-build procurement shifts wall specification authority from consulting engineers to general contractors with in-house geotechnical capability. This consolidation reduces interface risk on complex civil sites.
- Civil Engineers:Licensed soil mechanics specialists retain design authority on traditional design-bid-award projects, though scarcity constrains state transportation departments.
- Property Developers:Commercial real estate sponsors prioritize installation speed and first-cost economics on speculative development.
- Landscape Designers:Residential and park projects emphasize aesthetic integration and plant compatibility.
- Environmental Consultants:Coastal resilience and wetland mitigation projects require specialized expertise in habitat-compatible materials.
Procurement authority concentrates in Municipal Authorities; design influence is migrating fastest toward Contractors under alternative delivery frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure incentives and state-level resilience mandates are redistributing procurement volumes across concentrated construction corridors. Highway expansion programs and coastal protection initiatives dominate public spending patterns.
United States
FHWA-funded road projects and Florida DOT coastal resilience programs drive specification of certified modular systems. ASTM C1372 laboratory requirements compress the supplier base to testing-capable producers. Southeast regional demand concentrates in Florida and the Carolinas where storm surge protection mandates accelerate bulk orders of large-format precast units.
Canada
Provincial highway authorities and municipal stormwater integration mandates expand specification of permeable facing systems. CSA A165.1 standards for concrete block masonry govern material eligibility on public infrastructure bids. Ontario and Quebec transportation departments concentrate procurement authority through approved products registries.
Germany
Federal transport infrastructure programs and state-level flood protection schemes sustain demand for engineered earth retention. DIN 18516 standards for curtain walling and national technical approval certificates regulate system eligibility. Bavaria and North Rhine-Westphalia anchor fabrication capacity through specialized precast concrete operations.
China
National expressway network expansion and sponge city resilience initiatives accelerate procurement of modular block systems. GB standards for concrete masonry units and MIIT construction material regulations govern quality thresholds. Yangtze River Delta municipalities specify dual-function structural-drainage walls for urban flood management.
Australia
State road agencies and coastal council erosion control programs sustain demand for segmental retaining systems. AS 3706 geotextile standards and state-level building codes regulate installation specifications. New South Wales and Queensland concentrate project volume through metropolitan infrastructure corridors and shoreline stabilization schemes.
Gravity Retaining Wall Market Competitive Landscape
Listed leaders compete with private specialists across certification capability and distribution reach. The supplier base compresses toward tiered concentration where ASTM-qualified producers capture highway and municipal segments while regional fabricators serve residential landscaping. Three archetypes dominate: national distributors with laboratory certification, proprietary technology holders with large-format mold systems, and regional block manufacturers with cost-positioned dry-stack offerings. Competitive moves center on consolidation of approved supplier status with state DOTs and backward integration into raw material supply.
Within the certification-driven tier, Keystone Retaining Wall Systems and Big Block, Inc. exemplify divergent scale strategies. Keystone occupies a position anchored in national distribution networks that sustain multi-state transportation department relationships. Big Block, Inc. represents proprietary technology specialization through large-format mold capabilities that reduce field installation labor. Midwest Block and Brick sits within the regional fabricator archetype, serving cost-sensitive commercial and residential segments through standardized dry-stack product lines. These three patterns illustrate how ASTM C1372 compliance requirements reshape competitive positioning across public and private procurement channels.
| Leading Market Players |
|---|
| Stone Strong Systems |
| Midwest Block and Brick |
| Cornerstone Wall Solutions |
| Texas Retaining Systems |
| York Building Products |
| Keystone Retaining Wall Systems |
| Brickworks |
| Elevate Infrastructure |
| Big Block, Inc. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at regional precast concrete plants determines price floors for ASTM C1372-certified gravity wall units, compressing margins for uncertified producers while concentrating procurement authority with testing-capable facilities in the southeastern United States. Scale economies in large-format mold technology anchor competitive positioning across highway and commercial segments.
Pricing Analysis
Certification level creates the primary spread between premium ASTM C1372-qualified producers and uncertified regional fabricators. Three-tier pricing structure across certified premium, compliant standard, and non-certified economy levels segments buyer access. Price differentiation hinges on documented freeze-thaw performance and state DOT prequalification status. Cost compression in economy tiers is intensifying because cement input volatility squeezes fixed-price municipal contracts. Residential landscaping contractors exhibit highest price sensitivity, while state transportation departments prioritize certification compliance over unit cost.
Supply Chain Analysis
Inventory lead times for certified concrete masonry units extend 12-18 months due to freeze-thaw testing cycles, constraining rapid supplier qualification. Geographic supply concentrates in the United States, Canada, and Germany where precast fabrication capacity clusters near transportation corridors. Raw material dependencies center on Portland cement, steel reinforcement, and specialized mold aggregates. Single-source vulnerability runs through regional laboratory certification bottlenecks. Distribution runs through state DOT approved-products registries and national distributor networks serving multi-state contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gravity retaining wall procurement is shifting toward platform-economics dynamics where ASTM C1372 certification interoperability determines supplier eligibility across state transportation networks. Design-build delivery consolidation accelerates this ecosystem centralization.
For Market Incumbents: Consolidate approved-supplier status with Florida DOT and Texas DOT through accelerated laboratory certification investments. Deepen backward integration into captive cement supply to defend margin position against input cost volatility. Lock in exclusive distribution agreements with national highway contractors to preempt MSE wall displacement in high-load applications.
For New Entrants and Emerging Players: ASTM C1372 fast-track partnerships with existing certified laboratories compress qualification timelines for market entry. Target Texas suburban expansion corridors where residential landscaping segmental systems remain underpenetrated. Pursue design-build general contractor relationships as the primary go-to-market channel, bypassing traditional consulting engineer specification authority.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional fabricators with state DOT prequalification and established maintenance-contract backlogs. Five-to-ten year viability favors certified producers with proprietary large-format mold technology and coastal resilience project exposure. Monitor Inflation Reduction Act resilience funding disbursement velocity as the critical inflection signal for volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ASTM C1372 Laboratory Certification | State DOT prequalification locks in highway procurement eligibility for certified producers. |
| Large-Format Mold Technology Investment | Proprietary casting systems reduce field labor hours on Florida DOT alternative delivery projects. |
| Permeable Facing Unit Development | Dual-function structural-drainage walls capture stormwater-compliant premium positioning in coastal counties. |
| Design-Build Contractor Partnerships | Direct relationships with general contractors bypass traditional consulting engineer specification control. |
| Backward Integration into Cement Supply | In-house Portland cement sourcing insulates margins from commodity price volatility on fixed-price contracts. |
Research Methodology
Cross-validation between primary interviews with state DOT materials engineers and secondary analysis of FHWA infrastructure guidelines anchors the qualitative findings. Conversations with segmental block manufacturers, geotechnical contractors, and municipal procurement officers combined with ASTM International certification databases, state transportation department approved-products registries, and AASHTO LRFD guideline documents. Bottom-up project pipeline tracking and top-down federal funding allocation analysis triangulate volume estimates.
Sensitivity analysis across material cost, certification timeline, and design-build adoption scenarios frames projection uncertainty. Segmentation dimensions modeled include material type, construction method, application vertical, and end-user procurement channel across the analysis window. CAGRs derive from weighted average of historical state DOT expenditure patterns and federal infrastructure incentive trajectories. Forecast inputs incorporate cement price volatility indices and coastal resilience mandate adoption curves.
Decision-makers should treat outputs as directional under sustained federal highway funding and ASTM C1372 enforcement continuity; material deviation in either would warrant model refresh. Specific risk factors include MSE wall technology substitution in high-load applications and geotechnical engineer scarcity constraining design capacity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Europe Exterior Sheathing Market
Building Materials
Foam Bricks Market
Building Materials
Steel Products Market
Building Materials
Acoustic Damping Tiles Market
Building Materials
Dry Mix Mortar Market
Building Materials
Europe Concrete Admixtures Market
Building Materials
Drywall Joint Tape Market
Building Materials
North America Architectural Coatings Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Fiber Reinforced Polymer (FRP) Rebars Market
Building Materials
Block Paving Market
Building Materials
HDG Steel Pipe Market
Building Materials
Timber Frames Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Asia-Pacific Cement Market