
 Global Aggregates Market | 2026-2036
Global Aggregates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aggregates Market Foresight
Digital quarry management and automated crushing control is tilting capital deployment toward sensor-driven optimization and predictive maintenance systems. Holcim Limited leverages its integrated software platforms to synchronize extraction scheduling with real-time logistics across multiple continents. CRH plc anchors its competitiveness through deep backward integration into cement and asphalt, capturing margin pools that standalone aggregate producers cannot access. Heidelberg Materials AG differentiates through intensive R&D in carbon capture applications tied to limestone processing, positioning its aggregate operations within broader decarbonization roadmaps.
Aggregates are granular mineral materials—crushed stone, sand, gravel, or recycled construction debris—typically processed to specific gradations ranging from fines to coarse particles exceeding 75 mm, serving as the foundational load-bearing matrix in concrete, asphalt, and engineered fill applications. Crushed stone dominates value capture due to its structural performance in high-specification concrete and road base layers, while manufactured sand is displacing river sand in markets where dredging bans have constricted natural supply. Recycled aggregates occupy a narrow but expanding niche where landfill diversion mandates and proximity to demolition sites create localized cost advantages over virgin material.
The US EPA enforces stormwater discharge permits under the Clean Water Act that constrain quarry runoff and sediment release, directly shaping site permitting timelines and operational compliance costs. China's MEE implements dual carbon goals that tighten energy intensity standards for limestone calcination and crushing operations, while the EU Green Deal's embodied carbon thresholds are filtering into national building codes through ECHA-aligned product declarations. Stakeholders must monitor how regulatory divergence in carbon accounting methodologies affects cross-border material certification and project eligibility for public procurement contracts.
Market Dynamics
Carbon accounting mandates embedded in public procurement codes are restructuring competitive advantage toward producers with verified low-carbon supply chains, forcing capital reallocation into electrified processing and alternative binder development.
Growth Catalysts
- India's Bharatmala highway program:National road expansion consumes record volumes of crushed stone and manufactured sand, pulling material from Rajasthan and Madhya Pradesh quarries into active construction corridors.
- EU Green Deal embodied carbon thresholds:Building code alignment through ECHA-aligned product declarations creates preferential market access for certified low-carbon aggregate suppliers in German and French public tenders.
- Sensor-driven quarry automation:Predictive maintenance systems and real-time crushing control reduce downtime and energy intensity, improving unit economics for mid-scale operators.
Market Restraints
- Diesel fuel cost volatility:Haulage operations remain diesel-dependent, exposing margins to energy price swings that electrified transport cannot yet offset at scale.
- River sand dredging bans:Vietnam, Indonesia, and Malaysia have prohibited or restricted natural sand extraction, constricting supply and forcing rapid manufactured sand capacity buildouts with higher capital requirements.
- Limestone deposit depletion:Premium-quality carbonate reserves near major demand centers in Italy and Spain face exhaustion, lengthening haul distances and raising delivered costs.
Strategic Opportunities
- Urban demolition waste streams:Sao Paulo and Mexico City generate sufficient concrete debris to support scaled recycled aggregate plants, creating localized cost advantages over virgin material where landfill diversion mandates apply.
- Carbon capture integration:Limestone processing facilities can retrofit post-combustion capture systems, generating carbon credits that offset compliance costs under emerging cap-and-trade regimes.
- Geopolymer binder convergence:Alkali-activated materials reduce clinker demand in concrete formulations, opening aggregate supply contracts to new industrial buyers outside traditional ready-mix channels.
Industry Challenges
- Automation engineering talent scarcity:Quarry operators struggle to recruit and retain technicians capable of maintaining sensor networks and automated crushing control systems.
- Extended environmental permitting timelines:US EPA Clean Water Act stormwater discharge reviews and state-level air quality assessments stretch greenfield quarry approvals across multi-year horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aggregates Market |
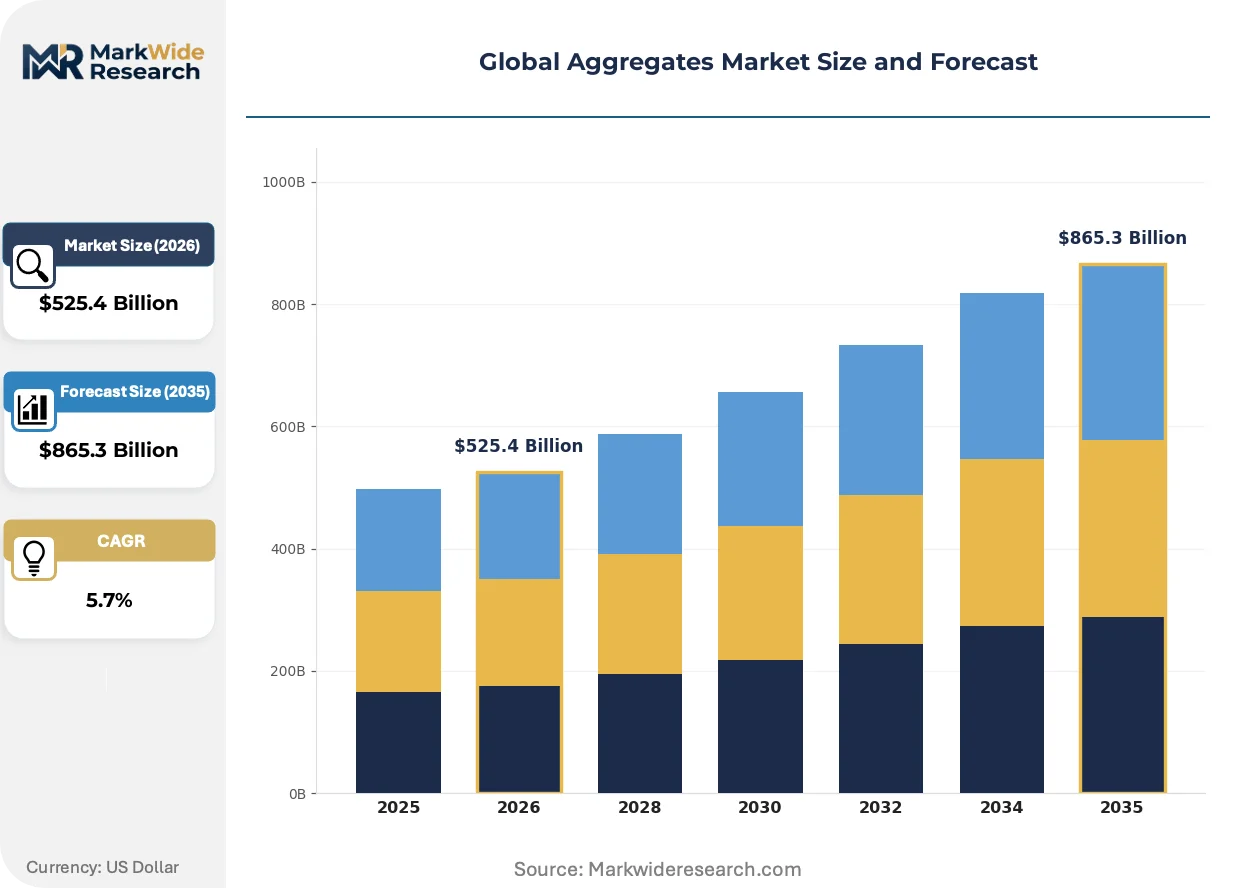
| Market Size in 2026 | $525.4 Billion |
| Market Size in 2035 | $865.3 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushed Stone, Sand, Gravel, Recycled Aggregates, Manufactured Sand Application: Construction Concrete, Road Base, Asphalt, Railway Ballast, Drainage Systems End User: Infrastructure Developers, Building Contractors, Precast Manufacturers, Landscaping Companies Distribution Channel: Direct Sales, Dealers & Distributors, Online Platforms, Wholesalers, Retail Outlets |
| Companies Covered | Holcim Limited, CRH plc, Heidelberg Materials AG, CEMEX S.A.B. de C.V., Vulcan Materials Company, Martin Marietta Materials, China Resources Cement Holdings Limited, EUROCEMENT Group, LSR Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aggregates Market Shifts & Advancements
Processing technology and regulatory measurement protocols are converging to compress the carbon intensity of aggregate supply, while procurement patterns shift toward verified chain-of-custody documentation.
Electrified mobile crushing and screening equipment is collapsing the diesel fuel exposure that historically dominated quarry operating costs. Scandinavian contractors are deploying battery-electric units in urban extraction sites where emissions restrictions are tightest. This transition compresses the total cost gap between electrified and conventional equipment, accelerating fleet replacement cycles.
China's MEE dual carbon goals tighten energy intensity standards for limestone calcination and crushing operations, forcing producers to document fuel switching and efficiency upgrades. Compliance documentation now feeds directly into provincial carbon trading registries. Export-oriented suppliers face parallel pressure from EU CBAM border adjustments on embodied carbon.
Buyer certification requirements are fragmenting procurement patterns across public infrastructure tenders. State transportation departments in Texas and California now mandate EPD-verified environmental product declarations for aggregate suppliers, displacing price-only award criteria. This behavioral shift concentrates contract awards among producers with established LCA documentation capabilities, marginalizing smaller uncertified competitors.
Global Aggregates Market Segmentation
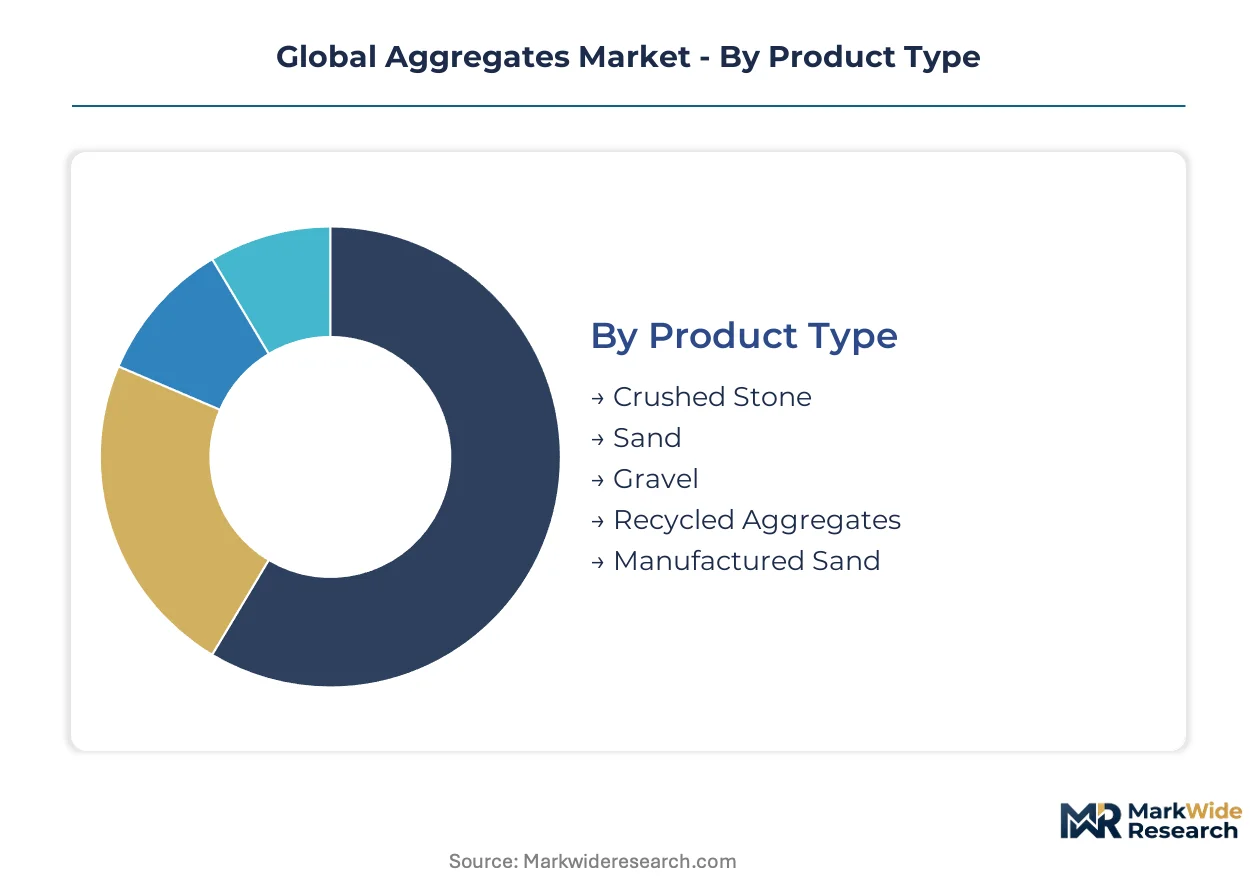
Aggregate producers face divergent margin pressures across product grades and delivery channels. Construction specifications dictate gradation requirements that fragment procurement patterns by end-use intensity.
Product Type:
Use-case spectrum spans structural load-bearing applications through engineered fill and drainage layers.
- Crushed Stone:Hard rock fragmentation produces angular particles with superior interlock strength for high-specification concrete and road base. India's Bharatmala highway program pulls premium carbonate feedstock from Rajasthan quarries into active construction corridors.
- Sand:Natural alluvial deposits and processed fines serve as the binder matrix in mortar and concrete formulations. Vietnam's dredging bans have constricted river sand supply, forcing rapid manufactured sand capacity buildouts with higher capital intensity.
- Gravel:Rounded alluvial particles from glacial or fluvial deposits suit drainage and landscaping applications with lower structural demands.
- Recycled Aggregates:Crushed concrete and asphalt debris from demolition sites divert landfill waste into secondary construction feedstock.
- Manufactured Sand:Vertical shaft impact crushing of hard rock generates cubical particles with controlled fines content for concrete substitution.
The dominant share belongs to Crushed Stone, while Manufactured Sand is closing the gap fastest.
Application:
Volume concentration tracks infrastructure investment cycles and building code specifications across geographies.
- Construction Concrete:Ready-mix and precast applications demand tightly graded aggregates with low alkali-silica reactivity for structural durability.
- Road Base:Unbound and cement-stabilized layers require crushed stone with specific California Bearing Ratio values for load distribution.
- Asphalt:Hot mix and warm mix formulations specify aggregate angularity and polish resistance for skid performance.
- Railway Ballast:High-specification crushed stone with uniform gradation and fracture toughness stabilizes track geometry under dynamic loading.
- Drainage Systems:Open-graded aggregates provide permeable subbase and filtration functions in stormwater management infrastructure.
Construction Concrete commands the largest volume share, though Road Base applications are expanding most quickly in Southeast Asian markets.
End User:
Procurement scale and specification stringency separate national infrastructure programs from dispersed commercial construction.
- Infrastructure Developers:State highway authorities and rail corporations issue bulk tenders with certified environmental product declaration requirements.
- Building Contractors:Commercial and residential general contractors source aggregates through ready-mix suppliers or direct quarry contracts.
- Precast Manufacturers:Standardized concrete element producers maintain captive aggregate inventories for continuous production scheduling.
- Landscaping Companies:Decorative and drainage aggregate demand concentrates in urban renovation and green infrastructure projects.
Infrastructure Developers absorb the greatest tonnage, while Precast Manufacturers are scaling fastest as offsite construction gains share.
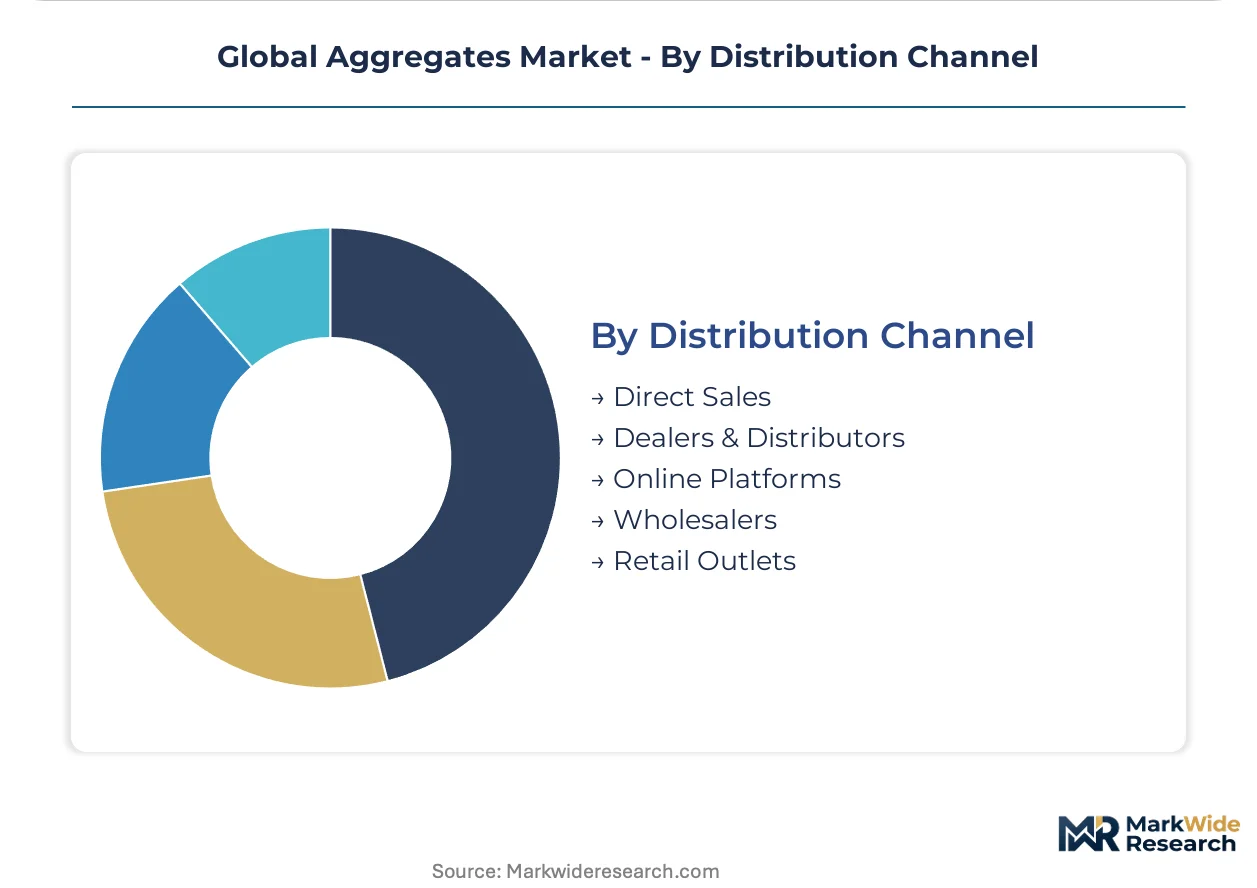
Distribution Channel:
Logistics configuration determines delivered cost competitiveness across haul distance and load consolidation economics.
- Direct Sales:Quarry operators contract directly with major infrastructure projects and ready-mix plants for dedicated supply agreements.
- Dealers & Distributors:Regional material yards stock multiple product grades for contractor pickup and short-haul delivery.
- Online Platforms:Digital procurement portals aggregate spot demand with real-time pricing for smaller construction firms.
- Wholesalers:Bulk intermediaries consolidate rail and barge shipments for redistribution to secondary markets.
- Retail Outlets:Bagged and small-lot sales serve residential and light commercial maintenance applications.
Direct Sales retains the dominant volume position, yet Online Platforms are gaining transaction share fastest among mid-scale contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian quarries supply crushed stone to Southeast Asian highway contractors facing domestic dredging bans. Brazil's limestone processors export manufactured sand to Caribbean construction markets. German aggregate certification standards now govern material eligibility for Dutch and Belgian public tenders.
United States
Texas and California transportation departments mandate EPD-verified environmental product declarations for aggregate suppliers. The EPA enforces Clean Water Act stormwater discharge permits that constrain quarry runoff and stretch permitting timelines. Vulcan Materials and Martin Marietta operate extensive quarry networks across the Southeast and Southwest, supplying asphalt and concrete producers.
China
National highway expansion and urban metro buildouts in the Yangtze River Delta consume record volumes of limestone and manufactured sand. The MEE implements dual carbon goals that tighten energy intensity standards for crushing operations and feed compliance data into provincial carbon trading registries. China Resources Cement Holdings maintains integrated quarry-to-concrete operations across Guangdong and Fujian provinces.
Germany
The EU Green Deal's embodied carbon thresholds filter into federal building codes through ECHA-aligned product declarations. Heidelberg Materials operates limestone processing facilities with carbon capture integration in the North Rhine-Westphalia industrial corridor. Bavarian quarries supply certified low-carbon aggregate for French and Dutch infrastructure tenders.
India
The Bharatmala highway program pulls premium carbonate feedstock from Rajasthan and Madhya Pradesh quarries into active construction corridors. State-level mining departments enforce progressive closure plans and rehabilitation bonds for greenfield quarry approvals. Mumbai and Delhi metro expansion projects source manufactured sand from Gujarat and Haryana crushing plants.
Brazil
Sao Paulo generates sufficient concrete demolition debris to support scaled recycled aggregate plants with localized cost advantages. ANVISA-aligned environmental licensing processes govern quarry expansion in Minas Gerais limestone belts. CEMEX operates integrated aggregate and ready-mix networks serving Southeast Brazil infrastructure projects.
Global Aggregates Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. The market structure tilts toward consolidated integrated producers with captive cement and asphalt operations, while mid-scale independent quarries defend position through geographic niche concentration. Three archetypes dominate: vertically integrated building materials conglomerates, standalone aggregate specialists with logistics scale, and recycled material processors exploiting urban demolition proximity. Competitive moves concentrate on M&A for reserve acquisition and electrified fleet deployment for emissions compliance.
Among Swiss and Irish building materials conglomerates, Holcim Limited and CRH plc exemplify the integrated archetype with multi-continent quarry networks and software-driven logistics coordination. Heidelberg Materials AG anchors the German industrial complex with carbon capture R&D positioning. These three represent the tier where backward integration into cement and asphalt captures margin pools unavailable to standalone producers.
| Leading Market Players |
|---|
| Holcim Limited |
| CRH plc |
| Heidelberg Materials AG |
| CEMEX S.A.B. de C.V. |
| Vulcan Materials Company |
| Martin Marietta Materials |
| China Resources Cement Holdings Limited |
| EUROCEMENT Group |
| LSR Group |
| Others |
Supply & Pricing Matrix
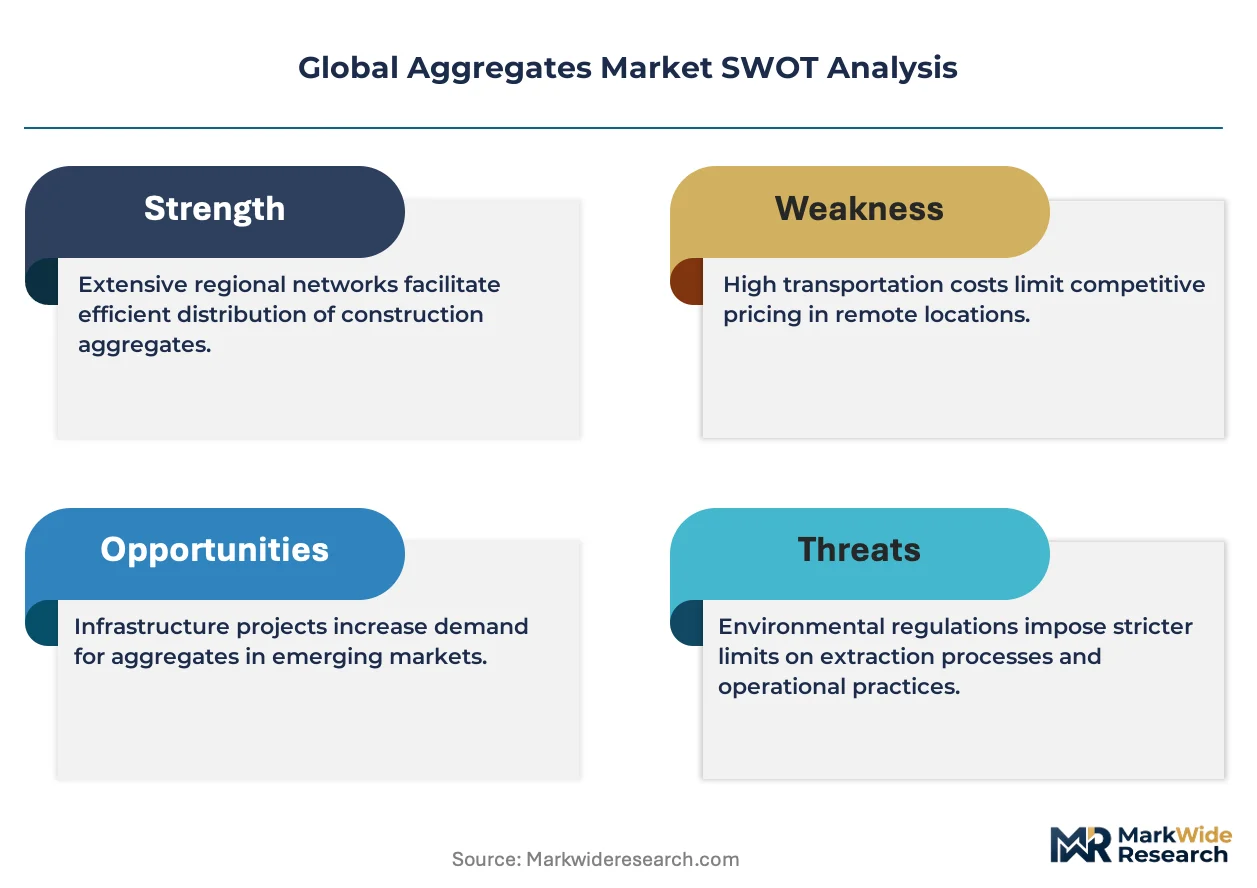
Rajasthan's carbonate quarry clusters in India anchor regional pricing power through their dominance of Bharatmala highway feedstock supply, with capacity utilization rates directly transmitting into spot market premiums for crushed stone delivered to Mumbai and Delhi construction corridors.
Pricing Analysis
Cost-plus contracts indexed to diesel fuel benchmarks govern long-term offtake agreements between Rajasthan quarries and national infrastructure developers. Price differentiation rests on EPD certification status and haul distance to demand centers, with certified low-carbon material commanding premiums in EU-linked procurement channels. Pricing pressure stems from manufactured sand capacity buildouts in Gujarat and Haryana compressing margins on natural river sand substitutes. Small-scale contractors exhibit highest price sensitivity, while state highway authorities prioritize specification compliance over unit cost.
Supply Chain Analysis
Upstream limestone and hard rock feedstock draws from India, China, and Vietnam, with quality stratification determining end-use eligibility for structural concrete versus road base applications. Key inputs span drilling consumables, crushing wear parts, and bitumen for coated aggregate production. Supply chain risk centers on single-source vulnerability for premium carbonate reserves near exhausted Italian and Spanish deposits. Distribution runs through direct quarry-to-project contracts for bulk infrastructure, with dealer networks handling fragmented contractor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and regional supply deficits creates niche entry points, as embodied carbon mandates split procurement pools between verified low-carbon suppliers and conventional producers.
For Market Incumbents: Pre-empt margin erosion from electrified fleet operators by securing captive renewable energy contracts for crushing operations and accelerating EPD documentation across quarry networks. Backward integration into rail and barge logistics anchors delivered cost competitiveness against emerging regional challengers. Carbon capture retrofits at limestone processing facilities generate compliance offsets that price-sensitive competitors cannot replicate. For New Entrants and Emerging Players: Southeast Asian markets facing dredging bans present the most penetrable white space, with Vietnam and Indonesia importing manufactured sand capacity faster than domestic buildout permits allow. Target urban demolition waste streams in Sao Paulo and Mexico City where landfill diversion mandates create localized feedstock cost advantages. Lead with recycled aggregate certification to bypass virgin material permitting timelines that stretch greenfield quarry approvals. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-automated quarry operators with predictive maintenance capabilities and real-time logistics coordination software. Long-term viability hinges on electrified fleet transition completion and carbon credit generation potential under expanding cap-and-trade regimes. Monitor EU CBAM border adjustment implementation as the inflection signal for low-carbon supply chain investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Fleet Deployment | Battery-electric crushing equipment collapses diesel cost exposure in urban extraction sites facing emissions restrictions. |
| Carbon Capture Retrofit | Post-combustion systems at limestone processors generate tradable credits under EU ETS and emerging Asian cap-and-trade schemes. |
| EPD Certification Investment | Environmental product declarations unlock German and French public tender eligibility that price-only competitors cannot access. |
| Recycled Aggregate Scale-Up | Urban demolition debris processing in Sao Paulo and Mexico City diverts landfill waste into cost-competitive secondary feedstock. |
| Sensor Automation Integration | Predictive maintenance networks reduce crushing downtime and energy intensity, improving unit economics for mid-scale operators. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with quarry operations managers, infrastructure procurement officers, and environmental compliance leads, alongside secondary validation through customs trade data, national mining department production statistics, and EU ECHA product declaration registries. Bottom-up volume estimates triangulated against top-down infrastructure investment pipeline assessments.
Forecast inputs considered product type segmentation across crushed stone, manufactured sand, and recycled aggregates; application intensity across concrete, road base, and railway ballast; and regional regulatory cluster divergence in carbon accounting methodologies. CAGRs derived from elasticity modeling against public infrastructure budget trajectories and construction sector output indices, with specific weighting applied to India's Bharatmala program execution pace and EU Green Deal procurement code adoption timelines.
Practitioners should monitor diesel price volatility, permitting timeline extensions under EPA Clean Water Act reviews, and EU CBAM implementation scope for early signals of forecast deviation. Quarterly review of provincial carbon trading registry inflows, EPD certification issuance rates, and electrified equipment order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
Plastic Decking Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
Wood House Frame Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
Rubble Sacks Market
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
Windows and Doors Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Sandwich Panel System Market