
 Foam Bricks Market | 2026-2036
Foam Bricks Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Bricks Market Foresight
Aftermarket refurbishment of existing building envelopes is reshaping margin distribution in the Foam Bricks Market. General Shale leverages its Appalachian manufacturing footprint to supply replacement insulation for aging commercial stock. LONTTO Group anchors its position through integrated equipment-to-material systems serving modular housing factories. Cherokee Brick differentiates via fire-rated phenolic formulations targeting infrastructure developers.
Foam bricks are rigid cellular polymer blocks manufactured through expansion molding of polystyrene, polyurethane, or polyisocyanurate resins, with densities ranging from 15 to 50 kg/m³ and thermal conductivity values below 0.035 W/m·K, engineered primarily to reduce heat transfer in building envelopes while minimizing structural dead load. Polystyrene blocks dominate volume due to cost scalability in residential applications, while polyisocyanurate panels command premium positioning in commercial construction where stringent thermal bridging requirements apply. Phenolic foam sheets represent the fastest-expanding product form for fireproofing in high-rise infrastructure, though polyethylene custom molded shapes retain niche utility in acoustic insulation for modular housing.
EPA regulations on hydrofluorocarbon blowing agents and REACH restrictions on flame retardant chemistries are compressing formulation flexibility for US and European producers, while India's BIS certification mandates for thermal insulation materials are creating compliance barriers for imported foam brick systems. China's GB standards on building energy efficiency and Saudi Arabia's SFDA fire safety protocols for construction materials are similarly tightening product specification requirements across major supply corridors. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned certification investments.
Market Dynamics
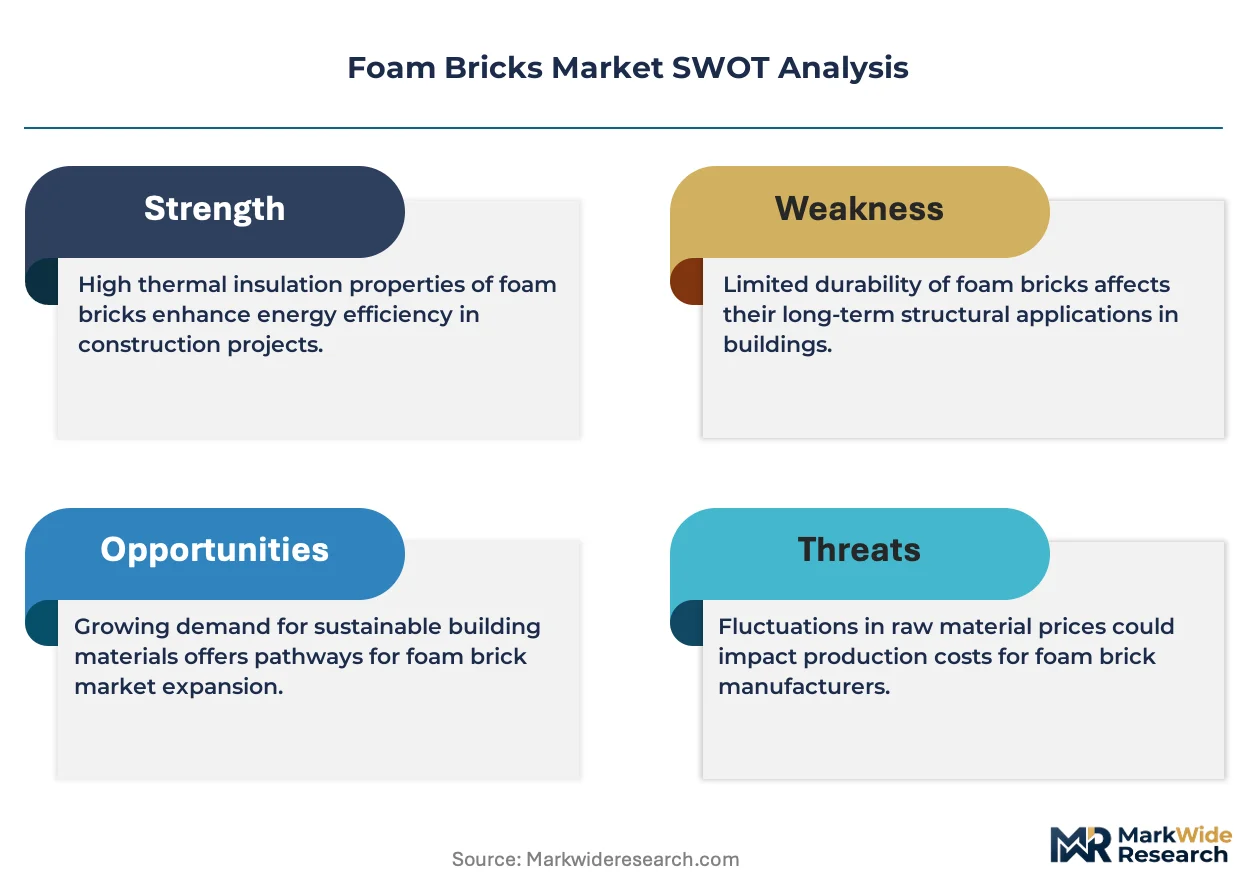
The EU Green Deal's tightened building energy codes are compressing formulation flexibility while accelerating material substitution toward high-performance insulation across residential and commercial envelopes. This regulatory pressure is redistributing margin pools from commodity polystyrene blocks toward fire-rated phenolic systems and polyisocyanurate panels.
Growth Catalysts
- Passive house mandates:Germany's building codes now require thermal conductivity below 0.035 W/m·K for envelope materials, pulling foam bricks into new construction and deep retrofit pipelines.
- REACH flame retardant restrictions:The phasedown of legacy halogenated chemistries is forcing reformulation investments that favor phenolic and polyisocyanurate chemistries with inherent fire resistance.
- Modular construction scaling:India's affordable housing segment is concentrating demand for lightweight, thermally efficient wall systems that reduce crane capacity requirements on tight urban sites.
Market Restraints
- HFC blowing agent phaseout:EPA regulations under the AIM Act are constraining polystyrene expansion processes, elevating capital costs for US-based extrusion lines.
- Raw material concentration:Benzene and styrene monomer supply clusters in the US Gulf Coast and Rotterdam create input cost volatility that compresses margin predictability for mid-scale molders.
- Mineral wool substitution:Stone wool and glass wool insulation are capturing specification share in commercial high-rises where fire rating requirements exceed foam brick capabilities without costly intumescent coatings.
Strategic Opportunities
- Deep energy retrofit pipelines:Aging commercial stock in Germany and France requires envelope replacement at scale, opening aftermarket refurbishment channels distinct from new construction cycles.
- Integrated equipment-to-material systems:Convergence of CNC cutting equipment with just-in-time foam brick supply is enabling modular housing factories to reduce on-site waste and labor hours.
- India's BIS certification barriers:Domestic thermal insulation mandates are creating protected market space for local manufacturers with certified testing infrastructure.
Industry Challenges
- Formulation chemistry expertise gap:The transition from HFC to hydrocarbon and CO2 blowing agents requires process engineering skills scarce among legacy polystyrene molders.
- Multi-jurisdiction certification timelines:Divergent fire safety protocols between Saudi Arabia's SFDA, China's GB standards, and EU CPR compliance are extending product launch cycles by 18-24 months.
- Legacy building integration complexity:Retrofit applications demand custom cutting and thermal bridge mitigation that standard block dimensions cannot address without field modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Bricks Market |
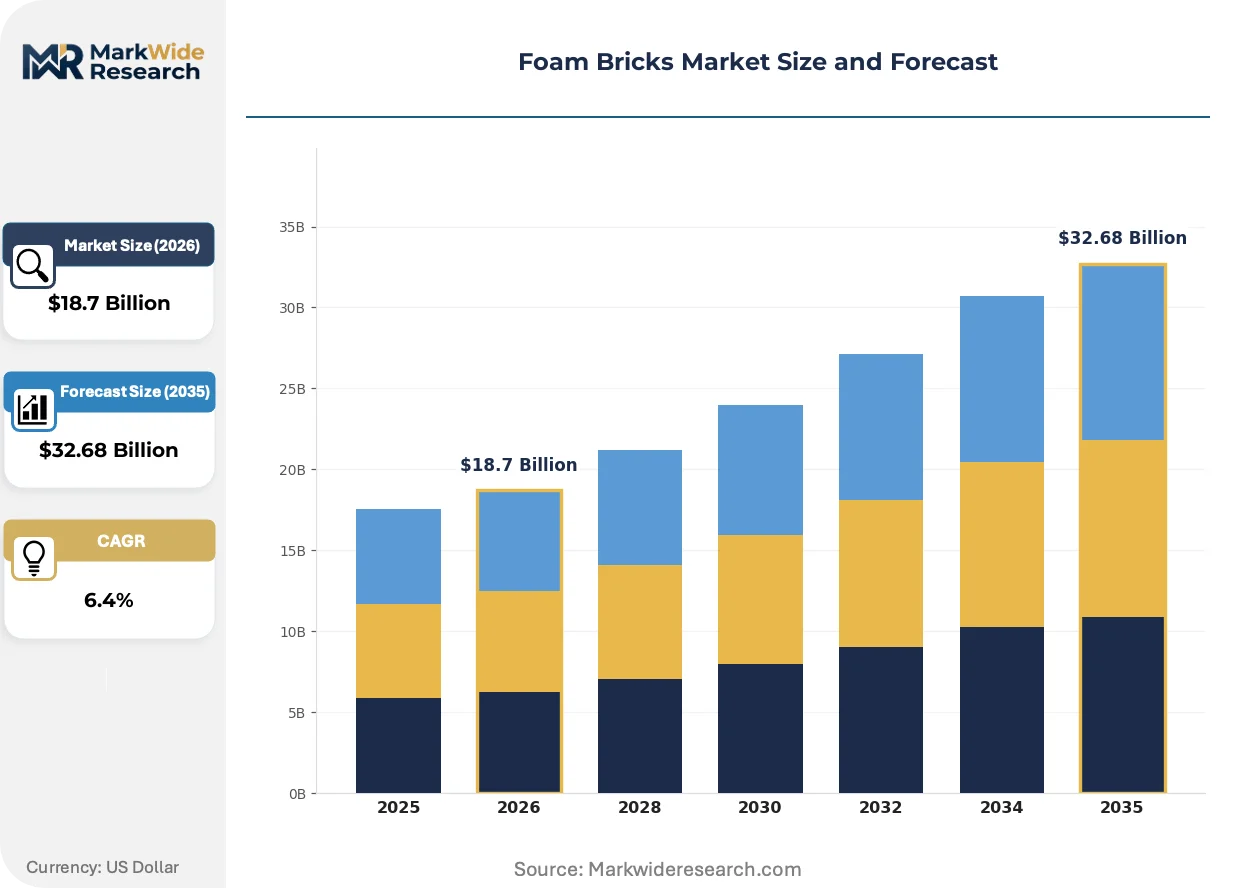
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polystyrene, Polyurethane, Polyethylene, Phenolic, Polyisocyanurate Application: Thermal Insulation, Acoustic Insulation, Lightweight Construction, Fireproofing End User Industry: Commercial Construction, Residential Builders, Infrastructure Developers, Modular Housing Product Form: Blocks, Sheets, Panels, Custom Molded, Laminated |
| Companies Covered | Triangle Brick Company, Riverside Brick & Supply Company, Yankee Hill Brick, Cherokee Brick, Glen-Gery, Bilco Corporation, General Shale, LONTTO Group, Hebron Brick, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Bricks Market Shifts & Advancements
Digital fabrication and regulatory chemistry shifts are restructuring how foam bricks are specified, produced, and installed across building typologies. These forces are compressing traditional supply chain margins while opening new service-based revenue pools.
Building information modeling is digitizing thermal envelope design workflows, enabling architects to simulate heat flow through foam brick assemblies before procurement. General contractors in Germany and the Netherlands are mandating BIM-compatible material libraries, forcing manufacturers to supply thermal performance data in standardized digital formats. This interoperability requirement is digitizing what had been opaque specification processes dominated by regional distributors.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon blowing agents is restructuring polystyrene production economics across European extrusion capacity. Manufacturers are retooling lines for pentane or CO2 expansion, elevating capital intensity and favoring larger integrated producers with captive chemical processing. Small and mid-scale molders without backward integration into polymer production are exiting or consolidating.
Buyers in India's affordable housing segment are consolidating procurement through integrated modular construction platforms that bundle design, material supply, and installation. This channel compression is displacing traditional distributor networks that historically captured 15-20 percent margin on foam brick sales. LONTTO Group and similar equipment-to-material integrators are capturing this consolidated demand through factory-direct relationships with housing developers in Maharashtra and Karnataka.
Foam Bricks Market Segmentation
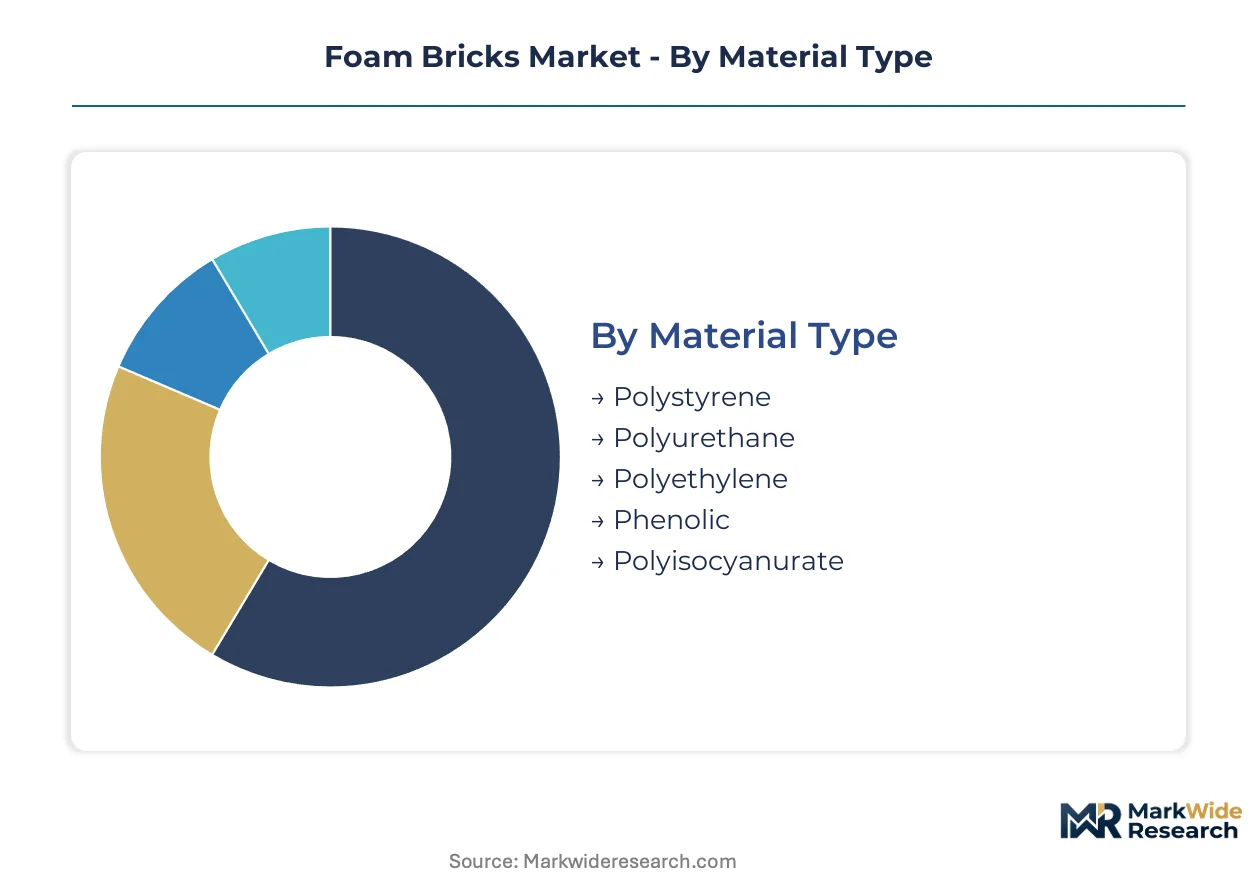
Segmentation in foam bricks reveals how material chemistry, application requirements, and product geometry create distinct competitive arenas with divergent margin profiles. Understanding these boundaries helps stakeholders allocate R&D and certification investments toward segments where regulatory pressure and construction methodology shifts are concentrating value capture.
Material Type:
The maturity spectrum spans from commodity polystyrene blocks with decades of production history to emerging phenolic formulations engineered for fire resistance.
- Polystyrene:Expanded and extruded polystyrene blocks dominate residential volume due to cost scalability and established supply chains. Demand concentrates in Germany's passive house new construction where thermal conductivity below 0.035 W/m·K is mandatory, though EPA AIM Act restrictions on HFC blowing agents are elevating capital requirements for US extrusion lines.
- Polyisocyanurate:Closed-cell polyisocyanurate panels command premium positioning through superior thermal resistance and dimensional stability. Commercial construction in France and the Netherlands specifies these for stringent thermal bridging requirements, with ECHA REACH flame retardant restrictions favoring their inherent fire resistance over halogenated alternatives.
- Phenolic:Rigid phenolic foam delivers the lowest thermal conductivity among organic insulants with exceptional fire performance. Infrastructure developers in Saudi Arabia specify phenolic under SFDA protocols for high-rise fire safety.
- Polyurethane:Spray and pour polyurethane systems offer seamless envelope continuity for complex geometries. Custom residential applications in India's affordable housing segment utilize polyurethane for modular wall assemblies.
- Polyethylene:Cross-linked polyethylene foam provides acoustic damping and moisture resistance. Niche demand centers on modular housing factories requiring vibration isolation for precision assembly lines.
Polystyrene handles the majority of throughput; phenolic is the fastest mover on share.
Application:
Cost tier differentiation separates specification-driven thermal performance from code-minimum compliance categories.
- Thermal Insulation:The core value proposition of foam bricks centers on reducing heat transfer through building envelopes. Residential builders in Germany and commercial developers in France prioritize thermal performance metrics, with EU Green Deal energy codes compressing demand toward high-conductivity materials.
- Fireproofing:Phenolic and intumescent-coated polyisocyanurate systems address high-rise infrastructure requirements. Saudi Arabia's SFDA and China's GB standards mandate fire-rated envelope materials, creating protected specification channels for compliant formulations.
- Acoustic Insulation:Open-cell polyethylene and specialized polyurethane foams absorb airborne and impact sound. Modular housing factories in Maharashtra deploy acoustic foam bricks to meet residential noise transmission standards.
- Lightweight Construction:Low-density polystyrene and polyethylene blocks reduce structural dead load and crane capacity requirements. India's urban affordable housing projects specify lightweight systems for tight site logistics.
Thermal insulation commands the largest addressable base; fireproofing is climbing the fastest as high-rise codes tighten across Middle East and Asian markets.
End User Industry:
Customer type determines procurement patterns, with integrated modular platforms consolidating demand differently than fragmented residential builders.
- Commercial Construction:Office, retail, and hospitality developers specify fire-rated and high-performance thermal systems. France and Germany's deep retrofit pipelines for aging commercial stock are opening aftermarket refurbishment channels distinct from new construction cycles.
- Modular Housing:Factory-built housing platforms in India consolidate design, material supply, and installation. LONTTO Group and similar integrators capture this demand through equipment-to-material systems serving Maharashtra and Karnataka factories.
- Residential Builders:Single-family and multi-family construction drives polystyrene volume through distributor networks. Germany's passive house mandates pull certified thermal materials into both new construction and envelope replacement.
- Infrastructure Developers:Transportation, healthcare, and educational facilities specify fire-rated phenolic and polyisocyanurate for code compliance. Saudi Arabia's SFDA protocols and China's GB standards create multi-jurisdiction certification complexity for suppliers.
Commercial construction absorbs the greatest material tonnage; modular housing is gaining share fastest as factory-based production scales.
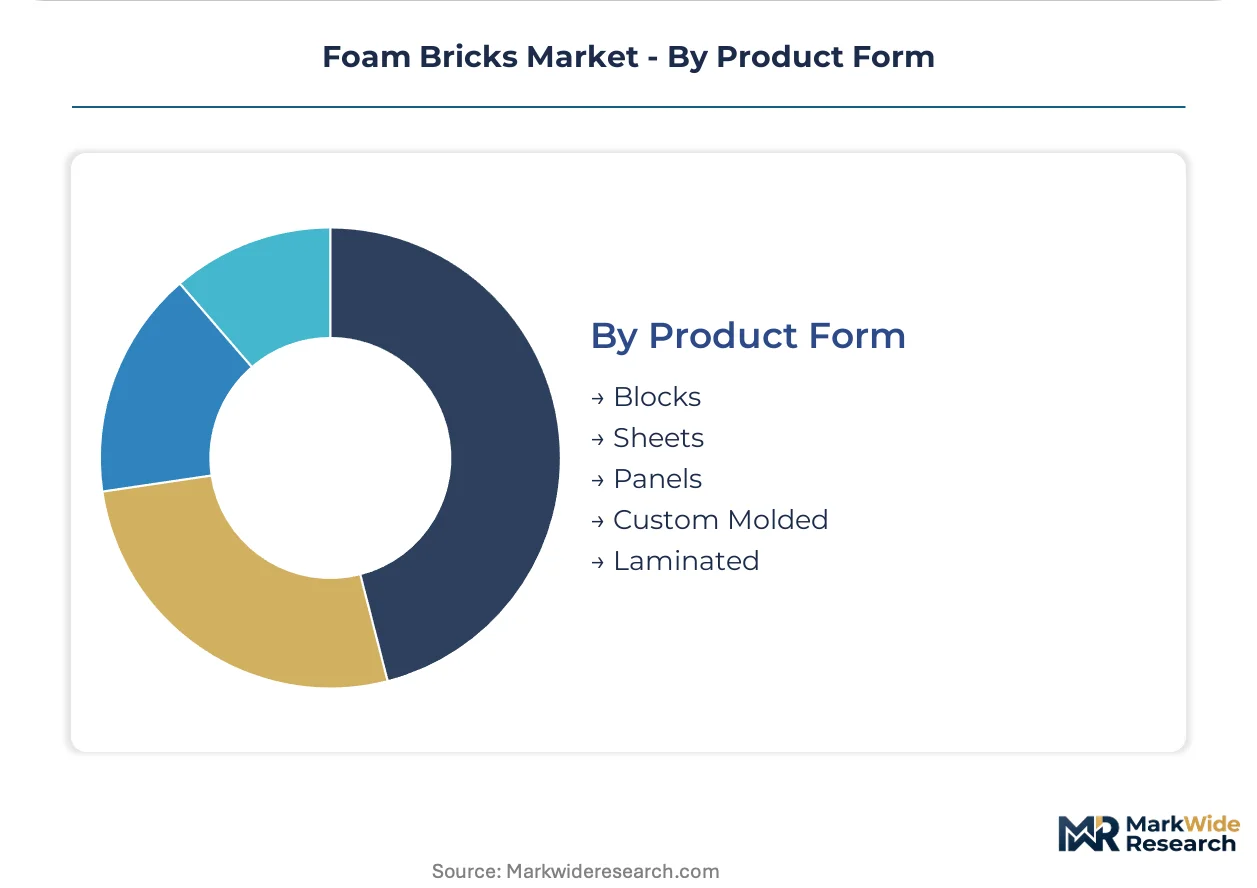
Product Form:
Supply concentration varies by geometry complexity, with standardized blocks produced at scale and custom molded shapes requiring captive tooling.
- Blocks:Rectangular polystyrene and polyurethane blocks in standardized dimensions serve high-volume residential and commercial wall applications. German and Dutch distributors stock blocks for immediate jobsite delivery, though BIM-compatible thermal data libraries are digitizing specification workflows.
- Panels:Polyisocyanurate and phenolic panels with facer laminations integrate structural and thermal functions. Commercial construction in France and the Netherlands specifies prefabricated panel systems for accelerated envelope installation.
- Sheets:Flat foam sheets enable field-cutting for retrofit applications with irregular substrate conditions. Deep energy refurbishment in Germany requires custom sheet dimensions for legacy building integration.
- Custom Molded:CNC-cut and molded shapes address complex geometries in modular housing and infrastructure. India's factory-based construction platforms demand just-in-time custom cutting to reduce on-site waste.
- Laminated:Multi-layer foam composites with gypsum, metal, or membrane facers deliver integrated performance. High-rise infrastructure in Saudi Arabia and China specifies laminated systems for combined thermal and fire-rated envelope solutions.
Blocks move the greatest volume through established distribution; custom molded shapes are expanding most quickly as digital fabrication converges with modular construction scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion capacity clusters in Germany, the United States, China, and India shape regional supply availability. Regulatory divergence on blowing agents and fire safety protocols fragments certification requirements across jurisdictions. Modular construction scaling in South Asia and deep retrofit pipelines in Western Europe redistribute demand geographically.
Germany
Passive house mandates drive specification of sub-0.035 W/m·K thermal materials in new construction and envelope replacement. The EU F-Gas Regulation phases down hydrofluorocarbon blowing agents, forcing retooling of polystyrene extrusion lines. Bavarian and Baden-Württemberg manufacturing clusters supply certified blocks for immediate jobsite delivery through digitized distributor networks.
United States
EPA AIM Act restrictions on HFC expansion processes elevate capital costs for domestic molders serving commercial refurbishment channels. Appalachian manufacturing footprints anchor supply for aging commercial stock replacement. Southeast and Midwest extrusion facilities face raw material volatility from Gulf Coast benzene and styrene monomer concentration.
China
GB standards on building energy efficiency tighten product specifications for high-rise envelope materials. Dual carbon goals accelerate substitution toward low-thermal-conductivity insulation in new urban construction. Yangtze River Delta and Pearl River Delta production bases scale phenolic and polyisocyanurate capacity for infrastructure developers.
India
BIS certification mandates for thermal insulation materials create compliance barriers for imported foam brick systems. Maharashtra and Karnataka factory-based construction platforms consolidate procurement through equipment-to-material integrators. Affordable housing programs in urban corridors specify lightweight wall systems reducing crane capacity requirements.
Saudi Arabia
SFDA fire safety protocols for construction materials mandate rated envelope solutions for high-rise infrastructure. Infrastructure investment in Riyadh and the Eastern Province pulls phenolic and laminated systems into specification. Gulf-based developers navigate multi-jurisdiction certification complexity spanning European CPR and domestic protocols.
Foam Bricks Market Competitive Landscape
Integrated material-to-equipment providers and regional specialty molders split the market into divergent margin pools. Consolidation pressures favor larger producers with captive chemical processing and backward integration into polymer production. Three archetypes dominate: Appalachian-based refurbishment suppliers, Asian equipment-to-material integrators, and fire-rated formulation specialists. Competitive moves center on certification portfolio expansion and modular construction partnership anchoring.
Among North American fabricators, General Shale and Cherokee Brick exemplify regional supply archetypes with Appalachian manufacturing concentration. LONTTO Group anchors the equipment-to-material integration model serving South Asian modular housing factories. These three occupy positions spanning refurbishment channels, fire-rated specification, and factory-direct construction platforms.
| Leading Market Players |
|---|
| Triangle Brick Company |
| Riverside Brick & Supply Company |
| Yankee Hill Brick |
| Cherokee Brick |
| Glen-Gery |
| Bilco Corporation |
| General Shale |
| LONTTO Group |
| Hebron Brick |
| Others |
Supply & Pricing Matrix
HFC blowing agent phaseout risk under the EPA AIM Act and EU F-Gas Regulation dictates both the spread between premium phenolic systems and commodity polystyrene blocks and the geographic redistribution of extrusion capacity toward integrated producers with captive hydrocarbon expansion capabilities.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across European foam brick supply, forcing a three-tier pricing structure across premium, standard, and economy levels. Phenolic formulations with inherent fire resistance command substantial premiums over halogenated polystyrene alternatives facing REACH flame retardant restrictions. Cost compression in standard-grade extruded polystyrene is intensifying because small molders lack backward integration into polymer production. Modular housing factories in India exhibit the highest price sensitivity due to consolidated procurement volumes, while infrastructure developers in Saudi Arabia prioritize fire-rated certification over unit cost.
Supply Chain Analysis
Specialized extrusion contractors in Germany's Bavarian cluster, the US Gulf Coast corridor, and China's Yangtze River Delta hold concentrated foam brick manufacturing capacity. Production draws from benzene and styrene monomer feedstocks clustered around Rotterdam and the US Gulf Coast, with polyisocyanurate precursors sourcing from integrated chemical complexes. Single-source vulnerability in blowing agent chemistry creates exposure as HFC-dependent lines face stranded asset risk. Distribution runs through digitized distributor networks in Western Europe and factory-direct equipment-to-material integrators in South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through India's modular housing procurement consolidation, fragmenting traditional distributor margins and forcing suppliers toward integrated service models or protected specification niches.
For Market Incumbents: Insulate margin pools by deepening backward integration into polymer production and capturing certification portfolios for multi-jurisdiction compliance. Mineral wool substitution in commercial high-rises and REACH flame retardant phasedowns threaten commodity polystyrene positions. Priority levers include hydrocarbon expansion line investments in Germany and phenolic formulation R&D for Saudi SFDA and China GB standard alignment. For New Entrants and Emerging Players: Mid-market commercial deep retrofit pipelines in France and Germany represent the most penetrable entry point, as aging envelope stock requires custom sheet dimensions incompatible with standardized block supply. India's BIS-certified domestic production gap offers protected market space for local testing infrastructure investments. A go-to-market angle anchoring CNC cutting equipment with just-in-time foam brick supply reduces modular factory waste and labor hours. For Investors and Strategic Acquirers: The EU F-Gas Regulation's HFC phasedown completion reshapes the acquisition landscape toward integrated producers with pentane or CO2 expansion capabilities. Long-term viability centers on captive chemical processing and multi-jurisdiction certification infrastructure rather than pure-play molding assets. The signal to watch is consolidation velocity among mid-scale European molders lacking retooling capital.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Production | Captive styrene supply insulates margin pools from Rotterdam and Gulf Coast monomer volatility. |
| Multi-Jurisdiction Certification Expansion | Parallel EU CPR, Saudi SFDA, and China GB compliance extends addressable specification channels. |
| Hydrocarbon Expansion Line Retooling | Pentane and CO2 systems satisfy EU F-Gas Regulation while elevating capital barriers for competitors. |
| Equipment-to-Material System Integration | CNC cutting convergence with just-in-time supply captures India's modular housing procurement consolidation. |
| Deep Retrofit Channel Development | Aftermarket refurbishment in Germany and France opens demand cycles distinct from new construction. |
Research Methodology
A spread of perspectives from plant managers at extrusion facilities, procurement leads at modular housing developers, distribution channel partners, and technical R&D directors converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from customs and trade data, SEC 10-K filings, BIS certification registries, and EU F-Gas Regulation implementation reports. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Demand-supply balance dynamics across material chemistry tiers, application requirements, end-user procurement patterns, and product geometry complexity shaped the analytical framework over the projection horizon. Segmentation modeling captured polystyrene, polyisocyanurate, phenolic, polyurethane, and polyethylene material splits crossed with thermal insulation, fireproofing, acoustic, and lightweight construction applications. CAGRs derived from installed base replacement cycles, regulatory compliance deadlines, and modular construction scaling curves.
Practitioners should monitor blowing agent chemistry transitions, REACH flame retardant restriction timelines, and BIS certification enforcement intensity for early signals of forecast revision. Quarterly review of extrusion line retooling announcements, modular housing factory commissioning rates, and multi-jurisdiction product launch cadences is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Refractory Cement Market
Building Materials
Mass Timber Construction Market
Building Materials
India Aluminum Door and Window Market
Building Materials
Concrete Admixtures Market
Building Materials
Lightweight Precast Wall Panel Market
Building Materials
GRC Cladding Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Global Building Panels Market
Building Materials
Zinc Polycarboxylate Cement Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Drywall Joint Tape Market
Building Materials
Plaster Accelerator Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Fiber Cement Market