
 Ireland Cement Market | 2026-2036
Ireland Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland Cement Market Insights
Decarbonized clinker substitution is tilting production economics across the Irish cement sector. Ecocem Ireland Ltd leverages its ground granulated blast-furnace slag expertise to anchor supply for low-carbon concrete projects. CRH plc sustains integrated coastal manufacturing through its Irish Cement Ltd subsidiary, controlling limestone reserves and marine distribution. Breedon Group plc competes through regional blending capacity, positioning bulk supply close to midland construction corridors.
Cement comprises hydraulic powder formed by calcining limestone with silicates, aluminates, and ferrites at temperatures exceeding 1,450°C, then grinding the resulting clinker with gypsum to control set time; its primary function binds aggregate into concrete for load-bearing structures and civil engineering works. Portland cement dominates volume through standardized EN 197-1 compliance, though blended cement captures margin expansion as fly ash and slag incorporation rises under carbon reduction mandates. Specialty cement occupies niche premium tiers in precast elements and sulfate-resistant foundations where performance specifications command price premiums over commodity grades.
Ireland's Building Regulations Part L and the EPA industrial emissions licensing framework shape product formulation and kiln fuel choices, pushing manufacturers toward alternative raw materials and waste-derived fuels. The EPA enforces Best Available Techniques standards for NOx and particulate emissions, constraining capacity expansion at older dry-process facilities. Stakeholders must weigh capital allocation between retrofitting existing kilns for lower clinker factors versus importing finished cement from EU ETS-compliant plants as carbon border adjustments tighten.
Market Dynamics
Decarbonization mandates from the EPA and tightened Building Regulations Part L standards are compressing clinker ratios across Irish cement production, forcing kiln operators toward alternative raw materials and waste-derived fuels.
Growth Catalysts
- Housing for All programme:Government-mandated residential construction targets are pulling Portland cement volumes into Dublin and surrounding counties where population density outstrips supply.
- EN 197-1 blended cement standards:Regulatory acceptance of slag and fly ash incorporation is expanding addressable product lines for low-carbon concrete specifications.
- Ground granulated blast-furnace slag processing:Domestic GGBS capacity is anchoring import substitution for bulk cement users seeking reduced embodied carbon.
Market Restraints
- Limestone reserve depletion:Accessible high-calcium limestone deposits near coastal manufacturing sites face extraction constraints from planning permission delays.
- EU ETS carbon pricing:Emissions trading scheme costs are compressing margins at older dry-process kilns lacking alternative fuel infrastructure.
- Ready-mix concrete substitution:Pre-cast element manufacturers are bypassing bulk cement procurement through direct clinker import arrangements.
Strategic Opportunities
- Midland construction corridors:Regional blending capacity expansion can capture bulk supply contracts for infrastructure projects outside Greater Dublin Area concentration.
- Carbon capture at source:Kiln exhaust mineralization technologies are opening compliance pathways for EPA industrial emissions licensing renewals.
- Marine distribution networks:Coastal terminal infrastructure enables finished cement import arbitrage as EU carbon border adjustments tighten.
Industry Challenges
- Alternative fuel sourcing:Waste-derived fuel supply chains require specialized handling certifications that limit qualified logistics providers.
- Clinker factor reduction:Lower-clinker cement formulations demand modified concrete admixture protocols that extend contractor qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland Cement Market |
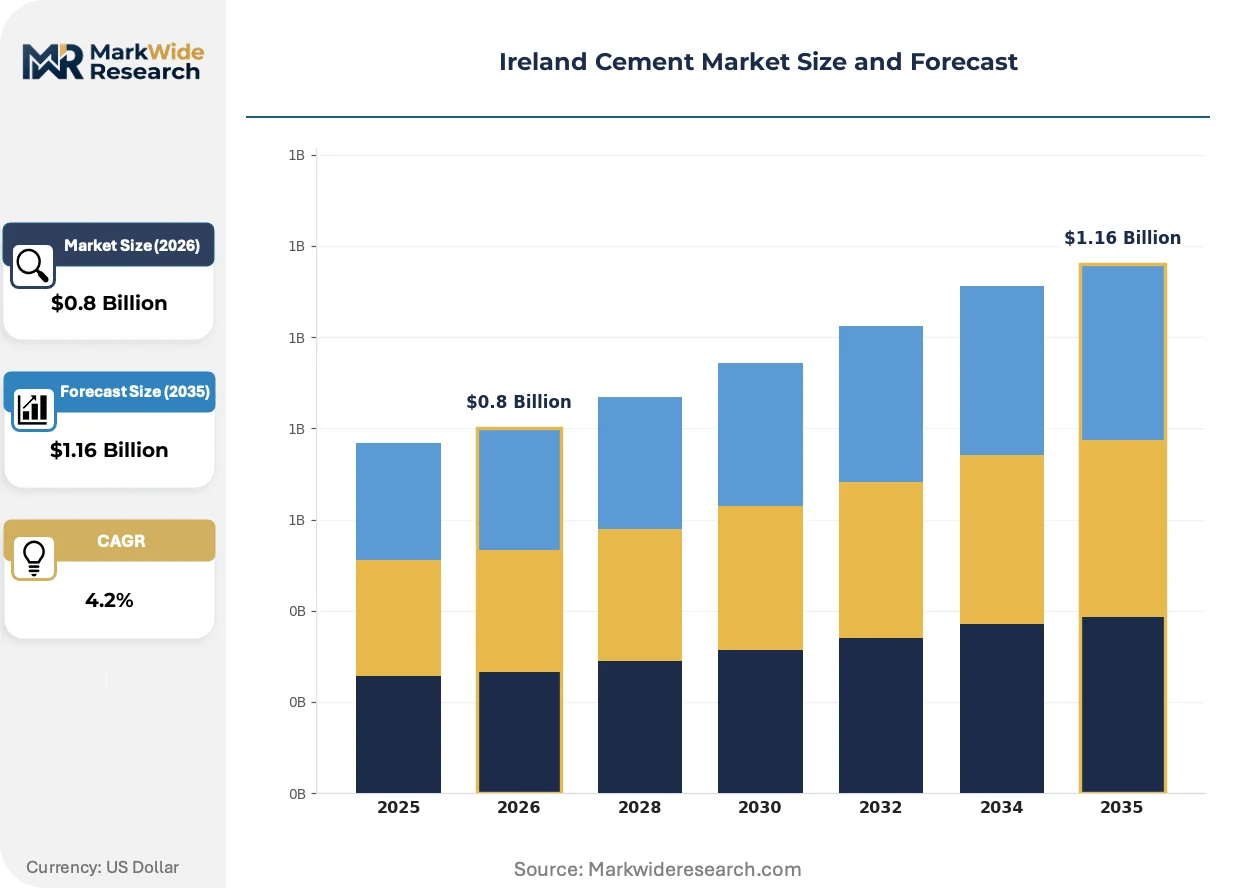
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portland Cement, White Cement, Blended Cement, Specialty Cement End User: Residential Construction, Commercial Construction, Infrastructure, Industrial Use Distribution Channel: Direct Sales, Retail Stores, Online Sales, Wholesale Application: Building, Road Construction, Water Management, Precast Elements |
| Companies Covered | Irish Cement Ltd, Mannok Holdings, Breedon Group plc, Ecocem Ireland Ltd, O'Brien Cement, Cookstown Cement Ltd, Mannok Cement, Breedon Cement, CRH plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland Cement Market Trends and Innovations
Kiln control systems and supply chain traceability platforms are digitizing production economics across Irish cement manufacturing, compressing quality variance and enabling real-time clinker substitution optimization.
Digital twin modeling is digitizing combustion efficiency across dry-process kilns, allowing operators to simulate alternative fuel blends before physical trials. Major concrete producers are adopting these platforms to pre-qualify low-carbon mix designs for Building Regulations Part L compliance. The structural consequence is compressing R&D cycle times from months to weeks for new cement formulations.
EPA industrial emissions licensing is enforcing Best Available Techniques standards for NOx and particulate limits, constraining capacity expansion at older facilities. Manufacturers must retrofit baghouse filters or face production caps. The dry-process kiln segment is responding with selective catalytic reduction installations to maintain operating permits.
Contractor procurement is consolidating around certified low-carbon concrete suppliers, displacing spot-market bulk purchasing. Main residential developers are mandating Environmental Product Declarations for all structural concrete. This concentration is most visible in Greater Dublin Area projects where Housing for All programme compliance requires documented embodied carbon thresholds.
Ireland Cement Market Segmentation
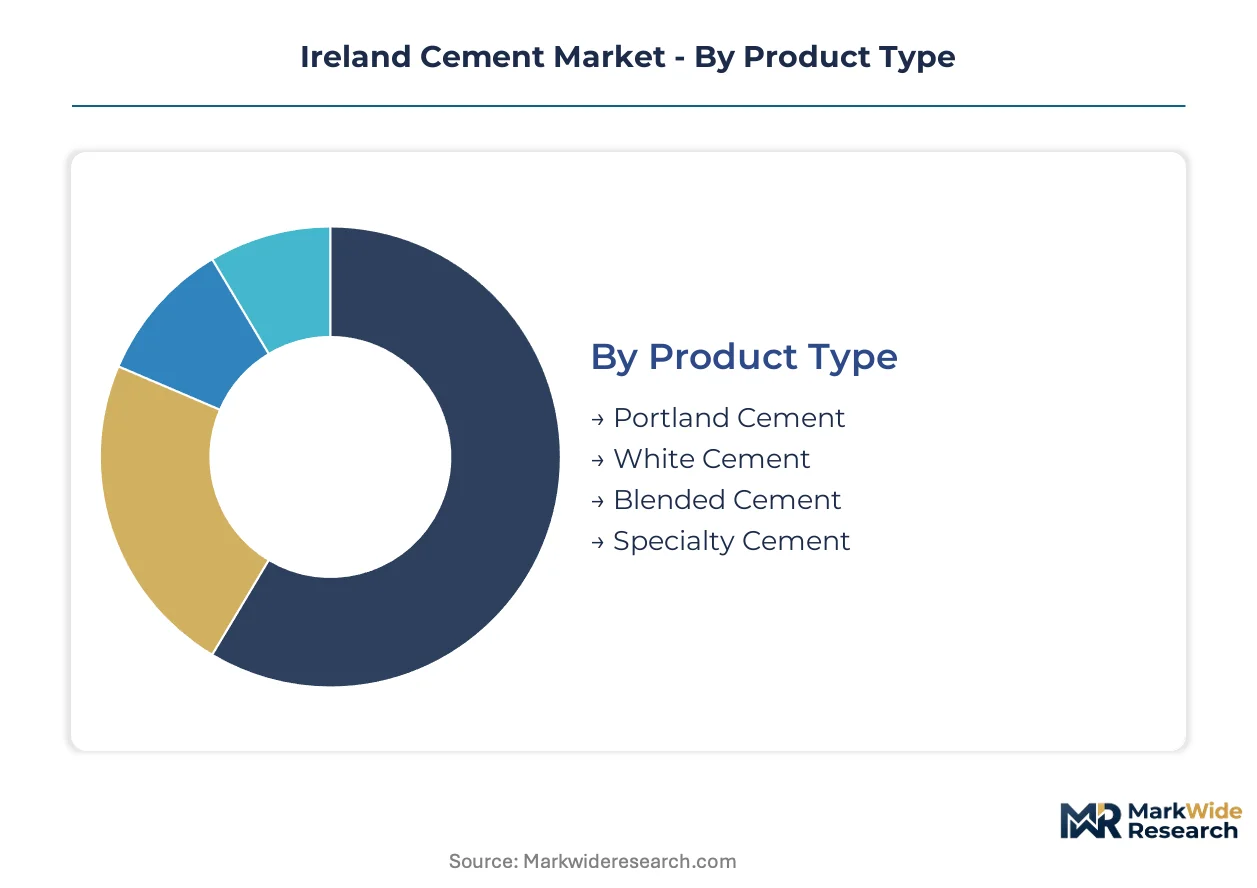
Cement segmentation in Ireland reflects divergent technical requirements across construction verticals and evolving procurement patterns under decarbonization mandates. Product formulation choices directly impact Building Regulations Part L compliance pathways, while distribution channel selection shapes contractor access to certified low-carbon supply.
Product Type:
Mature commodity grades dominate volume throughput, while emerging low-carbon formulations capture specification-driven premiums.
- Portland Cement:Standardized EN 197-1 CEM I formulation delivers consistent compressive strength for structural concrete across high-rise residential towers. Demand concentrates in Greater Dublin Area Housing for All programme sites where contractors prioritize predictable set times and supply security.
- Blended Cement:CEM II and CEM III classifications incorporate ground granulated blast-furnace slag or fly ash to reduce clinker factors below 65 percent. County Wicklow and Kildare infrastructure projects specify these grades for embodied carbon reporting under EPA industrial emissions licensing frameworks.
- White Cement:Low-iron clinker yields aesthetic finishes for architectural precast facades in Cork commercial developments.
- Specialty Cement:Sulfate-resistant and rapid-hardening variants serve marine foundations and emergency repair contracts.
Portland cement handles the majority of throughput; blended cement is the fastest mover on share.
End User:
Customer segmentation tracks construction cycle volatility and capital allocation priorities across public and private balance sheets.
- Residential Construction:Housing for All programme targets pull bulk cement volumes into Dublin, Meath, and Kildare counties where population growth outstrips existing housing stock. Developer procurement concentrates around certified Environmental Product Declaration suppliers to satisfy lender sustainability criteria.
- Infrastructure:Transport Infrastructure Ireland road and rail projects specify low-carbon concrete for public works compliance. Midland corridor investments in Offaly and Westmeath create regional demand pockets outside Greater Dublin Area concentration.
- Commercial Construction:Office and retail developments in Cork and Limerick drive white cement and specialty grade demand for aesthetic and performance specifications.
- Industrial Use:Manufacturing facility foundations and process equipment bases consume sulfate-resistant formulations.
Residential construction anchors absolute volume; infrastructure contracts are expanding most quickly on specification intensity.
Distribution Channel:
Channel structure reflects contractor scale segmentation and the technical complexity of low-carbon concrete qualification.
- Direct Sales:Major ready-mix producers negotiate bulk supply agreements with Irish Cement Ltd and Ecocem Ireland Ltd for guaranteed slag and clinker access. These arrangements dominate Housing for All programme procurement where volume certainty outweighs spot price flexibility.
- Wholesale:Regional distributors serve mid-tier contractors across Galway, Limerick, and Waterford with blended cement inventories positioned for next-day delivery.
- Retail Stores:Builder merchants supply bagged Portland cement for small-scale residential extensions and agricultural construction.
- Online Sales:Digital procurement platforms emerge for specification documentation and certified product traceability.
Direct sales commands the largest revenue share; wholesale networks are gaining share fastest through regional corridor expansion.
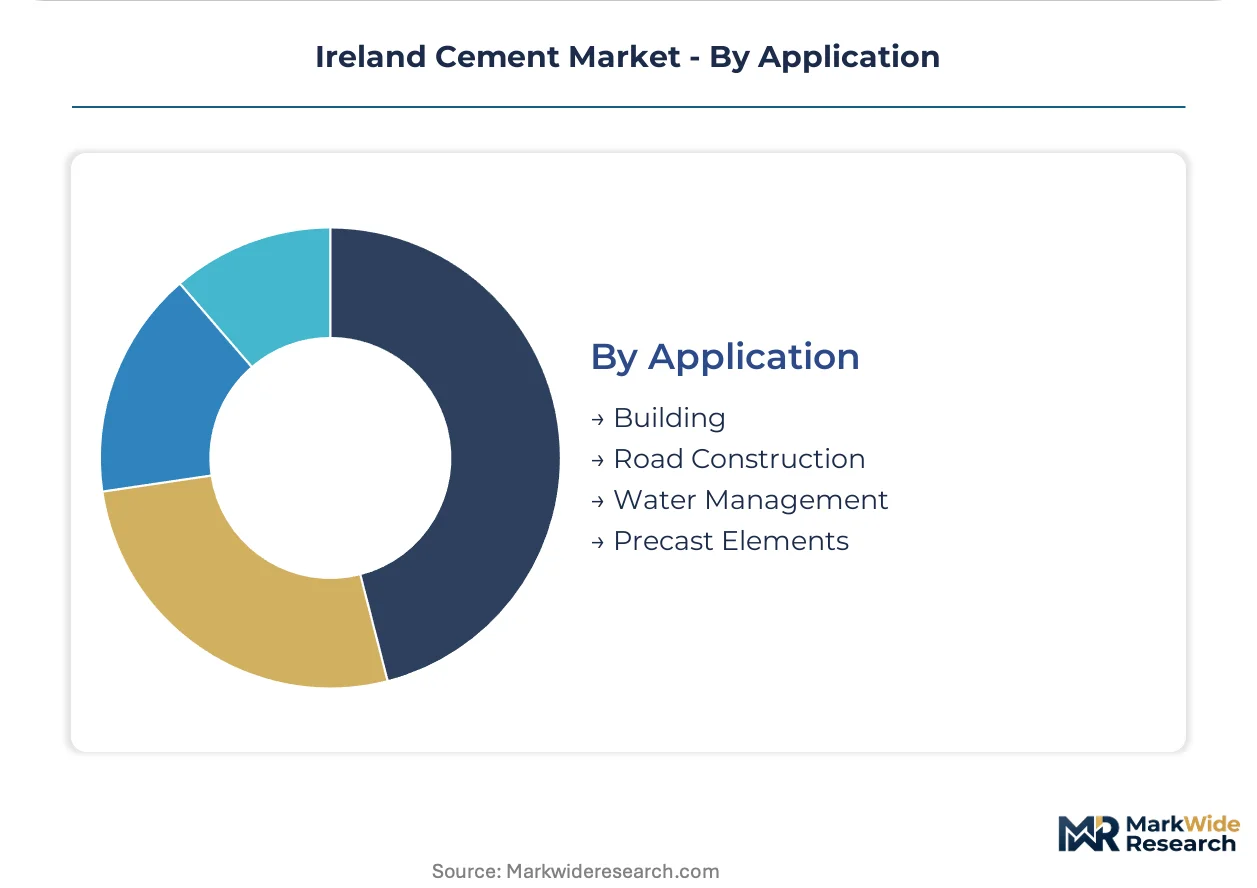
Application:
Application segmentation aligns with civil engineering discipline requirements and durability exposure conditions.
- Building:Structural concrete for multi-storey residential and commercial frames consumes the majority of Irish cement volume. Greater Dublin Area high-rise construction specifies CEM III blends for core wall and slab elements where thermal mass and fire resistance intersect.
- Road Construction:Transport Infrastructure Ireland pavement projects demand rapid-hardening grades for overnight lane reopening. Midland motorway extensions through Offaly and Laois create sustained demand outside coastal manufacturing zones.
- Water Management:Reservoir and wastewater treatment infrastructure specifies sulfate-resistant cement for submerged exposure.
- Precast Elements:Factory-cast wall panels and bridge beams bypass bulk cement procurement through direct clinker import arrangements.
Building applications absorb the dominant share; road construction is climbing the fastest on infrastructure programme acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential developers and infrastructure contractors concentrate procurement power in the Greater Dublin Area, with secondary demand pockets emerging across the midland construction corridors and southern port cities.
Greater Dublin Area
Housing for All programme targets pull cement volumes into Dublin, Meath, and Kildare counties where population growth outstrips housing stock. Local authorities enforce Building Regulations Part L energy efficiency standards that mandate low-carbon concrete specifications. Dublin Port and surrounding logistics zones anchor marine distribution networks for bulk cement import and coastal manufacturing access.
Midland Region
Transport Infrastructure Ireland road and rail investments through Offaly, Westmeath, and Laois create regional demand outside coastal manufacturing concentration. The EPA industrial emissions licensing framework constrains new kiln capacity, pushing contractors toward regional blending terminals. Tullamore and Athlone serve as logistics hubs for bulk supply contracts to infrastructure contractors.
Southwest Corridor
Cork commercial developments and pharmaceutical facility construction drive white cement and specialty grade demand for aesthetic and performance specifications. Cork Harbour enables marine import arbitrage for finished cement from EU ETS-compliant plants. Ringaskiddy and Little Island industrial zones concentrate precast element manufacturing that bypasses traditional bulk cement procurement.
Border Region
Cross-border infrastructure coordination with Northern Ireland creates procurement complexity under divergent regulatory frameworks. Monaghan and Louth counties position blending capacity to serve contractors operating across jurisdictions. Dundalk functions as a distribution node for regional supply chains extending into County Down.
Ireland Cement Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated manufacturing base where coastal limestone reserves and marine distribution determine strategic positioning. The market structures around integrated kiln operators, regional blenders, and slag-processing specialists. Dominant competitive moves include retrofitting existing facilities for alternative fuel compatibility and securing waste-derived fuel supply chain certifications.
Among Ireland-based operators, Irish Cement Ltd and Ecocem Ireland Ltd exemplify divergent archetypes within the low-carbon transition. CRH plc occupies a position as the parent entity controlling integrated coastal manufacturing through its Irish Cement Ltd subsidiary. Breedon Group plc represents regional blending capacity expansion targeting midland construction corridors outside Greater Dublin Area concentration.
| Leading Market Players |
|---|
| Irish Cement Ltd |
| Mannok Holdings |
| Breedon Group plc |
| Ecocem Ireland Ltd |
| O'Brien Cement |
| Cookstown Cement Ltd |
| Mannok Cement |
| Breedon Cement |
| CRH plc |
| Others |
Pricing and Supply Chain Analysis
UK ground granulated blast-furnace slag imports and County Louth limestone reserves concentrate upstream supply leverage, positioning margin capture with coastal kiln operators who control marine distribution terminals and alternative fuel processing infrastructure.
Pricing Analysis
Cost-plus contracts with quarterly EU ETS carbon allowance indexation dominate bulk procurement between Irish Cement Ltd and major ready-mix producers. Three-tier pricing structure across premium low-carbon certified, standard EN 197-1 blended, and economy-grade Portland tiers reflects clinker factor and EPD documentation levels. Cost compression in standard-grade supply is intensifying because of slag processing capacity expansion at Ecocem Ireland Ltd. Residential developers under Housing for All programme mandates show lowest price sensitivity due to lender sustainability covenants, while mid-tier regional contractors exhibit highest spot-market price responsiveness.
Supply Chain Analysis
High-calcium limestone from County Louth and Meath, marine fuel oil from Rotterdam, and processed GGBS from UK steelworks feed Irish kiln and blending operations. Raw material sourcing draws from coastal extraction sites facing planning permission delays, EU ETS-compliant fuel markets, and cross-channel slag logistics networks. Single-source vulnerability concentrates in marine terminal handling capacity at Dublin Port where bulk import volumes compete for limited berth allocation. Distribution runs through direct mill-to-plant bulk contracts for major concrete producers, supplemented by regional wholesale depots serving mid-tier contractors across Galway and Limerick counties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Housing for All programme developers who mandate certified low-carbon supply chains, fragmenting spot-market leverage and compressing margin pools toward documented Environmental Product Declaration holders.
For Market Incumbents: Entrench coastal manufacturing advantage through baghouse filter retrofits and selective catalytic reduction installations that secure EPA industrial emissions license renewals. Deepen upstream control over waste-derived fuel supply chains by acquiring qualified logistics certifications before alternative fuel mandates tighten. Carbon capture pilot investments at existing dry-process kilns represent the critical defensive lever against EU carbon border adjustment exposure. For New Entrants and Emerging Players: Midland construction corridors through Offaly and Westmeath represent the most penetrable entry point where regional blending terminals can capture Transport Infrastructure Ireland bulk contracts outside Greater Dublin Area concentration. Direct-to-contractor digital procurement platforms for specification documentation and certified product traceability offer a differentiated go-to-market angle against established direct sales relationships. For Investors and Strategic Acquirers: Capital is best deployed toward slag-processing specialists with established EPA licensing and marine terminal access rather than greenfield kiln capacity facing emissions constraints. Long-term viability across the projection horizon rests on alternative fuel infrastructure readiness and carbon capture technology partnerships. The signal to watch is EPA industrial emissions license renewal timelines for older dry-process facilities as a capacity rationalization indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Fuel Infrastructure Investment | Waste-derived fuel processing capabilities secure EPA license compliance and reduce EU ETS exposure. |
| Regional Blending Terminal Expansion | Midland corridor positioning captures Transport Infrastructure Ireland contracts outside Dublin concentration. |
| Carbon Capture Technology Partnership | Kiln exhaust mineralization opens compliance pathways for emissions license renewals at older facilities. |
| Environmental Product Declaration Certification | Documented embodied carbon thresholds satisfy Housing for All programme lender sustainability criteria. |
| Marine Distribution Network Optimization | Coastal terminal access enables finished cement import arbitrage as EU carbon border adjustments tighten. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with ready-mix concrete procurement directors, EPA regulatory compliance officers, Transport Infrastructure Ireland project managers, and regional contractor site supervisors. Secondary validation drew from EPA industrial emissions licensing databases, Building Regulations Part L technical guidance documents, EU ETS allowance trading records, and cement industry trade association publications. Bottom-up volume estimates from county-level construction permit data were triangulated against top-down kiln capacity utilization assessments.
Calibration against historical production volumes and announced capacity modifications anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product formulation grade, end-use construction vertical, distribution channel tier, and regional demand cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating Housing for All programme delivery schedules and infrastructure pipeline announcements. Clinker factor reduction trajectories and alternative fuel penetration rates served as key industry-specific forecast inputs.
Stress conditions across EU carbon pricing bands, limestone extraction permission timelines, and Housing for All completion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and construction sector labor availability. Cross-checking against Transport Infrastructure Ireland capital programme disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
United States White Cement Market
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
North America Construction Aggregates Market
Building Materials
North America Engineered Stone Market
Building Materials
US Facade Market
Building Materials
Global Metal Cladding Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
Southeast Asia Concrete Admixtures Market
Building Materials
Europe Building and Construction Sheets Market
Building Materials
Blended Cement Market
Building Materials
Industrial Concrete Flooring Market
Building Materials
India Concealed Cistern Market
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
Timber Frames Market
Building Materials
North America Architectural Coatings Market