
 Germany Aluminum Door and Window Market | 2026-2036
Germany Aluminum Door and Window Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Aluminum Door and Window Market Insights
Steel framing is pivoting toward aluminum in German fenestration as thermal performance regulations tighten and lifecycle cost advantages accumulate. SCHÜCO leverages its integrated profile-extrusion and system-design capabilities to dominate commercial specifications across the DACH region. Neuffer Fenster + Türen anchors its position through direct-to-consumer channels that bypass traditional distributor markups. Weru Group differentiates via specialized acoustic and security-rated aluminum systems for high-density residential zones.
Germany aluminum door and window systems comprise extruded aluminum alloy profiles, typically Grade 6063-T6 for architectural applications, assembled with polyamide thermal breaks and multi-chamber glazing to achieve U-values below 1.0 W/m²K for energy-efficient building envelopes. These systems serve as structural weather barriers while enabling natural daylighting and controlled ventilation in commercial and residential structures. Casement windows and sliding doors command the largest product volumes, though bi-fold configurations are gaining share in premium residential renovation where spatial flexibility commands price premiums. New construction installations face pressure from declining housing starts, while retrofit and custom installation segments absorb displaced capacity as building owners prioritize envelope upgrades over full rebuilds.
The EU Green Deal's renovation wave targets, enforced through national transposition by Germany's Federal Ministry for Economic Affairs and Climate Action, mandate stepwise efficiency improvements that favor thermally broken aluminum over PVC in commercial retrofits. KBA energy-efficiency labeling and local building codes in Munich, Hamburg, and Cologne further restrict single-pane and non-thermally-broken installations, tightening product eligibility. Stakeholders must monitor how the proposed EU Carbon Border Adjustment Mechanism reshapes raw aluminum sourcing economics and whether domestic extruders can secure low-carbon primary metal to maintain specification access.
Market Dynamics
The EU Green Deal's building renovation wave is compressing specification timelines across German fenestration, forcing aluminum system suppliers to pre-certify thermal performance ahead of tightened KBA energy-efficiency labeling deadlines.
Growth Catalysts
- EU Green Deal renovation targets:Germany's Federal Ministry for Economic Affairs and Climate Action transposes stepwise efficiency mandates that favor thermally broken aluminum over PVC in commercial envelope retrofits.
- Bavaria housing stock modernization:Urban centers across this state exceed national renovation rates, concentrating demand for high-performance aluminum systems in multi-family residential zones.
- Polyamide thermal break advances:Multi-chamber profile designs now achieve U-values below 1.0 W/m²K, qualifying products for premium efficiency tiers under local building codes in Munich, Hamburg, and Cologne.
Market Restraints
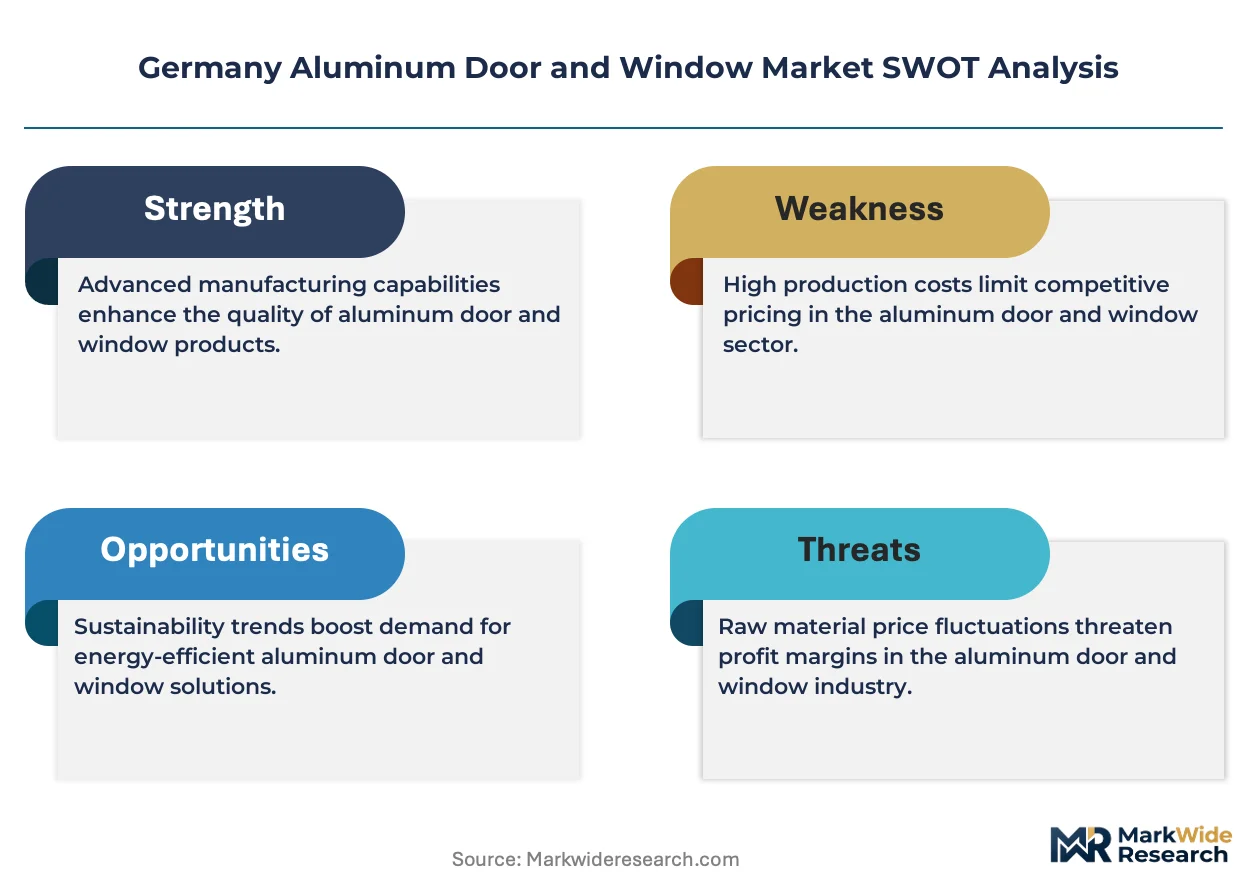
- Primary aluminum cost volatility:Raw metal price swings compress extruder margins and destabilize project quoting for commercial developers.
- EU Carbon Border Adjustment Mechanism exposure:Pending implementation threatens low-carbon specification access for suppliers dependent on non-EU primary aluminum sourcing.
- PVC substitution in residential new-build:Cost-sensitive single-family construction segments continue specifying vinyl frames despite inferior lifecycle performance.
Strategic Opportunities
- North Rhine-Westphalia retrofit backlog:Industrial building stock in this state presents concentrated envelope upgrade potential as efficiency deadlines tighten.
- Bi-fold configuration premiumization:Spatial flexibility demands in high-end residential renovation support price premiums for complex aluminum door systems.
- Direct-to-consumer channel development:Bypassing traditional distributor markups captures margin and installation scheduling control.
Industry Challenges
- Certification timeline compression:KBA labeling updates and local code revisions demand continuous product re-testing and documentation.
- Skilled installation labor scarcity:Complex thermal break assembly and glazing techniques require specialized craft training that outpaces workforce development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Aluminum Door and Window Market |
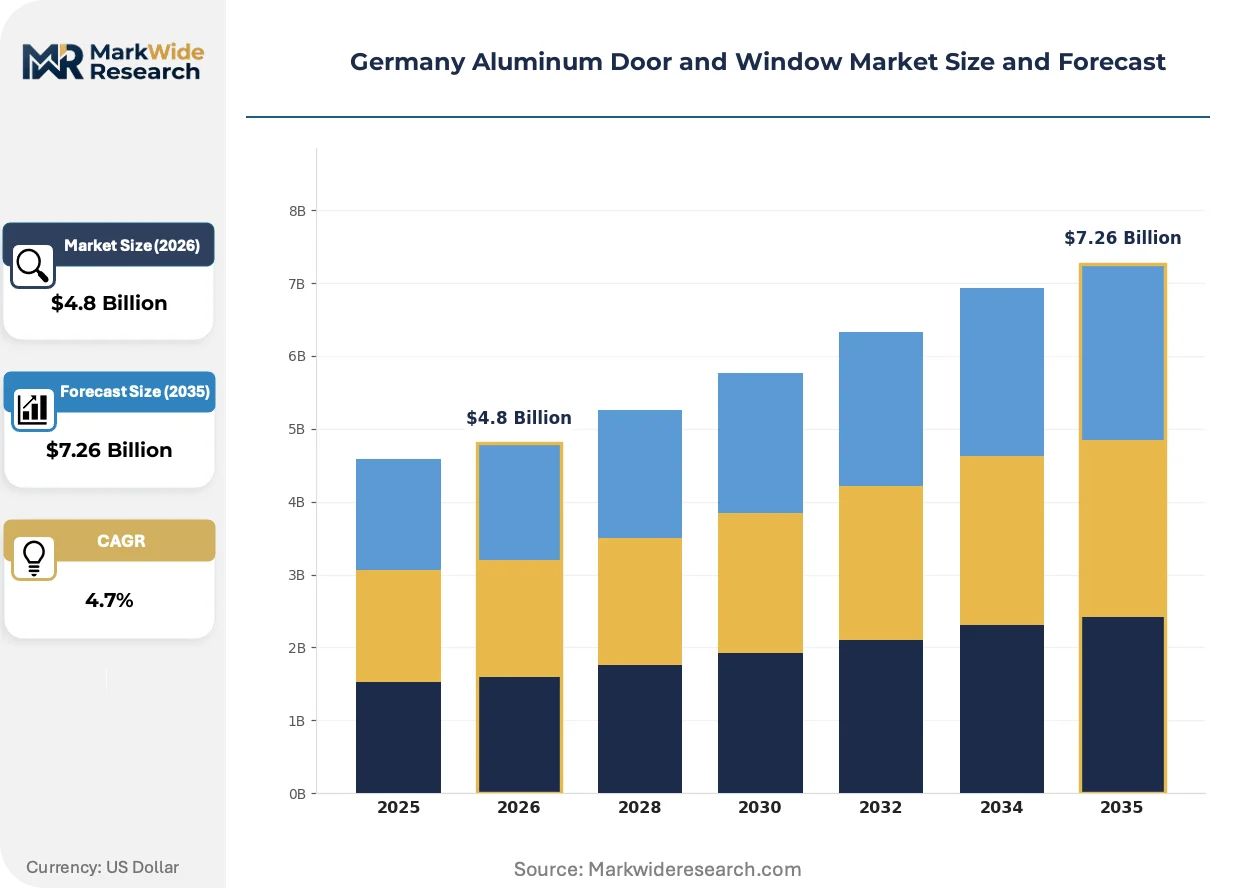
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, French Doors, Casement Windows, Bi-Fold Windows Installation Type: New Construction, Renovation, Retrofit, Custom Installation End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Public Infrastructure Material Grade: Grade 6063, Grade 6061, Grade 6005, Others |
| Companies Covered | Müller & Sohn Fensterfabrik, Fensterfabrik Niederhofer, Weru Group, Dressler GmbH, Fenster Morlok Fensterfabrik, SCHÜCO, Neuffer Fenster + Türen, Unilux, Solarlux GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Aluminum Door and Window Market Trends and Innovations
Thermal performance engineering and channel restructuring are simultaneously reshaping how aluminum fenestration reaches German building owners. Specification logic is shifting from first-cost to lifecycle cost accounting.
Polyamide thermal break technology is expanding into commercial retrofit specifications as U-value thresholds tighten. Property managers in Munich and Hamburg now prioritize whole-building envelope performance over frame material first-cost. This shift compresses PVC's addressable market in non-residential segments.
KBA energy-efficiency labeling revisions are forcing product portfolio rationalization. Manufacturers must maintain parallel certification tracks for legacy and next-generation thermal break configurations. Commercial specification teams now exclude non-labeled systems from bid lists, accelerating industry consolidation around certified suppliers.
Direct installation contracting is displacing traditional distributor-led project fulfillment. End-users in Bavaria and North Rhine-Westphalia increasingly source aluminum systems through manufacturer-affiliated installation networks. This channel shift captures margin previously allocated to wholesale intermediaries while tightening quality control over final assembly.
Germany Aluminum Door and Window Market Segmentation
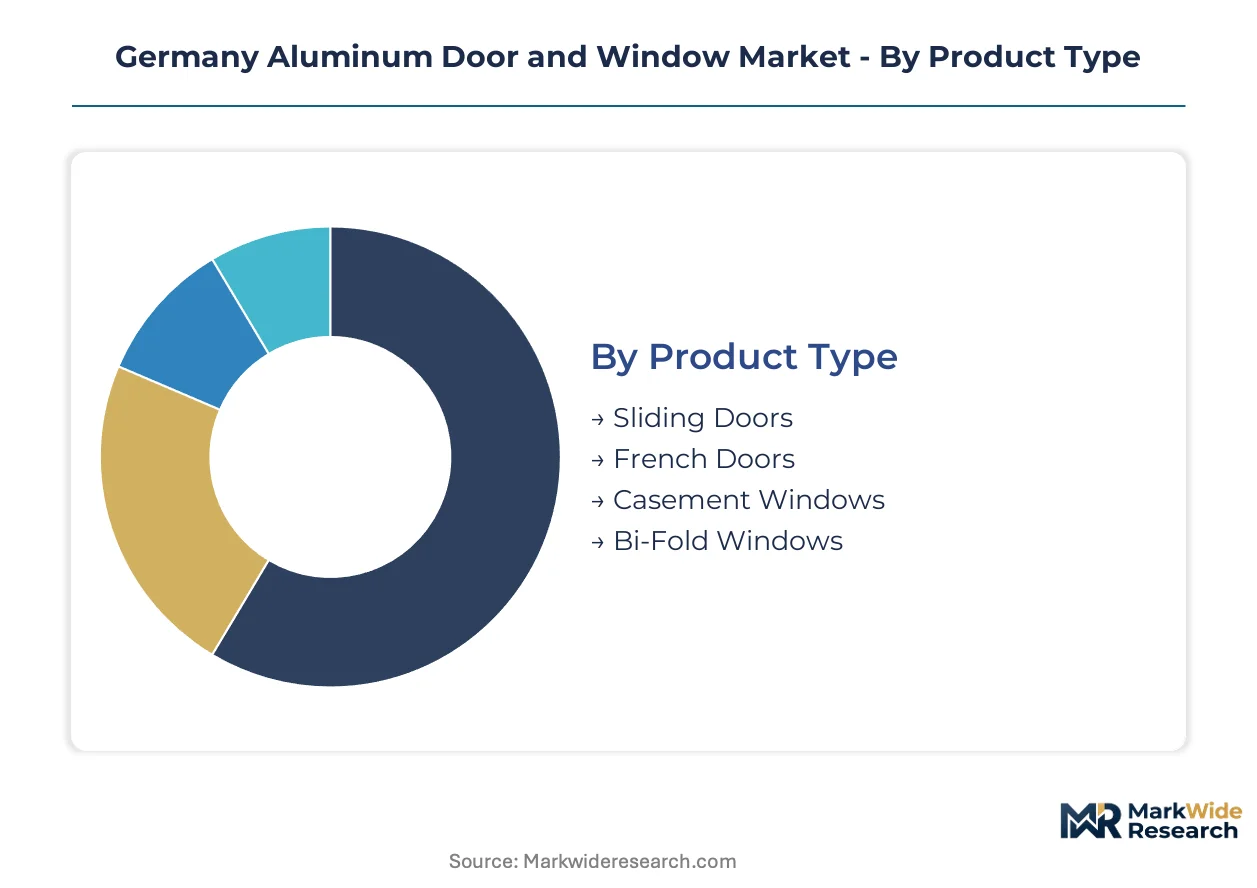
German aluminum fenestration segments diverge sharply between integrated building systems and standalone replacement products. Specification pathways, thermal certification requirements, and channel economics differ fundamentally across these boundaries.
Product Type:
Standalone door systems command premium engineering investment versus window units that embed more readily into standardized envelope modules.
- Sliding Doors:Multi-track aluminum rail systems with low-threshold drainage and thermal break continuity dominate balcony and terrace access in multi-family residential zones across Munich and Hamburg. Bavarian housing associations specify these for space-efficient floor plans where swing clearance is constrained.
- Casement Windows:Hinged sash configurations with multi-point locking and concealed hardware represent the volume core of German aluminum fenestration, achieving U-values below 1.0 W/m²K through polyamide thermal break engineering. North Rhine-Westphalia renovation contractors source these for industrial building envelope upgrades under EU Green Deal efficiency mandates.
- French Doors:Symmetrical double-leaf aluminum systems with heritage aesthetic profiles serve heritage building renovations in Cologne and Hamburg where facade preservation codes restrict modernist geometries.
- Bi-Fold Windows:Accordion-folding aluminum sash arrays enable complete wall opening in premium residential renovations; spatial flexibility commands specification premiums in high-density urban districts.
Sliding doors lead volumes today; bi-fold windows are gaining share fastest.
Installation Type:
Project origination channels split between developer-led bulk procurement and owner-directed custom specification with divergent margin structures.
- Renovation:Whole-building envelope replacement of existing aluminum, steel, or timber frames dominates German market value as EU Green Deal deadlines compress specification timelines in Munich, Hamburg, and Cologne.
- New Construction:Volume contracting to residential developers faces pressure from declining housing starts; aluminum system suppliers compete with PVC on first-cost in cost-sensitive single-family segments.
- Retrofit:In-situ frame replacement without structural modification absorbs displaced manufacturing capacity as building owners prioritize efficiency upgrades over full rebuilds.
- Custom Installation:Architect-specified bespoke aluminum systems for high-end residential and commercial projects bypass distributor markups through direct manufacturer contracting.
Renovation commands value concentration; custom installation is climbing the fastest.
End User:
Thermal performance thresholds and procurement authority structures fragment demand across building ownership categories.
- Residential Buildings:Multi-family housing associations in Bavaria and North Rhine-Westphalia drive specification volume for thermally broken aluminum systems as modernization rates exceed national averages.
- Commercial Buildings:Office and retail property managers in Hamburg and Cologne prioritize whole-building envelope performance over frame material first-cost, compressing PVC's addressable market in non-residential segments.
- Industrial Facilities:Manufacturing and logistics building owners in North Rhine-Westphalia present concentrated envelope upgrade potential as efficiency deadlines tighten for aging stock.
- Public Infrastructure:Municipal procurement for schools, hospitals, and administrative buildings follows federal efficiency guidelines that mandate KBA-labeled aluminum systems.
Residential buildings anchor demand today; commercial buildings show steepest expansion trajectory.
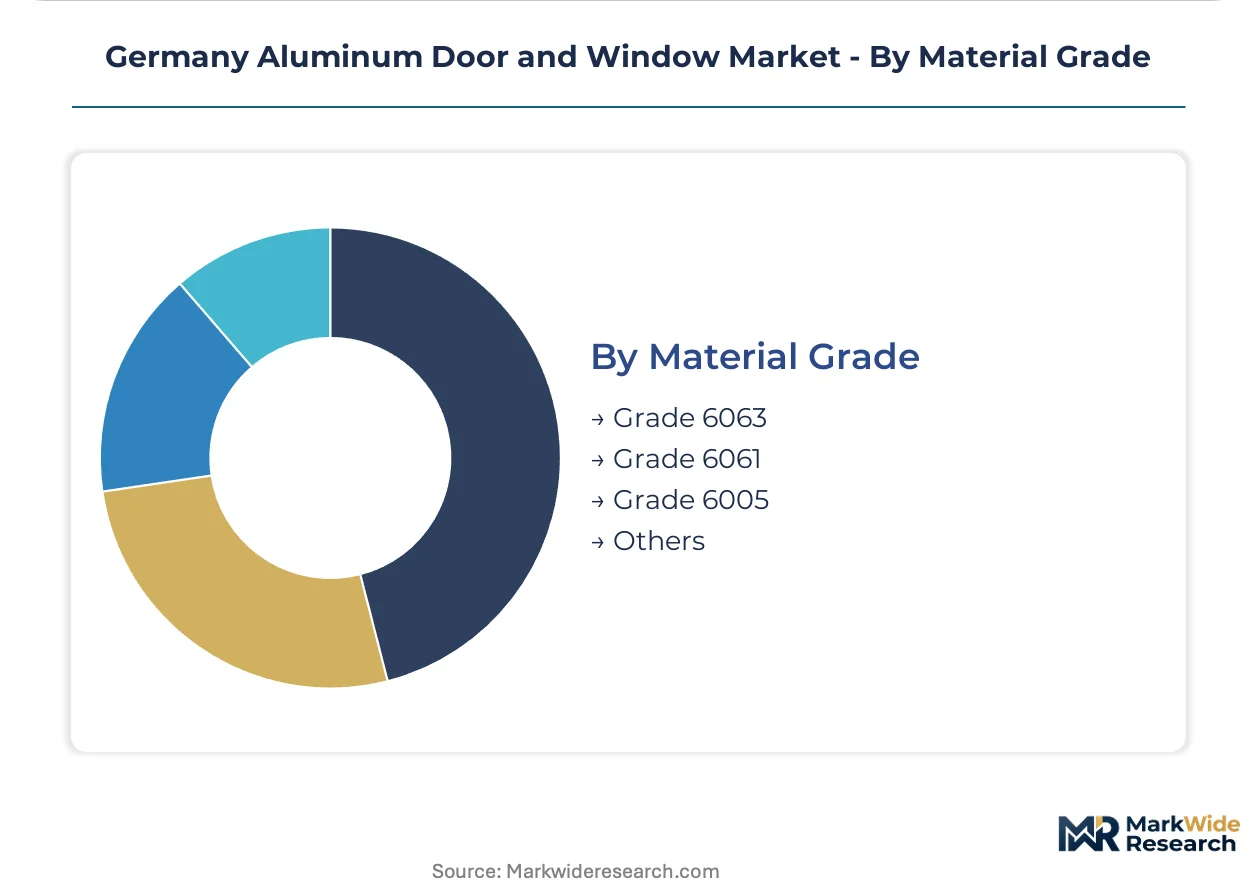
Material Grade:
Alloy selection tradeoffs between extrudability, strength-to-weight ratio, and anodizing response determine application-specific sourcing patterns.
- Grade 6063:Architectural aluminum alloy with excellent extrusion characteristics and surface finish quality dominates German fenestration profile production; T6 temper achieves required mechanical properties for structural glazing applications.
- Grade 6061:Higher-strength aluminum-magnesium-silicon alloy with superior structural performance commands specification in oversized commercial door systems and high-wind-load applications.
- Grade 6005:Intermediate-strength alloy with improved extrusion speed versus 6061 serves secondary structural members and cost-optimized residential window frames.
- Others:Specialized alloys including 6082 for marine-proximity installations and 7000-series for security-rated applications occupy niche specification pockets.
Grade 6063 leads volumes today; Grade 6061 is expanding most quickly in commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Rhine-Westphalia anchors German aluminum fenestration demand through its dense industrial building stock and concentrated housing association modernization programs. The state's legacy manufacturing infrastructure creates retrofit urgency under federal efficiency mandates. Four additional German states concentrate distinct demand patterns across commercial, residential, and public procurement segments.
North Rhine-Westphalia
Industrial facility envelope upgrades drive specification volume for thermally broken aluminum systems across the Ruhr region and Lower Rhine. KBA energy-efficiency labeling requirements compress procurement timelines for manufacturing and logistics property managers. Cologne anchors commercial retrofit activity where whole-building performance standards now exclude non-certified framing systems from bid lists.
Bavaria
Multi-family housing associations in Munich and Nuremberg exceed national renovation rates, concentrating demand for Grade 6063-T6 aluminum window systems with polyamide thermal breaks. The Federal Ministry for Economic Affairs and Climate Action transposes EU Green Deal stepwise mandates that accelerate specification of U-values below 1.0 W/m²K. Bavarian fabricators report capacity constraints as municipal efficiency deadlines tighten for 1970s housing stock.
Baden-Württemberg
Automotive supplier headquarters and precision manufacturing clusters generate commercial building envelope investment across Stuttgart and Mannheim. Local building codes in these cities restrict single-pane and non-thermally-broken installations more aggressively than federal minimums. The state's Mittelstand fabricators specialize in custom aluminum door systems for architect-specified commercial projects.
Hamburg
Port-adjacent logistics facilities and high-density residential zones create dual demand streams for acoustic-rated and thermally efficient aluminum systems. Hamburg's Senate Department for Urban Development enforces envelope performance standards that favor aluminum over PVC in non-residential segments. Harbor City redevelopment projects specify bi-fold aluminum configurations for spatial flexibility in premium residential units.
Hesse
Frankfurt's financial district commercial towers and surrounding suburban residential stock present bifurcated specification requirements. The state's implementation of federal renovation wave targets forces stepwise efficiency improvements across aging office buildings. Regional fabricators in the Rhine-Main metropolitan area report growing direct-to-consumer channel development as installation scheduling control becomes a competitive differentiator.
Germany Aluminum Door and Window Market Competitive Landscape
Global majors compete with regional champions across certification timelines and thermal performance engineering in German aluminum fenestration. The market structure tilts toward integrated system suppliers with captive extrusion capabilities and distributed installation networks. Three archetypes dominate: integrated profile-extrusion specialists, direct-to-consumer fabricators, and acoustic-security rated system designers. Competitive moves concentrate on pre-certification of next-generation thermal break configurations and direct contracting channels that bypass wholesale intermediaries.
Among Germany-based fabricators, SCHÜCO and Weru Group exemplify the integrated system-supplier archetype through their control over profile production and specification relationships. Neuffer Fenster + Türen occupies a position within the direct-to-consumer tier, leveraging manufacturer-affiliated installation networks. These three entities represent distinct strategic pathways—extrusion integration, specialized performance engineering, and channel restructuring—that collectively illustrate how German aluminum fenestration suppliers respond to tightening thermal regulations and compressed project timelines.
| Leading Market Players |
|---|
| Müller & Sohn Fensterfabrik |
| Fensterfabrik Niederhofer |
| Weru Group |
| Dressler GmbH |
| Fenster Morlok Fensterfabrik |
| SCHÜCO |
| Neuffer Fenster + Türen |
| Unilux |
| Solarlux GmbH |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange aluminum pricing cascades through German extrusion tiers, compressing margins for non-integrated fabricators while rewarding captive smelter arrangements with cost stability across project quoting cycles.
Pricing Analysis
Input-cost pass-through from primary aluminum ingot to finished profile operates on 60-90 day lag contracts, with volatility absorbed differently across supplier tiers. Three-tier pricing structure across premium, standard, and economy levels separates KBA-certified thermal break systems from basic extrusions and PVC-competitive entry products. Pricing pressure stems from EU Carbon Border Adjustment Mechanism exposure threatening low-carbon specification access for importers. Single-family residential developers exhibit highest price sensitivity, while commercial property managers prioritize lifecycle cost over first-cost.
Supply Chain Analysis
KBA energy-efficiency labeling gates specification eligibility, forcing continuous re-certification that filters uncertified imports from commercial bid lists. Primary aluminum supply concentrates in Norway, Iceland, and domestic German smelters for low-carbon metal access. Polyamide thermal break strips, EPDM gaskets, and low-E glass coatings constitute critical component dependencies. Single-source vulnerability runs through Austrian and Swiss thermal break insert specialists. Distribution runs through manufacturer-affiliated installation networks displacing traditional wholesale intermediaries in Bavaria and North Rhine-Westphalia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in thermally broken premium tiers as EU Green Deal deadlines compress substitution elasticity and installation backlogs extend pricing power.
For Market Incumbents: Anchor specification relationships through pre-certified next-generation thermal break portfolios ahead of KBA labeling revisions. Deepen backward integration into low-carbon primary aluminum sourcing to defend against EU Carbon Border Adjustment Mechanism exposure. Prioritize direct-to-consumer channel control in North Rhine-Westphalia's industrial retrofit segment to capture margin from displaced distributor tiers.
For New Entrants and Emerging Players: Begin with acoustic-rated aluminum systems for Hamburg's port-adjacent logistics facilities, where specialized performance requirements limit incumbent saturation. Target bi-fold configuration gaps in premium residential renovation across Munich and Cologne. Pursue manufacturer-affiliated installer certification as primary go-to-market pathway.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale fabricators holding KBA pre-certification pipelines and captive extrusion capacity in Bavaria. Long-term viability favors integrated system suppliers over pure distributors as channel compression accelerates. Watch for EU Carbon Border Adjustment Mechanism implementation timing as inflection trigger for low-carbon aluminum sourcing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Break Pre-Certification | KBA labeling compliance secures commercial specification access ahead of regulatory deadlines. |
| Backward Integration into Extrusion | Captive profile production insulates margins from London Metal Exchange volatility. |
| Direct-to-Consumer Channel Buildout | Manufacturer-affiliated installation networks capture margin from wholesale intermediaries. |
| Low-Carbon Aluminum Sourcing | Nordic and domestic smelter contracts maintain specification access under carbon border rules. |
| Bi-Fold System Premiumization | Spatial flexibility configurations command price premiums in high-density urban renovation. |
Research Methodology
Multiple input streams — primary interviews with fenestration system engineers, procurement leads at housing associations, thermal break technology specialists, and installation contractors — were reconciled against secondary validation from KBA certification databases, Federal Ministry for Economic Affairs and Climate Action transposition documents, and London Metal Exchange price records. Bottom-up volume estimates from state-level building permit data and top-down cross-checks against EU Green Deal renovation wave targets were triangulated to produce segment-level outputs.
Historical installation volumes were cross-referenced against panel input from commercial specification teams and renovation contractors to establish baseline trajectories across the projection horizon. Segmentation modeling incorporated product type, installation channel, end-user category, and material grade dimensions. CAGRs were derived from elasticity-adjusted demand curves responding to efficiency mandate deadlines. Forecast inputs included housing stock age profiles, KBA labeling revision schedules, and industrial building envelope upgrade backlogs.
Several conditions sit outside the modeled scope, including specific EU Carbon Border Adjustment Mechanism implementation dates and potential raw material tariff adjustments. Forecasts reflect underlying assumptions about regulatory timeline adherence and skilled labor availability. A model refresh is warranted upon material change in federal efficiency mandate enforcement intensity or primary aluminum sourcing economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Ireland Cement Market
Building Materials
Block Paving Market
Building Materials
Australia Architectural Coatings Market
Building Materials
Foam Concrete Market
Building Materials
Construction Glass Market
Building Materials
GRC Cladding Market
Building Materials
Cement Tiles Market
Building Materials
Composite Decking and Railing Market
Building Materials
Global FRP Rebar Market
Building Materials
Europe Fiber Cement Market
Building Materials
Recycled Concrete Aggregates Market
Building Materials
South Africa White Cement Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
Brick Adhesive Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Pre-Fabricated Glass Block Market