
 Italy Cement Market | 2026-2036
Italy Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Cement Market Insights
Wholesale dealer networks across Italy's cement sector is fragmenting as bulk buyers seek direct mill relationships to secure volume commitments and lower logistics costs. Heidelberg Materials leverages its integrated quarry-to-terminal footprint across the Po Valley to sustain delivery density. Buzzi SpA anchors its position through deep vertical integration into limestone reserves and captive grinding capacity. Colacem S.p.A. competes via specialized distribution partnerships in central Italy's fragmented construction market.
Cement is a hydraulic binder produced by calcining limestone and clay minerals in rotary kilns at approximately 1,450 degrees Celsius, then grinding the resulting clinker with gypsum to control setting time; its primary function is to bind aggregates into concrete for load-bearing structures. Ordinary Portland Cement dominates volume but faces margin compression from carbon pricing, while Blended Cement with fly ash and slag content is capturing share as public tenders embed lower-emission specifications. Sulphate Resisting Cement commands premium positioning in coastal and wastewater applications across the Adriatic corridor.
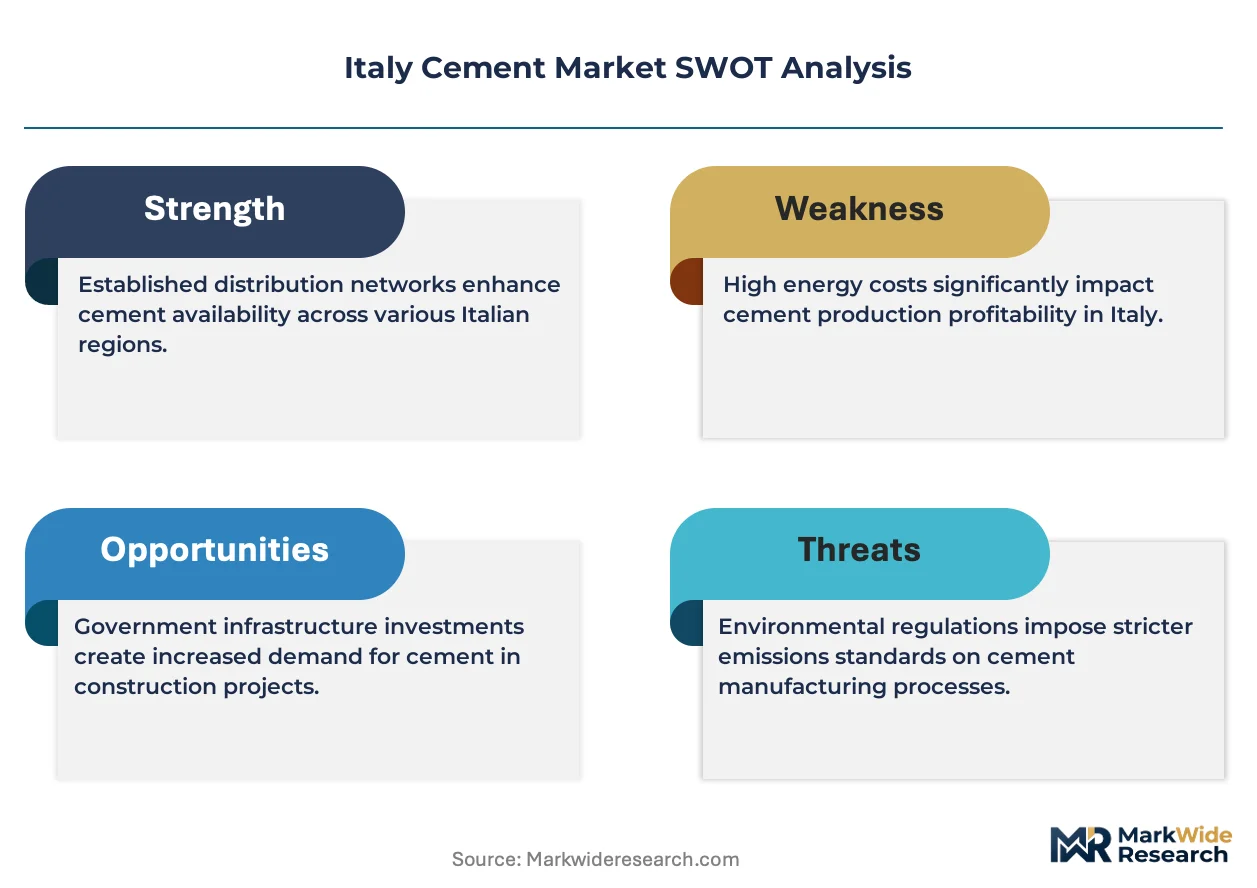
Italy's cement producers operate under the EU Emissions Trading System, national Integrated Pollution Prevention and Control permits, and EU Green Deal-aligned carbon border adjustment frameworks that raise the cost of imported clinker. The National Recovery and Resilience Plan channels public investment toward infrastructure resilience, tightening product certification requirements through the Italian National Unification Body. Stakeholders must monitor how the EU Carbon Border Adjustment Mechanism reshapes import economics and whether domestic alternative fuel substitution keeps pace with tightening free allowance phase-outs.
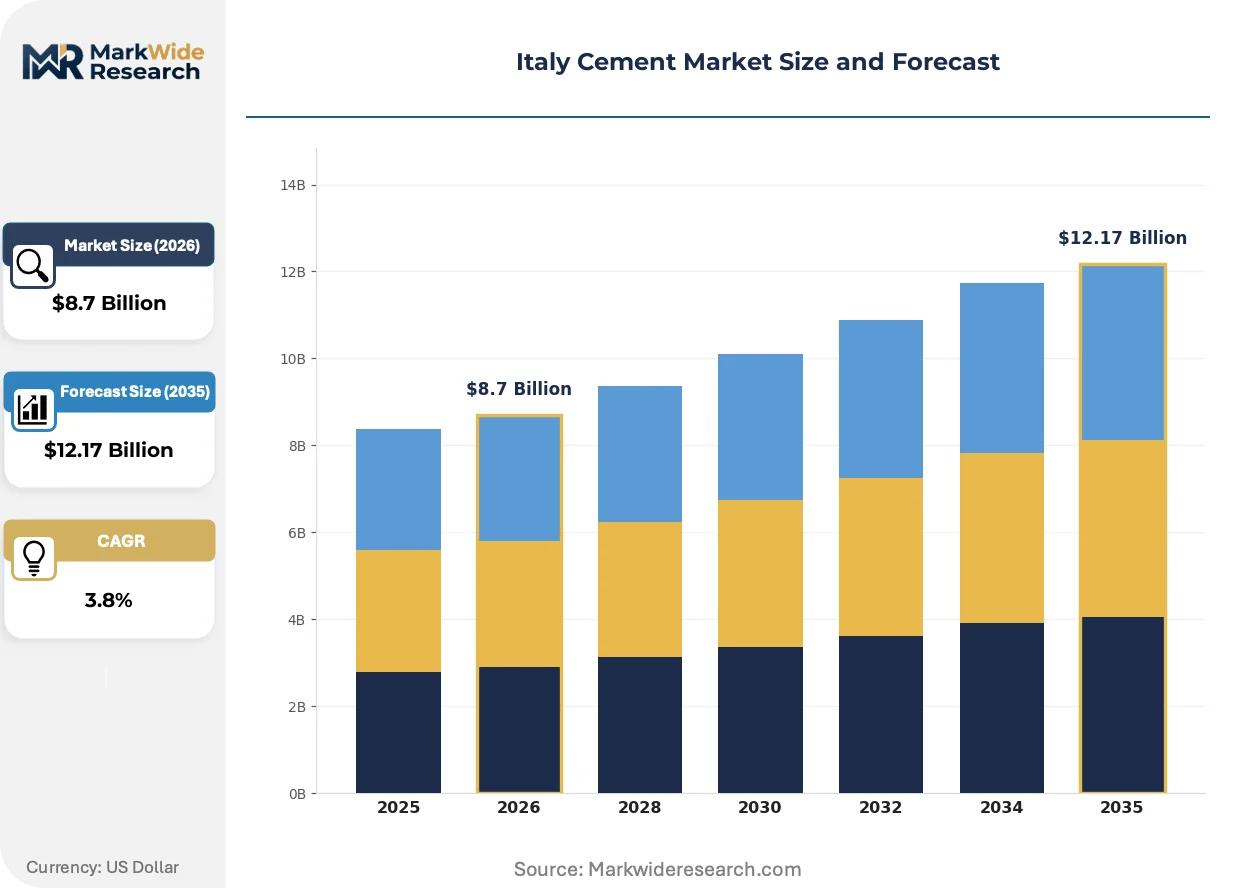
Market Dynamics
The EU Emissions Trading System is compressing kiln economics across Italy, forcing operators to restructure fuel mixes and clinker ratios while public infrastructure tenders accelerate procurement velocity in the Po Valley corridor.
Growth Catalysts
- EU Green Deal infrastructure mandates:The National Recovery and Resilience Plan channels public investment toward flood-defense and high-speed rail projects across Lombardy and Veneto, tightening certification requirements through the Italian National Unification Body.
- Blended cement formulation advances:Fly ash and slag substitution technologies are capturing share as public tenders embed lower-emission specifications, displacing Ordinary Portland Cement in load-bearing applications.
- Alternative fuel kiln retrofitting:Refuse-derived fuel and biomass co-processing systems are reducing carbon intensity at integrated plants operating under tightening free allowance phase-outs.
Market Restraints
- EU Carbon Border Adjustment Mechanism:Imported clinker faces escalating cost disadvantages versus domestic production, yet domestic alternative fuel infrastructure remains concentrated in northern provinces.
- Limestone reserve depletion:Quality carbonate feedstock accessibility is narrowing in central Italy, constrining captive grinding capacity expansion for mid-scale operators.
- Natural gas price volatility:Kiln thermal energy costs fluctuate with continental supply disruptions, compressing margins for plants without refuse-derived fuel integration.
Strategic Opportunities
- Sulphate Resisting Cement specialization:Coastal wastewater and Adriatic marine infrastructure specifications command premium positioning for producers with specialized formulation capabilities.
- Direct mill procurement models:Bulk buyers bypassing wholesale dealer networks seek volume commitments and logistics cost reductions through terminal-to-site delivery contracts.
- Integrated Pollution Prevention and Control permit expansion:Early compliance with tightening BAT conclusions positions operators for public tender pre-qualification advantages under national decarbonization timelines.
Industry Challenges
- Alternative fuel supply chain reconfiguration:Refuse-derived fuel logistics require new storage, handling, and quality assurance protocols at kiln sites historically optimized for pulverized coal.
- Clinker substitution certification timelines:Novel supplementary cementitious material approvals through the Italian National Unification Body extend product commercialization cycles versus conventional formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Cement Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ordinary Portland Cement, Rapid Hardening Cement, Sulphate Resisting Cement, Blended Cement End Use Industry: Residential Construction, Commercial Infrastructure, Industrial Projects, Road Construction Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesale Dealers Application: Precast Structures, Pavements, Mass Concrete, Residential Buildings |
| Companies Covered | Alpacem, Vicat, Heidelberg Materials, Italsacci, Cementir, Buzzi SpA, Holcim, Cemitaly, Colacem S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Cement Market Trends and Innovations
Digital twin technology is virtualizing production planning across Italian cement manufacturing, compressing energy intensity while predictive maintenance systems reshape asset utilization economics.
Carbon capture utilization and storage integration is virtualizing emission liability for integrated kiln operators. Heidelberg Materials and Buzzi SpA are piloting post-combustion capture at Po Valley facilities. This technology is compressing the effective carbon cost exposure for early adopters under EU ETS phase-out trajectories.
The EU Carbon Border Adjustment Mechanism reshapes import economics for clinker and finished cement entering Italian terminals. Domestic producers gain relative positioning versus Turkish and North African supply sources. Blended cement formulations with high substitution rates are capturing tender share as carbon-adjusted pricing disadvantages conventional Portland imports.
Buyer concentration among public infrastructure consortia is consolidating procurement leverage in northern regions. Direct mill relationships are displacing traditional wholesale dealer networks for volume commitments exceeding fifty thousand tonnes annually. This pattern concentrates in Lombardy and Veneto where high-speed rail and flood-defense megaprojects accelerate material offtake cycles.
Italy Cement Market Segmentation
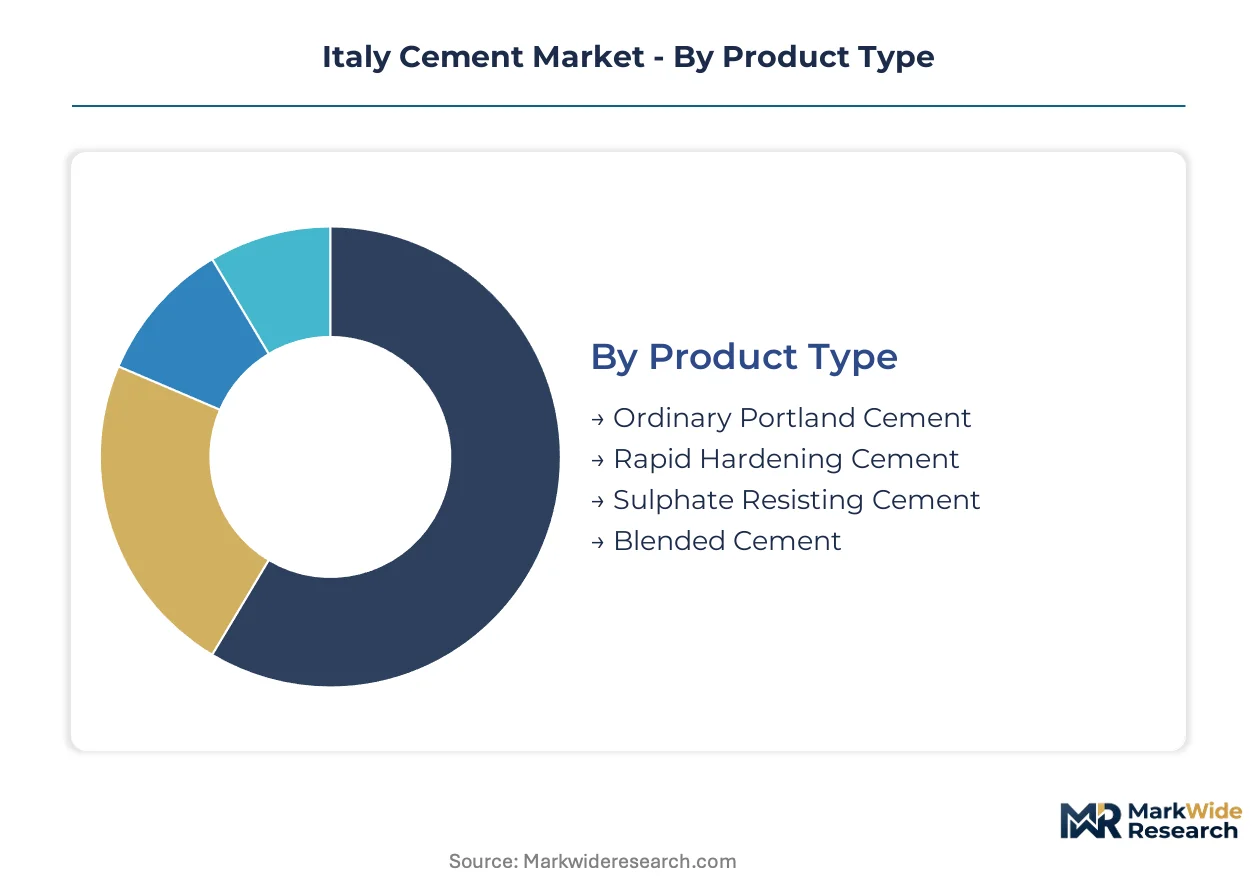
Product differentiation in the Italy cement market tracks closely with after-sales technical support intensity, as specialized formulations require application engineering assistance that commodity grades do not. Segment boundaries increasingly blur where carbon pricing and procurement consolidation reshape volume allocation across formulation types and delivery channels.
Product Type:
After-sales service intensity varies sharply across cement formulations, with specialty grades demanding field technical support that commodity products bypass entirely.
- Ordinary Portland Cement:Standard calcium silicate composition with 95% clinker content serves general construction across Lombardy and Veneto. Demand concentrates in residential foundations and standard commercial slabs where procurement offices prioritize volume certainty over formulation complexity.
- Blended Cement:Fly ash and blast furnace slag substitution reduces clinker ratios below 65%, capturing public tender share as the National Recovery and Resilience Plan embeds lower-emission specifications. Northern megaprojects accelerate procurement cycles for this grade.
- Sulphate Resisting Cement:Tricalcium aluminate content below 5% protects against sulphate attack in Adriatic coastal wastewater infrastructure and marine applications.
- Rapid Hardening Cement:Finer grinding and elevated tricalcium silicate content achieves 24-hour strength thresholds for precast yard turnaround schedules.
By volume, Ordinary Portland Cement leads. By growth pace, Blended Cement is ahead.
End Use Industry:
Cost tier stratification separates premium-specification industrial buyers from price-sensitive residential developers operating on thinner margin structures.
- Residential Construction:Single-family and multi-unit housing developments across central Italy drive baseline demand for standard-grade formulations with minimal technical service requirements.
- Commercial Infrastructure:Office complexes and retail centers in Milan and Turin specify higher-performance blends with certified low-carbon credentials for green building compliance.
- Industrial Projects:Manufacturing facilities and logistics hubs demand specialized sulphate-resistant and rapid-hardening grades with intensive quality assurance protocols.
- Road Construction:Highway and bridge contracts through ANAS procurement channels prioritize volume scalability and delivery precision over formulation sophistication.
Residential Construction anchors absolute tonnage. Commercial Infrastructure climbs fastest on decarbonization-linked tender specifications.
Distribution Channel:
Customer type fragmentation—bulk public consortia versus fragmented small contractors—drives channel bifurcation toward direct mill relationships or retail pickup.
- Direct Sales:Terminal-to-site delivery contracts serve public infrastructure consortia and ready-mix operators exceeding fifty thousand tonnes annually, bypassing wholesale markups.
- Wholesale Dealers:Regional distributors maintain inventory positions for mid-scale contractors lacking storage infrastructure, though their network share erodes under bulk buyer consolidation.
- Retail Stores:Builder merchants and construction supply yards capture small contractor and renovation demand with bagged product availability.
- Online Platforms:Digital procurement portals emerge for standardized grades where specification certainty reduces pre-purchase inspection requirements.
Direct Sales commands the largest volume flows. Online Platforms expand most quickly from minimal base penetration.
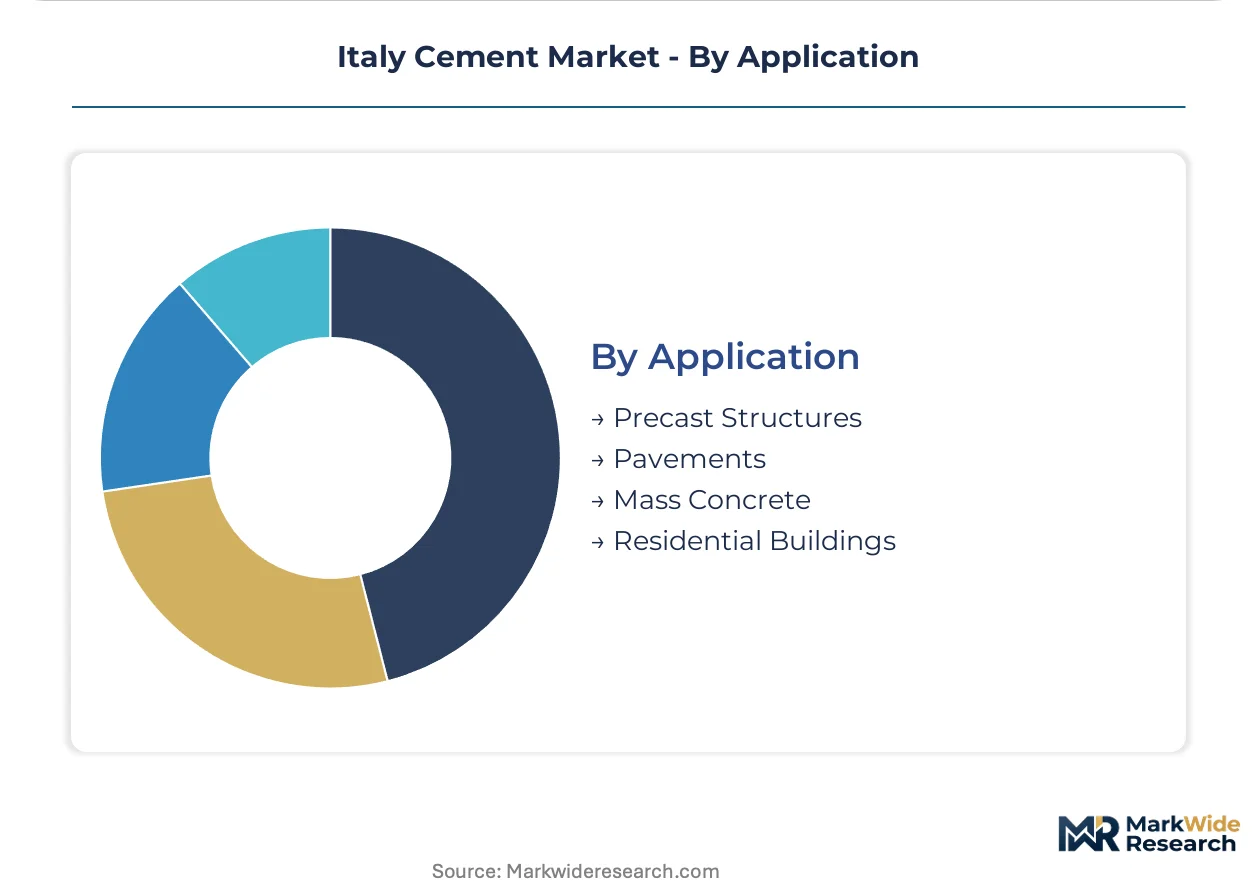
Application:
Supply concentration in precast yard clusters and megaproject corridors determines regional formulation availability and logistics configuration.
- Precast Structures:Factory-cast beams, panels, and tunnel segments demand rapid-hardening grades with controlled curing protocols for yard throughput optimization.
- Residential Buildings:Load-bearing walls and foundations across Emilia-Romagna and Tuscany consume standard Portland and blended formulations through established dealer networks.
- Pavements:Road surface and airport runway specifications prioritize abrasion resistance and freeze-thaw durability in northern climate zones.
- Mass Concrete:Dam foundations and heavy retaining walls require low-heat-of-hydration blended formulations to control thermal cracking in thick sections.
Residential Buildings dominates tonnage. Precast Structures gains share fastest on infrastructure prefabrication trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Brenner Base Tunnel anchors northern Italy's cement demand through its 64-kilometer rail corridor connecting Verona to Innsbruck. This megaproject underwrites procurement volumes across the Po Valley industrial belt.
Lombardy
Milan's high-speed rail expansion and flood-defense infrastructure drive blended cement procurement. The National Recovery and Resilience Plan channels public investment through Lombardy's metropolitan authority. Bergamo and Brescia host precast yard clusters supplying tunnel segments for Brenner corridor contracts.
Veneto
Venice MOSE flood barriers and Port of Venice dredging operations specify sulphate-resistant formulations. The EU Emissions Trading System compliance deadlines tighten kiln operations at Vicenza and Padua plants. Verona serves as the logistics hub for Brenner Base Tunnel material flows.
Piedmont
Turin's commercial infrastructure and Alpine tunnel maintenance sustain ordinary Portland demand. The Italian National Unification Body certifies low-carbon blends for public tenders. Novara and Alessandria grinding terminals distribute into Switzerland and southeastern France.
Emilia-Romagna
Bologna-Florence high-speed rail and Po River embankment rehabilitation accelerate material offtake. Regional environmental permits restrict alternative fuel kiln retrofits in densely populated corridors. Modena and Parma precast producers supply infrastructure consortia with rapid-hardening grades.
Lazio
Rome's metropolitan transit expansion and Tiber flood management sustain baseline consumption. Lazio's limestone reserves support captive grinding capacity for central Italy distribution. Civitavecchia port terminals handle clinker imports subject to EU Carbon Border Adjustment Mechanism pricing.
Italy Cement Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in quarry and grinding operations. Italy's cement sector consolidates around vertically integrated kiln operators and regional grinding terminals. Three archetypes dominate: multinational platforms with EU-wide logistics networks, family-controlled domestic producers with captive limestone reserves, and independent grinding specialists serving fragmented construction markets. Competitive moves center on alternative fuel kiln retrofits and direct procurement contracts with public infrastructure consortia.
Among Germany-based multinationals, Heidelberg Materials anchors integrated production across the Po Valley quarry-to-terminal footprint. Buzzi SpA exemplifies family-controlled domestic consolidation with deep upstream control over limestone reserves and captive grinding capacity. Colacem S.p.A. occupies a position within central Italy's specialized distribution tier, serving fragmented construction markets through regional partnership networks.
| Leading Market Players |
|---|
| Alpacem |
| Vicat |
| Heidelberg Materials |
| Italsacci |
| Cementir |
| Buzzi SpA |
| Holcim |
| Cemitaly |
| Colacem S.p.A. |
| Others |
Pricing and Supply Chain Analysis
EU Carbon Border Adjustment Mechanism exposure determines both pricing tier spreads and supply chain shape across Italian cement markets, compressing import economics while rewarding domestic alternative fuel integration with margin protection.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts, with public infrastructure consortia securing sub-market rates through fifty-thousand-tonne annual commitments while fragmented residential contractors absorb wholesale markups. Price differentiation rests on certification grade—EU ETS compliance tiers and UNI EN 197-1 specification levels—and geographic delivery cost from Po Valley kilns to Adriatic terminals. Cost compression in standard Portland grades is intensifying because Turkish and North African imports face escalating carbon-adjusted duties. Residential developers operating on thin margin structures exhibit highest price sensitivity; industrial buyers specifying sulphate-resistant formulations for coastal wastewater infrastructure show lowest.
Supply Chain Analysis
Export-control regime angles on clinker technology transfers limit kiln retrofit equipment flows from Germany and Denmark to Italian operators, constraining alternative fuel adoption timelines. Geographic supply concentrates in Turkey, Egypt, and Algeria for imported clinker feeding coastal grinding terminals. Raw material dependencies center on quality limestone from Lombardy and Veneto quarries, refuse-derived fuel from northern waste-to-energy networks, and gypsum from Sicilian evaporite deposits. Single-source vulnerability runs through natural gas supply for thermal energy at plants lacking biomass co-processing. Distribution runs through direct terminal-to-site contracts for bulk buyers and regional dealer networks for fragmented contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian cement markets track a cyclical recovery anchored to National Recovery and Resilience Plan infrastructure disbursement schedules, with public procurement velocity in northern megaprojects driving volume inflection.
For Market Incumbents: Build captive alternative fuel infrastructure as a moat against EU ETS allowance phase-outs. Secure Integrated Pollution Prevention and Control permit expansions ahead of tightening BAT conclusions to lock in public tender pre-qualification. Deepen upstream control over limestone reserves in Veneto and Lombardy to constrain mid-scale competitor grinding capacity expansion. For New Entrants and Emerging Players: Central Italy's fragmented construction markets present underpenetration for specialized distribution partnerships targeting mid-scale contractors bypassed by direct mill procurement consolidation. White-space targets include rapid-hardening cement for Emilia-Romagna precast yards and blended formulations for green building compliance in Rome commercial developments. Go-to-market through regional builder merchant networks with technical application support. For Investors and Strategic Acquirers: The market sits at a mid-cycle recovery phase that favors integrated kiln operators with captive fuel substitution assets over pure-play grinding terminals. Long-term viability across the analysis window hinges on EU ETS compliance positioning and alternative fuel infrastructure deployment. Acquisition target archetype: family-controlled domestic producers with limestone reserve control and pending permit expansions. Signal to watch: EU Carbon Border Adjustment Mechanism enforcement intensity on Turkish clinker imports.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Fuel Kiln Retrofit | Refuse-derived fuel integration reduces EU ETS exposure at Vicenza and Padua plants. |
| Clinker Substitution R&D | Fly ash and slag formulation advances capture public tender share under Green Deal specifications. |
| Direct Procurement Contracting | Terminal-to-site delivery bypasses wholesale markups for Brenner Base Tunnel consortia. |
| Carbon Capture Pilot Deployment | Post-combustion systems at Po Valley facilities compress effective carbon cost liability. |
| Sulphate-Resistant Grade Specialization | Adriatic coastal wastewater specifications command premium positioning for formulation specialists. |
Research Methodology
Initial hypotheses were tested against primary input from kiln operations managers, public infrastructure procurement officers, ready-mix plant directors, and wholesale distribution partners and refined through secondary validation against ANAS contract disclosures, EU ETS transaction registries, UNI certification databases, and customs import records. Bottom-up capacity utilization data from integrated plants was triangulated against top-down public investment flow tracking from National Recovery and Resilience Plan disbursement schedules.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling volume trajectories by product formulation type, end-use industry vertical, distribution channel structure, and regional infrastructure pipeline status. CAGRs were derived from elasticity-adjusted consumption coefficients applied to megaproject procurement schedules and residential construction permit flows. Industry-specific forecast inputs included EU ETS carbon price scenarios and alternative fuel substitution rate assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Turkish clinker exporters or accelerated EU Carbon Border Adjustment Mechanism enforcement would shift outcomes. Material shifts in EU ETS free allowance phase-out timelines or National Recovery and Resilience Plan disbursement delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Indonesia Concrete Admixtures Market
Building Materials
Mass Timber Construction Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Cementitious Waterproofing Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Composite Rebar Market
Building Materials
Spain Architectural Coatings Market
Building Materials
Commonwealth of Independent States (CIS) Building and Construction Sheets Market
Building Materials
Europe Dry-Mix Mortar Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Rapid Strength Concrete Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
Global Builders Joinery and Carpentry of Wood Market