
 China Aluminum Door and Window Market | 2026-2036
China Aluminum Door and Window Market Size, Share, and Industry Trends Forecast 2026-2036
China Aluminum Door and Window Market Insights
Buyer concentration across China's aluminum door and window sector is broadening from traditional state-owned developers toward private high-rise contractors and premium residential architects. Xingfa Aluminum leverages its vertical extrusion capacity to serve this fragmented but quality-demanding tier. Weiye Aluminium Group anchors southern China supply chains through integrated melting and finishing operations. Zhongwang Group competes on structural-grade aluminum for commercial facades, differentiating through alloy customization rather than volume scale.
China aluminum doors and windows are fabricated from extruded aluminum profiles, typically alloyed with magnesium and silicon for tensile strength between 160-310 MPa, then thermally broken with polyamide strips to achieve U-values below 2.0 W/m²K for energy-efficient building envelopes. Their primary purpose spans climate-controlled residential interiors, curtain-wall commercial towers, and industrial facilities requiring corrosion-resistant daylighting. Sliding doors and casement windows occupy the mature volume tier where powder-coated finishes dominate specification sheets, while bi-fold doors represent the fastest-growing product category as luxury residential developers in Chengdu and Hangzhou prioritize indoor-outdoor living configurations. Structural aluminum commands the deepest margin pool because high-rise developments require engineered load-bearing profiles that few domestic mills certify consistently.
China's GB 50411 standard for energy-efficient building envelopes and the Ministry of Housing and Urban-Rural Development's green building evaluation system shape product compliance thresholds, forcing manufacturers to invest in thermal-break extrusion and low-emissivity glazing compatibility. MIIT's dual carbon goals pressure smelters and downstream fabricators to document carbon intensity per ton of processed aluminum, which reshapes supplier qualification for state-backed projects. Stakeholders must monitor how provincial implementation of these national standards varies between first-tier cities and interior provinces, as enforcement consistency determines which fabricators retain market access versus face exclusion from public procurement pipelines.
Market Dynamics
China's dual carbon goals are compressing the aluminum door and window supply base, as MIIT's carbon intensity documentation requirements disqualify fabricators lacking smelter-to-finish traceability from state-backed procurement pipelines.
Growth Catalysts
- GB 50411 thermal-break mandates:Shenzhen and Shanghai enforcement of energy-efficient building envelope standards forces specification upgrades across high-rise developments, filtering low-grade suppliers from premium project pipelines.
- High-rise commercial facades:Load-bearing structural aluminum systems absorb disproportionate engineering investment as developers pursue green building certifications from the Ministry of Housing and Urban-Rural Development.
- Polyamide thermal-break extrusion:Domestic mills achieving consistent U-values below 2.0 W/m²K capture specification share from imports in climate-controlled residential and commercial towers.
Market Restraints
- Primary aluminum price volatility:Smelter power cost fluctuations in Yunnan and Xinjiang transmit directly to extrusion margins, compressing fabricators lacking captive alloy supply.
- Structural-grade certification scarcity:Few domestic mills consistently certify engineered load-bearing profiles for high-rise curtain walls, creating supply bottlenecks for premium commercial projects.
- Low-emissivity glazing compatibility gaps:Thermal-break systems requiring specialized glazing interfaces face specification friction where glass supply chains lag aluminum fabrication cycles.
Strategic Opportunities
- Hangzhou and Chengdu luxury residential:Bi-fold door configurations for indoor-outdoor living command margin premiums as private developers differentiate premium units.
- Provincial green building incentives:First-tier city implementation of national standards outpaces interior provinces, creating arbitrage windows for compliant fabricators expanding westward.
- Powder-coat and anodize convergence:Finishing technology integration with thermal-break extrusion enables single-source contracting that reduces project coordination costs for architects.
Industry Challenges
- Thermal-break extrusion technician scarcity:Polyamide strip insertion and precision cutting skills concentrate in Guangdong and Jiangsu, limiting expansion capacity for inland fabricators.
- GB standard compliance timeline compression:Rapid tightening of thermal insulation specifications forces simultaneous equipment and process retooling without grandfathering periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Aluminum Door and Window Market |
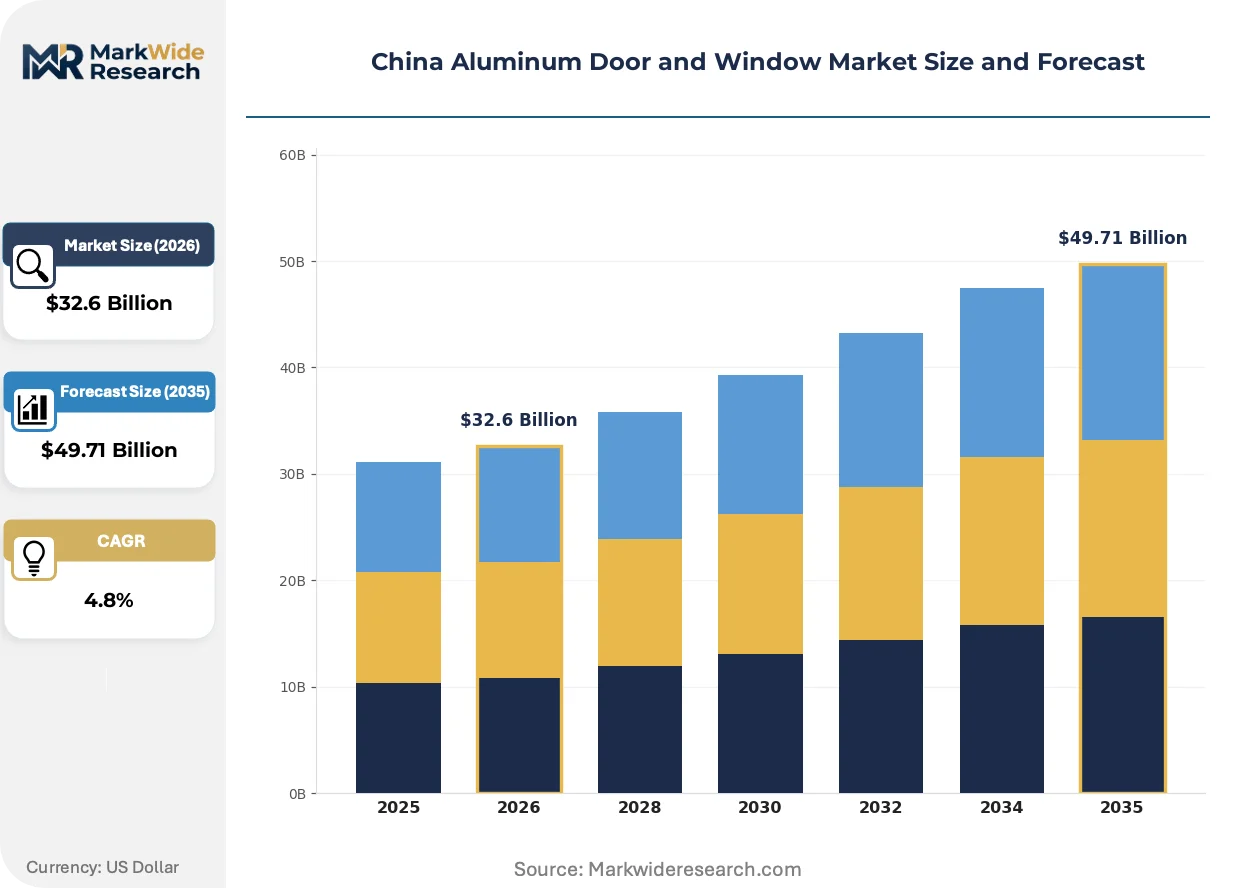
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $49.71 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Casement Windows, Bi-Fold Doors, Fixed Windows Application: Residential Buildings, Commercial Spaces, Industrial Facilities, High-Rise Developments Material Grade: Extruded Aluminum, Anodized Aluminum, Powder-Coated Aluminum, Structural Aluminum Customer Type: Contractors, Architects, End Consumers, Building Developers |
| Companies Covered | Xingfa Aluminum, Weiye Aluminium Group, Zhongwang Group, Fenglu Aluminum, JMA Aluminum, Doorwin Group, Superhouse Windows & Doors, Ya Ji Aluminum, ROPO Aluminium Windows & Doors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Aluminum Door and Window Market Trends and Innovations
Digital specification tools and low-carbon material tracing are reshaping how architects and contractors qualify aluminum systems, compressing traditional supplier relationships into data-driven procurement workflows.
Smart facade monitoring systems are converging with aluminum curtain wall installations, embedding sensors for thermal performance and structural load tracking. High-rise developers in Shanghai and Shenzhen pilot these integrated systems to satisfy green building certification requirements. This convergence is compressing the traditional separation between envelope fabrication and building automation contracting.
MIIT's carbon intensity documentation mandates now require smelter-to-finish traceability for state-backed project eligibility. Fabricators must retrofit supply chain accounting systems to capture per-ton emissions data across extrusion, thermal-break processing, and finishing stages. Southern China mills with integrated melting operations respond fastest, while independent fabricators face qualification gaps.
Architects in Chengdu and Hangzhou now specify bi-fold door systems through direct mill relationships rather than traditional distributor channels. Premium residential developers unbundle after-sales service contracts to capture margin previously allocated to regional distributors. This channel compression is most visible in luxury residential segments where customization requirements exceed distributor technical capabilities.
China Aluminum Door and Window Market Segmentation
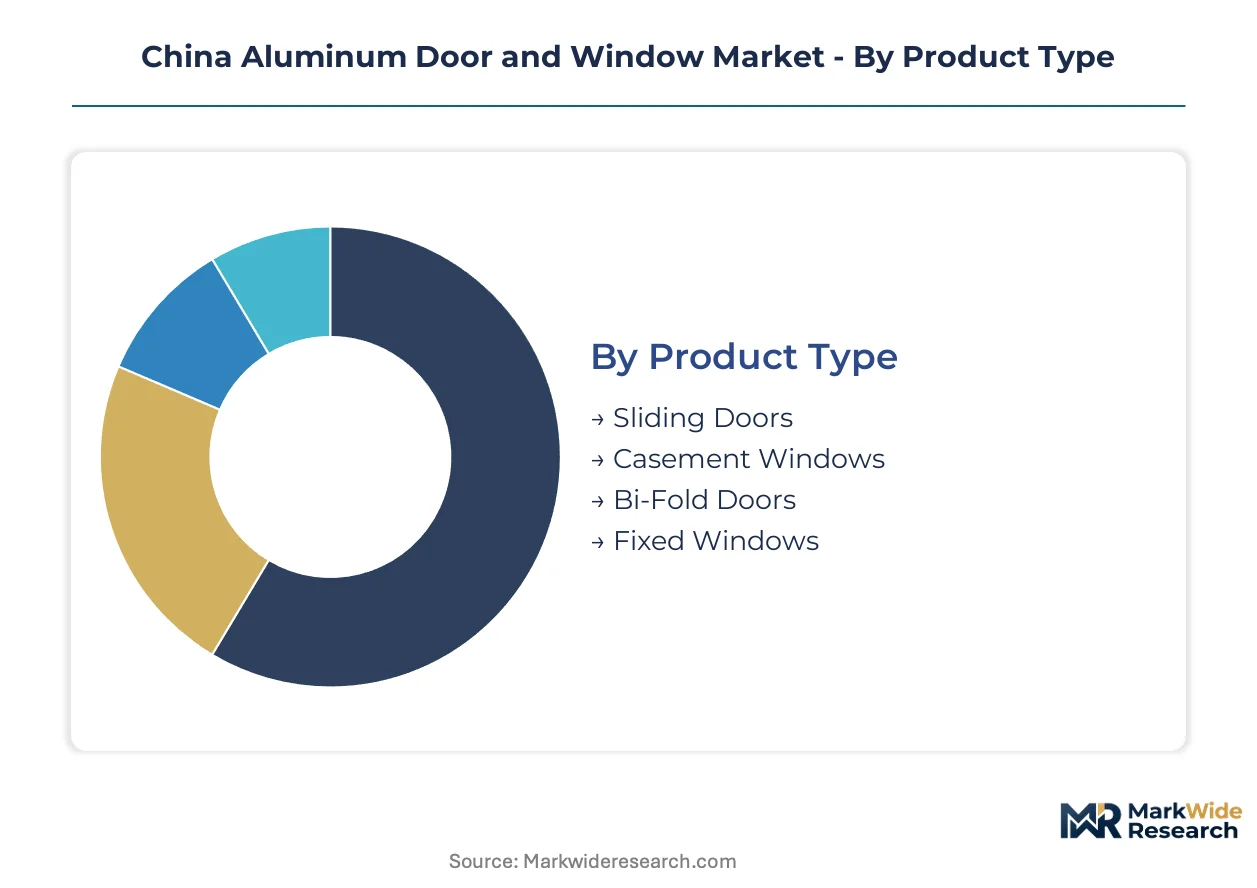
China's aluminum door and window market fragments across product architecture, end-use intensity, material specification, and procurement authority. Each dimension reveals distinct margin pools and compliance thresholds that reshape supplier positioning.
Product Type:
Integration depth separates standalone operable units from fixed architectural elements, with thermal performance requirements dictating fabrication complexity.
- Sliding Doors:Horizontal track systems using 6063-T5 alloy extrusions with U-values typically ranging 2.0-2.5 W/m²K dominate mass residential construction in Guangdong and Jiangsu provinces. Volume concentration in southern China reflects established extrusion infrastructure and powder-coat finishing clusters.
- Casement Windows:Side-hinged configurations with multi-point locking hardware achieve superior air tightness for climate-controlled interiors. Demand clusters in Beijing and Tianjin where GB 50411 enforcement is strictest, forcing thermal-break specifications that filter non-compliant fabricators.
- Bi-Fold Doors:Multi-panel folding systems for indoor-outdoor living command premium specifications in Chengdu and Hangzhou luxury residential.
- Fixed Windows:Non-operable glazing frames for commercial curtain walls prioritize structural load-bearing over thermal performance.
Sliding doors lead volumes today; bi-fold doors are gaining share fastest.
Application:
End-use intensity creates tiered engineering requirements, with high-rise commercial facades demanding certified structural performance that residential retrofit cannot match.
- High-Rise Developments:Curtain wall and unitized facade systems require engineered load-bearing aluminum profiles certified to GB/T 5237 structural grades. Shenzhen and Shanghai developers absorb disproportionate engineering investment as green building certification mandates from the Ministry of Housing and Urban-Rural Development tighten specification thresholds.
- Residential Buildings:Single-family and multi-family housing drives volume throughput for standard thermal-break windows and sliding door systems. Provincial implementation gaps between first-tier cities and interior provinces create arbitrage opportunities for compliant fabricators expanding westward.
- Commercial Spaces:Office and retail fit-outs prioritize rapid installation and standardized dimensions over custom engineering.
- Industrial Facilities:Corrosion-resistant daylighting systems for manufacturing plants emphasize durability coatings over thermal performance.
Residential buildings anchor volume scale; high-rise developments capture the deepest margin pools.
Material Grade:
Surface treatment and alloy specification stratify cost tiers, with structural grades requiring smelter-to-finish traceability that MIIT carbon documentation mandates now enforce.
- Structural Aluminum:6061-T6 and 6082-T6 alloys with tensile strength exceeding 290 MPa serve engineered load-bearing applications. Few domestic mills achieve consistent certification for high-rise curtain walls, creating supply bottlenecks where Shenzhen and Shanghai developers compete for qualified capacity.
- Powder-Coated Aluminum:Electrostatic polyester or fluoropolymer finishes dominate visible architectural surfaces for color durability. Guangdong finishing clusters integrate with thermal-break extrusion lines to reduce project coordination costs for southern China contractors.
- Anodized Aluminum:Electrochemical oxide layers provide wear resistance for high-traffic commercial entrances.
- Extruded Aluminum:Mill-finish profiles for concealed structural elements or secondary finishing operations.
Powder-coated aluminum leads specification frequency; structural aluminum commands the steepest expansion trajectory in value terms.
Customer Type:
Procurement authority is concentrating toward direct mill relationships as technical specification complexity exceeds distributor capabilities.
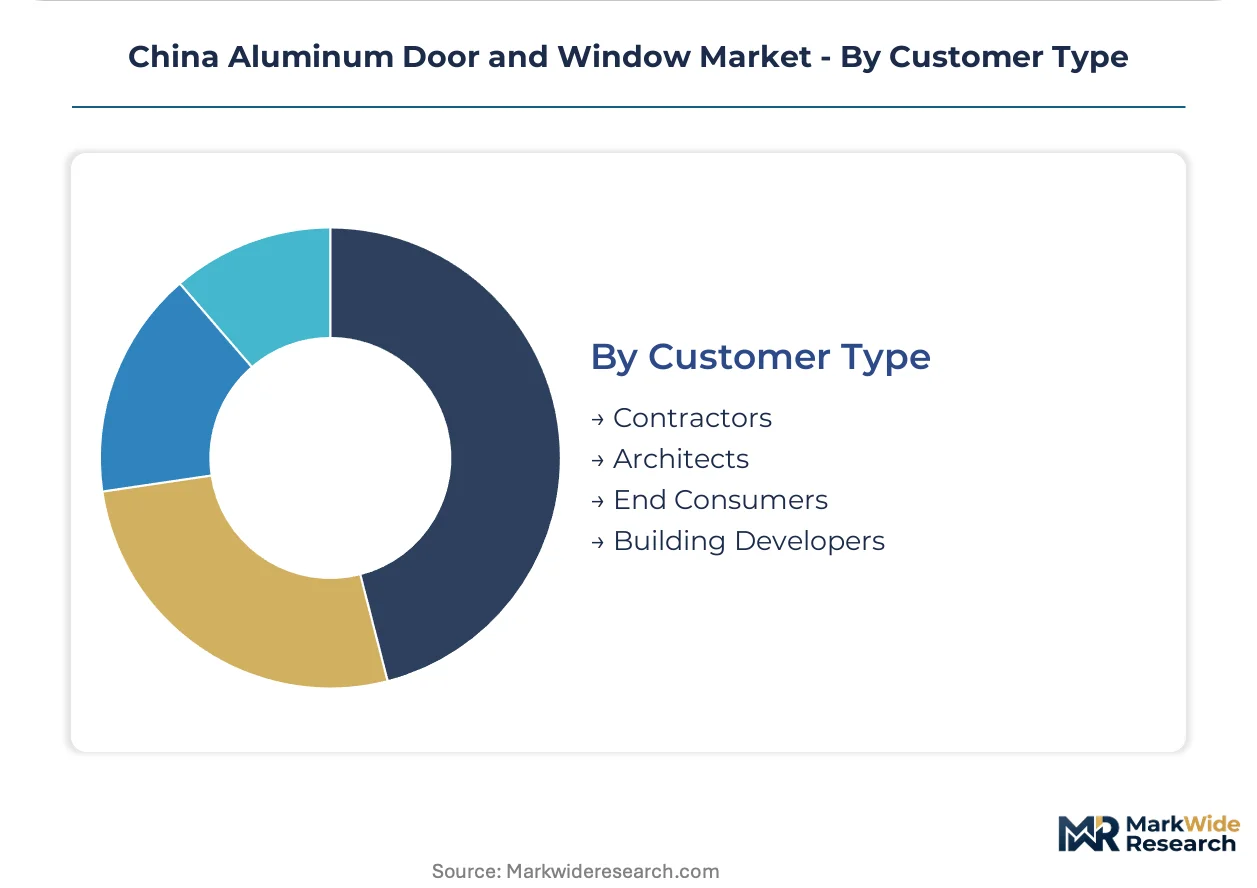
- Building Developers:State-owned and private developers now specify aluminum systems directly, unbundling after-sales service contracts to capture margin previously allocated to regional distributors. Hangzhou and Chengdu luxury residential segments show the most advanced channel compression.
- Architects:Design professionals increasingly specify through digital tools that embed thermal performance data and carbon intensity documentation, compressing traditional supplier relationships into data-driven procurement workflows.
- Contractors:Installation-focused procurement emphasizes logistics reliability and dimensional standardization over technical customization.
- End Consumers:Individual homeowners drive replacement demand through retail channels with limited thermal-break penetration.
Building developers control the largest contract values; architects are reshaping specification authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermal-break extrusion technicians concentrate in Guangdong and Jiangsu provinces, anchoring fabrication capacity along China's eastern seaboard while inland expansion faces talent migration barriers.
Guangdong Province
Shenzhen's high-rise developers absorb premium structural aluminum systems as green building certification mandates tighten. MIIT's dual carbon goals pressure fabricators to document carbon intensity per ton of processed aluminum. Foshan's extrusion and finishing clusters integrate thermal-break lines with powder-coat operations, reducing project coordination costs for southern contractors.
Jiangsu Province
Shanghai's enforcement of GB 50411 thermal-break standards filters non-compliant suppliers from state-backed procurement pipelines. The Ministry of Housing and Urban-Rural Development's green building evaluation system shapes specification thresholds across the Yangtze River Delta. Suzhou fabricators leverage proximity to architectural design hubs, compressing traditional distributor channels through direct mill relationships.
Beijing-Tianjin-Hebei
Stringent climate-control requirements for residential retrofits drive casement window specifications with multi-point locking hardware. GB standards for thermal insulation in building envelopes tighten faster here than in interior provinces. Tianjin's port access enables alloy import flexibility, though local extrusion capacity lags Guangdong in thermal-break technician density.
Sichuan-Chongqing
Chengdu's luxury residential developers prioritize bi-fold door configurations for indoor-outdoor living, commanding margin premiums over standard sliding systems. Provincial implementation of national green building standards trails first-tier cities, creating arbitrage windows for compliant fabricators expanding westward. Chongqing's inland location increases logistics costs for coastal alloy supply, favoring fabricators with captive melting operations.
Shandong Peninsula
Industrial daylighting applications emphasize corrosion-resistant coatings over thermal performance, segmenting demand from commercial facade markets. Local fabricators serve manufacturing plant retrofits with mill-finish or anodized profiles rather than thermal-break systems. Qingdao's port infrastructure supports export-oriented finishing operations, though structural-grade certification for high-rise work remains concentrated in southern mills.
China Aluminum Door and Window Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across China's aluminum door and window sector, creating a tiered structure where scale-driven mills and customization-oriented fabricators occupy distinct margin pools. The vendor base stratifies by certification depth: integrated smelter-to-finish operators capture state-backed procurement, while independent extruders serve residential retrofit channels. Three archetypes dominate—vertically integrated southern mills with captive alloy supply, precision-focused specialists in thermal-break engineering, and regional fabricators competing on logistics proximity. Competitive dynamics center on backward integration into primary aluminum and geographic expansion into enforcement-lagging interior provinces.
Among southern China's integrated operators, Xingfa Aluminum and Weiye Aluminium Group exemplify the smelter-to-finish archetype with extrusion capacity anchored in Guangdong's industrial clusters. Zhongwang Group occupies a position emphasizing structural-grade alloy customization rather than volume scale, representing the engineering-specialist tier that serves high-rise commercial facade requirements. These three entities illustrate how certification depth and supply chain control separate premium-tier suppliers from commodity competitors in procurement pipelines shaped by MIIT carbon documentation mandates.
| Leading Market Players |
|---|
| Xingfa Aluminum |
| Weiye Aluminium Group |
| Zhongwang Group |
| Fenglu Aluminum |
| JMA Aluminum |
| Doorwin Group |
| Superhouse Windows & Doors |
| Ya Ji Aluminum |
| ROPO Aluminium Windows & Doors |
| Others |
Pricing and Supply Chain Analysis
Family-owned extrusion specialists in Guangdong and Jiangsu provinces anchor supply-side discipline through generational control over thermal-break technician networks, translating workforce retention into pricing power that resists commodity erosion despite primary aluminum volatility.
Pricing Analysis
The bundled-versus-unbundled service split separates project-based contracting from single-source specification. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service inclusion. Cost compression in the economy tier is intensifying because independent fabricators lack captive alloy supply. State-backed developers show least price sensitivity, while retail replacement channels absorb maximum margin pressure.
Supply Chain Analysis
Thermal-break extrusion technician scarcity in Guangdong and Jiangsu provinces concentrates fabrication capacity along China's eastern seaboard. The supply chain draws from Yunnan and Xinjiang smelters for primary aluminum, polyamide strip imports for thermal-break cores, and low-emissivity glass from domestic float-glass producers. Single-source vulnerability sits with structural-grade certification mills serving high-rise curtain wall demand. Distribution runs through direct mill relationships with developers, compressing traditional regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's aluminum door and window market represents a late-cycle quality story as GB 50411 enforcement shifts procurement toward certified thermal-break systems that filter commodity suppliers from premium pipelines.
For Market Incumbents: Deepen backward integration into captive melting operations to secure carbon intensity documentation required by MIIT dual carbon goals. Invest in polyamide thermal-break extrusion certification to defend against emerging precision-focused specialists capturing high-rise commercial share. Consolidate technician training pipelines in Guangdong and Jiangsu to lock in workforce scarcity advantages. For New Entrants and Emerging Players: Digital specification platforms for architect-direct procurement offer the lowest-friction entry vector. Target Chengdu and Hangzhou luxury residential bi-fold door segments where customization requirements exceed incumbent distributor capabilities. Pursue white-label thermal-break fabrication partnerships with southern mills lacking western China logistics presence. For Investors and Strategic Acquirers: Valuations sit cheapest among independent fabricators with GB 50411 compliance gaps but intact extrusion infrastructure. Five-to-ten year viability hinges on carbon traceability system deployment and provincial green building standard adoption curves. Monitor MIIT enforcement consistency across interior provinces as the inflection signal for qualification-driven consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Smelting | Captive primary aluminum supply secures MIIT carbon documentation for state-backed procurement eligibility. |
| Thermal-Break Certification Investment | GB 50411 compliance unlocks specification access in Beijing and Shanghai enforcement zones. |
| Direct Architect Channel Development | Digital specification tools compress distributor margins and capture premium customization revenue. |
| Westward Expansion to Sichuan-Chongqing | Arbitrage windows emerge where provincial green building implementation trails first-tier city enforcement. |
| Smart Facade System Integration | Sensor-embedded curtain walls satisfy Ministry of Housing green building certification requirements. |
Research Methodology
Direct dialogue with extrusion plant managers, thermal-break process engineers, procurement leads at state-owned developers, and architect specification consultants grounded the qualitative foundation. Secondary validation drew from MIIT policy circulars, Ministry of Housing green building evaluation system documentation, GB standards publications, and customs trade data for aluminum alloy imports. Bottom-up capacity modeling and top-down demand estimation triangulated market sizing across the analysis window.
Segment-level outputs reflect product architecture, end-use intensity, material specification grade, and procurement authority dimensions modeled throughout the forecast period. CAGRs derived from province-level construction permit analysis and thermal-break penetration curves by building type. Primary aluminum price volatility assumptions and GB standard enforcement timelines served as key forecast sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for smart facade sensor integration would alter the outlook for premium system demand. Forecasts reflect documented assumptions regarding provincial implementation speed and carbon documentation compliance thresholds. Material deviation in MIIT enforcement consistency or primary aluminum power cost regimes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
GRC Cladding Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Roofing and Insulation Market
Building Materials
Asia-Pacific Facade Market
Building Materials
Construction Repair Composites Market
Building Materials
East Africa White Cement Market
Building Materials
Europe Concealed Cistern Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
GCC Concealed Cistern Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
Stone Adhesive Market
Building Materials
Construction Coatings Market
Building Materials
Africa Green Cement Market
Building Materials
Ireland Cement Market