
 Thin Brick Market | 2026-2036
Thin Brick Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Brick Market Insights
Prefabricated panel installation services are repositioning how thin brick reaches commercial job sites, shifting value from raw material supply to finished subsystem delivery. General Shale leverages captive clay reserves across Appalachia to sustain cost advantages in wire cut production. Triangle Brick Company anchors its position through automated manufacturing investments that compress lead times for regional developers. Glen-Gery differentiates via color-matching capabilities that serve architect-specified restoration projects.
Thin brick denotes kiln-fired clay units measuring roughly 13 to 25 millimeters in thickness, bonded to substrates with polymer-modified mortars or mechanical anchoring systems for structural weight reduction. Exterior cladding applications dominate volume, though interior walls command wider margin pools as designers specify handmade and reclaimed varieties for hospitality and retail environments. Wire cut thin brick leads production output, while reclaimed thin brick occupies the fastest-expanding niche as deconstruction sourcing networks mature.
ASTM International governs physical property requirements for thin veneer brick in the United States, while the EPA regulates kiln emissions under Clean Air Act standards that shape plant location decisions. State-level building codes in Florida and California impose wind-load and seismic performance criteria that filter which anchoring technologies gain approval. Stakeholders must monitor how evolving embodied-carbon disclosure rules affect material selection in publicly procured construction.
Market Dynamics
Prefabricated panel systems are restructuring how thin brick reaches construction sites, compressing traditional material supply chains into integrated subsystem delivery models that favor manufacturers with captive installation capabilities.
Growth Catalysts
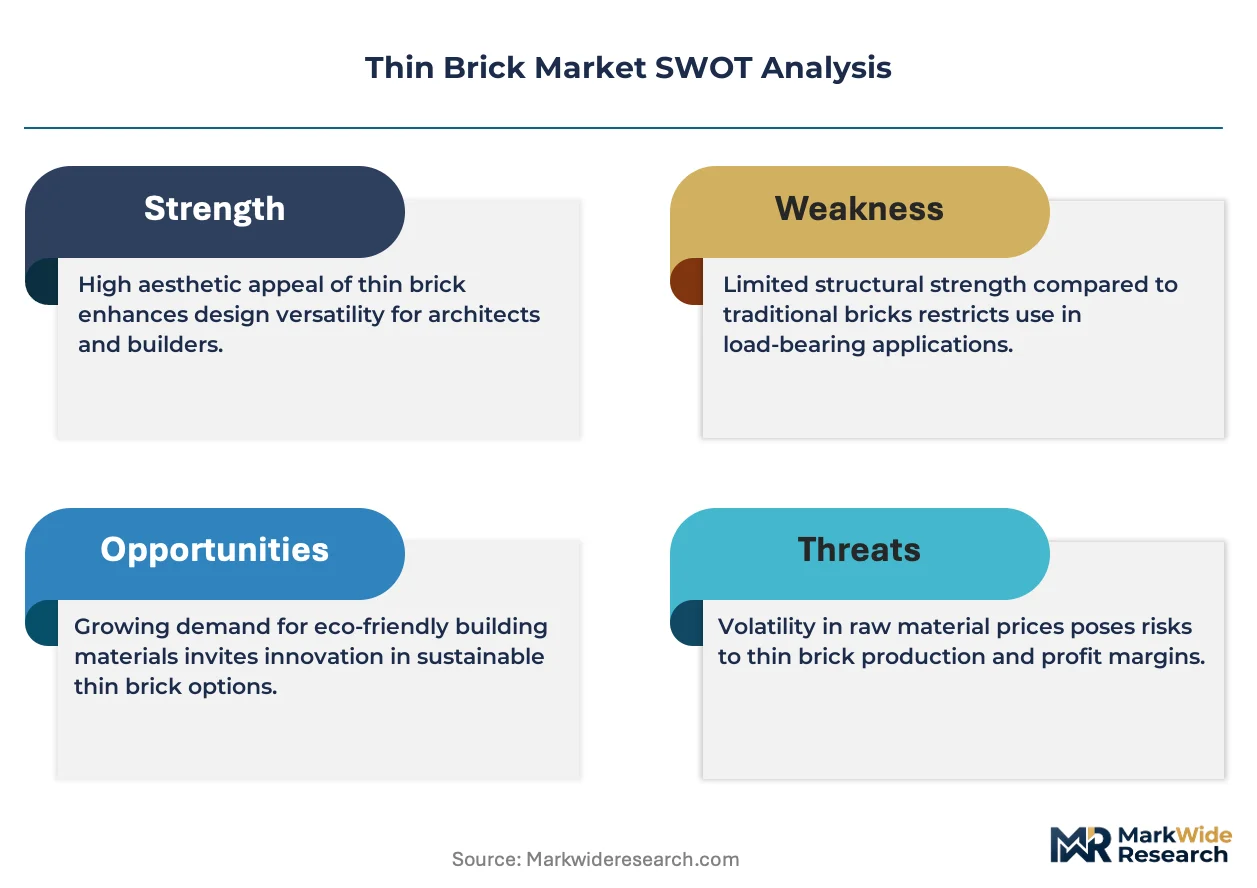
- ASTM C1088 Standards:Tightening quality thresholds in North America are filtering out marginal producers and elevating specification rates for certified thin veneer units in commercial cladding.
- Sun Belt Construction:Residential and commercial building activity across Florida, Texas, and Arizona concentrates demand for lightweight cladding systems that reduce structural load requirements.
- Interior Accent Specification:Renovation contractors increasingly specify thin brick for feature walls, driven by hospitality and retail designers seeking tactile materiality without full masonry weight.
Market Restraints
- Natural Gas Price Volatility:Kiln firing costs fluctuate with regional energy markets, compressing margins for producers without long-term fuel hedging or on-site renewable generation.
- Clay Reserve Concentration:High-quality sedimentary deposits cluster in specific Appalachian and Midwestern formations, creating geographic supply vulnerability for wire cut production.
- Full-Thickness Masonry Substitution:Traditional brick maintains preference in heritage-sensitive districts and high-wind zones where anchoring complexity raises installed cost premiums for thin systems.
Strategic Opportunities
- Reclaimed Sourcing Networks:Deconstruction partnerships with demolition contractors in Rust Belt cities yield authentic weathered units for premium interior applications.
- California Seismic Codes:State-level performance criteria for mechanical anchoring systems create first-mover advantage for tested fastening technologies in high-risk zones.
- Polymer-Modified Mortar Convergence:Advanced adhesive chemistry combined with rainscreen cavity design enables direct-to-substrate installation without traditional lath systems.
Industry Challenges
- Certified Installer Scarcity:Proper thin brick application demands trained craftspeople familiar with polymer-modified mortar mixing ratios and expansion joint placement, creating bottlenecked project timelines.
- Embodied Carbon Disclosure:Emerging requirements for Environmental Product Declarations in publicly procured construction force kiln operators to document and reduce Scope 1 emissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Brick Market |
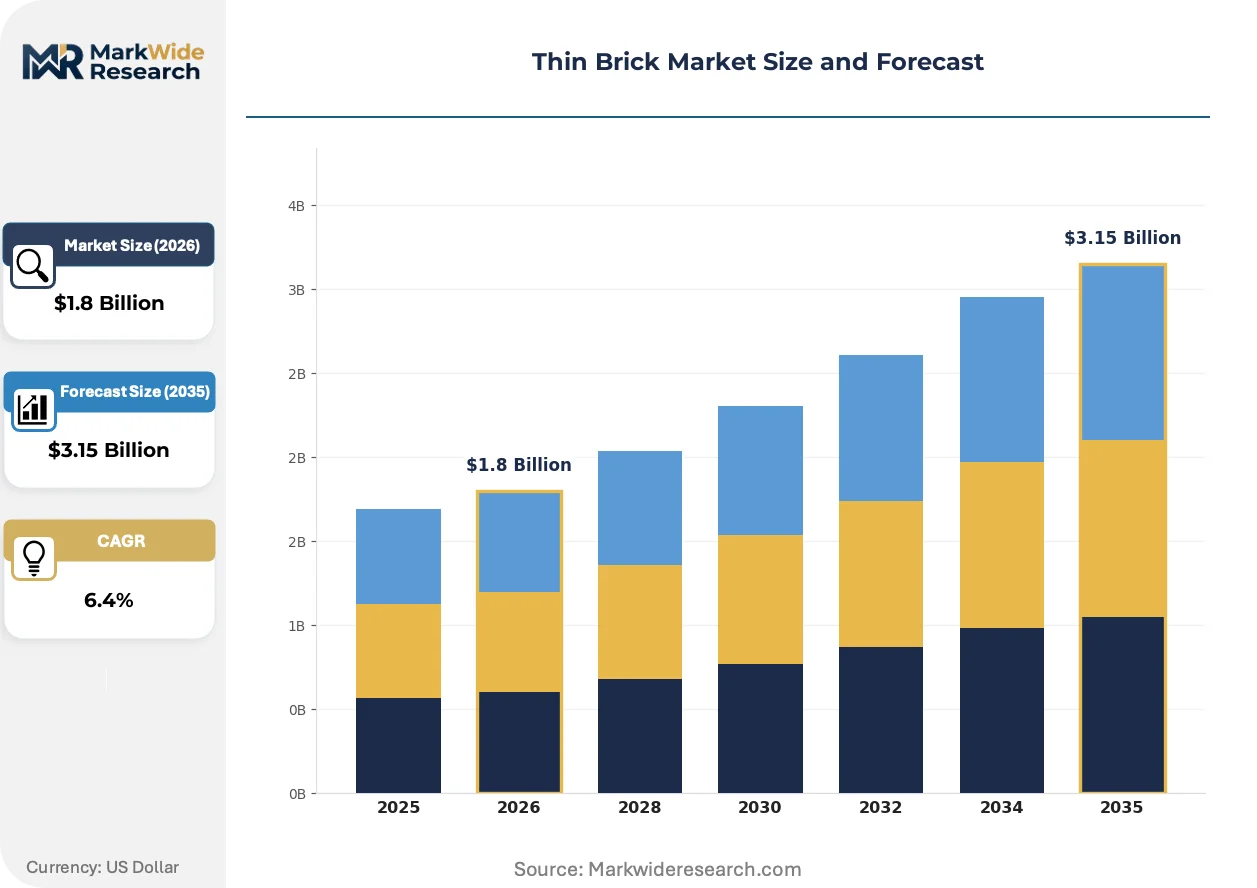
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reclaimed Thin Brick, Handmade Thin Brick, Wire Cut Thin Brick, Smooth Thin Brick, Textured Thin Brick Technology: Extrusion, Dry Pressing, Wet Pressing, Slip Casting, Automated Manufacturing Application: Exterior Cladding, Interior Walls, Fireplace Surrounds, Landscape Design, Retaining Walls End User: Construction Contractors, Architects, Interior Designers, Real Estate Developers, Renovation Specialists |
| Companies Covered | General Shale, Triangle Brick Company, Yankee Hill Brick, Riverside Brick & Supply Company, Belden Brick Company, Pine Hall Brick Company, Hebron Brick, LOPO Terracotta, Glen-Gery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Brick Market Trends and Innovations
Thin brick manufacturing and installation methods are converging around automation, environmental compliance, and prefabrication models that compress field labor requirements.
Mechanical anchoring systems with integrated drainage planes are overtaking traditional adhesive-only attachment in commercial applications above four stories. Façade engineers specify these hybrid fastening methods for high-rise hospitality projects in Miami and Houston. The technology is overtaking specification norms by satisfying wind-load calculations that polymer mortars alone cannot achieve.
EPA Clean Air Act standards for kiln emissions are tightening particulate and NOx thresholds, forcing plant operators to install scrubber systems or relocate to rural airsheds with less stringent attainment status. Brick manufacturers in Pennsylvania and Ohio face capital decisions between retrofitting legacy tunnel kilns or consolidating production at greenfield sites. The regulation most affects wire cut producers with aged combustion equipment.
General contractors now bundle cladding procurement with installation labor through single-source panel fabricators, displacing traditional two-step material-then-subcontractor purchasing. This consolidated sourcing model compresses project schedules and transfers liability to subsystem suppliers. The shift is most visible in Sun Belt commercial developments where speed-to-enclosure drives developer returns.
Thin Brick Market Segmentation
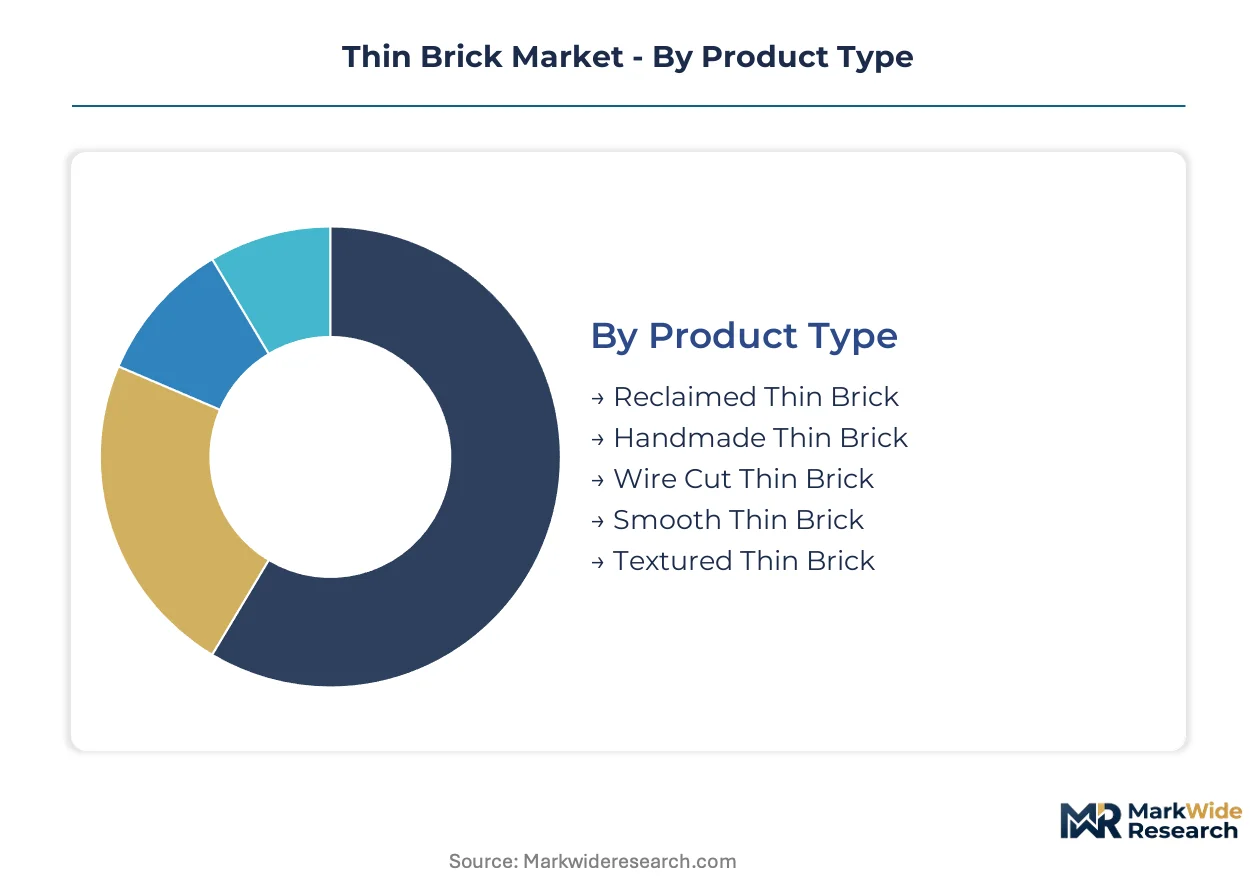
Thin brick market segmentation reveals how production methods, aesthetic finishes, and installation contexts create distinct competitive arenas with varying margin structures and capital requirements. Understanding these divides helps suppliers align manufacturing investments with specification pathways that dominate commercial and residential construction flows.
Product Type:
Capital intensity varies sharply across product categories, with mechanized wire cut production demanding continuous kiln investment while reclaimed sourcing networks require minimal fixed assets but complex logistics coordination.
- Wire Cut Thin Brick:Clay extrusion through steel cutting wires produces consistent rectangular units with visible drag marks. Sun Belt commercial developers in Florida and Texas specify wire cut for large-scale exterior cladding where uniformity and cost predictability matter more than surface variation.
- Reclaimed Thin Brick:Salvaged from demolished industrial buildings and cleaned for reuse, these units carry authentic weathering and mineral deposits. Interior designers in hospitality and retail environments pay premium prices for tactile authenticity that manufactured surfaces cannot replicate.
- Handmade Thin Brick:Individual clay shaping in wooden molds creates irregular edges and color variation prized for restoration work.
- Smooth Thin Brick:Sanded or glazed surfaces suit contemporary architectural specifications requiring clean lines.
- Textured Thin Brick:Surface impressions from mechanical rollers or hand tools mimic aged masonry for budget-conscious projects.
Wire cut thin brick absorbs the bulk of installed capacity; reclaimed thin brick is expanding most quickly.
Technology:
Manufacturing technology segmentation tracks how automation levels separate high-volume commodity producers from craft-scale operations serving architect-specified niches.
- Automated Manufacturing:Robotic handling systems and computer-controlled kiln firing enable output rates exceeding traditional methods by an order of magnitude. Regional developers in Arizona and Nevada rely on automated suppliers for compressed lead times on multi-phase commercial developments.
- Extrusion:Clay forced through dies creates hollow or solid profiles with dimensional precision. EPA Clean Air Act compliance costs disproportionately affect extrusion operators with legacy tunnel kilns in Pennsylvania and Ohio.
- Dry Pressing:High-pressure compaction of low-moisture clay suits dense, uniform units for structural applications.
- Wet Pressing:Higher moisture content enables intricate surface detailing for premium architectural specifications.
- Slip Casting:Liquid clay poured into molds produces complex shapes for ornamental thin brick elements.
Automated manufacturing dominates volume throughput; reclaimed sourcing networks gain share fastest in premium interior segments.
Application:
Application segmentation maps how structural requirements and exposure conditions dictate anchoring system selection and mortar specifications across construction contexts.
- Exterior Cladding:Rainscreen cavity systems with mechanical anchoring dominate commercial facades above four stories. Miami and Houston hospitality projects specify hybrid fastening methods to satisfy wind-load calculations that adhesive-only attachment cannot achieve.
- Interior Walls:Polymer-modified mortars applied directly to drywall or cement board enable feature wall installations without structural reinforcement. California seismic codes filter which adhesive systems gain approval for interior vertical surfaces.
- Fireplace Surrounds:Heat-resistant thin brick surrounds gas and electric hearth installations in residential renovation.
- Landscape Design:Exterior paving and garden wall applications require freeze-thaw resistant units.
- Retaining Walls:Structural thin brick facing on concrete cores combines aesthetic appeal with load-bearing capacity.
Exterior cladding commands the greatest installed square footage; interior walls deliver the widest margin pools.
End User:
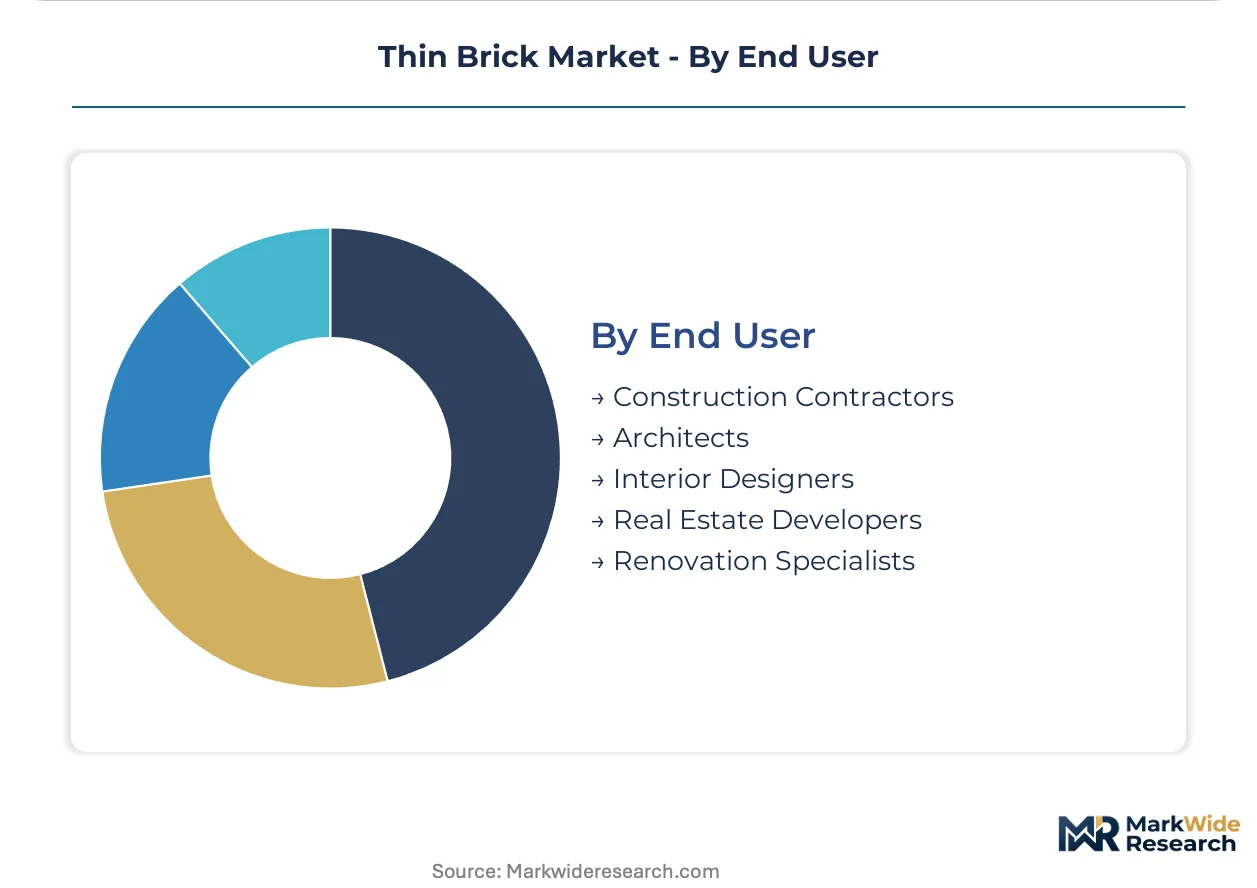
End user segmentation captures how specification authority and procurement patterns fragment across construction value chain participants with divergent priorities.
- Construction Contractors:Volume purchasers prioritize material availability, installation speed, and warranty coverage. Prefabricated panel fabricators in the Sun Belt now bundle thin brick procurement with installation labor, compressing traditional two-step purchasing into single-source relationships.
- Architects:Specification authority over color, texture, and anchoring method shapes project outcomes. ASTM C1088 certification requirements filter which producers qualify for commercial documentation.
- Interior Designers:Handmade and reclaimed varieties for tactile materiality drive hospitality and retail specifications.
- Real Estate Developers:Speed-to-enclosure metrics favor standardized products with predictable lead times.
- Renovation Specialists:Residential accent wall projects specify thin brick for weight advantages over full-thickness masonry.
Construction contractors absorb the bulk of volume procurement; architects control specification pathways for premium applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the United States where Appalachian clay reserves feed wire cut operations, while consumption spreads across Sun Belt states seeking lightweight cladding for commercial expansion. This geographic split shapes logistics costs and specification patterns across North American construction markets.
United States
Florida and Texas developers specify thin brick for hospitality and retail projects requiring speed-to-enclosure metrics. EPA Clean Air Act standards tighten kiln emissions thresholds, forcing Pennsylvania and Ohio operators to retrofit tunnel kilns or consolidate at greenfield sites. The Miami-Houston corridor anchors demand for hybrid mechanical anchoring systems in high-rise applications.
Germany
Restoration architects in Bavaria and North Rhine-Westphalia specify handmade thin brick for heritage-sensitive facades. REACH regulations govern chemical content in polymer-modified mortars, filtering which adhesive systems gain specification approval. The Stuttgart industrial cluster hosts automated extrusion operations serving Central European commercial developers.
China
Urban renewal projects in Shanghai and Shenzhen integrate reclaimed thin brick for interior feature walls in hospitality conversions. MIIT standards for building materials quality shape import requirements for foreign-manufactured units. The Yangtze River Delta concentrates terracotta production serving domestic and export markets.
United Kingdom
London-based renovation specialists specify wire cut thin brick for residential accent walls in Victorian terrace conversions. Building Regulations Part A structural requirements filter anchoring system approvals for exterior cladding above three stories. The Midlands manufacturing belt supplies clay products to Southeast England construction markets.
Australia
Sydney and Melbourne developers specify thin brick for medium-density residential projects seeking masonry aesthetics with reduced structural load. The National Construction Code energy efficiency provisions influence cladding system selection for commercial envelopes. New South Wales quarry operations feed both domestic production and export shipments to Southeast Asian markets.
Thin Brick Market Competitive Landscape
Top-tier vendors anchor specification-driven commercial projects, while mid-scale fabricators compete on lead-time compression for regional developers. The market structures around three tiers: kiln operators with captive clay reserves, automated manufacturers with robotic handling systems, and reclaimed sourcing networks with deconstruction partnerships. Strategic moves concentrate on backward integration into clay mining and prefabricated panel fabrication capabilities that bundle material with installation labor.
Among North American kiln operators, General Shale and Triangle Brick Company occupy positions representing reserve-backed and automation-driven archetypes respectively. Glen-Gery anchors the color-matching specialist tier serving architect-specified restoration projects. These three entities exemplify how geographic control over raw materials, manufacturing scale, and specification relationships fragment competitive advantage across distinct market vectors.
| Leading Market Players |
|---|
| General Shale |
| Triangle Brick Company |
| Yankee Hill Brick |
| Riverside Brick & Supply Company |
| Belden Brick Company |
| Pine Hall Brick Company |
| Hebron Brick |
| LOPO Terracotta |
| Glen-Gery |
| Others |
Pricing and Supply Chain Analysis
Captive clay reserves across Appalachian formations anchor supply positions and pricing power for wire cut producers, while prefabricated panel fabricators compress traditional material-then-labor procurement into bundled subsystem pricing that transfers margin from kilns to installers.
Pricing Analysis
Margin tightening in wire cut production reflects natural gas cost volatility and EPA compliance capital requirements. Three-tier pricing structure across reclaimed, handmade, and wire cut levels separates premium interior specifications from commodity exterior cladding. Price differentiation rests on ASTM C1088 certification status and color-matching capability for architect-specified restoration. Renovation contractors exhibit highest price sensitivity on standard wire cut, while hospitality designers show lowest sensitivity for reclaimed authenticity.
Supply Chain Analysis
Single-source vulnerability sits with high-quality sedimentary clay deposits concentrated in Appalachian and Midwestern United States formations. Production draws from Pennsylvania, Ohio, and Tennessee kiln operations feeding Sun Belt construction demand. Supply chain risk centers on EPA Clean Air Act enforcement forcing plant consolidation or rural relocation. Distribution runs through prefabricated panel fabricators bundling material with installation labor for commercial developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kiln capacity constraints under EPA emission standards prop thin brick pricing, creating supply-constrained conditions that favor producers with compliant operations and captive reserves.
For Market Incumbents: To counter prefabricated panel fabricators capturing downstream margin, secure backward integration into clay mining to lock raw material cost positions. Invest in automated manufacturing to compress lead times for regional Sun Belt developers and defend specification relationships against reclaimed sourcing networks. For New Entrants and Emerging Players: The price-point gap between premium reclaimed and economy wire cut creates entry space for mid-tier textured thin brick targeting budget-conscious commercial interiors. Target California seismic code-compliant anchoring systems as the most penetrable specification pathway, leveraging polymer-modified mortar convergence for direct-to-substrate installation. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by building materials conglomerates seeking cladding subsystem capabilities. Long-term viability favors producers with compliant kiln assets and deconstruction partnerships for reclaimed supply. Watch EPA attainment status designations as the signal for capacity constraint inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Clay Reserve Acquisition | Secures Appalachian sedimentary deposits against supply disruption for wire cut production. |
| Prefabricated Panel Fabrication | Bundles thin brick with installation labor to capture downstream margin from commercial developers. |
| Reclaimed Sourcing Network Buildout | Deconstruction partnerships in Rust Belt cities yield authentic weathered units for premium interior specifications. |
| Automated Manufacturing Investment | Robotic handling systems compress lead times for multi-phase Arizona and Nevada commercial developments. |
| EPA Compliance Technology Deployment | Scrubber systems and kiln retrofits maintain operational permits under tightening Clean Air Act thresholds. |
Research Methodology
Multi-period observation of kiln capacity utilization, ASTM certification rates, and prefabricated panel adoption anchored the trend analysis, supplemented by interviews with plant operations managers, commercial procurement officers at regional developers, façade engineers specifying anchoring systems, and demolition contractors supplying reclaimed material. Secondary validation drew from EPA enforcement records, state building code filings in Florida and California, and SEC disclosures from building materials producers. Bottom-up volume estimates triangulated against top-down construction spending allocations.
Input-output matrices modeled thin brick demand across product type, manufacturing technology, application context, and end-user specification authority. CAGRs derived from regression analysis of historical production data and forward projection of Sun Belt construction permits. Industry-specific inputs included natural gas price scenarios and EPA attainment status timelines.
Underlying measurement precision varies by segment; wire cut production volumes carry tighter precision than reclaimed sourcing estimates due to informal deconstruction network opacity. Forecasts reflect assumptions about regulatory enforcement intensity and commercial construction cycle duration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Exterior Doors Market
Building Materials
United States White Cement Market
Building Materials
United States Architectural Coatings Market
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
India Concrete Admixtures Market
Building Materials
Canada Architectural Coatings Market
Building Materials
Fiber Cement Market
Building Materials
Fireproof Cladding Market
Building Materials
Italy Cement Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
Construction Materials Market
Building Materials
North America Construction Aggregates Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
China Architectural Coatings Market
Building Materials
Cellular Concrete Market
Building Materials
Sanded Grout Market