
 North America Concrete Admixtures Market | 2026-2036
North America Concrete Admixtures Market Size, Share, and Industry Trends Forecast 2026-2036
North America Concrete Admixtures Market Analytics
Market Dynamics
Multi-source procurement of chemical additives is realigning how ready-mix producers manage formulation costs across North America. Sika AG leverages its integrated supply chain to sustain pricing leverage in superplasticizer categories. BASF SE anchors its position through R&D intensity in polycarboxylate ether chemistry. GCP Applied Technologies Inc. differentiates via specialized accelerator portfolios for cold-climate pours.
Product Landscape
Concrete admixtures comprise chemical or mineral additives dosed at under five percent by weight of cement to modify hydration kinetics, workability, or durability performance. Superplasticizers enable water reduction exceeding thirty percent while maintaining slump, a specification critical for high-strength precast elements. Plasticizers retain dominant volume share across the product type dimension due to baseline demand in residential foundations. The infrastructure end user segment commands premium margin pools as DOT specifications tighten for bridge deck longevity.
Regulatory Environment
ASTM C494 governs chemical admixture classification across the United States while Canada's CSA A266.1 sets parallel performance benchmarks. The EPA's National Ambient Air Quality Standards indirectly shape admixture demand by pressuring cement plants to reduce clinker factor through supplementary cementitious material compatibility. Stakeholders must monitor state-level Buy America provisions in infrastructure bills that could restrict sourcing flexibility for imported active ingredients.
Market Dynamics
EPA's tightening National Ambient Air Quality Standards are forcing cement producers to reduce clinker factor through supplementary cementitious material compatibility, creating structural pull for high-performance admixtures that maintain strength at lower cement content.
Growth Catalysts
- Infrastructure Investment and Jobs Act:Federal highway and bridge spending across the United States is accelerating specification-grade admixture procurement for DOT-compliant concrete durability.
- Carbon capture compatibility:Emerging CCS retrofit requirements at cement plants are elevating demand for admixtures that offset CO2-intensive clinker reduction without sacrificing set times.
- Texas and California megaprojects:Concentrated transportation and energy infrastructure pipelines in these states are reshaping regional supply requirements for cold-weather accelerators and corrosion inhibitors.
Market Restraints
- Naphthalene sulfonate price volatility:Feedstock fluctuations in petrochemical supply chains are compressing margin pools for conventional superplasticizer formulations.
- Active ingredient import dependency:Concentration of polycarboxylate ether monomer production in Asian chemical clusters creates exposure to tariff and logistics disruptions.
- ASTM C494 certification timelines:Extended approval cycles for novel chemistries delay commercialization of next-generation shrinkage-reducing admixtures.
Strategic Opportunities
- Canada's Green Building Strategy:Federal procurement mandates for low-carbon construction materials are opening specification pathways for admixture-enabled cement reduction in federal projects.
- Mass timber hybrid construction:Convergence of concrete admixtures with cross-laminated timber systems is creating demand for specialized bonding agents and moisture-control formulations.
- Direct-to-contractor digital channels:Ready-mix producers are bypassing traditional distribution layers through platform-based specification tools that embed admixture selection algorithms.
Industry Challenges
- Concrete technologist shortage:Specialized expertise in rheology modification and compatibility testing is scarce across quality control laboratories serving major metropolitan markets.
- Legacy batching system integration:Automated admixture dosing retrofits at aging ready-mix plants require capital outlays that conflict with compressed project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Concrete Admixtures Market |
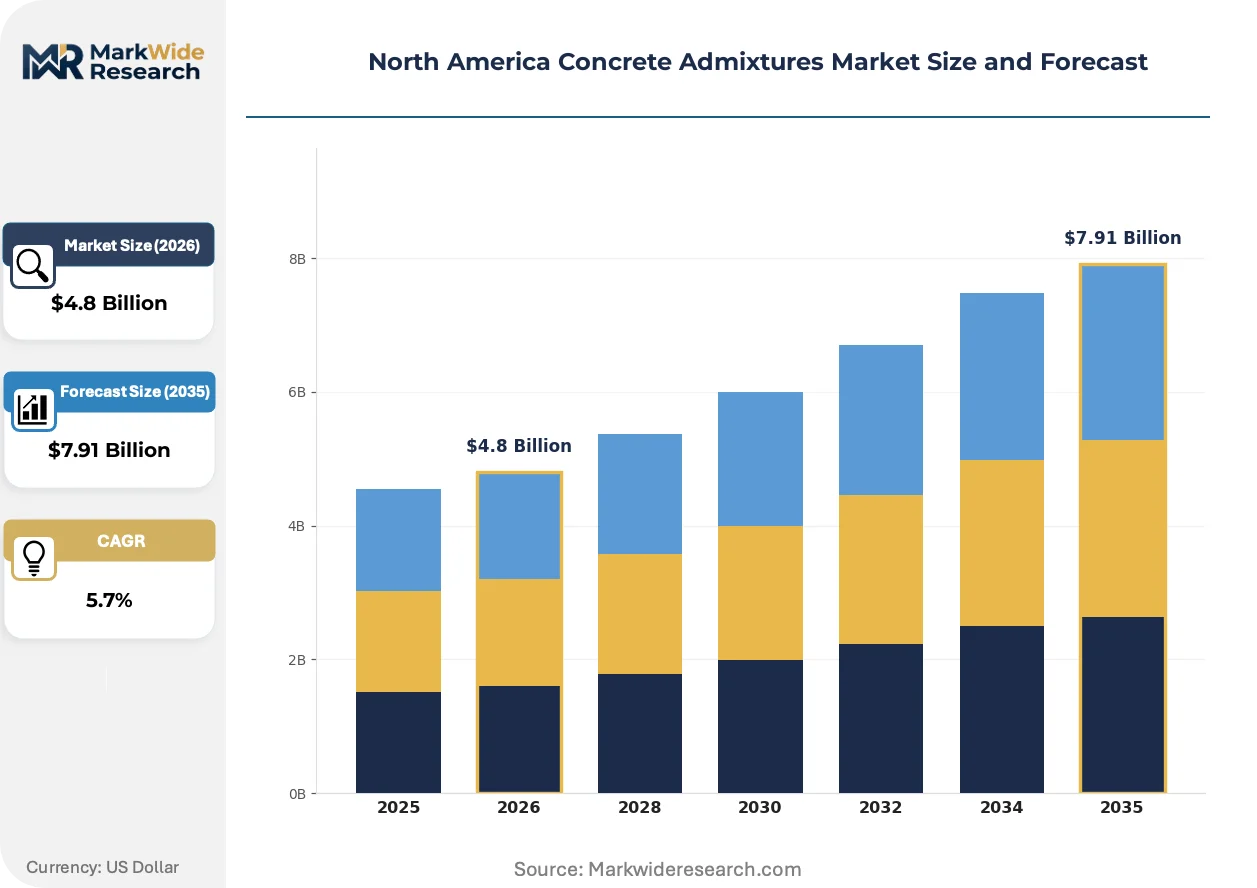
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Superplasticizers, Accelerators, Retarders End User: Residential, Commercial, Infrastructure, Industrial Distribution Channel: Direct Sales, Retailers, Distributors, Online Platforms Application: Precast, Ready-Mix, Shotcrete, Flooring |
| Companies Covered | Sika AG, GCP Applied Technologies Inc., MAPEI SpA, RPM International Inc., BASF SE, CEMEX SAB de CV, Fosroc, Inc., Dow Inc., Saint-Gobain SA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Concrete Admixtures Market Evolving Landscape
Formulation science is converging with digital specification platforms to compress the distance between laboratory development and jobsite deployment, collapsing traditional multi-month qualification cycles.
Biopolymer-based viscosity modifiers are converging with conventional polycarboxylate ether superplasticizers to enable self-consolidating concrete at reduced cement content. Precast producers in the Great Lakes region are piloting these hybrid systems for complex architectural elements. The technology is converging with automated quality assurance protocols to reduce rejection rates on high-specification infrastructure pours.
EPA's emerging standards for particulate matter and NOx emissions are pressuring cement plants to lower kiln operating temperatures, which slows hydration kinetics and elevates demand for high-early-strength accelerators. Producers in the Southwest are reformulating around calcium nitrate and calcium formate chemistries to compensate. The regulatory shift is concentrating specification authority among state DOTs with the most stringent bridge deck longevity requirements.
Specification decisions are migrating from laboratory technicians to procurement officers armed with lifecycle cost models that monetize durability performance. National ready-mix chains are consolidating vendor relationships around integrated suppliers capable of technical service bundling. The behavioral shift is most pronounced in California where Caltrans specifications now require 75-year service life guarantees on marine exposure structures.
North America Concrete Admixtures Market Segmentation
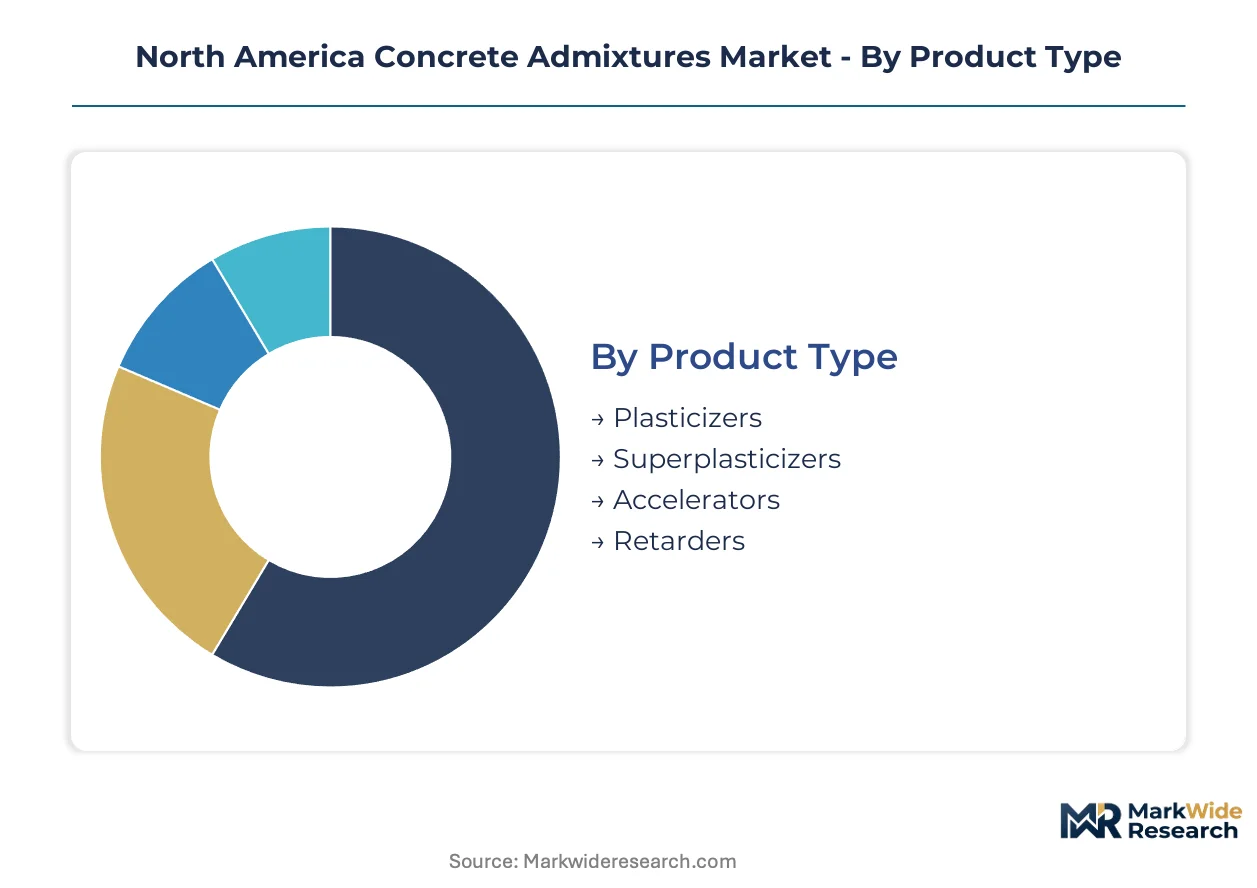
Concrete admixture purchasing patterns diverge sharply across end-use contexts in North America. Specification-grade infrastructure projects demand certified performance guarantees while residential contractors prioritize cost-per-cubic-yard efficiency. Understanding these segmentation fault lines reveals where margin pools concentrate and which technical service models win.
Product Type:
Buyers in this category separate by performance specification intensity rather than absolute volume scale.
- Superplasticizers:Polycarboxylate ether and naphthalene sulfonate chemistries enable water reduction exceeding thirty percent for high-strength precast and post-tensioned structural elements. Texas DOT bridge specifications and California marine exposure requirements are concentrating procurement of high-range water reducers that maintain workability at low water-cement ratios.
- Plasticizers:Lignosulfonate and conventional sulfonate formulations serve baseline workability modification for residential foundations and slab-on-grade construction. Volume demand clusters in Sun Belt metropolitan markets where single-family housing starts drive repetitive procurement of mid-range water reducers.
- Accelerators:Calcium nitrate and calcium formate chemistries compress set times for cold-weather pours and rapid-formwork cycling.
- Retarders:Hydroxylated carboxylic acid and sugar-based formulations extend workability windows for mass concrete placements and hot-weather delivery.
Plasticizers lead volumes today; superplasticizers are gaining share fastest.
End User:
Project scale and specification authority determine formulation complexity requirements across buyer segments.
- Infrastructure:State DOTs and federal agencies mandate ASTM C494-compliant admixtures with certified durability performance for bridge decks, tunnels, and marine structures. Caltrans 75-year service life guarantees and Texas megaproject pipelines are elevating procurement of corrosion inhibitors and shrinkage reducers.
- Commercial:High-rise cores, parking structures, and retail shells require mid-tier superplasticizers for pumpability and finishability. Demand concentrates in Dallas-Fort Worth, Atlanta, and Toronto where commercial construction velocity sustains specification-grade volume.
- Residential:Single-family and multifamily foundations prioritize cost-optimized plasticizers with minimal technical service overhead.
- Industrial:Manufacturing floors, warehouses, and process facilities specify abrasion-resistant and chemical-resistant formulations.
Infrastructure commands premium pricing tiers; commercial generates the steadiest volume baselines.
Distribution Channel:
Channel selection tracks customer technical sophistication and order fragmentation patterns.
- Distributors:Regional chemical distributors aggregate fragmented ready-mix producer demand across secondary markets. Inventory positioning in Ohio, Pennsylvania, and Ontario enables same-day delivery for emergency specification changes.
- Direct Sales:National ready-mix chains and major precast producers negotiate direct supply agreements with integrated admixture manufacturers for technical service bundling and volume pricing.
- Retailers:Construction supply yards serve small contractors and repair specialists with packaged admixture quantities.
- Online Platforms:Emerging digital procurement channels target mid-tier contractors with specification tools and algorithmic dosing recommendations.
Distributors still capture the largest transaction volume; direct sales is climbing the fastest as national accounts consolidate.
Application:
Placement method dictates rheology requirements and admixture compatibility constraints.
- Ready-Mix:Central-batch plants serving metropolitan construction markets require versatile superplasticizer systems compatible with variable aggregate sources and haul times. The category spans residential, commercial, and infrastructure end uses with formulation adjustments for local materials.
- Precast:Controlled factory environments enable precise dosing of high-performance admixtures for architectural and structural elements. Great Lakes region producers are piloting biopolymer-polycarboxylate hybrid systems for complex geometries and surface finishes.
- Shotcrete:Pneumatic placement requires specialized accelerators and viscosity modifiers for overhead and vertical applications.
- Flooring:Industrial and commercial slabs demand shrinkage reducers and curing compounds for flatness and durability.
Ready-mix anchors volume today; precast shows the steepest expansion trajectory on specification-grade chemistry uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity is shifting toward jurisdictions where EPA enforcement intensity creates cost-of-compliance arbitrage. Canadian and Mexican facilities capture overflow demand when US Gulf Coast plants face emissions-driven curtailments. Cross-border supply chains now route polycarboxylate ether monomers through Ontario and Baja California to bypass tariff exposure.
United States
Texas DOT bridge specifications and California marine exposure mandates drive specification-grade superplasticizer procurement. EPA's National Ambient Air Quality Standards pressure cement plants in the Southwest to reduce clinker factor, elevating demand for high-early-strength accelerators. Houston-Galveston and Los Angeles-Long Beach anchor the continent's densest admixture formulation clusters.
Canada
Federal procurement mandates under Canada's Green Building Strategy open specification pathways for low-carbon construction materials. Health Canada's alignment with CSA A266.1 performance benchmarks ensures regulatory continuity with US ASTM standards. Ontario's Golden Horseshoe and Metro Vancouver concentrate precast production piloting biopolymer-based viscosity modifiers.
Mexico
Nearshoring of automotive and aerospace manufacturing elevates demand for industrial flooring admixtures with abrasion resistance. The country's national environmental regulator enforces progressively tighter particulate standards at cement kilns. Nuevo León and the Bajío Region host expanding ready-mix capacity serving US-bound construction supply chains.
North America Concrete Admixtures Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital specification platforms and biopolymer chemistry. The vendor base concentrates around integrated chemical conglomerates with captive R&D infrastructure and regional distributors with inventory positioning advantages. Three archetypes dominate: multinational integrated suppliers, specialty chemical independents, and construction-materials conglomerates with backward integration into admixture production. Consolidation through strategic partnerships and capacity expansion at Gulf Coast chemical hubs represent the dominant competitive vectors.
Within the integrated supplier tier, Sika AG and BASF SE exemplify multinational scale advantages, while GCP Applied Technologies Inc. occupies a position as a specialty-focused independent. Sika AG anchors European-origin technical service bundling; BASF SE represents polycarboxylate ether chemistry depth; GCP Applied Technologies Inc. exemplifies accelerator portfolio specialization for climate-specific applications. These three sit within distinct competitive positions that shape how procurement officers evaluate vendor relationships across DOT-compliant infrastructure projects.
| Leading Market Players |
|---|
| Sika AG |
| GCP Applied Technologies Inc. |
| MAPEI SpA |
| RPM International Inc. |
| BASF SE |
| CEMEX SAB de CV |
| Fosroc, Inc. |
| Dow Inc. |
| Saint-Gobain SA |
| Others |
Value Network & Pricing Analysis
Biopolymer-polycarboxylate hybrid formulation development is simultaneously compressing per-unit production costs and concentrating specification authority among integrated suppliers with captive R&D infrastructure. EPA emissions enforcement and state DOT longevity mandates are reshaping how admixture producers balance input cost exposure against premium pricing for certified performance.
Pricing Analysis
Distributor margin layers in conventional supply chains face compression as national ready-mix chains consolidate around direct procurement agreements. Three-tier pricing structure across premium certified-grade, standard DOT-compliant, and economy residential tiers separates infrastructure projects paying durability-guarantee premiums from cost-optimized foundation work. Pricing pressure stems from naphthalene sulfonate feedstock volatility in petrochemical supply chains. Residential contractors exhibit highest price sensitivity; state DOT procurement officers prioritize lifecycle cost models over unit pricing.
Supply Chain Analysis
Domestic-content mandates in federal infrastructure legislation are redirecting polycarboxylate ether monomer sourcing through North American chemical hubs. Production gravity centers on the United States, Canada, and Mexico with cross-border routing through Ontario and Baja California mitigating tariff exposure. Raw material dependencies include ethylene oxide derivatives, lignosulfonate byproducts from pulp processing, and calcium nitrate industrial feedstocks. Single-source vulnerability concentrates in Asian chemical clusters for specialty monomers. Distribution runs through regional chemical distributors aggregating fragmented ready-mix demand alongside direct sales channels serving consolidated national accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Concrete Admixtures Market functions as a regulatory compounder where EPA National Ambient Air Quality Standards enforcement and state DOT durability specifications create structural demand for certified high-performance formulations.
For Market Incumbents: Deepen backward integration into polycarboxylate ether monomer production to offset Asian import dependency and tariff exposure. Expand technical service bundling capabilities to defend margin position against digital-native entrants offering algorithmic specification tools. Prioritize R&D investment in biopolymer-based viscosity modifiers where Great Lakes precast producers are piloting next-generation systems. For New Entrants and Emerging Players: Begin with digital specification platforms targeting mid-tier commercial contractors underserved by incumbent technical service models. White-space opportunity concentrates in direct-to-contractor channels embedding algorithmic dosing recommendations for ready-mix procurement. Canada's Green Building Strategy federal procurement mandates offer a penetrable specification pathway for low-carbon admixture-enabled cement reduction technologies. For Investors and Strategic Acquirers: Valuations sit cheapest among specialty chemical independents with accelerator portfolio depth and regional distributor inventory positioning in Texas and California megaproject corridors. Long-term viability hinges on regulatory enforcement continuity for emissions-driven clinker reduction. Watch EPA particulate matter standard revision timing as the critical inflection signal for high-early-strength accelerator demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive supply of polycarboxylate ether inputs insulates margin pools from Asian tariff exposure. |
| Digital Specification Platform Launch | Algorithmic dosing tools collapse procurement cycles for mid-tier ready-mix contractors. |
| Biopolymer Hybrid Formulation Investment | Self-consolidating concrete chemistry aligns with Caltrans 75-year service life mandates. |
| Regional Capacity Expansion | Gulf Coast chemical hub positioning captures Texas DOT bridge specification procurement. |
| Technical Service Bundling Consolidation | Integrated laboratory and field support wins national account contracts from fragmented distributors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged ready-mix plant managers, state DOT materials engineers, precast production directors, admixture R&D chemists, and regional chemical distributor procurement leads. Secondary validation drew from EPA enforcement databases, state transportation department specification filings, ASTM C494 certification registries, customs trade flow records, and SEC filings of publicly traded construction materials conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, and application dimensions.
Historical reference periods anchored the projection framework against documented specification-grade procurement cycles and infrastructure spending authorization timelines. Segmentation modeling spanned product chemistry tier, end-use project scale, distribution channel structure, and regional regulatory enforcement intensity. CAGRs derived from trend extrapolation of DOT-compliant specification uptake and residential construction velocity. Forecast inputs incorporated clinker factor reduction trajectories at cement plants and cold-weather accelerator demand patterns linked to regional climate severity.
Several conditions sit outside the modeled scope, including unannounced revisions to Buy America domestic-content thresholds, abrupt trade policy shifts affecting polycarboxylate ether monomer tariffs, and breakthrough cement chemistry displacing conventional admixture-based carbon reduction. Forecasts reflect documented assumptions subject to revision from macroeconomic construction cycle turns or accelerated biopolymer formulation adoption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Cement Tiles Market
Building Materials
Cribbing Blocks Market
Building Materials
Block Paving Market
Building Materials
India Cement Market
Building Materials
Spain Architectural Coatings Market
Building Materials
US Facade Market
Building Materials
Ireland Cement Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
Construction Glass Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Door Frame Metal Market
Building Materials
Canada Architectural Coatings Market
Building Materials
Asia-Pacific Cement Market
Building Materials
Geocells Market
Building Materials
Aluminum Door and Window Market
Building Materials
Global Commercial Paving Slabs Market