
 Landscaping Tools Market | 2026-2036
Landscaping Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Landscaping Tools Market Foresight
Commercial-grade durability specifications is unwinding a long-standing price ceiling in professional segments. Deere & Company leverages its precision manufacturing network to dominate tractor-mounted landscaping attachments. Husqvarna Group anchors battery-powered innovation through its dedicated robotics division. The Toro Company differentiates via irrigation-integrated grounds management systems for municipal clients.
Landscaping tools encompass manually operated and motorized implements engineered for soil cultivation, vegetation management, and terrain modification, with power equipment typically rated between 18V and 56V for battery platforms and 25cc to 50cc for small gas engines, serving groundskeeping professionals and property maintenance operations. Power tools command the largest revenue pool due to replacement cycles and attachment ecosystems, while battery-operated technology captures the fastest expansion as lithium-ion energy density improves runtime parity with gas equivalents. Hand tools retain stable margin profiles in the professional channel where ergonomics and warranty terms drive repurchase loyalty.
EPA Phase 3 emission regulations constrain small-engine specifications and push manufacturers toward electrified platforms, while California Air Resources Board ordinances banning gas-powered equipment in select municipalities directly reshape product mix requirements for brands distributing in western states. OSHA noise exposure limits further influence design priorities for commercial-grade equipment used by landscape contractors on sustained daily schedules. Stakeholders must weigh battery supply chain commitments against residual gas-engine service revenue as regulatory thresholds tighten unevenly across state jurisdictions.
Market Dynamics
Battery energy density improvements are compressing replacement cycles for gas-powered equipment fleets while California's municipal ordinances force immediate product mix pivots for distributors serving western states.
Growth Catalysts
- EPA Phase 3 Emission Standards:Small-engine manufacturers face tightening exhaust limits that accelerate electrified platform development. Professional contractors upgrade fleets to maintain compliance across state jurisdictions.
- Robotics Integration:Autonomous mowing systems reduce labor dependency for large commercial grounds. Municipal golf courses and corporate campuses deploy units for overnight maintenance cycles.
- Sun Belt Urbanization:Year-round landscaping demand in Texas, Florida, and Arizona metropolitan areas sustains equipment utilization rates above seasonal northern markets.
Market Restraints
- Lithium-Ion Supply Concentration:Cathode material processing concentrates in China, exposing battery pack costs to geopolitical supply disruptions and export restriction risks.
- Small-Engine Residual Value:Gas equipment retains secondary market liquidity in states without CARB-equivalent bans, slowing capital redeployment toward electrified alternatives.
- Runtime Parity Gaps:Commercial crews operating 10-hour schedules encounter battery swap limitations that gas refueling avoids, constraining pure-electric fleet transitions.
Strategic Opportunities
- Interchangeable Battery Platforms:Cross-brand compatibility standards allow contractors to consolidate power sources across trimmers, blowers, and mowers. Reduced inventory complexity improves working capital efficiency.
- Smart Irrigation Convergence:Soil moisture sensors and weather data integration enable predictive maintenance scheduling for municipal clients. Water utility rebate programs subsidize connected system adoption.
- Equipment-as-a-Service Models:Subscription pricing with bundled maintenance shifts capex burdens to manufacturers. Landscape contractors in high-turnover labor markets prefer predictable operating expenses.
Industry Challenges
- Technician Certification Lags:High-voltage battery repair requires specialized training that community college programs have not scaled to match equipment rollout timelines.
- Reverse Logistics Complexity:End-of-life battery collection networks remain underdeveloped, creating compliance exposure under emerging state extended producer responsibility frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Landscaping Tools Market |
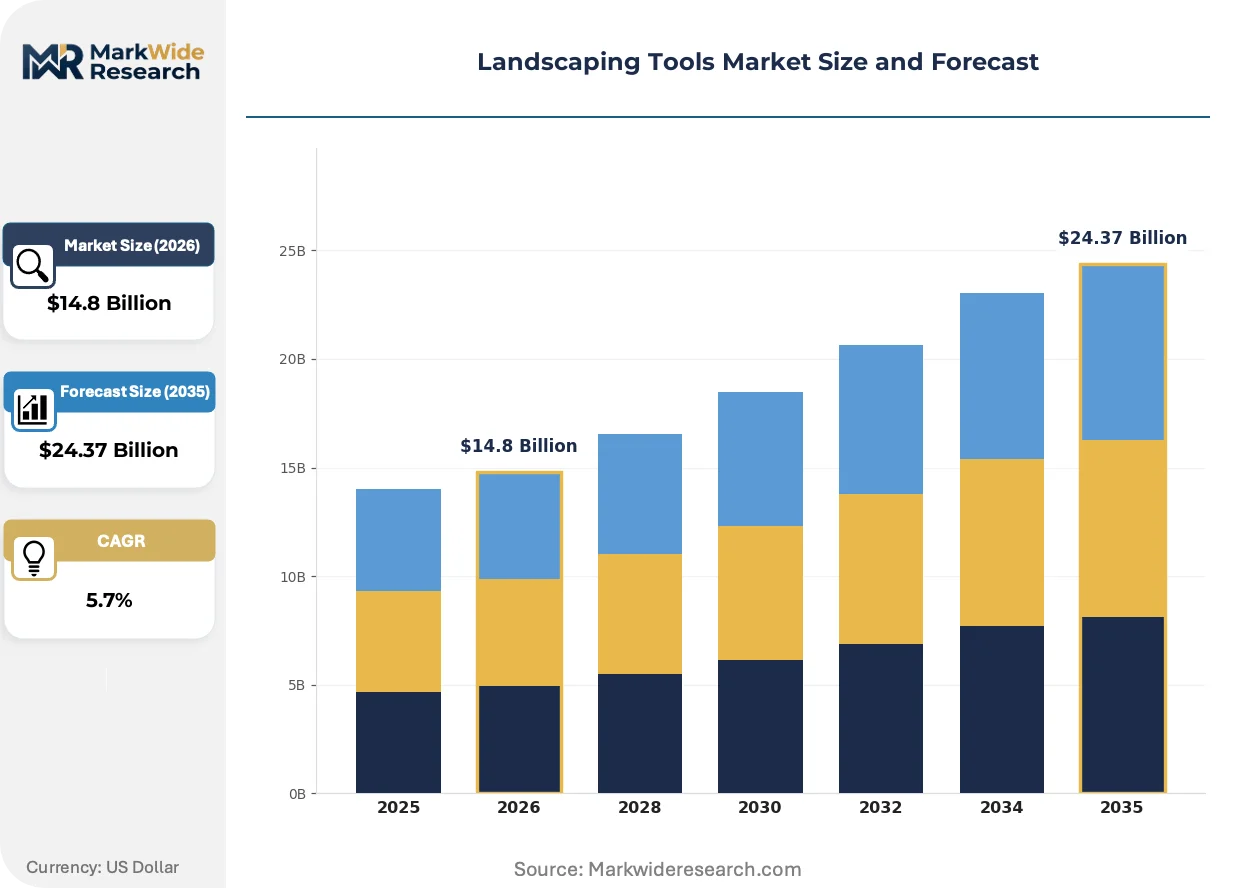
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Tools, Power Tools, Garden Equipment, Lawn Care Products Application: Residential, Commercial, Agricultural, Public Spaces End User: Homeowners, Professionals, Landscape Contractors, Garden Centers Technology: Manual, Electric, Gas-Powered, Battery-Operated |
| Companies Covered | Deere & Company, Husqvarna Group, The Toro Company, Stanley Black & Decker, Robert Bosch GmbH, Kubota Corporation, MTD Products, Briggs & Stratton Corporation, Honda Power Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Landscaping Tools Market Shifts & Advancements
Electrification is rewriting equipment specifications while connectivity features create new service revenue streams for manufacturers. Regulatory fragmentation across states forces parallel product development tracks.
Brushless DC motor architectures are supplanting brushed designs in professional-grade string trimmers and hedge cutters. Landscape contractors operating daily 8-hour schedules adopt these systems for reduced heat generation and extended duty cycles. The shift is compressing maintenance intervals and enabling longer warranty terms that lock in brand loyalty.
OSHA noise exposure enforcement is tightening permissible decibel thresholds for groundskeeping crews. Equipment manufacturers redesign housing geometries and blade profiles to reduce operator dose levels. Commercial buyers in dense urban corridors prioritize certified-low-noise units to avoid worksite shutdowns and citation exposure.
Buying committees at multi-site property management firms now specify fleet standardization across their vendor base. Regional distributors respond with volume pricing agreements and consolidated invoicing portals. This consolidation concentrates purchasing power among national accounts while squeezing margins for independent dealers serving fragmented residential segments.
Landscaping Tools Market Segmentation
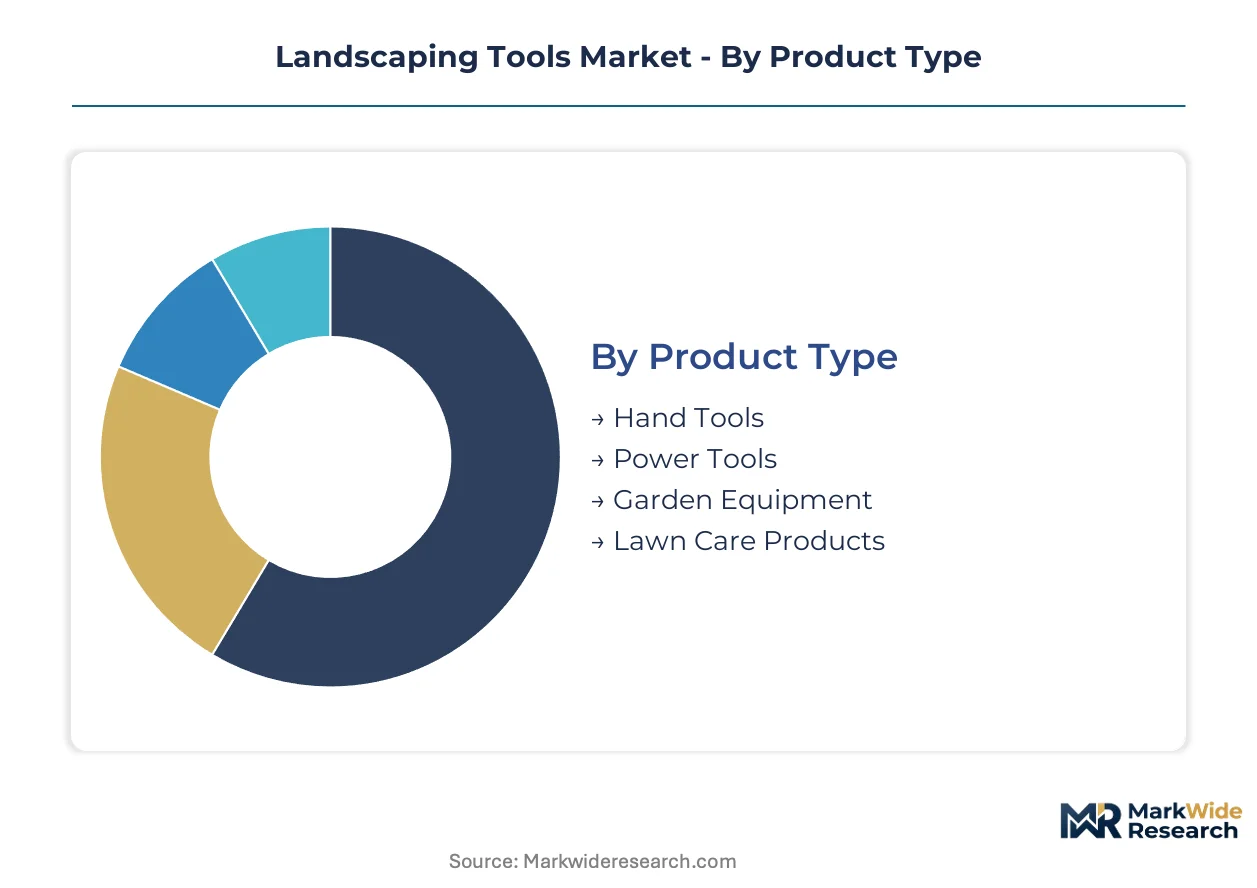
Segmentation in landscaping tools determines channel strategy, warranty structures, and inventory turns. Professional contractors purchase through specialized dealers with service networks, while residential buyers favor mass retail and direct-to-consumer platforms. Technology transitions are fragmenting traditional category boundaries as battery platforms span multiple product types.
Product Type:
Professional landscape contractors source through dealer networks that bundle maintenance contracts, whereas residential consumers purchase hand tools and entry-level power equipment through home improvement retailers and e-commerce platforms.
- Hand Tools:Forged steel implements including shovels, rakes, and pruners with fiberglass or hardwood handles. Demand clusters among garden centers and independent hardware stores in suburban markets where homeowners perform seasonal maintenance. Ergonomic grip designs and lifetime warranties drive repurchase loyalty in this segment.
- Power Tools:Motorized equipment rated between 18V and 56V for battery platforms and 25cc to 50cc for small gas engines, encompassing string trimmers, hedge cutters, and chainsaws. Landscape contractors operating commercial contracts in Sun Belt metropolitan areas favor brushless DC motor architectures for reduced heat generation during extended duty cycles.
- Garden Equipment:Cultivators, tillers, and soil preparation machinery for vegetable and ornamental planting. Sales concentrate through agricultural supply cooperatives and regional equipment dealers serving hobby farms and community gardens.
- Lawn Care Products:Spreaders, aerators, and dethatching equipment for turf maintenance. Municipal parks departments and golf course superintendents specify commercial-grade durability ratings for these implements.
Power tools dominate installed base. Battery-operated variants within power tools are where expansion concentrates.
Application:
Cost tier differentiation separates specification-grade equipment for commercial operators from consumer-grade alternatives, with pricing spreads of three-to-five times reflecting duty cycle ratings and warranty terms.
- Residential:Single-family homeowners and rental property managers purchasing for periodic groundskeeping. Volume flows through home improvement chains and online marketplaces with seasonal promotional calendars tied to spring planting and fall cleanup cycles.
- Commercial:Multi-site property management firms, corporate campuses, and retail centers requiring fleet standardization. Buying committees specify cross-brand battery compatibility and consolidated invoicing through national distribution agreements.
- Agricultural:Vineyards, nurseries, and specialty crop operations utilizing tractor-mounted attachments and walk-behind equipment. Dealer networks in California's Central Valley and Florida's citrus belt provide localized service support for these customers.
- Public Spaces:Municipal parks departments, highway maintenance crews, and school district groundskeepers. Procurement runs through formal bidding processes with EPA emission compliance and OSHA noise exposure certification as mandatory specifications.
Commercial applications command premium pricing tiers. Public spaces procurement is gaining share fastest as infrastructure maintenance budgets expand.
End User:
Volume concentration varies sharply by user type, with professionals replacing equipment on compressed cycles compared to homeowners who retain tools for extended durations.
- Homeowners:Residential property owners purchasing for personal use with replacement cycles extending seven to ten years. Retailers capture this demand through spring promotional events and financing programs for higher-ticket power equipment.
- Professionals:Independent groundskeepers and small maintenance crews requiring commercial-grade durability. These operators prioritize runtime parity and rapid battery swap capabilities to sustain daily production schedules.
- Landscape Contractors:Incorporated businesses serving commercial and municipal contracts with fleet sizes exceeding fifty units. Equipment-as-a-service subscription models are displacing capital purchases among contractors in high-turnover labor markets.
- Garden Centers:Retail and wholesale nurseries utilizing specialized propagation and transplanting equipment. These operators source through horticultural supply distributors with seasonal credit terms aligned to planting cycles.
Landscape contractors drive replacement demand. Garden centers represent the most stable margin profile due to specialized equipment requirements.
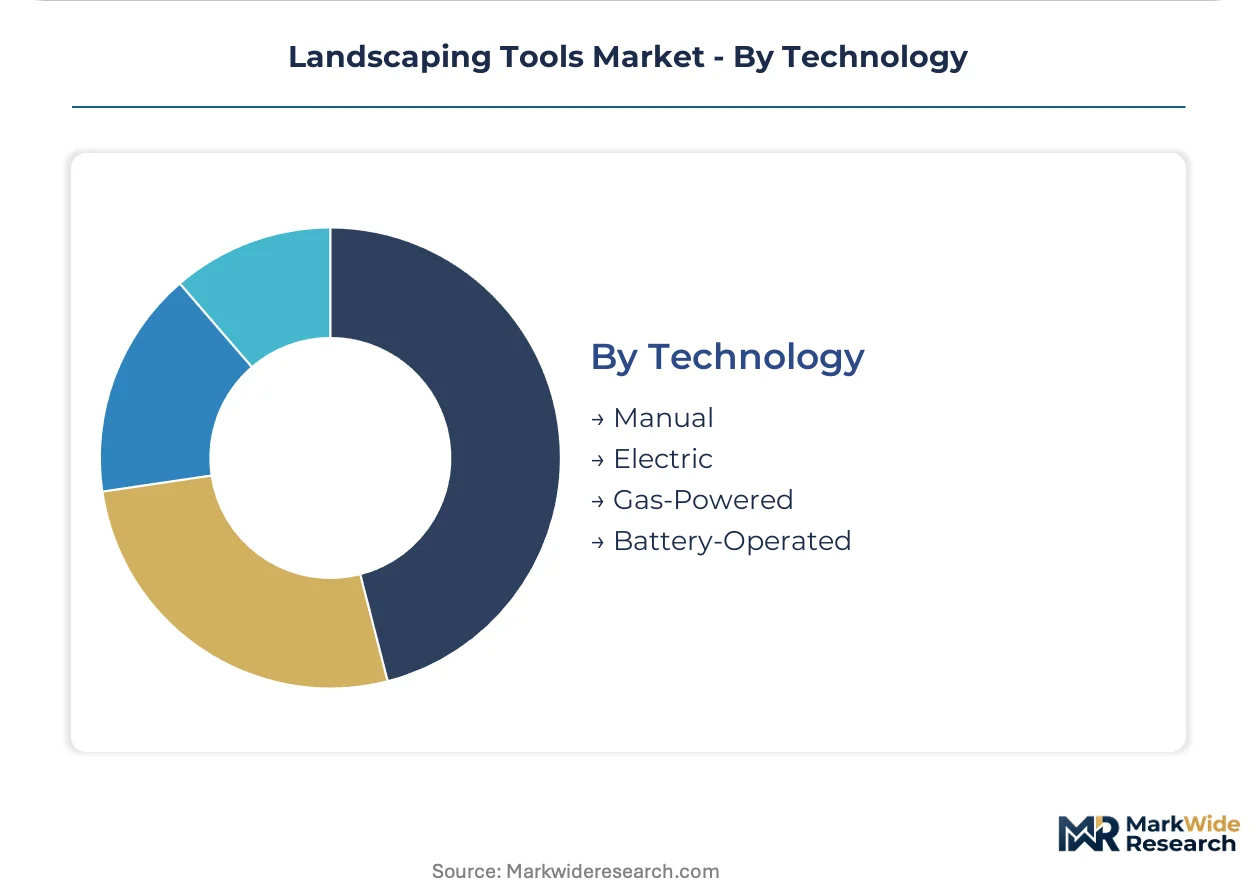
Technology:
Maturity curves diverge across technology platforms, with gas-powered equipment retaining residual value in unregulated jurisdictions while battery systems capture specification mandates in progressive municipalities.
- Manual:Human-powered implements with no motor or power source, valued for precision control and zero operating cost. Demand persists among organic gardening practitioners and heritage landscape restoration specialists.
- Electric:Corded equipment limited by tether radius but offering continuous runtime for stationary applications. These systems retain niche positioning among residential users with small lots and reliable grid access.
- Gas-Powered:Two-stroke and four-stroke small engines delivering highest power-to-weight ratios for commercial clearing and heavy-duty applications. CARB ordinances in California municipalities are constraining distribution channels for this technology.
- Battery-Operated:Lithium-ion platforms with interchangeable power sources across multiple tool categories. Lithium-ion energy density improvements are compressing replacement cycles for gas-powered fleets in professional segments.
Gas-powered equipment retains largest installed base. Battery-operated technology is climbing the fastest as regulatory thresholds tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in landscaping equipment tilt toward net-import status in advanced economies while manufacturing clusters concentrate in cost-optimized jurisdictions. Export-oriented producers in Asia-Pacific supply battery pack assemblies and motor components to assembly plants in North America and Europe. Regional demand patterns diverge sharply based on climatic conditions and regulatory stringency.
United States
Sun Belt metropolitan areas in Texas, Florida, and Arizona sustain year-round groundskeeping demand that compresses equipment replacement cycles. EPA Phase 3 emission standards constrain small-engine specifications and accelerate distributor pivots toward battery-operated inventory. California's municipal gas-equipment bans force immediate product mix adjustments for brands serving western states.
Germany
Precision engineering traditions support high-value commercial-grade equipment production for export across European Union markets. REACH regulations and EU Green Deal targets pressure manufacturers toward electrified platform development. Industrial clusters in Baden-Württemberg host specialized suppliers of brushless motor controllers and lithium-ion management systems.
China
Domestic battery cell production capacity anchors global supply chains for cordless landscaping equipment platforms. MIIT industrial policy directives prioritize lithium-ion energy density improvements and domestic cathode material processing. Manufacturing concentrations in the Yangtze River Delta export motor assemblies and battery packs to North American and European OEMs.
Japan
Advanced robotics integration for autonomous mowing systems originates from METI-supported R&D programs targeting labor shortage mitigation. JIS certification requirements establish durability benchmarks that filter into premium-tier export specifications. Industrial corridors around Nagoya and Osaka host precision manufacturing networks for compact powertrain components.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance tracks for equipment distributed across GB and EU markets. London metropolitan procurement specifications increasingly mandate low-noise certification for municipal groundskeeping contracts. Distribution networks in the Midlands serve as consolidation points for Irish and Scandinavian re-export flows.
Landscaping Tools Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology integration dimensions. The vendor base organizes around three tiers: diversified industrial conglomerates with precision manufacturing networks, dedicated outdoor power equipment specialists with robotics capabilities, and component suppliers with captive battery chemistry expertise. Consolidation pressures intensify as battery platform standardization raises scale thresholds for viable participation. Strategic moves concentrate on interchangeable battery ecosystem expansion and municipal procurement relationship deepening.
Within the diversified industrial tier, Deere & Company and Kubota Corporation exemplify capital-intensive positioning through precision manufacturing networks and tractor-mounted attachment dominance. Husqvarna Group occupies a specialist position anchored by dedicated robotics division capabilities. These three entities represent distinct archetypes: conglomerate-scale agricultural-industrial crossover, pure-play outdoor power innovation, and emerging autonomous systems integration.
| Leading Market Players |
|---|
| Deere & Company |
| Husqvarna Group |
| The Toro Company |
| Stanley Black & Decker |
| Robert Bosch GmbH |
| Kubota Corporation |
| MTD Products |
| Briggs & Stratton Corporation |
| Honda Power Equipment |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety day battery pack lead times concentrate pricing power with cathode material processors in China, compressing margin buffers for North American and European OEMs while forcing distributors into forward inventory commitments. This inventory intensity amplifies working capital pressure across dealer networks serving professional landscape contractors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates brushless DC motor architectures with extended warranty terms from brushed-motor alternatives and entry-level consumer units. Cost compression in standard tiers is intensifying because lithium-ion cell costs fluctuate with cathode metal spot markets. Residential homeowners exhibit highest price sensitivity, while municipal procurement committees prioritize EPA compliance certification over unit economics.
Supply Chain Analysis
Inventory carrying costs for battery platforms rest on concentrated cathode processing in China, South Korea, and Japan. Raw material dependencies span lithium carbonate, nickel sulfate, and cobalt hydroxide feedstocks. Single-source vulnerability in Chinese graphite anode supply creates tariff exposure under pending trade actions. Distribution runs through specialized dealer networks bundling maintenance contracts for professional segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery mode as equipment replacement cycles compress under California's municipal gas-equipment bans and EPA Phase 3 compliance deadlines. Sun Belt urbanization sustains utilization rates above seasonal northern patterns.
For Market Incumbents: Shield service revenue streams by deepening vertical integration into battery management system firmware and certified technician training networks. Defend against pure-play battery specialists by locking municipal procurement relationships through equipment-as-a-service subscription bundling. For New Entrants and Emerging Players: Differentiate on interchangeable battery platform compatibility, targeting independent landscape contractors in Texas and Florida metropolitan corridors underserved by national dealer networks. Pursue white-label manufacturing partnerships with agricultural supply cooperatives seeking private-label garden equipment lines. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-driven replacement cycle play because emission standards and noise ordinances force fleet turnover regardless of macroeconomic conditions. Target component suppliers with captive lithium-ion chemistry expertise and JIS-certified manufacturing capabilities. Watch CARB-equivalent ordinance adoption across additional Sun Belt states as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Cross-brand compatibility reduces contractor inventory complexity and locks in ecosystem switching costs. |
| Equipment-as-a-Service Launch | Subscription pricing shifts capex burdens from high-turnover landscape contractors to manufacturers. |
| Robotics Division Expansion | Autonomous mowing systems address labor shortages in municipal golf course and corporate campus segments. |
| Certified Technician Training Scale-Up | OSHA and high-voltage battery repair credentials close service capacity gaps faster than community college programs. |
| Smart Irrigation Convergence | Soil moisture sensor integration captures water utility rebate programs and deepens municipal client stickiness. |
Research Methodology
A spread of perspectives from landscape contractor fleet managers, municipal procurement officers, dealer network principals, and battery pack engineering directors converged on the working assumptions. Primary fieldwork combined structured interviews with aftermarket service heads and OEM platform engineers alongside secondary validation through EPA enforcement databases, state CARB ordinance filings, and customs trade records. Bottom-up equipment unit forecasts triangulated against top-down landscaping services revenue estimates.
Segmentation dimensions modeled include product type, application tier, end-user archetype, and technology platform across the projection horizon. CAGRs derived from equipment replacement cycle compression rates and regulatory compliance deadline clustering. Forecast inputs incorporated lithium-ion energy density improvement curves and Sun Belt metropolitan construction permit flows.
Material uncertainties — supply disruption in Chinese cathode processing, uneven state-level ordinance adoption timelines, and technician certification program scale — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Digital Laser Levels Market
Tools
Tool Boxes Market
Tools
Pliers Market
Tools
Impact Wrenches Market
Tools
Drilling Tools Market
Tools
China Power Tools Market
Tools
End Mill Holder Market
Tools
Global Protractor Market
Tools
China Power Tools and Hand Tools Market
Tools
GCC Machine Tools Market
Tools
Hydraulic Tools and Equipment Market
Tools
Spray Gun Market
Tools
Portable Boring Machines Market
Tools
Vise-Grip Pliers Market
Tools
Tool Hammer Market
Tools
Power Nibbler Market