
 Composite Rebar Market | 2026-2036
Composite Rebar Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Rebar Market Analysis
High-performance grade specification is rotating toward the center of composite rebar procurement decisions across public infrastructure programs. Aslan FRP leverages its North American manufacturing footprint to dominate transportation agency supply chains. Pultrall anchors its competitive position through deep specialization in pultruded FRP profiles for marine and civil applications. Schoeck differentiates via European technical approvals and established specification relationships with German and Austrian building authorities.
Composite rebar consists of continuous fiber filaments—typically glass, carbon, or basalt—impregnated with thermosetting resin and formed through pultrusion into ribbed bars that achieve tensile strengths exceeding 100 ksi while remaining electromagnetically transparent and immune to chloride corrosion. Glass Fiber Reinforced Polymer occupies the volume leadership position due to its cost-performance ratio in highway decks and parking structures, while Carbon Fiber Reinforced Polymer captures premium margin pools in structural strengthening and seismic retrofit applications where stiffness-to-weight ratios justify higher material costs. Basalt Fiber Reinforced Polymer competes as a mid-tier alternative with superior alkaline resistance compared to standard E-glass formulations.
ASTM D7957, ACI 440.1R, and CSA S807 collectively define the material qualification, design methodology, and quality assurance protocols that govern composite rebar acceptance in North American construction markets, with European equivalents including EN 13706 and ETAG 013 under EOTA oversight. Regulatory fragmentation across national building codes continues to constrain market access in jurisdictions lacking explicit FRP reinforcement chapters, creating compliance overhead for manufacturers pursuing multi-country certification. Stakeholders must monitor specification momentum in emerging infrastructure resilience codes, as climate-adaptive design standards increasingly embed corrosion resistance as a mandatory performance criterion rather than an optional upgrade.
Market Dynamics
Infrastructure resilience mandates are compressing specification timelines for corrosion-resistant reinforcement materials across public transportation procurement programs.
Growth Catalysts
- FHWA Bridge Deck Specifications:Updated federal guidelines mandating chloride-resistant reinforcement accelerate specification shifts in coastal highway projects.
- Glass Fiber Pultrusion:Continuous processing advances reduce manufacturing cycle times and enable cost-competitive positioning against epoxy-coated steel.
- Florida Department of Transportation:State-level material prequalification programs create predictable demand pools for approved composite rebar suppliers.
Market Restraints
- Vinyl Ester Resin Volatility:Petrochemical feedstock exposure creates margin compression risk for thermoset-dependent manufacturers.
- Single-Source Fiber Supply:E-glass roving concentration among three dominant suppliers concentrates input risk in North American production networks.
- ACI 440.1R Design Complexity:Engineer familiarity gaps with FRP-specific flexural and shear calculations slow specification velocity in private construction.
Strategic Opportunities
- Seismic Retrofit Applications:Carbon fiber reinforced polymer stiffness-to-weight ratios open premium positioning in structural strengthening of California and Japan infrastructure.
- EU Green Deal Procurement:Embodied carbon scoring in public works tenders favors lightweight reinforcement with lower transport emissions.
- Digital Specification Platforms:BIM-integrated material libraries enable direct architect-specifier engagement bypassing traditional distributor channels.
Industry Challenges
- Pultrusion Technician Shortage:Specialized die maintenance and process control expertise scarcity constrains capacity expansion timelines.
- Multi-Jurisdictional Certification:Parallel ASTM D7957, CSA S807, and EN 13706 testing requirements extend product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Rebar Market |
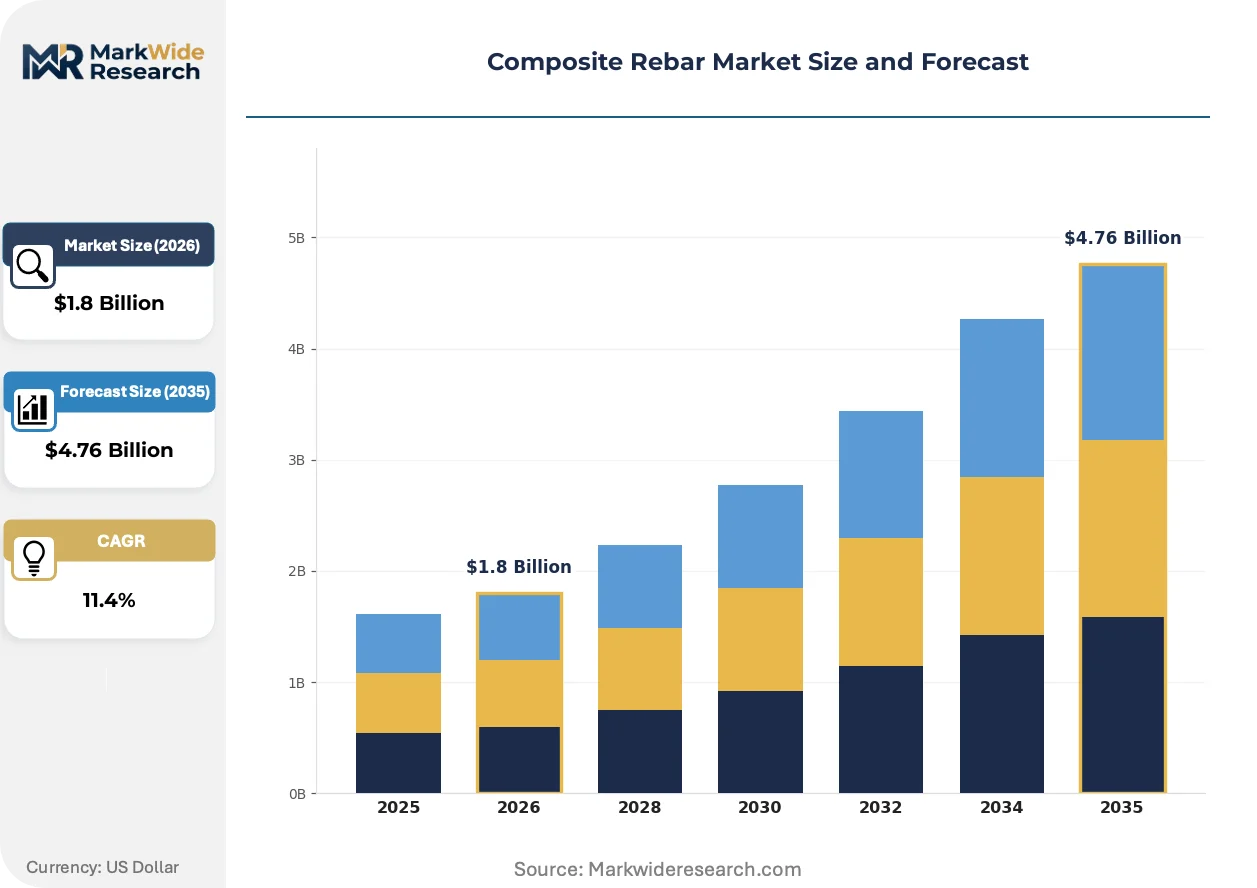
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Fiber Reinforced Polymer, Carbon Fiber Reinforced Polymer, Basalt Fiber Reinforced Polymer, Steel End User: Construction, Infrastructure, Marine Applications, Industrial Application: Bridges, Highways, Parking Structures, Buildings Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Aslan FRP, Armastek, Pultrall, Schoeck, Fiberline Composites, Marshall Composite Technologies, Nanjing Fenghui Composite, Sireg Geotech, Kodiak Fiberglass Rebar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Rebar Market Emerging Trajectories
Material qualification protocols and procurement digitization are restructuring how composite reinforcement enters specification workflows across transportation agencies.
Basalt fiber formulations are displacing standard E-glass in alkaline environments where portland cement exposure degrades conventional glass chemistry. Russian and Ukrainian basalt feedstock processors are securing long-term supply agreements with European pultruders. The displacement is compressing the premium positioning of carbon fiber in mid-performance structural applications.
ASTM D7957 revision cycles are accelerating test method harmonization with CSA S807 to reduce dual-certification burden for North American suppliers. The industrial consequence is streamlined agency prequalification processes in Ontario and California. Basalt-heavy product lines are capturing disproportionate specification share in these harmonization-first jurisdictions.
Agency engineers now demand BIM-embedded material property databases rather than static PDF submittals. State DOTs in Texas and Washington are piloting digital twin compatibility requirements that favor suppliers with parametric product models. This behavioral pivot is most visible in bridge deck reconstruction programs where design-build contracts compress traditional specification windows.
Composite Rebar Market Segmentation
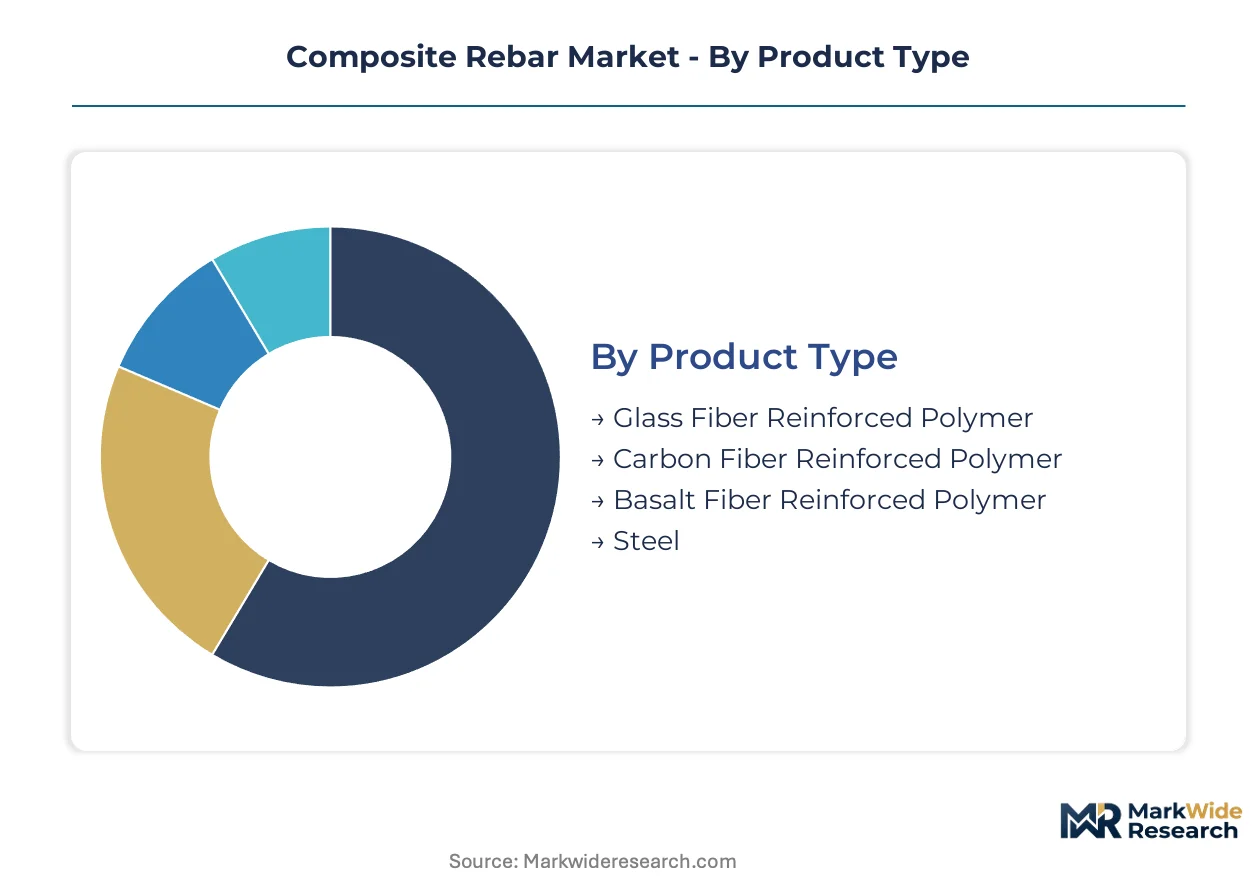
Composite rebar procurement divides sharply across material chemistry, project type, and channel economics. Specification engineers weight corrosion resistance against first-cost premiums differently across highway agencies, marine contractors, and private developers.
Product Type:
ASTM D7957, ACI 440.1R, and CSA S807 each impose distinct qualification burdens that segment manufacturers by certification depth.
- Glass Fiber Reinforced Polymer:E-glass filaments in vinyl ester resin achieve tensile strengths exceeding 100 ksi while maintaining electromagnetic transparency. Florida Department of Transportation prequalification programs concentrate procurement volume in coastal US states where chloride-induced corrosion drives replacement cycles.
- Carbon Fiber Reinforced Polymer:PAN-based carbon fiber delivers superior stiffness-to-weight ratios for seismic retrofit and structural strengthening. California and Japan infrastructure programs specify CFRP where deflection limits justify material cost premiums over glass alternatives.
- Basalt Fiber Reinforced Polymer:Continuous basalt filaments offer alkaline resistance superior to standard E-glass in portland cement exposure.
- Steel:Conventional black steel and epoxy-coated variants retain specification share in cost-sensitive private construction lacking corrosion mandates.
Glass Fiber Reinforced Polymer handles the majority of throughput; Basalt Fiber Reinforced Polymer is the fastest mover on share.
End User:
Public agency procurement cycles stretch 18-24 months while private construction moves on compressed design-build timelines.
- Construction:Private developers and general contractors specify composite rebar in parking structures and high-rise cores where long-term maintenance cost avoidance offsets first-cost premiums. Engineer familiarity gaps with ACI 440.1R flexural calculations slow specification velocity in this segment.
- Infrastructure:State DOTs and federal highway agencies drive standardization through prequalification programs. US Federal Highway Administration bridge deck specifications mandate chloride-resistant reinforcement in coastal zones.
- Marine Applications:Port authorities and coastal defense contractors specify pultruded FRP for seawall tie-backs and dock structures.
- Industrial:Chemical processing facilities and wastewater treatment plants deploy corrosion-resistant reinforcement in aggressive exposure environments.
Infrastructure commands the largest committed volume; Construction shows the steepest expansion trajectory as private engineer training programs mature.
Application:
Structural load paths and exposure severity determine whether GFRP cost economics or CFRP performance premiums prevail.
- Bridges:Deck slabs and barrier walls face cyclic chloride loading from de-icing salts and marine atmospheres. Texas and Washington State DOTs pilot digital twin compatibility requirements that favor suppliers with parametric product models.
- Highways:Pavement reinforcement and sound wall foundations specify composite rebar where electromagnetic transparency supports tolling and communications infrastructure.
- Parking Structures:Multi-level decks in northern climates suffer accelerated corrosion from tracked de-icing chemicals.
- Buildings:Foundation mats and elevator cores in coastal high-rises specify FRP where groundwater chlorides threaten conventional reinforcement.
Bridges absorb the dominant specification share; Buildings are climbing the fastest as urban coastal construction intensifies.
Distribution Channel:
Agency procurement rules and project delivery methods fragment channel economics across direct and intermediated routes.
- Direct Sales:Large transportation agencies and design-build consortia negotiate mill-direct contracts for multi-year bridge programs. State-level material prequalification creates predictable demand pools bypassing distributor markups.
- Online Retail:BIM-integrated material libraries enable architect-specifier engagement through digital platforms. Texas DOT pilots favor suppliers with parametric product models accessible through specification software.
- Wholesalers:Regional building material suppliers stock standard diameters for contractor spot purchases.
- Distributors:Specialized construction supply houses provide technical support and cut-to-length services for complex projects.
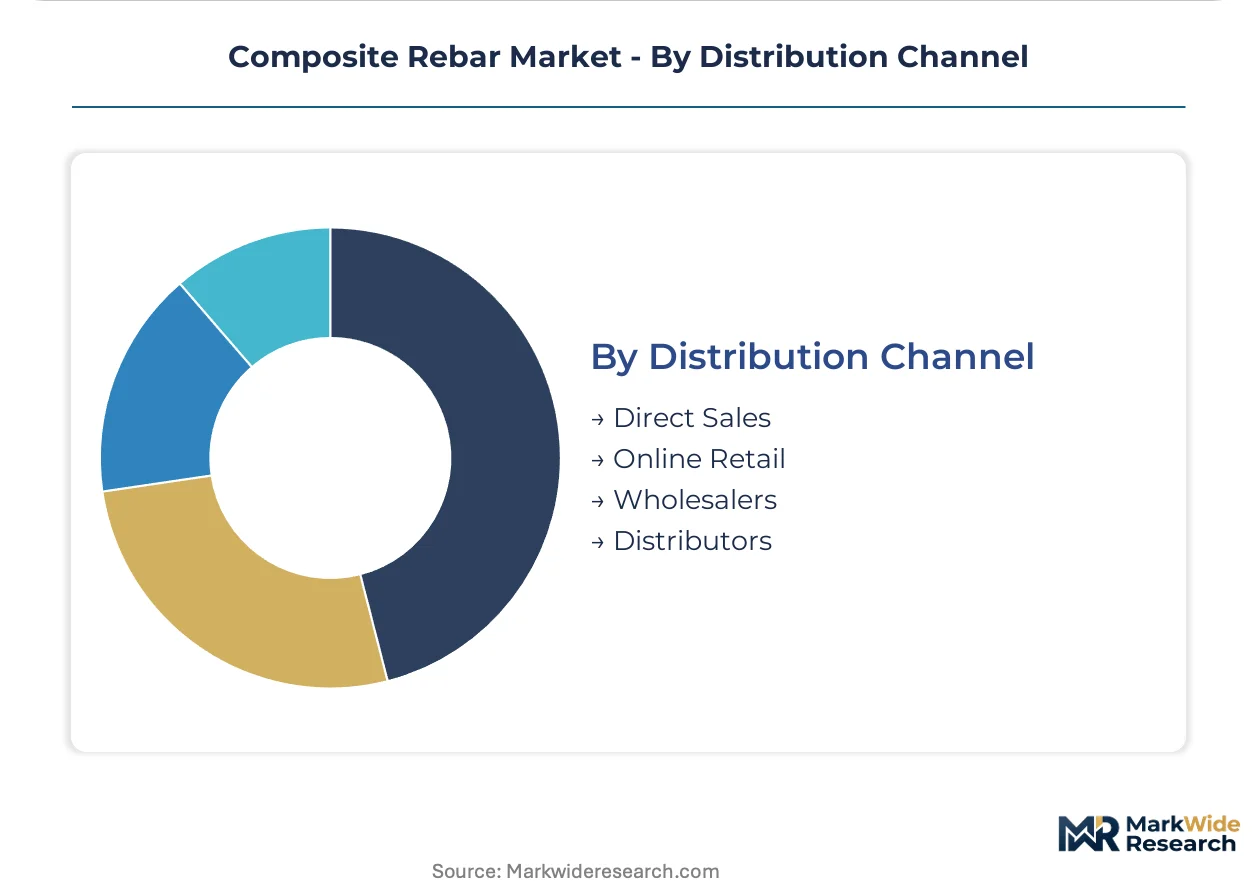
Direct Sales captures the dominant contract value; Online Retail is gaining share fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pultrusion capacity clusters in the United States, Germany, and China, with specialized glass fiber roving supply chains anchoring North American production networks. Regulatory harmonization between ASTM and CSA standards is compressing cross-border qualification timelines for manufacturers serving multiple jurisdictions.
United States
Federal Highway Administration bridge deck specifications mandate chloride-resistant reinforcement in coastal highway zones. State DOT prequalification programs in Florida, Texas, and Washington create predictable demand pools for approved suppliers. The Southeast corridor from Florida through Georgia concentrates specification volume where saltwater intrusion accelerates infrastructure replacement cycles.
Germany
Technical approvals from German building authorities anchor specification relationships across Central European infrastructure programs. The EU Green Deal's embodied carbon scoring in public procurement favors lightweight reinforcement materials with lower transport emissions. Industrial clusters in Bavaria and North Rhine-Westphalia host pultrusion operations serving Dutch and Austrian cross-border demand.
Canada
CSA S807 certification requirements govern composite rebar acceptance in Ontario and British Columbia transportation projects. Provincial infrastructure resilience mandates prioritize corrosion-resistant materials in marine-exposed bridge decks. The Greater Toronto Area anchors specification engineering expertise for Great Lakes region projects.
China
Dual carbon goals and coastal infrastructure investment drive specification of basalt fiber alternatives in port and marine construction. Domestic glass fiber roving supply concentration enables cost-competitive positioning against imported reinforcement products. Yangtze River Delta manufacturing clusters serve Southeast Asian export markets through integrated pultrusion operations.
Japan
METI-led seismic retrofit programs specify carbon fiber reinforced polymer for structural strengthening in earthquake-prone urban corridors. Stiffness-to-weight ratio requirements in high-rise core applications justify premium material positioning over glass alternatives. Osaka-Kobe industrial zones concentrate civil engineering procurement for Pacific coastal infrastructure resilience.
Composite Rebar Market Vendor Landscape
Concentration sits with North American and European specialists holding transportation agency prequalification relationships. The vendor base spans three tiers: multinational composite material conglomerates with diversified reinforcement portfolios, regional pultrusion specialists serving single-country procurement programs, and emerging basalt fiber processors capturing mid-performance structural applications. Strategic differentiation runs through certification depth and specification engineering relationships rather than manufacturing scale alone. Competitive moves center on ASTM/CSA/EN harmonization investments and BIM-embedded product data partnerships with state DOT digital twin pilots.
Among North American fabricators, Aslan FRP and Kodiak Fiberglass Rebar occupy positions within the transportation-specialist archetype, anchoring supply chain relationships with FHWA-compliant agencies. Pultrall represents the marine-civil specialization vector through its Quebec-based pultrusion focus. Schoeck sits within the European technical approval tier, leveraging German and Austrian building authority relationships. Nanjing Fenghui Composite exemplifies the Asian basalt fiber processing archetype, while Marshall Composite Technologies anchors the US regional specialist position. These five entities collectively span the certification-geography matrix that defines competitive positioning in procurement-constrained public infrastructure markets.
| Leading Market Players |
|---|
| Aslan FRP |
| Armastek |
| Pultrall |
| Schoeck |
| Fiberline Composites |
| Marshall Composite Technologies |
| Nanjing Fenghui Composite |
| Sireg Geotech |
| Kodiak Fiberglass Rebar |
| Others |
Supply Flow & Price Mechanics
ASTM D7957 and CSA S807 certification requirements gate both supplier qualification and price tier formation in North American composite rebar procurement. State DOT prequalification programs concentrate buying power among approved vendors while creating certification-premium tiers that separate agency-compliant suppliers from spot-market competitors.
Pricing Analysis
ASTM D7957 dictates the pricing tier structure across the composite rebar market. Three-tier pricing stratifies across premium carbon fiber formulations, standard glass fiber products, and economy basalt alternatives. Price differentiation centers on certification depth and fiber chemistry grade. Cost compression in standard GFRP segments is intensifying because vinyl ester resin feedstock volatility squeezes manufacturer margins. Private construction contractors exhibit the highest price sensitivity, while infrastructure agencies prioritize lifecycle cost avoidance over first-cost premiums.
Supply Chain Analysis
Inventory cycles for E-glass roving extend 8-12 weeks, creating working capital intensity for North American pultruders. Manufacturing gravity centers on the United States, Germany, and China, with specialized glass fiber supply anchored in domestic Chinese and North American production networks. Raw material dependencies rest on petrochemical-derived vinyl ester resin, continuous E-glass filaments, and PAN-based carbon fiber precursor. Single-source fiber concentration among three dominant roving suppliers concentrates input risk. Distribution runs through direct mill contracts for large transportation agencies and specialized construction distributors for contractor spot purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
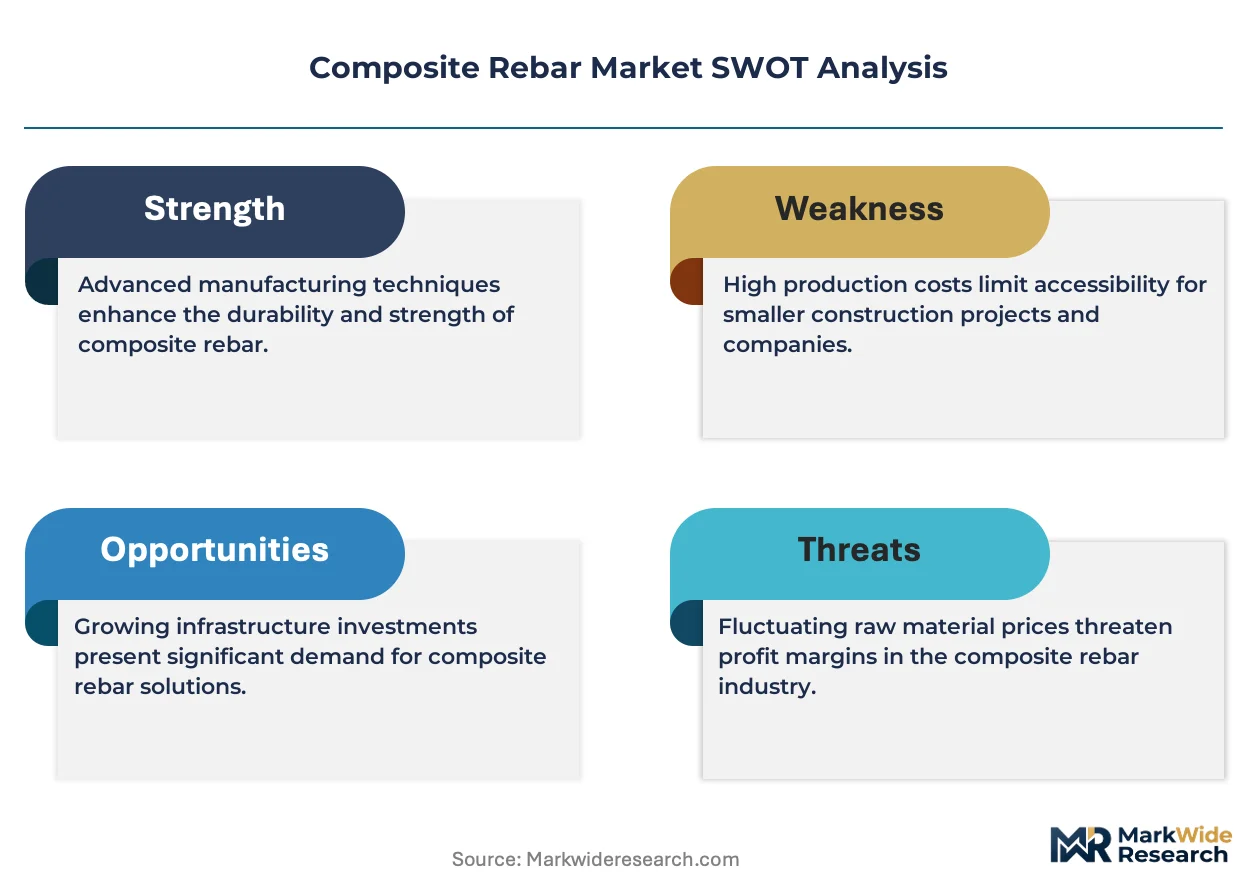
The composite rebar market presents a regulatory-entrenchment defensive moat. State DOT prequalification programs and harmonized ASTM/CSA certification requirements create switching costs that protect incumbent positions while raising barriers for unqualified competitors.
For Market Incumbents: Compound specification engineering relationships with FHWA-compliant agencies through BIM-embedded product data partnerships. Deepen backward integration into vinyl ester resin formulation to defend margin position against petrochemical feedstock volatility. Prioritize ASTM D7957/CSA S807 harmonization investments to compress dual-certification overhead for cross-border procurement programs. For New Entrants and Emerging Players: Anchor in basalt fiber processing for mid-performance structural applications where alkaline resistance specifications displace standard E-glass. Target private construction parking structures and high-rise cores in coastal US states where engineer training programs are narrowing familiarity gaps with ACI 440.1R design methodologies. Pursue digital specification platform partnerships to bypass traditional distributor channel economics. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across carbon fiber reinforced polymer production as PAN precursor supply tightens. Long-term viability favors vertically integrated specialists with captive fiber supply and established agency prequalification relationships. Monitor specification momentum in emerging infrastructure resilience codes as the inflection signal for accelerated procurement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Harmonization Investment | ASTM D7957/CSA S807 alignment reduces dual-testing burden for Ontario and California suppliers. |
| Backward Integration into Resin Formulation | Captive vinyl ester production insulates margin compression from petrochemical feedstock volatility. |
| BIM-Embedded Product Data Partnership | Parametric models for Texas and Washington DOT digital twin pilots secure specification lock-in. |
| Basalt Fiber Supply Agreement | Long-term Russian and Ukrainian feedstock contracts anchor mid-tier positioning against carbon fiber. |
| Pultrusion Technician Training Program | Specialized die maintenance expertise alleviates capacity expansion constraints in North American operations. |
Methodological Framework
Operator-level perspectives from pultrusion plant managers, state DOT materials engineers, FRP specification consultants, and construction procurement directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against ASTM D7957 revision documentation, FHWA bridge deck specification updates, and CSA S807 certification records. Trade data from USITC and customs filings provided import-export triangulation. Bottom-up segment sizing and top-down macro validation converged on volume and value estimates.
Sensitivity analysis framed the forecast architecture across the projection horizon. Segmentation dimensions modeled include fiber chemistry tier, end-use application, project delivery method, and regional regulatory cluster. CAGRs derived from historical specification velocity trends and infrastructure investment pipeline analysis. Forecast inputs incorporated FHWA resilience mandate implementation timelines and state-level DOT prequalification program expansion trajectories.
Decision-makers should treat outputs as directional under sustained infrastructure investment and regulatory harmonization assumptions; material deviation would warrant model refresh. Specific risks that could revise forecasts include vinyl ester resin supply disruption, ACI 440.1R design methodology adoption delays in private construction, and jurisdictional certification fragmentation in emerging markets. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Refractory Cement Market
Building Materials
Masonry Cement Market
Building Materials
Aluminum Door and Window Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
China Cement Market
Building Materials
GRC Cladding Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Steel Slag Market
Building Materials
Europe Fiber Cement Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Facade Gasket Market
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Concrete Market
Building Materials
Global Building Panels Market
Building Materials
Europe Fireproof Cladding Market