
 Construction Stone Market | 2026-2036
Construction Stone Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Stone Market Analysis
Quarry operators in Rajasthan is recalibrating extraction schedules to align with India's stricter BIS dimension stone protocols. CRH leverages its integrated supply chain across multiple continents to secure consistent block quality. Martin Marietta Materials anchors North American infrastructure demand through its extensive crushed stone network. Vulcan Materials Company competes on logistics density, positioning rail-linked quarries near major metropolitan construction zones.
Construction stone encompasses naturally occurring rock materials including granite, marble, limestone, and sandstone, quarried and processed to specified dimensions with compressive strengths typically ranging from 50 to 250 MPa depending on lithology. These materials serve as structural load-bearing elements, cladding systems, and aggregate feedstock for concrete and asphalt production. Granite and marble segments command premium positioning in interior design applications where aesthetic specification drives margin pools. Crushed stone forms the volume backbone of infrastructure spending, while slab and tile formats capture higher value per ton in building and landscaping channels.
India's BIS, the EPA in the United States, and the EU's CE marking framework collectively shape extraction permits, emissions controls, and product safety thresholds for dimension stone entering commercial building supply chains. REACH compliance in Europe and evolving silica exposure rules under OSHA constrain processing methods and quarry ventilation investments. Stakeholders must monitor how carbon border adjustments and embodied carbon disclosure requirements reshape competitive access for imported versus domestically quarried stone.
Market Dynamics
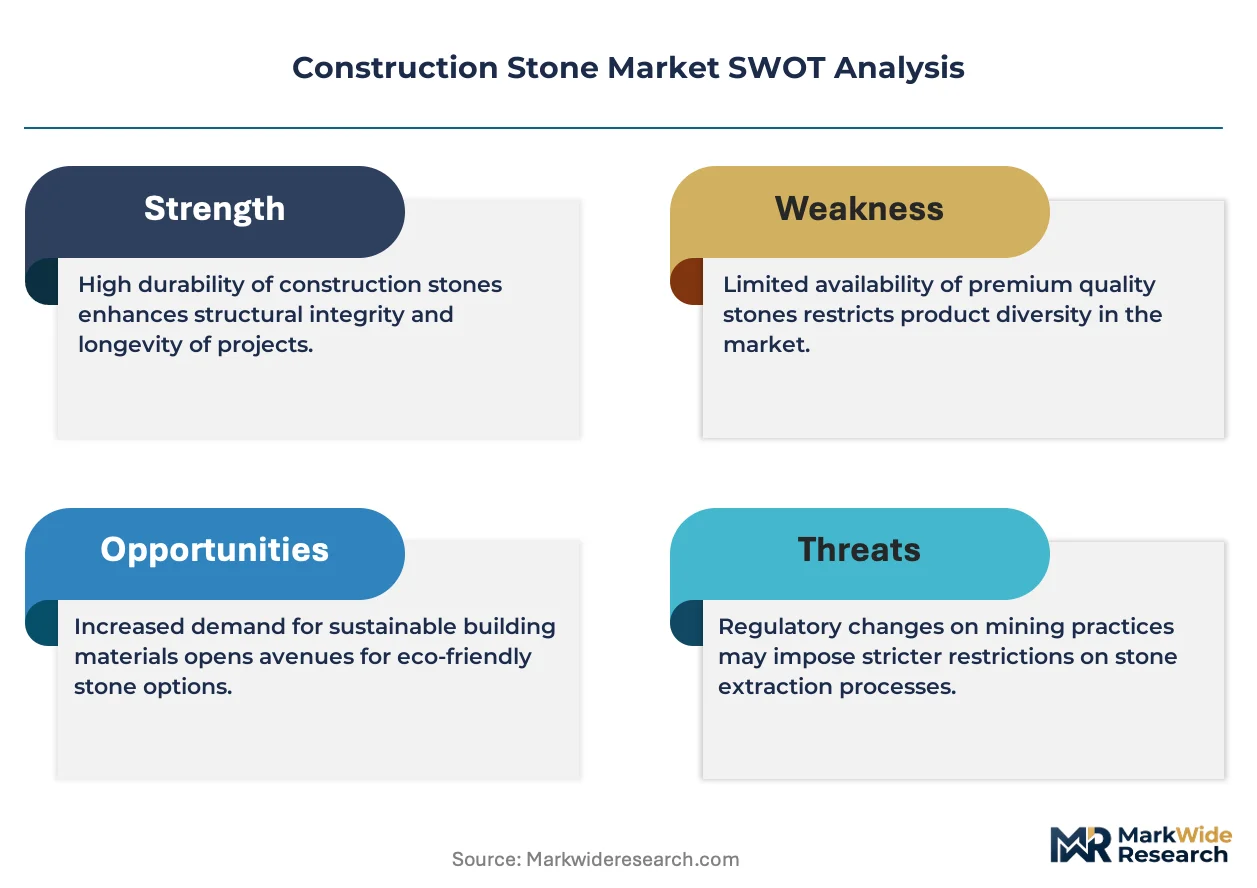
India's BIS certification tightening for dimension stone is forcing quarry operators to recalibrate extraction schedules and invest in quality control infrastructure, compressing supply timelines while elevating material grade requirements across residential and commercial procurement channels.
Growth Catalysts
- Urban residential construction:High-rise residential towers in Mumbai and Bangalore specify granite and marble cladding, pulling premium dimension stone volumes through certified fabricators.
- REACH compliance in Europe:ECHA's evolving substance restrictions on construction materials are accelerating certified stone imports from Indian quarries meeting CE marking protocols.
- Diamond wire cutting:This extraction technology is reducing block waste in Rajasthan quarry clusters, improving yield rates for export-grade material.
Market Restraints
- Diesel price volatility:Quarry operators in Gujarat face margin compression from fuel costs powering heavy extraction equipment and block transport fleets.
- Silica exposure regulations:OSHA's respirable crystalline silica rules mandate ventilation investments in US processing facilities, elevating fixed cost structures.
- Recycled concrete aggregate:Demolition waste crushing is displacing virgin crushed stone in European road base applications, particularly in Germany and the Netherlands.
Strategic Opportunities
- Carbon border adjustments:The EU's CBAM framework creates competitive openings for low-carbon quarried stone from operations with renewable energy integration.
- Landscaping segment:Premium patio and garden stone formats command higher value per ton than structural aggregate, with demand concentrating in US Sun Belt metro areas.
- Digital stone templating:CNC integration with 3D scanning is enabling custom fabrication for luxury hospitality interiors, compressing design-to-installation cycles.
Industry Challenges
- Certified stonemason shortage:India's BIS dimension stone protocols require trained inspectors at quarry and processing stages, creating recruitment bottlenecks in Rajasthan and Gujarat.
- Legacy equipment retrofit costs:Water recycling and dust suppression systems for existing gang saws demand capital deployment that smaller processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Stone Market |
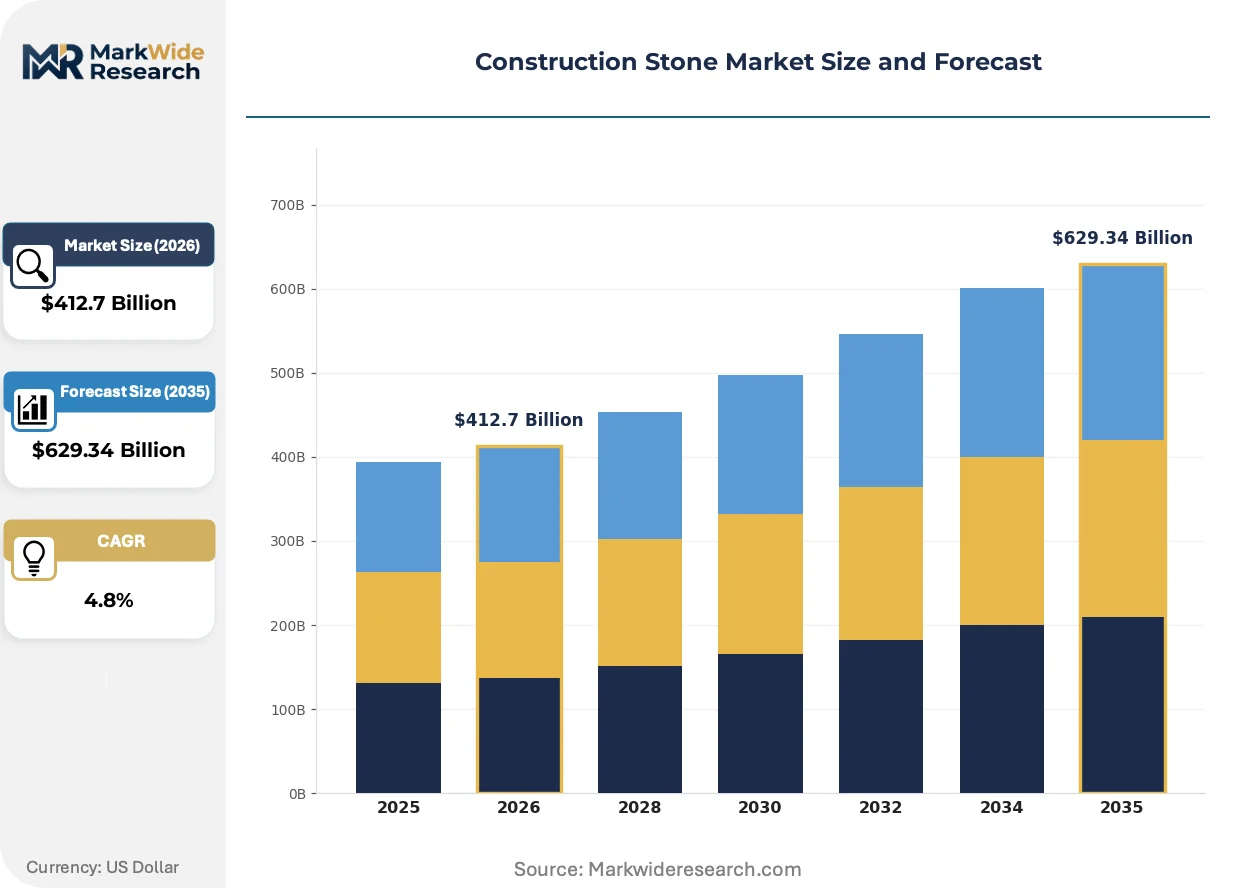
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $629.34 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Granite, Marble, Limestone, Sandstone Application: Building, Landscaping, Interior Design, Infrastructure Size: Small, Medium, Large, Custom Form: Blocks, Slabs, Tiles, Crushed Stone |
| Companies Covered | CRH, Martin Marietta Materials, Vulcan Materials Company, LafargeHolcim, HeidelbergCement, Cosentino, Caesarstone, Polycor Inc., Boral Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Stone Market Emerging Trajectories
Extraction and processing technologies are converging with environmental compliance frameworks, reshaping how dimension stone moves from quarry to specification. Automation and carbon accounting are becoming competitive differentiators.
Wire saw automation systems are automating block extraction in hard-rock quarries, with Rajasthan operators deploying sensor-guided cutting heads to reduce labor exposure to silica dust and vibration hazards. Large-scale infrastructure contractors specify automation-certified quarries for volume contracts, compressing procurement timelines. This technology is automating the shift from manual drilling-and-blasting to precision extraction, reducing yield loss and enabling thinner slab production.
REACH authorization requirements for construction chemicals are constraining resin-based stone treatments and adhesives used in European cladding installations. ECHA's substance evaluation process is extending compliance timelines for Indian exporters seeking CE marking. Fabricators serving German and French commercial building markets are reformulating surface finishes to eliminate restricted substances, accelerating water-based treatment adoption.
Architects and developers are unbundling stone specification from general contractor procurement, engaging directly with certified quarries for large commercial projects. This disintermediation is compressing margin capture for traditional distributors while rewarding fabricators with BIS and CE dual certification. Mumbai and Delhi commercial towers exemplify this pattern, with design firms mandating quarry-of-origin documentation for marble and granite facades.
Construction Stone Market Segmentation
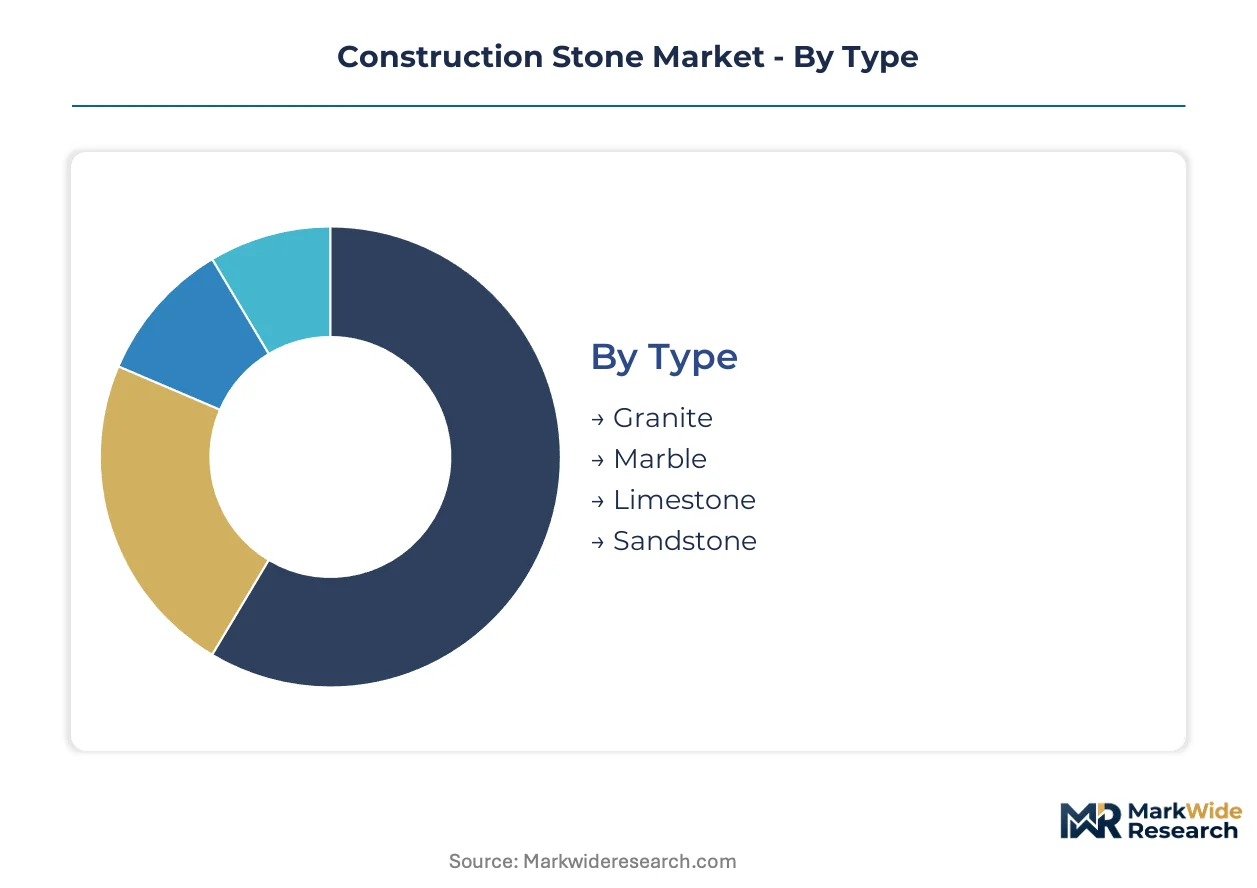
Construction stone segmentation reveals how certification requirements, processing intensity, and end-use specifications fragment procurement channels. Each dimension—material type, application, sizing, and form—carries distinct regulatory burdens and margin profiles that reshape supplier competitive positioning.
Type:
Granite and marble demand BIS dimension stone certification for Indian commercial exports, while limestone and sandstone face lighter protocol loads but stricter silica exposure controls during processing.
- Granite:Igneous rock with compressive strength typically exceeding 150 MPa, prized for structural load-bearing and high-traffic flooring. Demand concentrates in Mumbai and Bangalore high-rise residential towers where architects mandate quarry-of-origin documentation for facade cladding.
- Marble:Metamorphic carbonate stone with characteristic veining, specified for premium interior surfaces. Rajasthan quarry clusters feed both domestic luxury hospitality projects and European CE-marked export channels, with REACH compliance driving water-based treatment adoption.
- Limestone:Sedimentary carbonate rock serving as aggregate feedstock and dimensional cladding. Gujarat processors supply infrastructure contractors with medium-grade material for road base and commercial building facades.
- Sandstone:Clastic sedimentary stone with natural porosity variations, favored for landscaping and heritage restoration. Rajasthan deposits supply domestic garden architecture and Middle Eastern export markets with lower certification thresholds.
Leading the category by volume: Limestone. Growing fastest: Granite.
Application:
Building and infrastructure applications dominate tonnage flows, while interior design and landscaping command premium pricing through specification-driven procurement.
- Building:Structural and cladding stone for commercial and residential construction. Indian western states—Gujarat and Rajasthan—anchor supply to domestic tower projects and Middle Eastern developments.
- Landscaping:Patio, garden, and hardscape stone formats. US Sun Belt metro areas concentrate demand for premium value-per-ton material in residential outdoor living projects.
- Interior Design:Custom-fabricated surfaces for luxury hospitality and corporate environments. CNC integration with 3D scanning compresses design-to-installation cycles for this specification-heavy segment.
- Infrastructure:Crushed stone and riprap for roads, bridges, and utilities. North American rail-linked quarries position near metropolitan zones to capture public works procurement.
Volume leadership: Infrastructure. Fastest expansion: Interior Design.
Size:
Size classification determines handling equipment requirements, transport economics, and fabrication flexibility across quarry-to-site logistics chains.
- Small:Dimension stone under 0.5 cubic meters, suited for precision cutting and tile production. Tile fabricators in Gujarat optimize yield from small-block inputs for export markets.
- Medium:Standard construction blocks between 0.5 and 2 cubic meters. Rajasthan gang saw operators prefer this range for slab production efficiency.
- Large:Monolithic blocks exceeding 2 cubic meters, reserved for structural columns and statement cladding. Diamond wire cutting technology improves yield rates for this high-waste category.
- Custom:Non-standard dimensions specified for architectural landmarks and restoration projects. Direct quarry engagement by design firms bypasses traditional distribution for these premium contracts.
Standard blocks dominate procurement tonnage. Custom sizing gains share fastest in commercial tower segments.
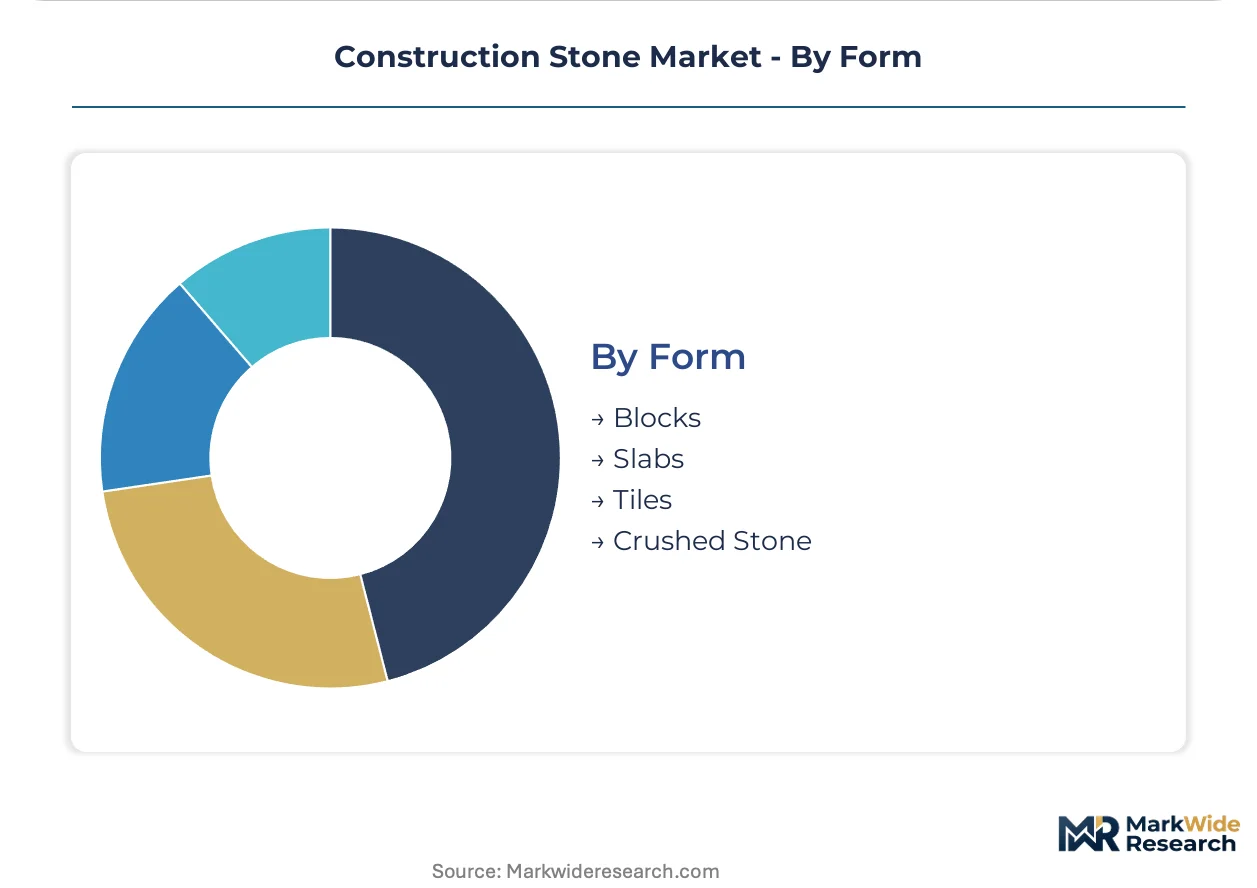
Form:
Form selection locks in downstream processing investment and determines which regulatory frameworks apply—dimension stone protocols versus aggregate standards.
- Blocks:Raw quarried material awaiting fabrication. Rajasthan operators recalibrate extraction schedules to align with BIS quality protocols, compressing supply timelines for certified export blocks.
- Slabs:Gang-sawn or wire-cut flat sections for countertops and wall cladding. Thinner slab production enabled by precision extraction technology expands addressable surface area per ton.
- Tiles:Precision-cut flooring and wall surfacing units. Small-format tile production concentrates in Gujarat processing clusters serving domestic and Gulf export markets.
- Crushed Stone:Mechanically fragmented aggregate for concrete, asphalt, and road base. European recycled concrete aggregate displacement threatens virgin crushed stone in German and Dutch infrastructure applications.
Crushed stone leads by volume. Slabs climb fastest on interior specification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rajasthan's granite and marble deposits anchor the Construction Stone Market's geographic footprint, with Gujarat's limestone belts and North American rail-linked quarry networks forming complementary supply anchors. India's western quarry clusters feed both domestic tower construction and certified export channels. European REACH compliance and US infrastructure stimulus are redrawing procurement flows across major economies.
India
High-rise residential towers in Mumbai and Bangalore specify BIS-certified granite cladding for facade applications. India's Bureau of Indian Standards tightened dimension stone protocols in 2024, forcing Rajasthan quarry operators to recalibrate extraction schedules and install quality control infrastructure. Gujarat's limestone processing clusters near Vadodara supply infrastructure contractors with road base material and commercial building facades.
United States
Metropolitan construction zones in Texas, Florida, and Georgia consume crushed stone volumes for highway expansion and residential foundation work. OSHA's respirable crystalline silica rules mandate ventilation investments in processing facilities, elevating fixed cost structures for domestic operators. Vulcan Materials Company and Martin Marietta Materials anchor North American supply through rail-linked quarries positioned near Sun Belt population centers.
Germany
Commercial building renovation and heritage restoration projects in Berlin and Munich specify CE-marked dimension stone for facade compliance. ECHA's REACH authorization requirements constrain resin-based stone treatments, accelerating water-based finish adoption among fabricators serving German markets. Recycled concrete aggregate displacement threatens virgin crushed stone demand in road base applications, particularly in North Rhine-Westphalia infrastructure procurement.
China
Yangtze River Delta and Pearl River Delta metro construction consumes granite and marble volumes for commercial tower cladding and interior surfacing. China's GB standards for construction materials and dual carbon goals are pressuring quarry operators to integrate renewable energy into extraction operations. Shandong Peninsula processing clusters supply both domestic infrastructure and Southeast Asian export markets with medium-grade limestone.
United Arab Emirates
Dubai and Abu Dhabi commercial developments and luxury hospitality projects import premium marble and granite slabs for interior specification. MOHAP construction material safety standards and UAE Green Building Council certification requirements filter supplier eligibility for government-backed developments. Jebel Ali fabrication clusters process imported blocks from Indian and European quarries for regional distribution.
Construction Stone Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue automation-certified quarry operations and carbon-accounted supply chains. The vendor base spans multinational aggregates conglomerates, regional dimension stone specialists, and integrated building materials groups. Three archetypes dominate: scale-driven crushed stone networks, premium-fabrication specialists with dual BIS-CE certification, and vertically integrated quarry-to-project operators. Competitive intensity centers on logistics density for infrastructure volumes and certification breadth for specification-driven commercial segments.
Among North American aggregates leaders, Vulcan Materials Company and Martin Marietta Materials exemplify scale-driven positioning through rail-linked quarry networks near metropolitan construction zones. CRH represents the multinational integrated archetype with quarry and processing assets spanning multiple continents. These three companies anchor competitive dynamics across infrastructure and commercial building channels without dominating premium interior specification segments where specialized fabricators hold stronger positions.
| Leading Market Players |
|---|
| CRH |
| Martin Marietta Materials |
| Vulcan Materials Company |
| LafargeHolcim |
| HeidelbergCement |
| Cosentino |
| Caesarstone |
| Polycor Inc. |
| Boral Limited |
| Others |
Supply Flow & Price Mechanics
EU carbon border adjustment mechanisms gate qualified supply and premium-tier pricing access for dimension stone exporters, compressing margin capture for high-carbon quarry operations while rewarding renewable-powered extraction with preferred procurement status in German and French commercial building channels.
Pricing Analysis
Warranty and certification bundling separates BIS-CE dual-certified slab suppliers from unbundled commodity block traders in Rajasthan and Gujarat. Three-tier pricing structure across premium certified, standard grade, and economy raw block levels reflects quality control infrastructure investment and quarry-of-origin traceability. Cost compression in economy-grade limestone is intensifying because diesel-powered transport fleets face margin pressure from fuel volatility. Infrastructure contractors demonstrate highest price sensitivity, while luxury hospitality developers absorb premiums for documented low-carbon dimension stone.
Supply Chain Analysis
Regional distribution centers in Vadodara and Jebel Ali form hub-and-spoke patterns for Indian dimension stone reaching Middle Eastern and European markets. Supply concentrates in India's western quarry clusters, with secondary processing anchored in Shandong Peninsula limestone networks. Diamond wire cutting equipment, gang saw blades, and water recycling systems constitute critical input dependencies. Single-source vulnerability runs through Rajasthan's certified stonemason labor pool. Distribution runs through direct quarry-to-project channels for premium commercial towers, bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's BIS certification tightening is forcing consolidation among unqualified Rajasthan processors, eliminating smaller operators unable to finance quality control infrastructure and trained inspector recruitment.
For Market Incumbents: Deploy automation-certified quarry status as a procurement qualification lever. CRH and Martin Marietta Materials should extend rail-linked network density near Sun Belt metropolitan zones to capture infrastructure volume contracts. Backward integration into diamond wire cutting technology reduces yield loss vulnerability and secures block quality consistency for export-grade certification.
For New Entrants and Emerging Players: CNC-integrated 3D templating systems offer a technology-first wedge into custom fabrication for luxury hospitality interiors. White-space targets include carbon-accounted supply chains for EU CBAM compliance and digital stone templating services for Mumbai and Delhi commercial tower projects. Go-to-market positioning should emphasize quarry-of-origin documentation and compressed design-to-installation cycles.
For Investors and Strategic Acquirers: BIS inspector recruitment bottlenecks in Rajasthan and Gujarat are the leading indicator that certified processing capacity will command scarcity premiums. Long-term viability favors vertically integrated quarry-to-project operators with dual certification and renewable energy integration. Acquisition targets include automation-equipped Rajasthan quarries and Jebel Ali-based fabrication clusters serving UAE government-backed developments.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | BIS quality control systems unlock Indian commercial export channels and EU CE marking eligibility. |
| Automation Technology Deployment | Sensor-guided wire saw systems reduce silica exposure and improve yield rates for large-block extraction. |
| Renewable Energy Integration | Solar-powered quarry operations qualify for EU carbon border adjustment preferential access. |
| Direct Quarry Engagement Model | Bypassing distribution layers captures margin from design firms mandating origin documentation. |
| Water Recycling System Retrofit | Gang saw operations in Gujarat meet tightening environmental discharge standards. |
Methodological Framework
Document review covered BIS dimension stone protocols, ECHA REACH authorization requirements, and OSHA silica exposure regulations, complemented by interviews with Rajasthan quarry operators, Gujarat gang saw processors, Mumbai commercial tower procurement managers, and German facade fabricators. Secondary validation drew from customs trade data, Indian Bureau of Mines production statistics, SEC 10-K filings of North American aggregates leaders, and EU CBAM implementation guidance. Bottom-up volume estimates from quarry cluster outputs were triangulated against top-down infrastructure spending projections.
Segment-level projections across material type, application, sizing, and form dimensions were generated through the analysis window using demand elasticity modeling calibrated to residential construction permit flows and public works procurement cycles. CAGRs were derived from regression analysis linking historical extraction volumes to macro construction indicators. Industry-specific inputs included diesel price volatility coefficients for transport cost modeling and certified stonemason labor availability constraints for processing capacity ceilings.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt BIS protocol amendments or EU carbon border adjustment rate revisions. Outputs reflect documented assumptions regarding infrastructure stimulus continuity and REACH substance restriction timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Europe Dry-Mix Mortar Market
Building Materials
Qatar Facade Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Africa Aluminum Door and Window Market
Building Materials
Construction Coatings Market
Building Materials
Indonesia Concrete Admixtures Market
Building Materials
Facade Gasket Market
Building Materials
Steel Slag Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Foam Bricks Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
Global Pozzolan Market
Building Materials
North America Engineered Stone Market
Building Materials
Iron and Steel Slag Market
Building Materials
HDG Steel Pipe Market
Building Materials
Dry Mix Mortar Market