
 Reciprocating Compressor Market | 2026-2036
Reciprocating Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Reciprocating Compressor Market Intelligence
Aftermarket service revenue is fragmenting across regional service networks and OEM-controlled parts channels. Atlas Copco AB leverages its global compressor service footprint to capture recurring maintenance contracts in process industries. Burckhardt Compression AG anchors high-margin overhauls for hyper-compressor installations in polyethylene plants. Siemens Energy competes through digital monitoring packages that extend mean time between overhauls for gas transmission operators.
A reciprocating compressor converts rotational energy into pressurized gas through piston displacement within a cylinder, achieving discharge pressures from 100 psi to over 10,000 psi depending on staging and frame design. Its primary commercial purpose centers on process gas handling, refrigeration cycles, and pipeline transmission where precise pressure ratios and oil-free delivery matter. Oil-free reciprocating models command premium positioning in food processing and pharmaceutical applications where contamination risks override first-cost considerations. Double-acting configurations dominate petrochemical processing due to higher throughput per frame size and superior energy efficiency at continuous duty cycles.
EPA New Source Performance Standards shape compressor seal and rod packing requirements for methane control in US oil and gas operations. EU F-Gas Regulation drives refrigerant compressor redesigns toward lower global warming potential working fluids across European HVAC and cold chain installations. China's GB energy efficiency standards and MEE air quality mandates accelerate replacement of legacy fixed-speed units in industrial zones. Stakeholders must weigh stranded asset risk in regions tightening emissions enforcement against the capital intensity of next-generation oil-free and variable-speed platforms.
Market Dynamics
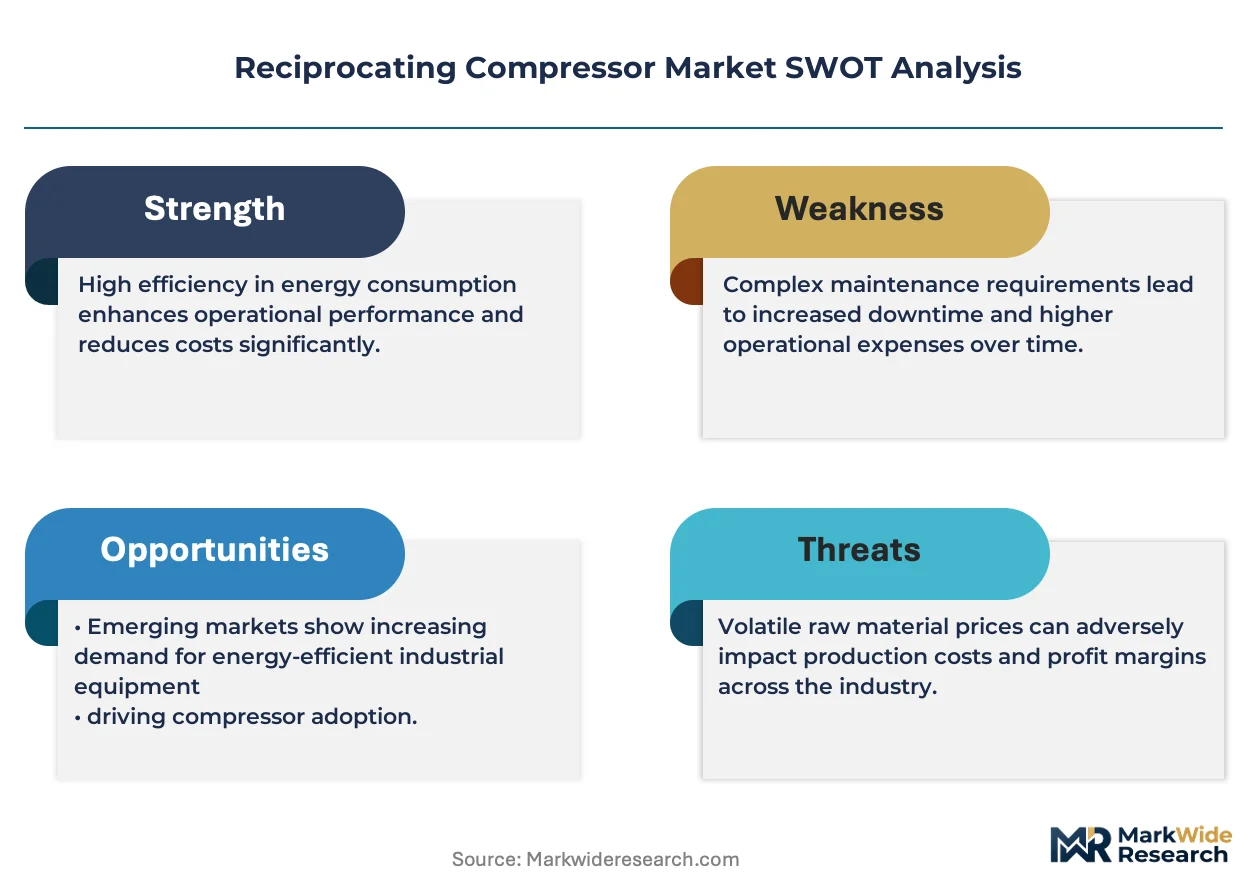
EPA methane emissions rules are compressing the installed base of legacy rod-packing designs while accelerating capital redeployment toward sealed crankcase and vent-capture systems across US gas transmission networks.
Growth Catalysts
- Shale gas throughput expansion:Petrochemical processing facilities in the United States are expanding compressor fleets to handle rising feedstock volumes from Permian and Appalachian basins.
- EU F-Gas Regulation:Refrigerant compressor redesigns toward lower global warming potential working fluids are driving replacement demand across European HVAC and cold chain installations.
- Double-acting configurations:Higher throughput per frame size and superior energy efficiency at continuous duty cycles are displacing single-acting units in polyethylene and ammonia plants.
Market Restraints
- Specialized alloy input costs:Crankshaft forgings and cylinder castings from concentrated European and Japanese foundries expose OEMs to nickel and chromium price volatility.
- Hyper-compressor technical limitation:Ultra-high pressure polyethylene applications above 3,500 bar require proprietary diaphragm designs with limited qualified supplier bases.
- China MEE air quality mandates:Accelerated replacement timelines for legacy fixed-speed units in industrial zones are straining regional service network capacity.
Strategic Opportunities
- India industrial corridor buildout:Petroleum refining and fertilizer complexes along the Chennai-Vizag belt are greenfield sites for heavy-duty double-acting installations.
- Variable-speed drive convergence:Integration of permanent magnet motors with advanced pulsation control is opening efficiency gains in gas storage injection service.
- US Inflation Reduction Act incentives:Methane monitoring and leak detection equipment tax credits are lowering effective costs for emissions-compliant compressor packages.
Industry Challenges
- Specialized field technician scarcity:Hyper-compressor overhaul capability requires decades of apprenticeship that OEMs struggle to replicate outside Swiss and German training centers.
- API 618 and ISO 13631 certification timelines:Third-party witness testing for pulsation and torsional analysis extends project delivery schedules by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reciprocating Compressor Market |
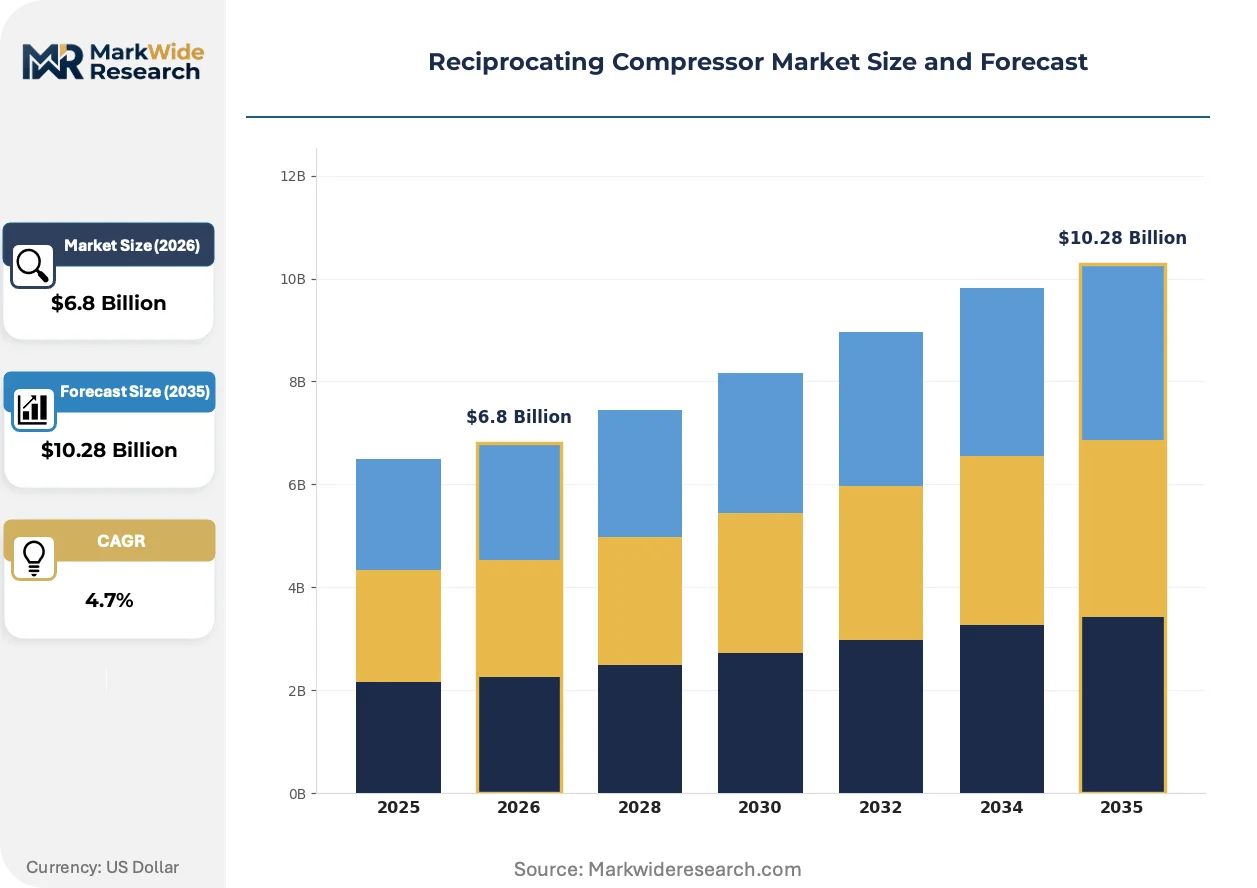
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Acting, Double-Acting, Oil-Lubricated, Oil-Free, Variable Speed Technology: Dry-running, Liquid Piston, Gas High-pressure, Balanced Piston, Plunger Application: Petrochemical Processing, Refrigeration, HVAC Systems, Gas Transmission, Food Processing End User: Oil & Gas Producers, Chemical Plants, Power Generation Facilities, Manufacturing Units |
| Companies Covered | Burckhardt Compression AG, Baker Hughes Company, Atlas Copco AB, ELGi, KAESER KOMPRESSOREN, Ingersoll Rand, Siemens Energy, Howden Group, Ariel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reciprocating Compressor Market Strategic Shifts & Innovations
Digital instrumentation and condition-based monitoring are redefining maintenance economics in high-horsepower process service, shifting value capture from hardware margins to recurring diagnostics revenue.
Variable-speed drive integration with advanced pulsation control algorithms is digitizing compressor performance optimization across gas storage and pipeline booster applications. Midstream operators are retrofitting legacy frames with permanent magnet motor packages to capture part-load efficiency gains. This convergence is digitizing the traditional fixed-speed aftermarket, compressing overhaul intervals while extending mean time between failures through real-time rod load and valve temperature telemetry.
EPA New Source Performance Standards are tightening seal and rod packing requirements for methane control in oil and gas operations. Compressor packagers must now engineer vent-capture systems and distance-piece monitoring into standard offerings. US gas transmission operators are responding by bundling emissions-compliant packages with ten-year service contracts that shift compliance liability to OEMs.
Aftermarket service unbundling is fragmenting procurement patterns across process industries. Petrochemical operators are separating parts sourcing from labor contracts, pitting OEM-controlled channels against independent service networks. This disintermediation is most pronounced in Germany and the Netherlands, where specialized hyper-compressor rebuild shops are capturing high-margin overhauls from incumbent suppliers through faster turnaround guarantees.
Reciprocating Compressor Market Segmentation
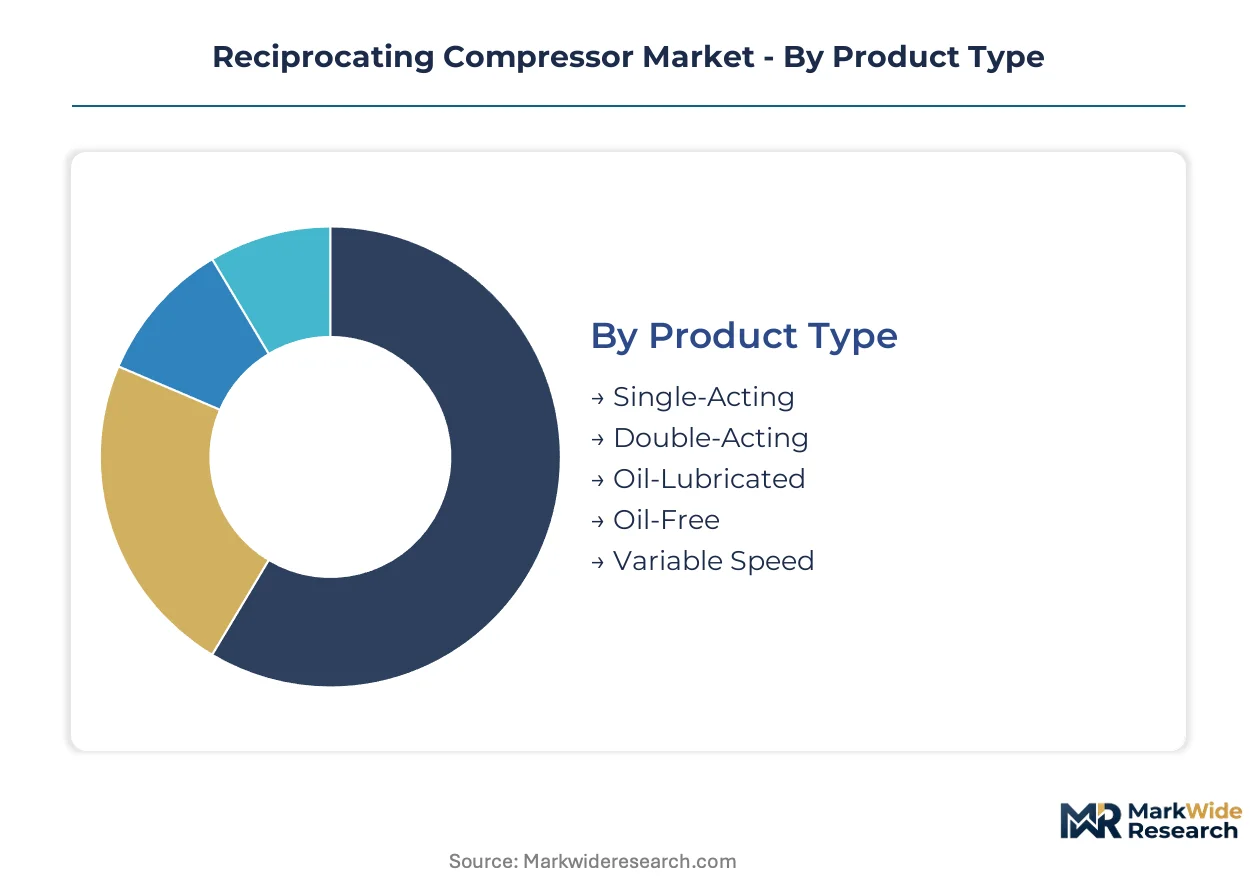
Reciprocating compressor procurement patterns diverge sharply across pressure duty, contamination tolerance, and duty cycle requirements. Each segmentation dimension captures distinct technical specifications that determine OEM pricing power and aftermarket service attach rates.
Product Type:
Cost tier structures the competitive landscape from entry-level single-acting units to premium oil-free and variable-speed platforms commanding three-to-five-x hardware premiums.
- Single-Acting:Piston displacement occurs on one side of the cylinder only, limiting throughput to intermittent duty cycles below 150 psi discharge. Demand concentrates in small-scale refrigeration service across India and Southeast Asian food processing clusters where capital constraints override efficiency considerations.
- Double-Acting:Both sides of the piston handle gas compression, delivering continuous duty at pressures exceeding 3,000 psi with 15-20% efficiency gains over single-acting equivalents. Petrochemical processors in the US Permian Basin and China's Ningbo-Zhoushan petrochemical zone anchor procurement for ethylene and ammonia synthesis trains.
- Oil-Lubricated:Crankcase oil films reduce cylinder wear and enable cast iron construction for cost-sensitive industrial applications.
- Oil-Free:PTFE piston rings and distance-piece seals eliminate hydrocarbon contamination for pharmaceutical aseptic processing and food-grade nitrogen generation.
- Variable Speed:Permanent magnet motor integration with VFD control matches output to fluctuating demand profiles in gas storage injection and pipeline booster service.
Double-acting configurations command the established base. The steepest expansion runs through variable-speed platforms.
Technology:
Application severity dictates technology selection, with dry-running and liquid piston designs dominating moderate-pressure process service while hyper-compressor applications require proprietary balanced piston and plunger architectures.
- Dry-running:Self-lubricating piston materials eliminate oil injection for clean gas service in hydrogen fueling stations and medical oxygen generation. German automotive suppliers and Japanese electronics manufacturers anchor specification authority for contamination-intolerant applications.
- Liquid Piston:A liquid column replaces mechanical pistons, enabling near-isothermal compression with reduced pulsation for biogas upgrading and landfill gas recovery. Nordic waste-to-energy facilities and Dutch greenhouse horticulture clusters drive adoption for renewable natural gas injection.
- Gas High-pressure:Multi-stage staging with intercooling achieves discharge pressures above 5,000 bar for polyethylene hyper-compressor service.
- Balanced Piston:Opposed cylinder arrangements cancel reciprocating forces, extending bearing life in continuous-duty refinery hydrogen recycle.
- Plunger:Solid metal displacement without piston rings handles ultra-high-pressure carbon dioxide injection for enhanced oil recovery.
Gas high-pressure installations retain the largest installed value. Dry-running technology is climbing the fastest on hydrogen economy buildout.
Application:
End-use margins determine specification intensity, with petrochemical and gas transmission operators accepting extended payback periods for efficiency gains while HVAC and food processing prioritize first-cost minimization.
- Petrochemical Processing:Ethylene, propylene, and ammonia synthesis require 24/7 operation at 2,000-3,500 bar with 99.5% mechanical availability. US Gulf Coast crackers and Middle Eastern integrated complexes specify API 618 compliance with ten-year design life guarantees.
- Refrigeration:Ammonia and CO2 compressor packages serve industrial cold storage and district cooling networks. EU F-Gas Regulation compliance is redirecting specification toward lower-GWP working fluids in German retail logistics and Dutch floral export hubs.
- HVAC Systems:Comfort cooling and heating applications favor scroll and screw alternatives for noise and footprint advantages.
- Gas Transmission:Pipeline booster and storage withdrawal service demands 5,000+ hour annual operation with remote monitoring integration.
- Food Processing:Oil-free delivery for packaging, carbonation, and pneumatic conveying faces stringent FDA and EU hygiene mandates.
Petrochemical processing commands specification authority and service contract values. Refrigeration applications are gaining share fastest on cold chain infrastructure buildout.
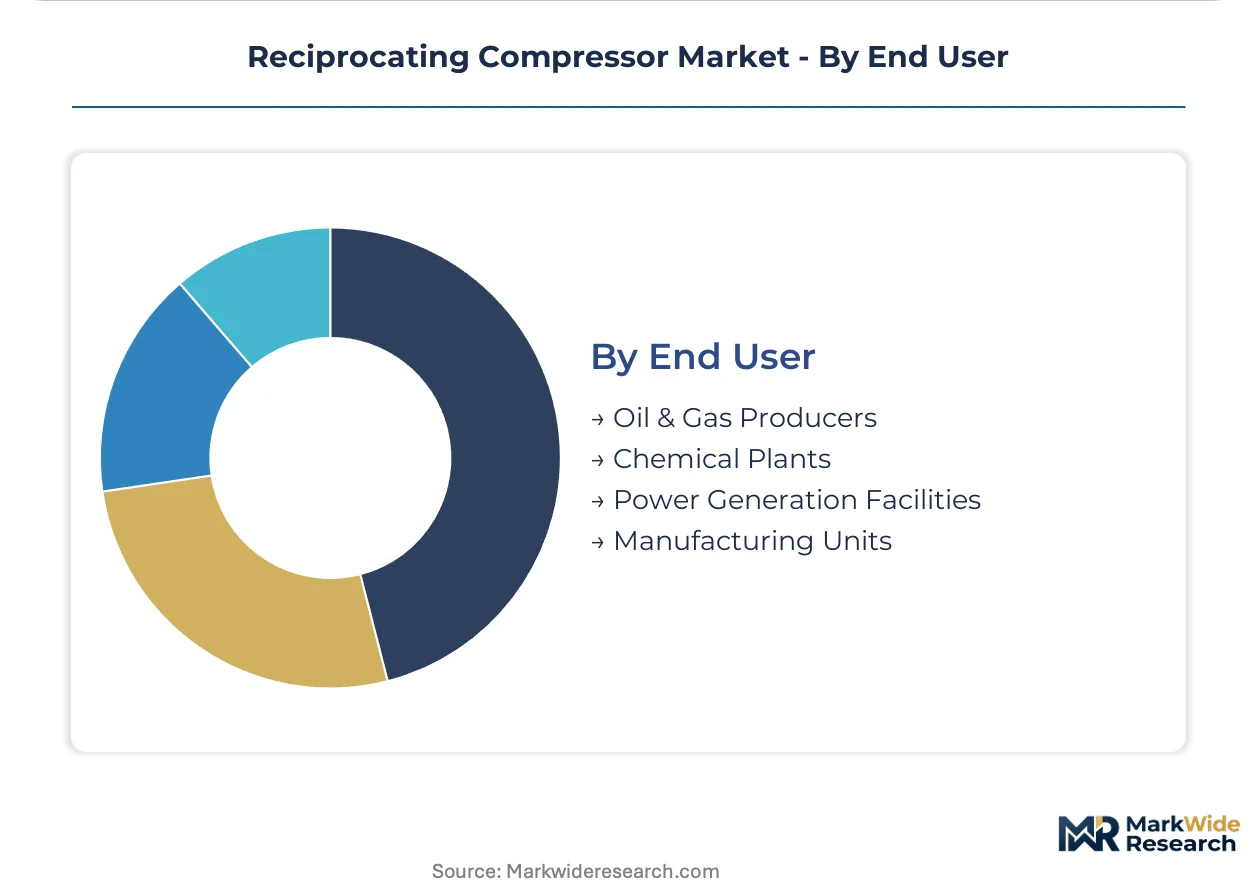
End User:
Customer procurement sophistication fragments between integrated majors with captive engineering teams and mid-tier operators dependent on OEM turnkey delivery.
- Oil & Gas Producers:Upstream operators deploy wellhead gas gathering and vapor recovery units across shale plays. EPA methane regulations are compressing replacement cycles for rod-packing designs in the Permian and Bakken basins.
- Chemical Plants:Fertilizer, methanol, and specialty chemical producers specify for process integration and catalyst protection. India's Dahej and Mundra chemical zones are greenfield demand centers for heavy-duty double-acting installations.
- Power Generation Facilities:Natural gas peaker plants and combined-cycle stations require instrument air and fuel gas compression.
- Manufacturing Units:General industrial compressed air service favors rotary screw alternatives for maintenance simplicity.
Oil and gas producers anchor aftermarket service revenue through emissions-driven retrofit obligations. Chemical plants represent the steepest expansion trajectory on capacity buildout in India and the Middle East.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Indian and Southeast Asian buyers prioritize capital efficiency in small-scale refrigeration, while US petrochemical operators accept extended payback periods for emissions-compliant double-acting systems. German and Swiss purchasers anchor premium positioning for oil-free and hyper-compressor specifications.
United States
Permian Basin shale gas throughput expansion and Appalachian feedstock growth drive fleet expansion at ethylene crackers. EPA methane emissions rules compress replacement cycles for legacy rod-packing designs. Gulf Coast petrochemical clusters around Houston and Port Arthur specify API 618-compliant packages with ten-year service contracts.
China
Ningbo-Zhoushan petrochemical zone capacity buildout and coal-to-chemicals integration anchor heavy-duty double-acting demand. MEE air quality mandates and GB energy efficiency standards accelerate retirement of fixed-speed legacy units. Sichuan-Chongqing shale gas development creates gathering compression opportunities.
Germany
Ruhr Valley chemical complexes and Bavarian automotive hydrogen fueling infrastructure specify contamination-intolerant dry-running technology. EU F-Gas Regulation compliance redirects refrigeration compressor procurement toward lower-GWP working fluids. Specialized hyper-compressor rebuild shops in the Netherlands and western Germany capture high-margin overhauls.
India
Dahej and Mundra chemical zones anchor greenfield demand for heavy-duty double-acting installations in fertilizer and methanol synthesis. Petroleum refining expansion along the Chennai-Vizag belt strains regional service network capacity. Small-scale food processing clusters in Maharashtra and Gujarat prioritize single-acting capital efficiency over operating cost optimization.
Saudi Arabia
Jubail and Yanbu integrated petrochemical complexes specify continuous-duty hyper-compressor trains for polyethylene export capacity. Domestic gas processing expansion for power generation and industrial feedstock drives pipeline booster procurement. Joint venture technology licensing agreements with European OEMs localize assembly while preserving proprietary diaphragm sourcing.
Reciprocating Compressor Market Key Industry Players
Capability concentration sits with specialized hyper-compressor and oil-free technology developers; scale advantage sits with diversified industrial conglomerates offering full compressor portfolios. The market structures around three tiers: premium specialists commanding proprietary diaphragm and balanced piston architectures; mid-tier integrators bundling emissions-compliant packages with long-term service contracts; and regional fabricators competing on delivery speed and customization flexibility. Dominant competitive moves include strategic partnerships for local assembly in high-growth markets and vertical integration into permanent magnet motor supply chains for variable-speed platforms.
Among Swiss and German precision engineering specialists, Burckhardt Compression AG exemplifies the hyper-compressor capability tier with decades of apprenticeship-dependent overhaul expertise. Atlas Copco AB and Siemens Energy occupy positions spanning the mid-to-premium spectrum, leveraging global service footprints and digital monitoring integration respectively. Baker Hughes Company represents the integrated energy technology conglomerate archetype with cross-segment compression portfolio breadth.
| Leading Market Players |
|---|
| Burckhardt Compression AG |
| Baker Hughes Company |
| Atlas Copco AB |
| ELGi |
| KAESER KOMPRESSOREN |
| Ingersoll Rand |
| Siemens Energy |
| Howden Group |
| Ariel Corporation |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp heavy-lift corridor freight costs amplify price spreads between European hyper-compressor specialists and Asian fabricators, compressing margins for mid-tier integrators while reinforcing premium positioning for diaphragm-technology holders. Supply concentration in Swiss and German foundries for nickel-chromium alloy castings directly shapes tiered pricing power across API 618-certified and uncertified equipment categories.
Pricing Analysis
Long-term offtake contracts dominate procurement for petrochemical and gas transmission operators, bundling ten-year service obligations with hardware delivery to shift compliance liability onto OEMs. Price differentiation rests on API 618 certification tier and permanent magnet motor integration, with emissions-compliant packages commanding substantial premiums over legacy rod-packing designs. Cost compression in single-acting units is intensifying as Indian and Southeast Asian food processors prioritize capital efficiency. Small-scale refrigeration buyers exhibit highest price sensitivity; polyethylene plant operators accept extended payback periods for sealed crankcase configurations.
Supply Chain Analysis
Export-control regimes restricting high-pressure diaphragm technology flows limit qualified supplier bases for ultra-high-pressure polyethylene applications above 3,500 bar. Geographic supply concentration centers on Germany, Switzerland, and Japan for specialized crankshaft forgings and cylinder castings. Raw material dependencies draw from nickel and chromium alloys, PTFE piston ring compounds, and permanent magnet motor rare earth elements. Single-source vulnerability in European and Japanese foundries exposes OEMs to alloy price volatility. Distribution runs through OEM-controlled service networks and independent rebuild shops competing on turnaround speed.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as EPA methane rules and EU F-Gas Regulation splinter procurement patterns, creating specialized niches for emissions-compliant packagers and refrigerant redesign specialists.
For Market Incumbents: Pre-empt independent service network encroachment by capturing hyper-compressor overhaul capability through apprenticeship program expansion in Swiss and German training centers. Accelerate backward integration into permanent magnet motor supply chains to defend margin position against variable-speed platform commoditization. Anchor long-term service contracts with US Gulf Coast petrochemical operators to lock in emissions-driven retrofit cycles. For New Entrants and Emerging Players: Establish a beachhead in India's Dahej and Mundra chemical zones where greenfield fertilizer and methanol capacity strains regional OEM service capacity. Target dry-running compressor applications for hydrogen fueling infrastructure in German automotive supplier networks. Pursue joint venture assembly partnerships with Saudi joint venture licensors to bypass proprietary diaphragm sourcing barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core compression portfolios amid energy transition portfolio rebalancing. Long-term viability favors specialists with captive diaphragm technology and established apprenticeship pipelines over pure-play fabricators. Monitor EPA enforcement intensity in Permian Basin gathering operations as inflection indicator for emissions-compliant equipment replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Integration | Captures part-load efficiency gains for gas storage injection operators retrofitting legacy frames. |
| Emissions-Compliant Package Bundling | Shifts EPA methane compliance liability from US transmission operators to OEM service contracts. |
| Hyper-Compressor Overhaul Capability | Secures high-margin recurring revenue through decades-long apprenticeship-dependent technical moats. |
| Joint Venture Local Assembly | Enables Saudi petrochemical complexes to meet domestic content requirements while preserving proprietary technology control. |
| Digital Monitoring Platform Deployment | Extends mean time between overhauls for gas transmission operators through real-time telemetry analytics. |
Research Approach
Findings reconcile primary fieldwork against secondary review of trade association filings, customs data, and regulatory disclosure databases to anchor market size estimates. Primary interviews engaged maintenance directors at petrochemical complexes, aftermarket service heads at OEM networks, plant engineers specifying compression trains, and procurement leads at gas transmission operators. Secondary validation drew from EPA enforcement databases, EU F-Gas Regulation implementation reports, API certification registries, and SEC filings of listed compressor manufacturers. Bottom-up unit deployment tracking triangulates against top-down industry value chain analysis.
Forecast inputs incorporate product type segmentation across single-acting, double-acting, oil-free, and variable-speed platforms; technology categories spanning dry-running, liquid piston, and hyper-compressor architectures; and application splits between petrochemical processing, refrigeration, gas transmission, and food processing. CAGRs derive from fitted growth curves calibrated to disclosed capacity expansion timelines, regulatory compliance deadlines, and replacement cycle acceleration factors. Industry-specific inputs include shale gas throughput trajectories in US basins, MEE air quality mandate enforcement intensity in Chinese industrial zones, and EU cold chain infrastructure buildout projections.
Sensitivities concentrate around EPA methane rule enforcement variability, nickel and chromium alloy price volatility, and hyper-compressor diaphragm supplier qualification timelines. Forecasts reflect documented assumptions regarding regulatory implementation schedules, apprentice technician pipeline development, and permanent magnet motor cost curves. Material shifts in US emissions enforcement intensity or European export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Compressed Air Filtration and Dryer System Market
Compressors
Asia-Pacific Compressor Oil Market
Compressors
Portable Air Compressor Market
Compressors
Compressor Wheel Market
Compressors
Automotive Compressors Market
Compressors
Hydrogen Compressor Market
Compressors
PAG Compressor Oil Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Root Blower Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Portable Compressor Market
Compressors
Rotary Lobe Compressor Market
Compressors
North America Compressor Market
Compressors
LNG Compressor Market
Compressors
Oil-Free Air Compressor Market
Compressors
Scroll Compressor Market