
 Hydrogen Compressor Market | 2026-2036
Hydrogen Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Compressor Market Analysis
Germany's electrolyzer manufacturing corridor is narrowing the supply gap for high-pressure hydrogen handling equipment. Atlas Copco AB leverages its oil-free compression portfolio to anchor European hydrogen mobility projects. Burckhardt Compression AG sustains leadership in hyperbaric solutions for chemical processing. Ingersoll Rand Inc. competes through integrated service networks spanning North American refinery retrofits.
A hydrogen compressor is a mechanical device that raises hydrogen gas pressure from atmospheric or low-pressure states to levels required for storage, pipeline transport, or industrial injection, typically achieving discharge pressures from 350 bar to 700 bar for mobility applications and up to 1,000 bar for industrial processes. Reciprocating compressors dominate existing refinery installations where mature service infrastructure and proven reliability preserve installed base loyalty. Diaphragm technology captures emerging share in fuel cell vehicle fueling stations where zero-contamination guarantees override capital cost premiums. Mechanical compression anchors current revenue pools while electrochemical approaches attract R&D capital for efficiency gains in distributed hydrogen production.
The US Inflation Reduction Act directs EPA and DOE coordination on clean hydrogen hub certification, conditioning tax credit eligibility on lifecycle emissions verification that favors efficient compression pathways. Europe's F-Gas Regulation and EU Green Deal hydrogen bank criteria tighten equipment efficiency standards and favor low-leakage compressor architectures. REACH compliance adds material traceability requirements for seals and coatings in high-purity hydrogen service. Stakeholders must weigh electrochemical compression maturation timelines against mechanical platform refresh cycles when committing capital to hydrogen infrastructure build-outs.
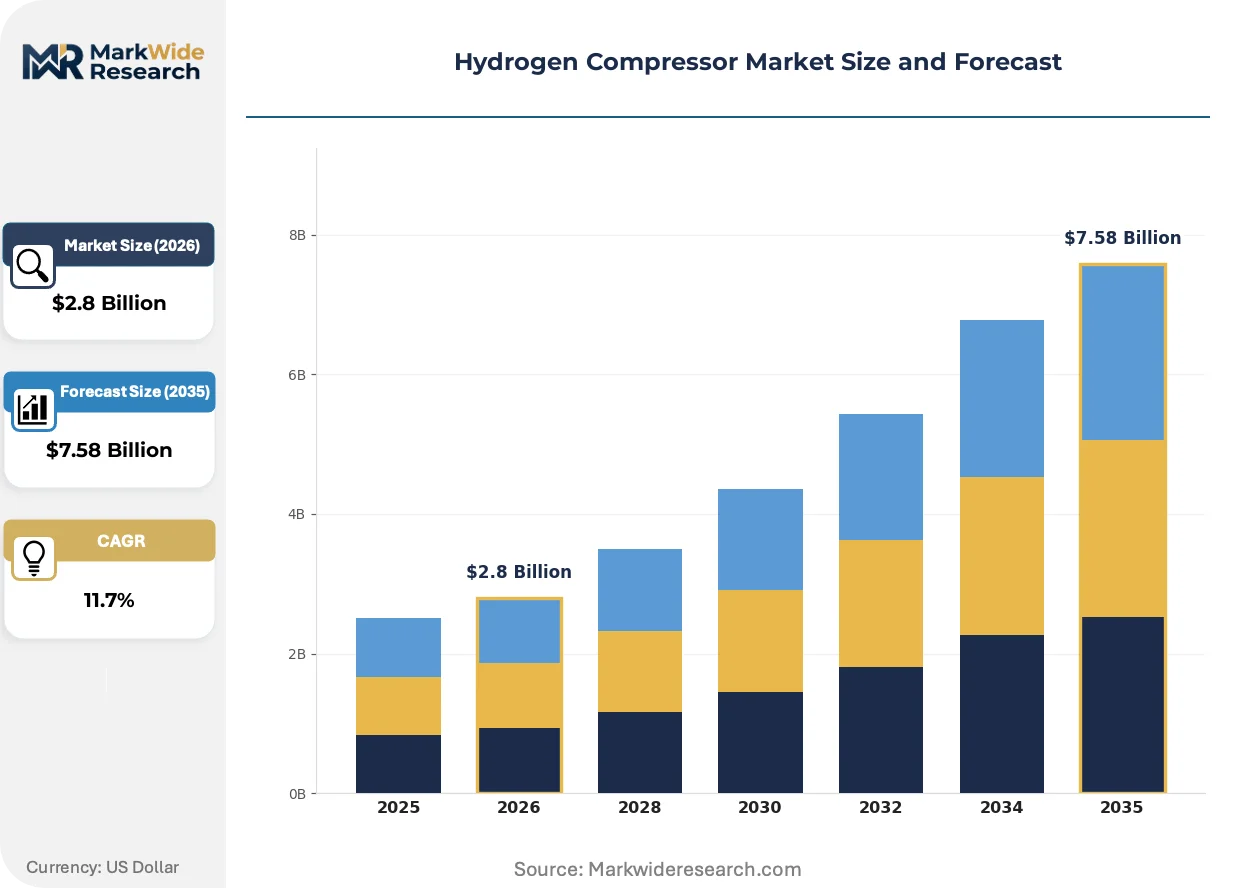
Market Dynamics
The US Inflation Reduction Act's hydrogen production tax credits have reordered project economics, compressing payback periods for refinery retrofits and fueling station build-outs while conditioning eligibility on lifecycle emissions verification that favors efficient compression pathways.
Growth Catalysts
- Electrolyzer corridor expansion:Germany's Rhine-Ruhr industrial clusters are narrowing supply gaps for high-pressure hydrogen handling equipment, driving synchronized procurement of compression systems alongside electrolyzer manufacturing capacity.
- Mobility infrastructure mandates:EU Green Deal hydrogen bank criteria are accelerating fuel cell vehicle fueling station deployment, with zero-contamination guarantees specified in equipment tenders favoring diaphragm compressor architectures.
- Refinery hydrogen demand:FCC regulations in the United States are tightening sulfur specifications, forcing refiners to expand hydrogen production units and associated compression capacity for hydroprocessing operations.
Market Restraints
- Specialized alloy supply concentration:High-purity hydrogen service requires nickel-based superalloys for seals and coatings, with primary smelting capacity concentrated in a limited supplier base subject to price volatility.
- Technical leakage constraints:Hydrogen's small molecular diameter creates persistent sealing challenges at pressures above 700 bar, limiting maximum discharge pressures for certain mechanical compression architectures.
- F-Gas Regulation compliance friction:Europe's tightening equipment efficiency standards impose retrofit obligations on existing refinery installations, extending procurement cycles and compressing near-term order flow.
Strategic Opportunities
- Underpenetrated chemical processing:India's emerging green hydrogen hubs present white space for hyperbaric compression solutions as the country's PLI scheme for electrolyzer manufacturing matures.
- Electrochemical-mechanical convergence:Integration of electrochemical compression with mechanical staging offers pathway to efficiency gains in distributed hydrogen production serving off-grid industrial sites.
- Service network unbundling:Aftermarket compression maintenance contracts are fragmenting from OEM-captive models toward independent service providers, creating channel entry points for specialized contractors.
Industry Challenges
- High-pressure welding certification gaps:Fabrication of 1,000-bar pressure vessels requires ASME Section VIII Division 3 qualified welders, with training pipeline lagging deployment timelines for industrial hydrogen projects.
- Legacy system integration complexity:Refinery retrofits must interface compression skids with existing distributed control systems, extending commissioning schedules and requiring specialized automation engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Compressor Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Diaphragm, Rotary, Screw End User: Refineries, Fuel Cell Vehicles, Industrial Gas, Power Generation Technology: Electrochemical, Mechanical Compression, Thermochemical, Cryogenic Application: Transportation, Energy Storage, Chemical Processing, Electronics |
| Companies Covered | Atlas Copco AB, Burckhardt Compression AG, Ingersoll Rand Inc., Ariel Corporation, Neuman & Esser Group, HAUG Sauer Kompressoren AG, Howden Group Ltd, Hitachi Ltd., Fluitron Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Compressor Market Emerging Trajectories
Compression technology is bifurcating between incremental mechanical efficiency gains and disruptive electrochemical architectures, with digitization of condition monitoring emerging as the cross-cutting investment priority across both pathways.
Intelligent compressor monitoring is digitizing maintenance scheduling and failure prediction. Refinery operators are deploying vibration and temperature sensors on reciprocating compressor frames to shift from calendar-based overhauls to condition-based interventions. This is digitizing spare parts inventory management and compressing unplanned downtime intervals across North American processing facilities.
Europe's F-Gas Regulation is tightening leakage rate thresholds for high-pressure hydrogen equipment. The industrial consequence is accelerated R&D investment in metal-to-metal sealing technologies and hermetic compressor architectures. Fuel cell vehicle fueling station developers in Germany and the Netherlands are responding by specifying diaphragm compressors with certified leakage rates below 0.5% annually.
Buyer procurement patterns are consolidating toward integrated compression-hydrogen production tenders. Electrolyzer OEMs are bundling compression skids into turn-key supply contracts, displacing standalone compressor procurement by project developers. This bundling is most visible in German industrial cluster developments where single-source accountability reduces interface risk for green hydrogen offtake agreements.
Hydrogen Compressor Market Segmentation
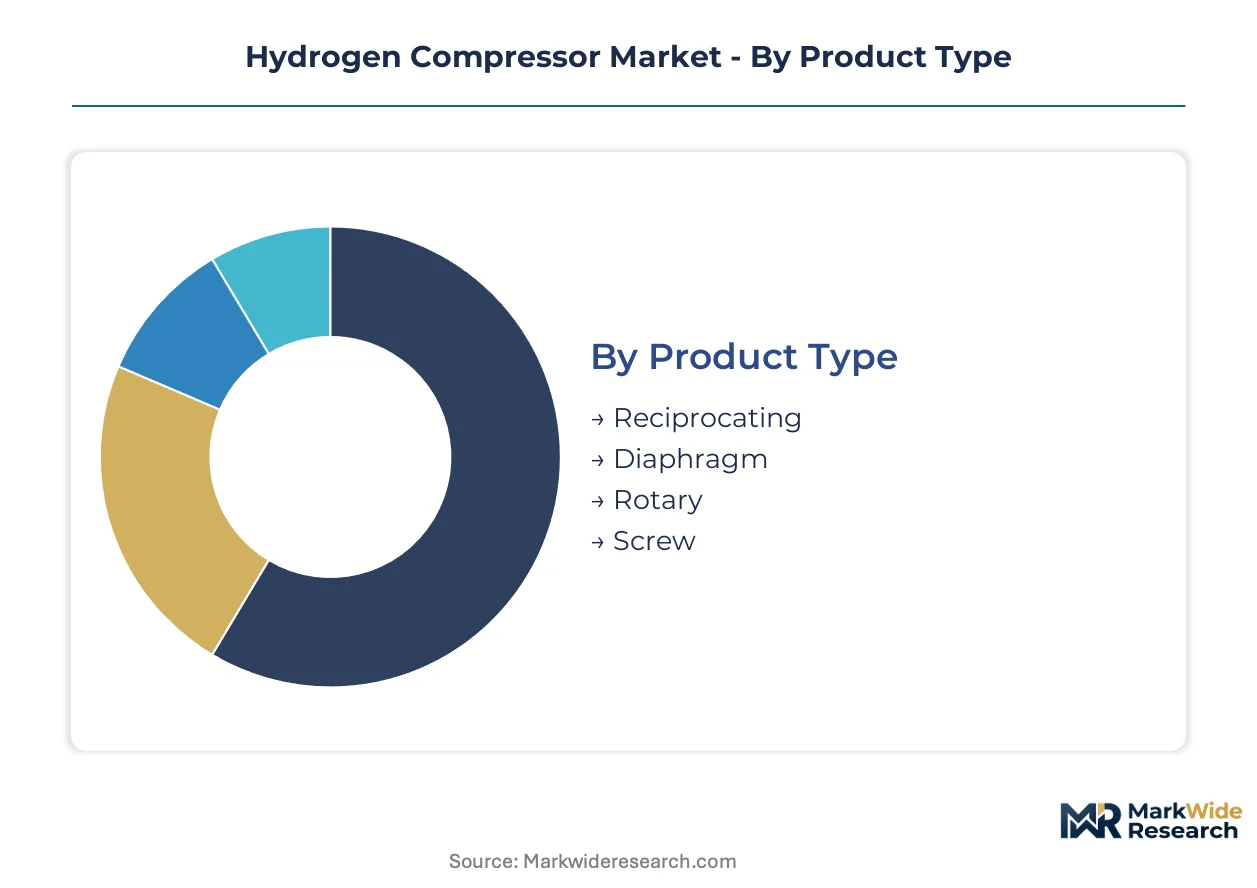
Hydrogen compressor segmentation reveals divergent technology maturities and application-specific performance requirements. Procurement patterns cluster around proven mechanical architectures in established industries while electrochemical and diaphragm systems capture emerging mobility and purity-critical applications.
Product Type:
Mature mechanical platforms anchor refinery procurement while emerging architectures address contamination-sensitive fueling applications.
- Reciprocating:Piston-driven compression achieves discharge pressures exceeding 1,000 bar through multi-stage configurations with proven reliability in hydroprocessing operations. Refinery operators in the United States prioritize these units for FCC-driven hydrogen expansion where service infrastructure and spare parts availability dominate procurement criteria.
- Diaphragm:Metal or elastomer membranes isolate process gas from lubricants, delivering contamination-free discharge essential for proton exchange membrane fuel cells. German fueling station developers specify these units under EU Green Deal hydrogen bank criteria despite 40-60% capital cost premiums over reciprocating alternatives.
- Rotary:Vane and lobe configurations handle lower pressure ratios with continuous flow characteristics suited to chemical process feed compression.
- Screw:Twin-rotor designs offer oil-free compression with moderate pressure capabilities for industrial gas distribution networks.
Reciprocating compressors handle the majority of throughput; diaphragm systems are expanding most quickly on share.
End User:
Customer segments span from sulfur-regulation-driven refinery retrofits to emerging fuel cell mobility infrastructure with divergent purity and pressure specifications.
- Refineries:Hydroprocessing units for diesel and jet fuel desulfurization consume hydrogen at scales exceeding 100,000 Nm³/h, requiring multi-stage reciprocating or centrifugal compression trains. EPA FCC regulations in the United States mandate sulfur reductions that expand hydrogen production capacity and associated compression procurement cycles.
- Fuel Cell Vehicles:Light-duty and heavy-duty mobility applications demand 350-700 bar dispensing with zero oil contamination, driving diaphragm and ionic liquid compressor adoption. California's H2Hubs program and Germany's Rhine-Ruhr clusters coordinate electrolyzer-to-dispenser procurement that bundles compression into turn-key fueling station contracts.
- Industrial Gas:Merchant hydrogen suppliers require compression for tube trailer filling and pipeline injection across steel, glass, and semiconductor manufacturing.
- Power Generation:Gas turbine blending and stationary fuel cell installations utilize medium-pressure compression for grid-scale energy storage applications.
Refineries command the largest installed base; fuel cell vehicle infrastructure is climbing the fastest on capital deployment.
Technology:
Mechanical dominance persists in revenue terms while electrochemical R&D attracts efficiency-focused investment for distributed production scenarios.
- Mechanical Compression:Reciprocating, rotary, and screw architectures leverage mature supply chains and qualified welding certifications for pressure vessels up to 1,000 bar. ASME Section VIII Division 3 compliance requirements create fabricator bottlenecks that extend lead times for industrial hydrogen projects in North America.
- Electrochemical:Proton-conducting membranes and solid-state pumps eliminate moving parts, targeting 70-80% energy efficiency gains over mechanical alternatives in electrolyzer-integrated applications. DOE funding under the Inflation Reduction Act accelerates pilot deployments for off-grid industrial sites where maintenance access constraints favor solid-state architectures.
- Thermochemical:Metal hydride and chemical looping systems utilize thermal energy rather than mechanical work for pressure elevation, suited to waste-heat-rich industrial environments.
- Cryogenic:Liquid hydrogen pumping achieves density advantages for long-distance maritime transport, requiring specialized insulation and boil-off management systems.
Mechanical compression retains the dominant revenue share; electrochemical approaches are gaining share fastest on R&D intensity.
Application:
Application requirements diverge between high-pressure mobility dispensing, large-scale energy storage cycling, and precision chemical process integration.
- Transportation:Heavy-duty trucking and maritime applications drive 700-bar dispensing specifications with rapid fill rates below 10 minutes. Netherlands and Germany deploy coordinated hydrogen corridor infrastructure with standardized compressor skids for cross-border fueling compatibility.
- Chemical Processing:Ammonia synthesis and methanol production require 200-300 bar injection with continuous duty cycles exceeding 8,000 hours annually. India's emerging green hydrogen hubs under the PLI scheme for electrolyzer manufacturing create demand for hyperbaric compression integration with Haber-Bosch retrofits.
- Energy Storage:Salt cavern and depleted reservoir injection utilizes 100-200 bar compression for seasonal hydrogen banking in power-to-gas configurations.
- Electronics:Semiconductor annealing and flat-panel display manufacturing demand ultra-high purity hydrogen at moderate pressures with sub-ppb contamination limits.
Transportation applications absorb the largest capital allocation; chemical processing is expanding most quickly on green hydrogen project announcements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compressor fabrication capacity clusters in Germany, the United States, Japan, and China, with specialized alloy supply chains and qualified welding certification pipelines creating geographic stickiness in equipment sourcing.
United States
Refinery retrofits along the Gulf Coast and California hydrogen hub deployments drive multi-stage reciprocating compressor procurement. The Inflation Reduction Act conditions clean hydrogen production tax credits on lifecycle emissions verification that favors efficient compression pathways. Houston-area fabricators face ASME Section VIII Division 3 welder shortages that extend lead times for 1,000-bar industrial projects.
Germany
Rhine-Ruhr industrial clusters synchronize electrolyzer manufacturing with high-pressure hydrogen handling equipment procurement. EU Green Deal hydrogen bank criteria and F-Gas Regulation leakage thresholds accelerate diaphragm compressor adoption for fuel cell vehicle fueling stations. Bavarian and North Rhine-Westphalian project developers bundle compression skids into turn-key supply contracts to reduce interface risk.
China
Dual carbon goals and provincial hydrogen energy development plans expand electrolyzer-to-compressor procurement pipelines in Inner Mongolia and Jiangsu. The Ministry of Ecology and Environment tightens industrial emissions standards that favor hydrogen substitution in steel and chemical processes. Yangtze River Delta fabricators scale metal-to-metal sealing production for 700-bar mobility applications.
Japan
METI hydrogen roadmap targets and fuel cell vehicle deployment mandates sustain demand for 700-bar dispensing infrastructure. Kansai and Chubu industrial zones integrate compressor procurement with ammonia co-firing pilot projects for power generation. Domestic fabricators prioritize hermetic architectures for semiconductor-grade hydrogen supply chains.
India
PLI scheme incentives for electrolyzer manufacturing mature into green hydrogen hub development in Gujarat and Tamil Nadu. Central Electricity Authority grid integration standards and BIS pressure equipment codes shape compressor specification for ammonia synthesis retrofits. Reliance Industries and Adani-led clusters in Mundra and Hazira anchor early procurement cycles for hyperbaric solutions.
Hydrogen Compressor Market Vendor Landscape
Integrated industrial conglomerates and specialized compression engineering houses split the market between scale-driven refinery retrofits and purity-critical mobility applications. The vendor base tiers around three strategic archetypes: diversified industrial groups with oil-free portfolios, hyperbaric specialists with chemical processing heritage, and electrochemical technology pioneers targeting distributed production. Consolidation pressure concentrates in aftermarket service networks, while technology licensing agreements accelerate diaphragm and ionic liquid architecture diffusion.
Among European-based engineering groups, Atlas Copco AB and Burckhardt Compression AG exemplify divergent strategic positions within the mechanical compression domain. Atlas Copco's Stockholm-anchored industrial conglomerate structure supports cross-technology bundling into hydrogen mobility project tenders. Burckhardt Compression AG, organized as a Swiss Aktiengesellschaft, occupies a specialist position in hyperbaric process applications. Ingersoll Rand Inc., structured as a US corporation, represents the integrated service network model spanning North American refinery maintenance contracts.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Burckhardt Compression AG |
| Ingersoll Rand Inc. |
| Ariel Corporation |
| Neuman & Esser Group |
| HAUG Sauer Kompressoren AG |
| Howden Group Ltd |
| Hitachi Ltd. |
| Fluitron Inc. |
| Others |
Supply Flow & Price Mechanics
Specialized alloy supply concentration in nickel-based superalloy smelting determines both pricing tier spreads and supply chain shape, compressing margins for high-pressure hydrogen service equipment while amplifying procurement risk for project developers facing extended lead times.
Pricing Analysis
The US Inflation Reduction Act dictates the pricing tier structure by conditioning tax credit eligibility on lifecycle emissions verification that favors efficient compression pathways. Three-tier pricing structure across premium, standard, and economy levels separates hermetic diaphragm architectures certified for fuel cell vehicle fueling from conventional reciprocating units and refurbished refinery equipment. Cost compression in the standard tier is intensifying because electrolyzer OEMs bundle compression skids into turn-key supply contracts, displacing standalone procurement. Refinery operators demonstrate lowest price sensitivity due to FCC-mandated sulfur reduction deadlines, while independent fueling station developers face acute capital constraints.
Supply Chain Analysis
Nickel-based superalloy feedstock draws from primary smelting capacity concentrated in the United States, Germany, and Japan, with limited qualified suppliers for seals and coatings in high-purity hydrogen service. Critical component dependencies include ASME-certified pressure vessel fabricators, metal-to-metal sealing specialists, and high-pressure welding certification pipelines. Single-source vulnerability runs through qualified welder training programs lagging deployment timelines for 1,000-bar industrial projects. Distribution runs through OEM-captive service networks fragmenting toward independent contractors, creating channel entry points for specialized aftermarket providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen compressor market tracks a cyclical recovery anchored to refinery retrofit waves driven by sulfur regulation tightening and electrolyzer manufacturing corridor maturation in Germany's industrial clusters.
For Market Incumbents: Build certification moats around ASME Section VIII Division 3 welding qualifications and F-Gas Regulation leakage compliance to defend against electrochemical compression substitutes. Anchor aftermarket service contracts through predictive maintenance digitization, locking in refinery loyalty where spare parts availability dominates procurement criteria. Expand captive supply of nickel-based superalloy components to offset raw material price volatility. For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu green hydrogen hubs present the most penetrable geographic underpenetration as PLI scheme incentives mature into ammonia synthesis retrofit demand. Target diaphragm compressor niches in semiconductor-grade hydrogen supply chains where hermetic architectures command premium positioning. Pursue technology licensing agreements with European engineering houses to accelerate architecture diffusion without fabrication bottlenecks. For Investors and Strategic Acquirers: The EU Green Deal hydrogen bank certification deadline reshapes the acquisition landscape by favoring vendors with proven F-Gas compliance and bundled electrolyzer-compressor integration capabilities. Focus on electrochemical-mechanical convergence plays serving off-grid industrial sites across the projection horizon. Monitor DOE pilot deployment announcements under Inflation Reduction Act funding as the inflection indicator for solid-state compression viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Supply | Captive nickel-based alloy sourcing insulates margins from smelter concentration in Germany and Japan. |
| Electrochemical Compression R&D Partnership | DOE-funded pilot deployments accelerate efficiency gains for distributed hydrogen production sites. |
| Diaphragm Technology Licensing Agreement | European fueling station mandates under EU Green Deal criteria expand addressable market for zero-contamination architectures. |
| Aftermarket Service Network Unbundling | Independent contractor channel entry captures maintenance contracts fragmenting from OEM-captive models. |
| High-Pressure Welder Certification Pipeline | ASME-qualified training programs reduce fabrication bottlenecks extending lead times for 1,000-bar vessels. |
Methodological Framework
Operator-level perspectives from refinery maintenance directors, electrolyzer OEM procurement teams, fueling station developers, and aftermarket service contractors anchored the qualitative base. Primary interview insights combined with secondary validation from EPA regulatory filings, DOE hydrogen hub announcements, EU Green Deal implementation documents, and SEC equipment manufacturer disclosures. Bottom-up unit economics triangulated against top-down industrial hydrogen demand projections across the analysis window.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling technology segmentation by mechanical, electrochemical, and thermochemical architectures alongside end-use splits in refineries, fuel cell vehicles, and chemical processing. CAGRs derived from electrolyzer manufacturing capacity announcements, FCC regulation compliance timelines, and hydrogen corridor infrastructure deployment schedules. Compressor duty cycle assumptions and pressure specification trends informed equipment replacement and greenfield procurement estimates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by electrochemical technology pioneers or unexpected F-Gas Regulation enforcement acceleration would shift outcomes. Cross-checking against IEA hydrogen demand scenarios and regional electrolyzer manufacturing capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Process Gas Compressors Market
Compressors
Rotary Air Compressor Market
Compressors
Axial Compressor Market
Compressors
Automotive Compressors Market
Compressors
Compressor Rental Market
Compressors
Air and Gas Compressor Market
Compressors
Oil Free Compressor Market
Compressors
Rotary Lobe Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Centrifugal Compressors Market
Compressors
Root Blower Market
Compressors
North America Hydrogen Compressor Market
Compressors
Compressed Air Lubricators Market
Compressors
Portable Air Compressor Market
Compressors
Industrial Air Compressor Market
Compressors
Chlorine Compressors Market