
 Oil and Gas Automation and Instrumentation Market | 2026-2036
Oil and Gas Automation and Instrumentation Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Automation and Instrumentation Market Analysis
US shale producers is pivoting toward digital wellsite architectures as pad drilling intensifies. Honeywell International Inc leverages its Experion platform to anchor control-system deployments across Permian and Bakken fields. Siemens AG competes through integrated DCS-SCADA bundles that sustain long-term service contracts with supermajors.
Oil and gas automation and instrumentation encompasses electromechanical systems, process controllers, and field devices engineered to operate across temperature ranges from minus 40 to plus 85 degrees Celsius while maintaining SIL 3 safety integrity levels. These systems execute real-time monitoring, closed-loop control, and emergency shutdown functions that protect personnel and optimize hydrocarbon throughput. SCADA and DCS technology segments command the largest installed base, though IoT Solutions is expanding fastest as edge computing enables sub-second anomaly detection at remote wellheads. Control Systems and Safety Equipment capture disproportionate margin pools due to certification barriers and replacement-cycle stickiness.
The US EPA enforces methane performance standards under OOOOb that mandate continuous emissions monitoring at new and modified facilities, while the EU F-Gas Regulation phases down hydrofluorocarbon use in refrigeration and cooling circuits tied to gas processing. Brazil's national petroleum regulator ANP imposes local content requirements that shape procurement decisions for subsea instrumentation. Stakeholders must weigh the capital cost of retrofitting legacy infrastructure against the operational savings and compliance certainty delivered by integrated automation platforms.
Market Dynamics
Upstream operators are consolidating control architectures around edge-native platforms as pad drilling density in US shale fields demands real-time coordination across multi-well sites. This infrastructure compression is forcing hardware vendors to embed analytics directly into field devices rather than rely on centralized SCADA hierarchies.
Growth Catalysts
- US EPA OOOOb methane standards:Continuous emissions monitoring mandates at new and modified facilities are accelerating replacement of intermittent leak detection with automated optical gas imaging systems.
- Permian Basin pad drilling intensification:Multi-well pads sharing surface infrastructure require synchronized choke management and artificial lift optimization through integrated DCS platforms.
- Edge computing hardware:Sub-second anomaly detection at remote wellheads is eliminating latency penalties that previously forced data transmission to onshore processing centers.
Market Restraints
- Semiconductor supply concentration:Safety instrumented systems depend on specialized industrial microcontrollers sourced predominantly from East Asian foundries, creating 26-32 week lead time volatility.
- EU F-Gas Regulation phase-down:Hydrofluorocarbon restrictions on refrigeration circuits in gas processing plants are forcing premature retrofit of cooling-dependent analyzer shelters.
- Subsea cable reliability limits:Fiber-optic umbilical failures in deepwater Brazil fields exceed mean-time-between-failure thresholds for critical control loops, constraining automation depth.
Strategic Opportunities
- Offshore Brazil pre-salt expansion:ANP local content requirements for subsea instrumentation create captive demand for suppliers establishing Brazilian manufacturing presence.
- Digital twin convergence with physics-based modeling:Integration of reservoir simulation with real-time production data is enabling predictive well intervention before productivity degradation.
- North Sea electrification mandates:UK and Norwegian offshore platform power-from-shore requirements are opening retrofit contracts for power management and variable frequency drive systems.
Industry Challenges
- SIL 3 certification timelines:Functional safety validation for modified control logic in legacy DCS architectures extends project schedules by 8-14 months.
- Cybersecurity skill scarcity:OT security architecture design for upstream remote terminal units lacks qualified practitioners, delaying deployment of zero-trust network segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Automation and Instrumentation Market |
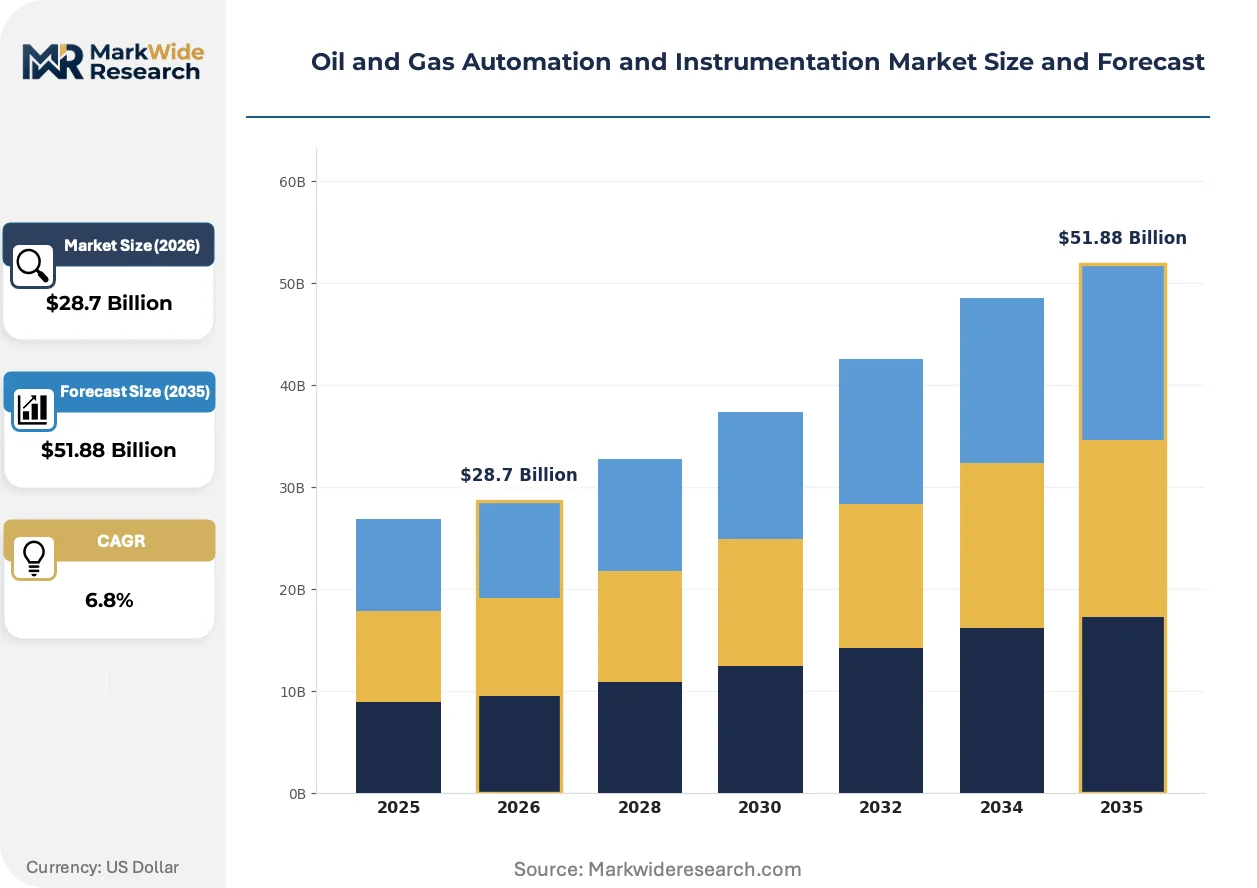
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Systems, Sensors, Safety Equipment, Measurement Devices Technology: SCADA, PLC, DCS, IoT Solutions Application: Production Monitoring, Pipeline Management, Refinery Operations, Predictive Maintenance End User: Upstream, Midstream, Downstream, Oilfield Services |
| Companies Covered | Honeywell International Inc, Siemens AG, Schneider Electric, Mitsubishi Electric Corp., Rockwell Automation Inc., Emerson Electric Co., Yokogawa Electric Corporation, Endress+Hauser AG, ABB Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Automation and Instrumentation Market Emerging Trajectories
Automation architectures are flattening hierarchies as compute migrates toward the process edge. Vendors are reconfiguring product portfolios around software-defined instrumentation that decouples hardware lifecycle from functionality updates.
Edge-native control systems are decentralizing decision authority from centralized DCS servers to field-mounted controllers with embedded analytics. US shale operators are deploying these architectures across Permian multi-well pads to eliminate single points of failure. This topology is compressing response latency for emergency shutdown sequences from hundreds of milliseconds to sub-100 microsecond ranges.
The EU F-Gas Regulation is accelerating refrigerant transition in gas processing analyzer shelters, forcing replacement of hydrofluorocarbon-dependent cooling systems with CO2 or ammonia alternatives. Equipment suppliers are engineering compact chiller retrofits that maintain +5°C setpoints in desert ambient conditions. North Sea operators are absorbing 15-20% capital premiums for compliant systems to avoid production permit suspensions.
Buyer contracting is consolidating around performance-guaranteed service agreements rather than capital equipment purchases. Supermajors are unbundling automation hardware from long-term optimization services, forcing vendors to price outcome-based contracts for throughput improvement. This model is most advanced in Norwegian continental shelf projects where Statoil-equivalent operators demand guaranteed production uptime clauses.
Oil and Gas Automation and Instrumentation Market Segmentation
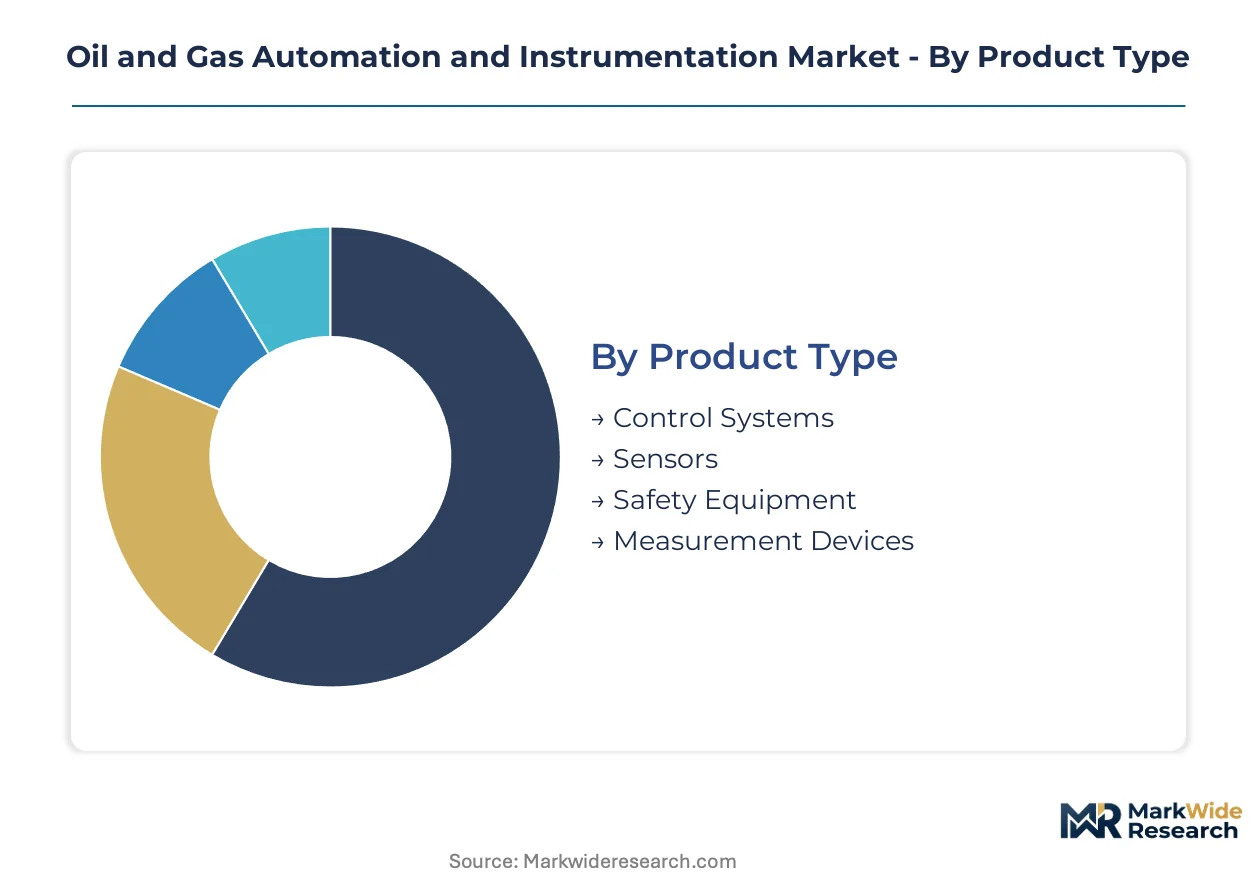
Automation and instrumentation procurement decisions in oil and gas operations hinge on safety integrity requirements, legacy infrastructure compatibility, and regulatory compliance mandates. Segment boundaries increasingly blur as vendors bundle hardware with predictive analytics and outcome-based service contracts.
Product Type:
Supply concentration among certified safety system vendors creates tiered procurement dynamics where SIL 3-validated equipment commands extended lead times and premium pricing.
- Control Systems:Distributed control systems and programmable logic controllers execute real-time process regulation across temperature extremes from minus 40 to plus 85 degrees Celsius. Demand clusters in Permian Basin pad drilling operations where multi-well synchronization requires sub-100 microsecond emergency shutdown response.
- Safety Equipment:Safety instrumented systems and emergency shutdown devices maintain SIL 3 integrity levels through redundant architectures and fail-safe logic. US EPA OOOOb methane standards are accelerating replacement cycles for leak detection systems at new and modified facilities.
- Sensors:Pressure, temperature, and flow transmitters provide field-level data acquisition for closed-loop control.
- Measurement Devices:Analyzers and metering systems quantify hydrocarbon composition and volume for custody transfer and environmental reporting.
Control Systems absorbs the bulk of installed capacity; Safety Equipment is expanding most quickly.
Technology:
Cost tier stratification separates capital-intensive legacy platforms from subscription-based edge-native architectures that reduce upfront deployment expenditure.
- DCS:Distributed control systems anchor centralized process management through redundant server architectures and proprietary communication protocols. Supermajors in the North Sea sustain long-term service contracts with vendors bundling hardware and optimization services.
- SCADA:Supervisory control and data acquisition systems enable remote monitoring across geographically dispersed infrastructure through master terminal units and radio telemetry. Midstream operators deploy these architectures for pipeline corridor surveillance spanning hundreds of kilometers.
- PLC:Programmable logic controllers deliver deterministic control for discrete manufacturing and batch processes.
- IoT Solutions:Edge computing platforms embed analytics directly into field devices for sub-second anomaly detection.
DCS retains the largest installed base; IoT Solutions is gaining share fastest.
Application:
Volume concentration in production environments reflects the upstream sector's capital intensity and well count expansion in US shale and offshore Brazil.
- Production Monitoring:Real-time surveillance of wellhead parameters, artificial lift performance, and reservoir pressure depletion enables optimization of hydrocarbon recovery rates. Edge-native architectures in Permian multi-well pads eliminate single points of failure through decentralized decision authority.
- Predictive Maintenance:Machine learning models applied to vibration, thermal, and electrical signature data forecast equipment degradation before functional failure. Offshore platforms in the North Sea and Brazil are accelerating adoption as unplanned shutdown costs exceed preventive intervention expenditure.
- Pipeline Management:Leak detection, pig tracking, and compression optimization secure hydrocarbon transport integrity.
- Refinery Operations:Catalytic process control and distillation optimization maximize throughput in downstream conversion facilities.
Production Monitoring dominates current deployment; Predictive Maintenance is climbing the fastest.
End User:
Customer type differentiation separates integrated operators with captive engineering capabilities from oilfield services contractors procuring standardized automation packages.
- Upstream:Exploration and production companies deploy automation across drilling, completion, and field development phases with stringent safety and environmental compliance requirements. Pad drilling intensification in US shale fields demands synchronized choke management and artificial lift optimization through integrated platforms.
- Midstream:Pipeline and storage operators prioritize leak detection and flow assurance across extensive linear infrastructure networks.
- Downstream:Refining and petrochemical processors focus on catalytic reaction control and product quality optimization.
- Oilfield Services:Contract drilling and well intervention providers rent or lease automation equipment for project-specific deployment.
Upstream accounts for the greatest automation intensity; Midstream is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin shale formations anchor North American automation intensity, while North Sea electrification mandates and Brazil's pre-salt expansion reshape procurement geography across three continents.
United States
Pad drilling densification across the Permian Basin and Bakken fields drives synchronized choke management demand. EPA OOOOb methane performance standards mandate continuous emissions monitoring at new and modified facilities. Midland-Odessa operators deploy edge-native architectures for sub-100 microsecond emergency shutdown response across multi-well sites.
Norway
Offshore platform power-from-shore requirements accelerate retrofit contracts for power management systems. Norwegian continental shelf regulators enforce production uptime clauses in performance-guaranteed service agreements. Stavanger-based supermajors unbundle automation hardware from long-term optimization services, reshaping vendor contracting models.
Brazil
Pre-salt field development concentrates subsea instrumentation demand at depths exceeding 2,000 meters. ANP local content requirements shape procurement decisions for subsea control systems. Santos Basin operators absorb fiber-optic umbilical reliability constraints that exceed mean-time-between-failure thresholds for critical control loops.
Germany
EU F-Gas Regulation phase-down forces hydrofluorocarbon-dependent cooling system retrofits in gas processing analyzer shelters. ECHA restrictions on industrial refrigerants accelerate CO2 and ammonia alternative adoption. Ruhr Valley equipment suppliers engineer compact chiller retrofits maintaining +5°C setpoints in desert ambient conditions.
United Kingdom
North Sea decommissioning timelines intersect with electrification mandates for aging platform infrastructure. UK offshore regulators enforce variable frequency drive system upgrades to reduce carbon intensity. Aberdeen supply bases consolidate procurement for integrated DCS-SCADA bundles serving supermajor long-term service contracts.
Oil and Gas Automation and Instrumentation Market Vendor Landscape
Global majors compete with regional champions across certification-intensive safety system tiers. Market structure concentrates around vendors holding SIL 3 validation credentials and proprietary communication protocol ecosystems. Three archetypes dominate: diversified industrial conglomerates bundling hardware with optimization services, pure-play automation specialists embedding analytics into field devices, and regional system integrators serving local content mandates. Competitive moves center on strategic partnerships for edge computing integration and geographic expansion through Brazilian manufacturing presence.
Within the diversified conglomerate tier, Honeywell International Inc and Siemens AG exemplify contrasting platform strategies. Honeywell leverages its Experion control architecture across Permian and Bakken field deployments, anchoring long-term service relationships through centralized system integration. Siemens competes through integrated DCS-SCADA bundles that sustain supermajor contracts across the North Sea and Norwegian continental shelf. Yokogawa Electric Corporation occupies a position within the precision instrumentation specialist tier, representing Japanese engineering concentration in high-integrity measurement devices for subsea and harsh environment applications.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Siemens AG |
| Schneider Electric |
| Mitsubishi Electric Corp. |
| Rockwell Automation Inc. |
| Emerson Electric Co. |
| Yokogawa Electric Corporation |
| Endress+Hauser AG |
| ABB Ltd |
| Others |
Supply Flow & Price Mechanics
SCADA systems engineering talent concentration in Houston and Stavanger amplifies labor-cost differentials between premium-tier integrated service contracts and economy-tier hardware-only procurement. EPA OOOOb compliance mandates widen this spread as buyers absorb 15-20% premiums for continuous emissions monitoring bundles that embed certification and warranty coverage.
Pricing Analysis
Warranty and field-service bundling separates outcome-based contracts from unbundled equipment-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects SIL certification grade and geographic service response commitments. Pricing pressure stems from semiconductor lead time volatility forcing buyers toward spot-market component premiums. Midstream pipeline operators exhibit highest price sensitivity due to standardized SCADA requirements, while North Sea supermajors prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Industrial microcontroller supply rests on East Asian foundry concentration for safety instrumented systems requiring extended temperature-range operation. Specialized sensors draw from German precision engineering and Japanese measurement device manufacturers. Single-source vulnerability concentrates in subsea fiber-optic umbilical production for deepwater Brazil fields. Distribution runs through authorized system integrator networks that anchor long-term service relationships with Permian Basin operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as edge-native architectures displace centralized DCS hierarchies across US shale operations. IoT Solutions deployment is replacing legacy SCADA topologies that previously forced data transmission to onshore processing centers.
For Market Incumbents: Lock in supermajor relationships through performance-guaranteed uptime clauses that embed hardware, software, and optimization services into indivisible contracts. Expand Brazilian manufacturing presence to satisfy ANP local content requirements for pre-salt subsea instrumentation. Counter pure-play edge computing entrants by accelerating embedded analytics roadmaps for field-mounted controllers.
For New Entrants and Emerging Players: Begin with predictive maintenance software layers that unbundle from incumbent DCS-SCADA bundles, targeting Permian Basin independent operators lacking captive engineering capabilities. White-space concentration sits in cybersecurity architecture design for upstream remote terminal units where OT security skill scarcity delays zero-trust deployment. Pursue channel partnerships with regional system integrators serving midstream pipeline corridors.
For Investors and Strategic Acquirers: Re-rating potential sits with edge-native automation specialists given EPA methane monitoring mandate acceleration. Long-term viability favors vendors holding SIL 3 validation credentials alongside software-defined instrumentation portfolios. Watch ANP local content enforcement intensity as inflection indicator for Brazilian manufacturing footprint valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Platform Development | Embedded analytics in field controllers eliminates centralized SCADA latency penalties for Permian operators. |
| Brazilian Manufacturing Localization | ANP content rules create captive demand for subsea instrumentation suppliers establishing domestic production. |
| Cybersecurity Architecture Investment | Zero-trust network segmentation for upstream RTUs addresses critical OT security skill scarcity. |
| Refrigerant Transition Engineering | EU F-Gas Regulation compliance opens retrofit contracts for CO2 and ammonia analyzer shelter cooling. |
| Outcome-Based Service Contracting | Performance-guaranteed uptime clauses reshape Norwegian continental shelf vendor relationships toward long-term partnerships. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this oil and gas automation market assessment. Primary interviews with control systems engineers, upstream operations managers, subsea project procurement leads, and industrial cybersecurity consultants combined with EPA enforcement databases, ANP regulatory releases, and EU F-Gas implementation guidance. Bottom-up wellhead device counts and top-down supermajor capital expenditure triangulation validated segment-level estimates.
Granularity-level modeling distinguished product type, technology platform, application function, and end-user category across the projection horizon. Control Systems and Safety Equipment segments incorporated SIL certification tier and replacement cycle assumptions. IoT Solutions trajectory reflected edge computing hardware cost curves and sub-second anomaly detection adoption patterns. CAGRs derived from segment-level volume buildups and value-per-unit trends normalized against hydrocarbon production forecasts.
Underlying measurement precision varies by segment; Control Systems and established DCS-SCADA categories carry tighter precision than nascent IoT Solutions deployments where vendor reporting remains sparse. Forecasts reflect assumptions around EPA OOOOb enforcement timing, semiconductor supply normalization, and Brazilian pre-salt development cadence. A small set of regulatory trigger points—EU F-Gas phase-down acceleration, ANP local content threshold adjustments, and North Sea electrification mandate expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oilfield Chemicals Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Downhole Tools Market
Oil & Gas
Mud Balance Market
Oil & Gas
Egypt Oil and Gas Midstream Market
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
South America Deep Water and Ultra Deep Water Exploration and Production (Eandp) Market
Oil & Gas
Crown Block Market
Oil & Gas
Natural Gas Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
Whipstocks Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Underwater Monitoring System for Oil and Gas Market
Oil & Gas
GCC Natural Gas Market