
 North America Compressor Market | 2026-2036
North America Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Compressor Market Analytics
Multi-source procurement for large-frame centrifugal units is repositioning how midstream operators manage fleet reliability. Ingersoll Rand leverages its aftermarket service density across the Gulf Coast to sustain recurring revenue streams. Atlas Copco AB anchors its position through oil-free screw technology leadership in food and pharmaceutical processing. Kaeser Kompressoren competes on energy efficiency ratings, differentiating its rotary screw portfolio in manufacturing-intensive states.
A compressor is a mechanical device that increases gas pressure by reducing volume through positive displacement or dynamic action, typically achieving discharge pressures from 100 psi to over 10,000 psi depending on stage configuration and application requirements. Its primary industrial purpose centers on enabling pneumatic tools, process gas transport, refrigeration cycles, and hydrocarbon extraction across commercial and heavy industrial settings. Rotary screw compressors command the largest share of installed base value due to their continuous-duty reliability in manufacturing environments, while centrifugal systems capture premium margin pools in oil and gas processing where multi-stage configurations handle high-volume flows. Electric-drive technology is gaining structural share against diesel alternatives as grid access expands and carbon accounting intensifies across buyer procurement criteria.
EPA methane regulations under the Inflation Reduction Act and OSHA workplace noise exposure standards shape product design requirements and replacement timelines across the North American installed base. DOE minimum efficiency performance standards for air compressors redirect R&D investment toward variable-speed drive integration and heat recovery systems. Stakeholders must monitor how FERC pipeline certification delays and state-level renewable gas mandates reshape demand timing and technology specifications for new compression assets.
Market Dynamics
EPA methane emissions rules under the Inflation Reduction Act are compressing replacement cycles across the installed base while electric-drive technology captures share from diesel alternatives in Permian Basin operations.
Growth Catalysts
- Upstream Gathering Expansion:Oil and gas operators across Texas and New Mexico are deploying additional compression capacity for Permian Basin production growth and associated gas capture.
- FERC Pipeline Certification:Midstream infrastructure buildouts receiving federal approval are triggering sequential compression station investments along new transport corridors.
- Variable-Speed Drive Integration:DOE efficiency standards are redirecting capital toward intelligent compressor systems with integrated heat recovery capabilities.
Market Restraints
- Large-Frame Supply Concentration:Multi-stage centrifugal compressor manufacturing concentrates among a limited supplier base, creating procurement bottlenecks for midstream operators.
- Copper and Rare Earth Volatility:Electric motor windings and permanent magnet materials face input cost swings that compress margins on high-efficiency units.
- Grid Access Limitations:Remote wellpad locations in West Texas and Western Canada lack transmission infrastructure to support electrification timelines.
Strategic Opportunities
- Renewable Gas Mandates:California and Northeast state-level biogas and hydrogen blending requirements are creating demand for corrosion-resistant compression specifications.
- Aftermarket Service Density:Gulf Coast maintenance networks can extend recurring revenue streams through predictive diagnostics and remote monitoring platforms.
- Food and Pharma Oil-Free Conversion:Screw compressor technology convergence with advanced coating materials is opening replacement demand in FDA-regulated processing facilities.
Industry Challenges
- Rotating Equipment Specialist Shortage:Maintenance technician pipelines are thinning across Texas and Louisiana energy corridors, extending downtime windows.
- OSHA Noise Compliance Timelines:Workplace exposure standard enforcement is accelerating acoustic enclosure retrofit schedules beyond planned capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Compressor Market |
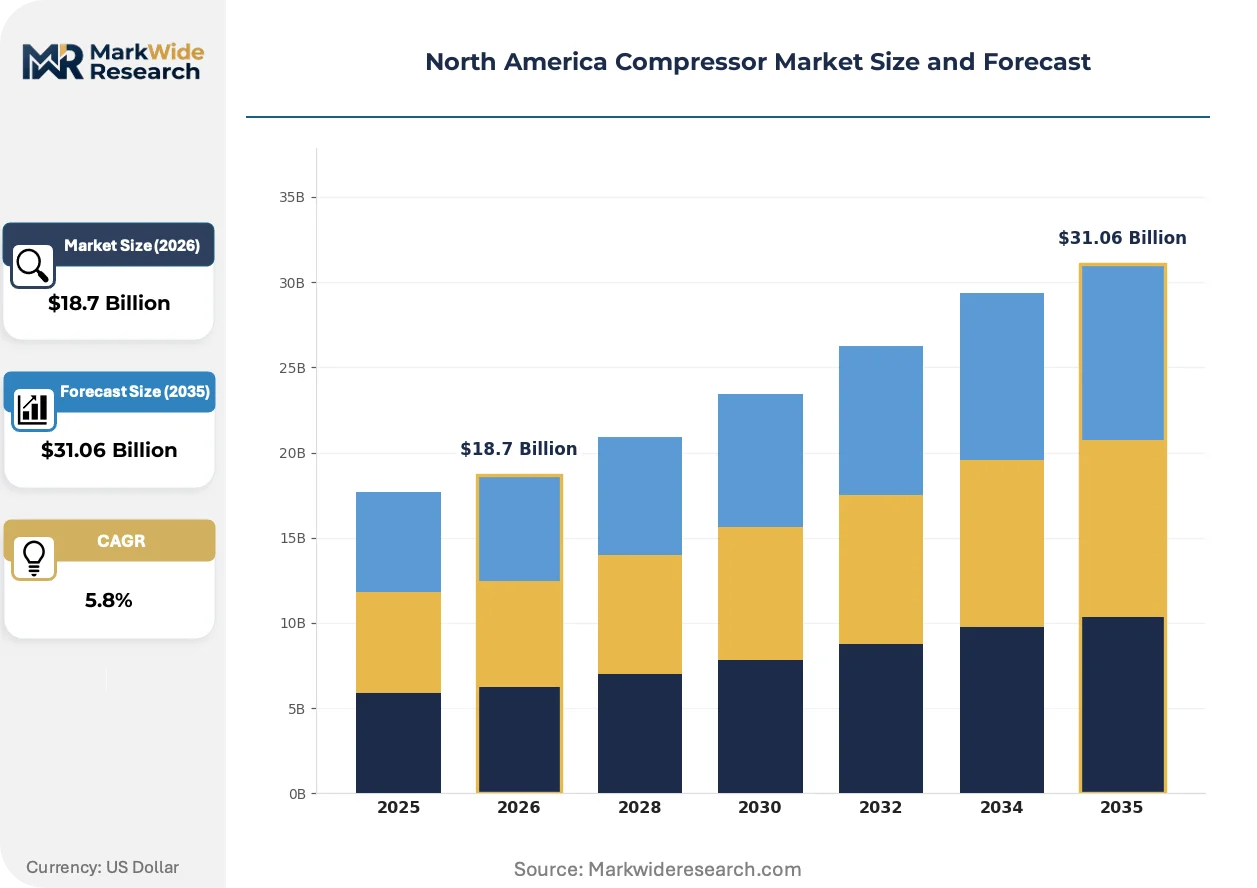
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Rotary Screw, Centrifugal, Scroll End User: Manufacturing, Oil & Gas, HVAC, Food & Beverage Installation: Onshore, Offshore, Mobile, Stationary Technology: Electric, Diesel, Gas, Hybrid |
| Companies Covered | Atlas Copco AB, Ingersoll Rand, Ariel Corporation, Gardner Denver, Sullair, Quincy Compressor, Kaeser Kompressoren, Aerzener Maschinenfabrik GmbH, Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Compressor Market Evolving Landscape
Compression technology is pivoting toward electrification and intelligence as regulatory pressure and operational efficiency demands converge across North American industrial and energy infrastructure.
Permanent magnet motor technology paired with variable frequency drives is overtaking conventional fixed-speed induction systems in midstream applications. Pipeline operators in Texas and Oklahoma are specifying these configurations for new-build stations. The shift is compressing energy intensity metrics while raising upfront capital requirements.
EPA methane performance standards under the Inflation Reduction Act are mandating leak detection and repair protocols that favor sealed compressor designs over legacy reciprocating architectures. Equipment procurement specifications now incorporate continuous emissions monitoring as a baseline requirement. Oil and gas gathering segments in the Permian and Bakken formations are responding with accelerated fleet turnover schedules.
Service contract structures are fragmenting from bundled maintenance agreements toward unbundled component-level subscriptions. Large manufacturing facilities in the Midwest and Southeast are separating predictive analytics, parts logistics, and field labor into discrete purchasing decisions. This pattern is most visible among automotive and aerospace production plants with mature reliability engineering functions.
North America Compressor Market Segmentation
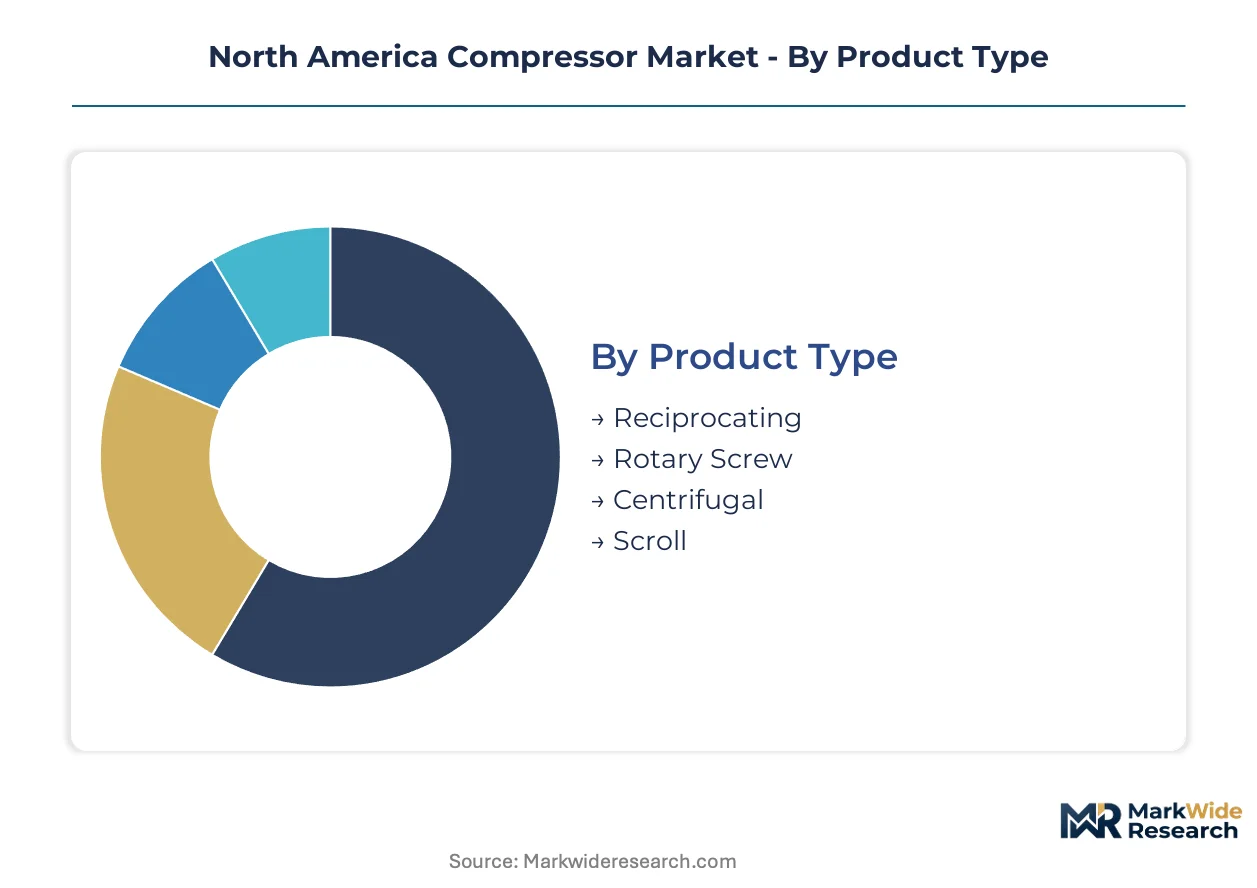
Compressor segmentation in North America reflects divergent equipment economics across duty cycles and regulatory exposure. Product type and technology choices determine capital intensity and operating cost profiles for buyers managing EPA compliance and energy accounting pressures.
Product Type:
Volume deployment concentrates in continuous-duty rotary architectures, while premium margin pools attach to multi-stage dynamic systems serving hydrocarbon processing.
- Reciprocating:Piston-driven positive displacement units achieve intermittent duty at pressures exceeding 5,000 psi through single or multi-stage configurations. Demand clusters in upstream wellhead gas gathering across the Permian Basin, where EPA methane rules are accelerating replacement of unsealed crankcase designs.
- Rotary Screw:Meshing helical rotors deliver pulsation-free compressed air across 100-200 psi ranges with minimal maintenance intervals. Manufacturing facilities in Michigan and Ohio specify these units for automated production lines, driven by DOE efficiency standards redirecting procurement toward variable-speed configurations.
- Centrifugal:Dynamic impeller stages handle high-volume flows above 500 cfm in pipeline transmission service.
- Scroll:Orbiting spiral compressors serve HVAC and medical air applications requiring oil-free output.
Mature deployment sits with rotary screw systems in Midwest manufacturing corridors. Newer deployment is concentrated in centrifugal configurations along Texas and Oklahoma pipeline corridors.
End User:
Application concentration splits between process-critical hydrocarbon infrastructure and quality-sensitive regulated manufacturing.
- Manufacturing:Automotive stamping plants and metal fabrication facilities in Tennessee and Indiana deploy rotary screw fleets for pneumatic tooling and paint booth operations. OSHA noise exposure enforcement is accelerating acoustic enclosure retrofit schedules beyond planned capital cycles.
- Oil & Gas:Midstream gathering and processing operators across Texas, New Mexico, and Western Canada specify large-frame centrifugal and reciprocating units for gas lift, reinjection, and pipeline transport. FERC certification timelines for new interstate pipelines are compressing procurement windows for sequential compression station investments.
- HVAC:Commercial building stock in Florida and Arizona drives scroll and screw chiller compressor demand for cooling-degree-day intensity.
- Food & Beverage:Dairy processing and beverage packaging lines in Wisconsin and California require oil-free screw or centrifugal systems meeting FDA compressed air purity standards.
Installed base density peaks in manufacturing end-use across the Great Lakes region. Fastest expansion is occurring in oil and gas processing tied to Permian Basin production growth.
Installation:
Mobility requirements versus fixed infrastructure access determine power source flexibility and maintenance logistics.
- Onshore:Fixed installations at well pads, processing plants, and manufacturing facilities dominate capital deployment. Electric grid availability constraints in West Texas and rural Alberta are extending diesel dependency timelines despite carbon accounting pressures.
- Offshore:Platform-mounted compression systems in the Gulf of Mexico handle gas reinjection and export pumping. Corrosion-resistant specifications and helicopter-lift maintenance logistics elevate capital and operating cost structures versus comparable onshore units.
- Mobile:Trailer-mounted diesel and gas-engine compressors serve drilling completion and workover operations.
- Stationary:Permanent plant installations anchor aftermarket service contract economics.
Stationary infrastructure commands the majority of installed value. Mobile deployment is expanding most quickly in fracking fleet electrification trials.
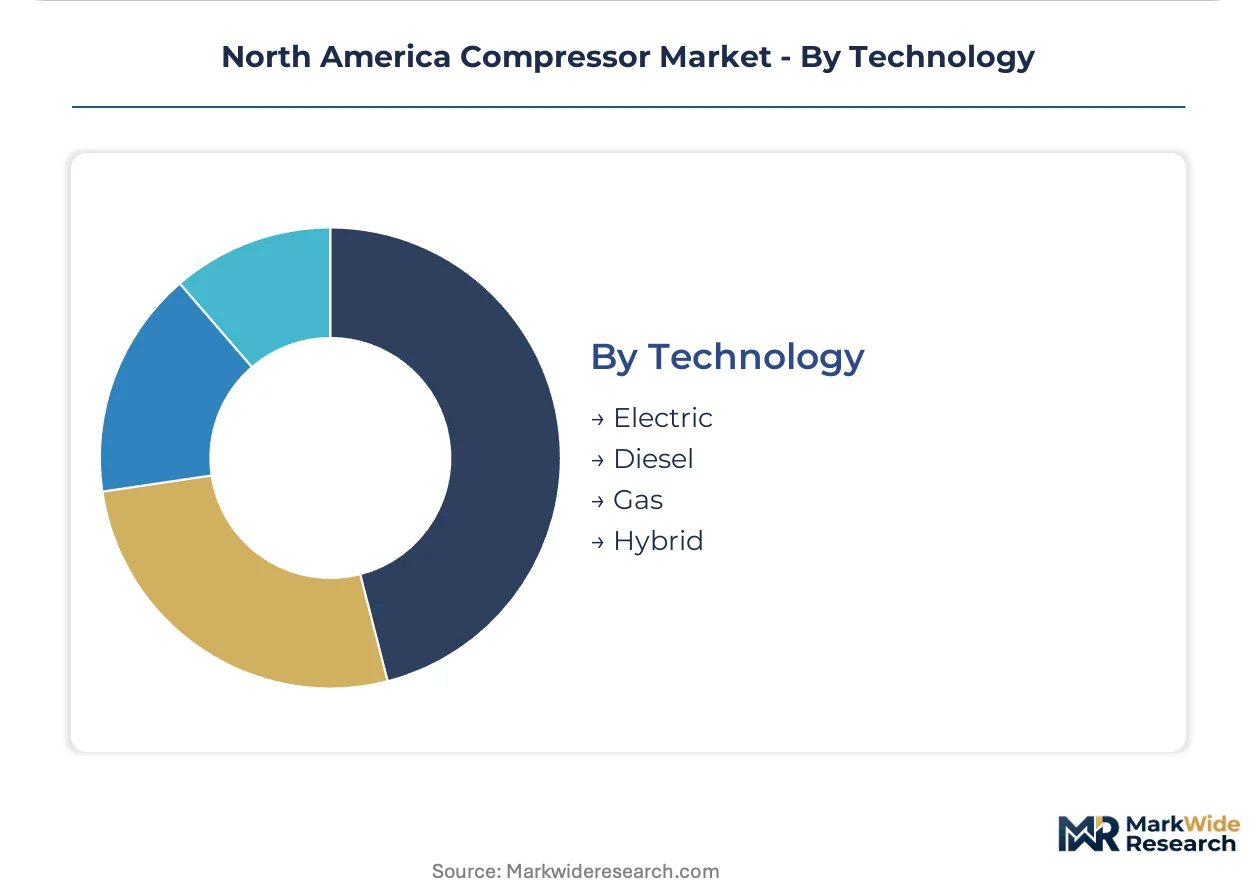
Technology:
Power source selection reflects grid access, emissions accounting, and duty cycle predictability tradeoffs.
- Electric:Grid-connected motors with variable frequency drives are displacing fixed-speed induction systems across manufacturing and pipeline applications. DOE minimum efficiency performance standards are redirecting R&D investment toward permanent magnet motor integration and heat recovery capture.
- Diesel:Compression ignition engines retain share in remote locations lacking transmission infrastructure. Input cost volatility and carbon intensity disclosure requirements are compressing addressable market scope to emergency backup and mobile service roles.
- Gas:Field gas and pipeline natural gas fueling serves upstream gathering operations with available hydrocarbon supply.
- Hybrid:Dual-fuel and battery-buffered configurations pilot in emission-controlled zones.
Electric technology anchors new procurement in grid-connected industrial corridors. Gas-engine deployment persists in Permian and Bakken wellhead locations with stranded gas economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Permian Basin tight gas formations anchor North American compression demand through upstream gathering and midstream transport infrastructure buildouts.
United States
Texas and New Mexico field operations drive centrifugal and reciprocating unit procurement for Permian Basin gas lift and pipeline injection. EPA methane performance standards under the Inflation Reduction Act compress replacement cycles for legacy unsealed designs. Houston-Gulf Coast maintenance networks sustain aftermarket service density for midstream operator fleets.
Canada
Western Alberta oil sands and Montney formation developments require large-frame compression for gas reinjection and bitumen processing. The country's national energy regulator enforces pipeline integrity standards that elevate specification requirements for new compression assets. Calgary-headquartered operator procurement concentrates on cold-weather hardened configurations for sub-zero duty cycles.
Mexico
Burgeoning LNG import terminal capacity at Altamira and Manzanillo drives coastal compression infrastructure investment. State utility procurement guidelines favor electric-drive configurations where grid interconnection permits. Northeastern industrial corridor manufacturing clusters around Monterrey specify rotary screw fleets for automotive supplier parks.
North America Compressor Market Competitive Landscape
Portfolio diversification dominates the current landscape as established suppliers extend service contract structures and aftermarket density. The vendor base concentrates around three strategic tiers: full-line industrial conglomerates with Gulf Coast service networks, specialized oil and gas compression engineers with large-frame capabilities, and regional efficiency-focused rotary screw manufacturers. M&A activity and vertical integration into predictive maintenance platforms represent the primary competitive vectors reshaping positioning.
Among European-headquartered industrial groups, Atlas Copco AB and Aerzener Maschinenfabrik GmbH exemplify technology-led positioning through oil-free and process gas specializations. Ingersoll Rand occupies a scale-driven archetype anchored by aftermarket service density across North American energy corridors. These three represent divergent strategic postures: technology differentiation, regional service intensity, and portfolio breadth respectively.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Ingersoll Rand |
| Ariel Corporation |
| Gardner Denver |
| Sullair |
| Quincy Compressor |
| Kaeser Kompressoren |
| Aerzener Maschinenfabrik GmbH |
| Emerson Electric Co. |
| Others |
Value Network & Pricing Analysis
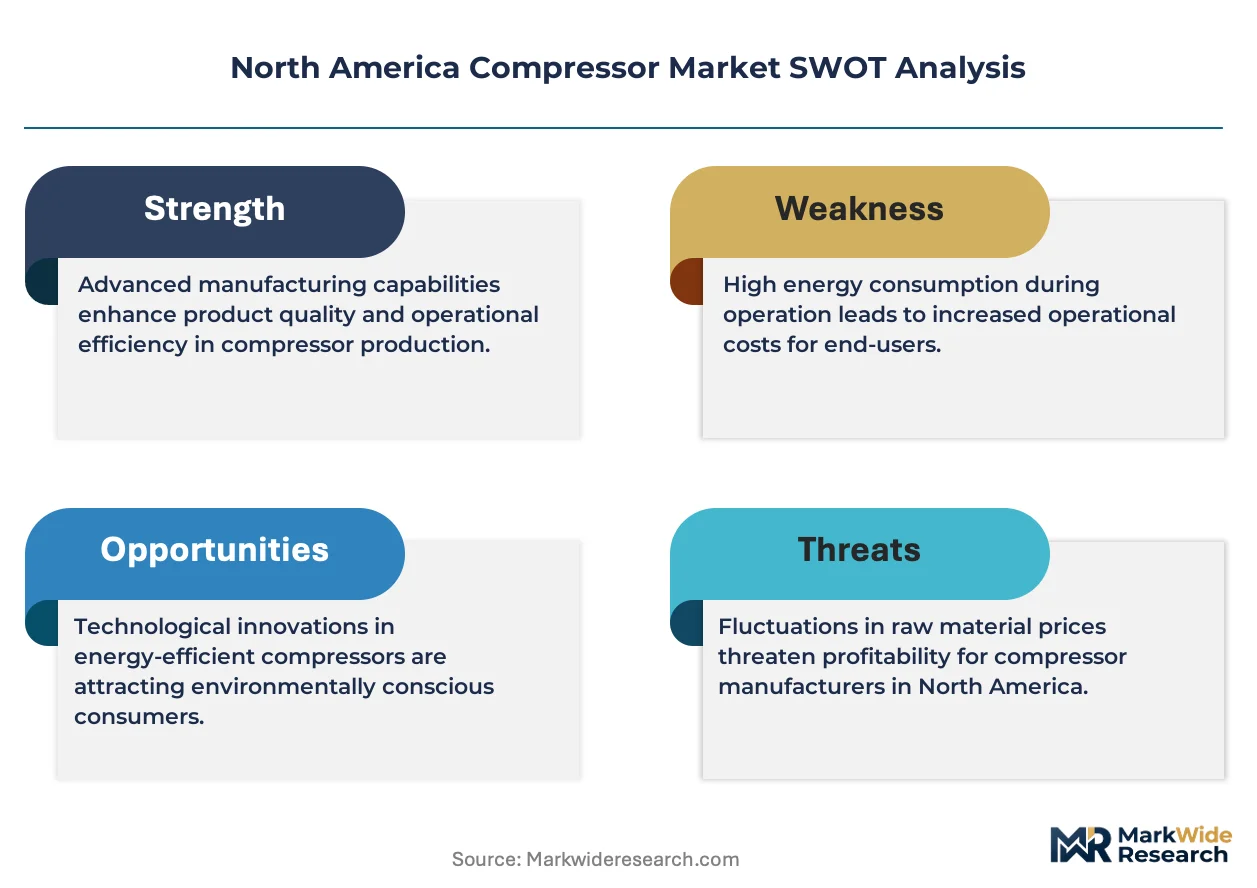
Copper and rare earth price indices cascade through North American compressor manufacturing, elevating permanent magnet motor costs and stratifying final equipment pricing across premium electric-drive, standard induction, and economy fixed-speed tiers. Midstream operators absorb these input swings through long-term offtake agreements while manufacturing buyers face spot-market exposure on replacement cycles.
Pricing Analysis
Warranty bundling separates full-service contracts with predictive maintenance from unbundled equipment-only procurement. Three-tier pricing structure across premium, standard, and economy levels reflects permanent magnet efficiency ratings, EPA emissions certification tiers, and aftermarket service density. Pricing pressure stems from copper volatility in electric motor windings, compressing margins on high-efficiency units. Manufacturing facilities in Michigan and Ohio exhibit highest price sensitivity due to volume procurement cycles, while Permian Basin operators prioritize reliability over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from midstream operators require qualified suppliers in Germany, Japan, and the United States for large-frame centrifugal components. Manufacturing draws from copper Chilean mining, Chinese rare earth processing, and domestic steel forging for pressure vessels. Single-source vulnerability concentrates in permanent magnet supply chains. Distribution runs through Houston-Gulf Coast logistics hubs serving Permian and Bakken field operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America compressor market sits in a technology-transition phase as electric-drive systems with variable frequency drives displace diesel and fixed-speed induction architectures across pipeline and manufacturing applications.
For Market Incumbents: Anchor aftermarket service density through predictive diagnostics platforms and remote monitoring subscriptions. Defend position against emerging electric-drive specialists by deepening backward integration into permanent magnet motor production. Prioritize EPA emissions certification investment to capture accelerated replacement demand under Inflation Reduction Act methane rules. For New Entrants and Emerging Players: Begin with corrosion-resistant compression specifications for California and Northeast biogas blending mandates. Target food and pharmaceutical oil-free conversion opportunities in Wisconsin and California processing facilities. Pursue unbundled component-level service contracts with automotive and aerospace plants possessing mature reliability engineering functions. For Investors and Strategic Acquirers: Distressed-cycle entries favor Gulf Coast maintenance networks with established field technician pipelines in Texas and Louisiana. Long-term viability centers on electrification exposure and regulatory compliance service revenue. Monitor FERC pipeline certification velocity as the primary inflection signal for sequential compression station investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Integration | Captures DOE efficiency standard compliance and premium pricing in pipeline applications. |
| Aftermarket Service Density Expansion | Builds recurring revenue through predictive diagnostics platforms across Gulf Coast corridors. |
| EPA Emissions Certification Investment | Unlocks accelerated replacement cycles under Inflation Reduction Act methane performance standards. |
| Corrosion-Resistant Specification Development | Addresses California and Northeast renewable gas blending mandates for hydrogen and biogas service. |
| Acoustic Enclosure Retrofit Capacity | Captures OSHA noise compliance-driven demand from manufacturing facilities in Tennessee and Indiana. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. EIA production statistics, FERC pipeline certification databases, EPA emissions enforcement records, and DOE efficiency standard publications provided validation. Bottom-up equipment deployment counts triangulated against top-down energy infrastructure investment flows.
Granularity-level modeling operated at product type, end-use sector, installation category, and power source technology dimensions across the analysis window. CAGRs derived from equipment replacement cycle analysis, regulatory compliance timeline compression, and electrification penetration curves. Permian Basin production growth forecasts and FERC pipeline approval queues served as oil and gas demand inputs. Manufacturing sector modeling incorporated DOE efficiency standard phase-in schedules and OSHA enforcement patterns.
Copper and rare earth price volatility, FERC certification delays, and grid access expansion timelines are the dominant revision risks. Deviation in electrification infrastructure buildout pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Tandem Piston Compressors Market
Compressors
Middle East and Africa Booster Compressor Market
Compressors
Portable Air Compressor Market
Compressors
Process Gas Compressors Market
Compressors
Scroll Compressor Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Reciprocating Air Compressor Market
Compressors
USA Scroll Compressor Market
Compressors
Portable Compressor Market
Compressors
Compressed Air Lubricators Market
Compressors
Industrial Air Compressor Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Air Compressor Market
Compressors
Compressed Air Filtration and Dryer System Market
Compressors
Compressor Rental Market