
 LNG Compressor Market | 2026-2036
LNG Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Compressor Market Outlook
Aftermarket service contracts and predictive maintenance subscriptions is shifting how LNG compressor vendors capture lifetime value from installed base assets. Siemens anchors its position through digital twin diagnostics bundled with long-term service agreements. Baker Hughes differentiates via remote monitoring platforms that reduce unplanned downtime at liquefaction trains. Mitsubishi Heavy Industries extends its geographic reach by combining compressor overhauls with performance guarantees.
An LNG compressor is a mechanical device that pressurizes natural gas to enable liquefaction at approximately minus 162 degrees Celsius, typically handling inlet flows from 50,000 to over 500,000 cubic meters per hour depending on train capacity. Centrifugal compressors dominate large-scale baseload liquefaction due to continuous flow efficiency and lower maintenance intervals compared to reciprocating alternatives. Multi-stage cryogenic configurations represent the fastest-growing technology segment as operators pursue higher thermal efficiency and reduced refrigerant leakage. Screw compressors occupy a specialized niche in small-scale and modular LNG applications where footprint constraints outweigh absolute throughput requirements.
The EPA enforces methane performance standards under New Source Performance Standards that compel compressor seal upgrades and leak detection protocols at US liquefaction facilities. EMA's F-Gas Regulation progressively restricts high-global-warming-potential refrigerants used in compressor cooling circuits across European terminals. Japan's METI incorporates LNG infrastructure resilience into national energy security planning, influencing compressor redundancy specifications. Stakeholders must weigh stranded asset risk against the capital intensity of next-generation compression architectures as feedstock quality and carbon intensity benchmarks evolve.
Market Dynamics
Multi-stage cryogenic compression architectures are displacing conventional single-stage systems as liquefaction operators pursue thermal efficiency gains and methane containment under tightening emission protocols.
Growth Catalysts
- EU F-Gas Regulation:Progressive refrigerant phase-down mandates compressor cooling circuit redesigns, creating replacement demand across European LNG terminals.
- Floating LNG infrastructure:Offshore liquefaction and regasification vessel deployments require compact, modular compression packages with marine certification.
- Qatar North Field expansion:Mega-train liquefaction projects drive procurement of high-capacity centrifugal compressors exceeding 500,000 cubic meters per hour throughput.
Market Restraints
- Specialized alloy supply concentration:Nickel-based superalloys for cryogenic impellers concentrate among a limited supplier base, creating input cost volatility and lead time uncertainty.
- Extended certification timelines:API 617 and ISO 10494 compliance testing for large-frame compressors extends delivery schedules by 12-18 months.
- Electrification infrastructure gaps:Grid capacity limitations at remote liquefaction sites constrain adoption of motor-driven alternatives to gas turbine drivers.
Strategic Opportunities
- Small-scale modular LNG:Distributed liquefaction for mining and marine bunkering applications creates demand for screw compressor packages below 50,000 cubic meters per hour.
- US IRA clean hydrogen production:Tax credits for low-carbon hydrogen stimulate compressor demand for LNG-to-hydrogen transition infrastructure at Gulf Coast facilities.
- Predictive maintenance convergence:Integration of vibration analytics with digital twin platforms enables subscription-based service revenue models.
Industry Challenges
- Cryogenic sealing expertise shortage:Specialized knowledge for dry gas seal maintenance at minus 162 degrees Celsius concentrates among aging technician cohorts.
- Legacy control system integration:Retrofitting variable speed drives onto fixed-speed compressor trains from prior decades requires custom engineering and extended commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Compressor Market |
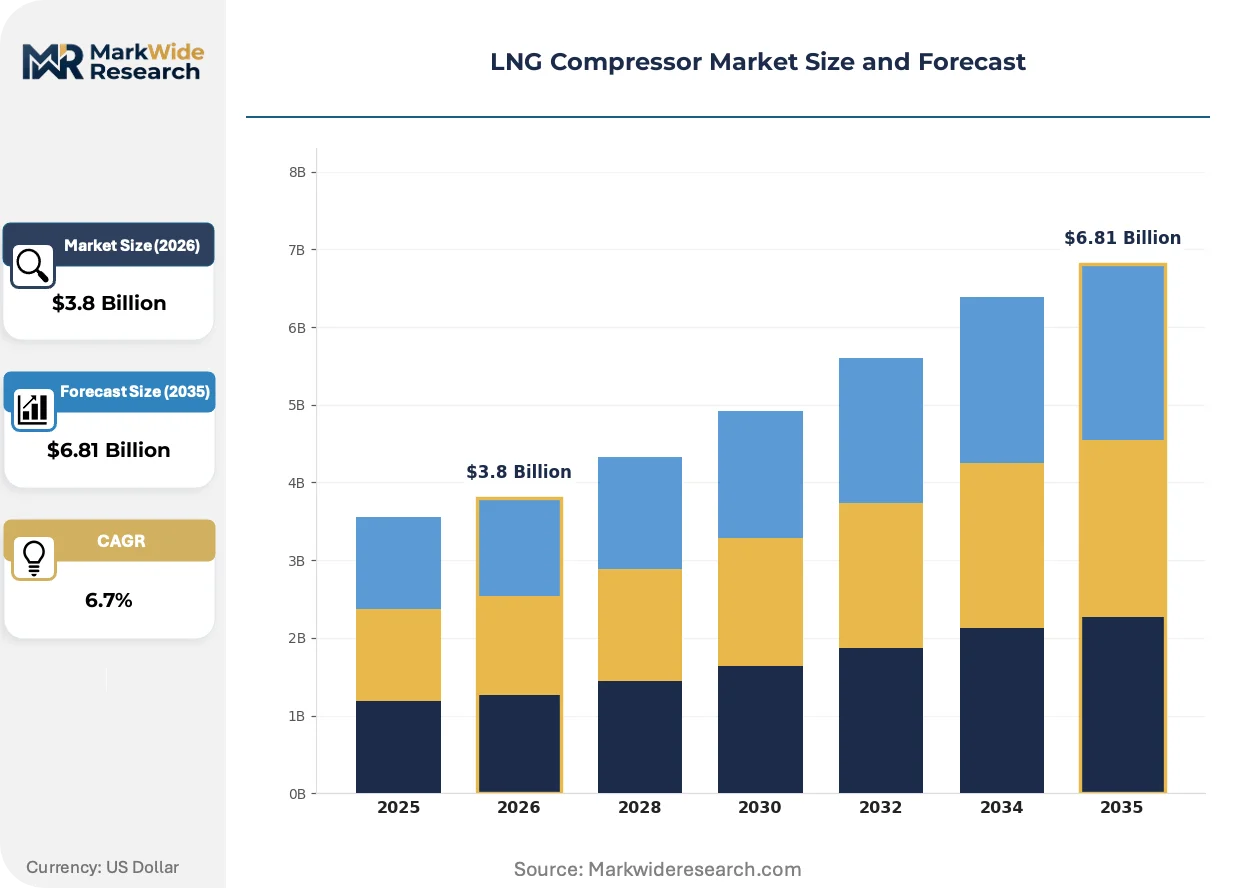
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating Compressors, Screw Compressors, Centrifugal Compressors, Diaphragm Compressors Technology: Single-Stage, Multi-Stage, Cryogenic, Hybrid Application: Liquefaction, Regasification, Transportation, Storage End User: Power Plants, Industrial, Commercial, Shipping |
| Companies Covered | Atlas Copco, Baker Hughes, Cameron, Emerson Electric, Cryostar, Siemens, Mitsubishi Heavy Industries, Kobelco, GE Oil & Gas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Compressor Market Strategic Shifts
Electrification of drive systems, refrigerant chemistry transformation, and procurement model restructuring are converging to redefine compressor specification and vendor relationships across liquefaction value chains.
High-speed direct-drive electric motors coupled with variable frequency drives are electrifying the traditional gas turbine-compressor pairing that dominated baseload liquefaction for decades. Train operators in Australia and the United States are piloting all-electric configurations to eliminate combustion-related methane leakage and reduce refrigerant charge volumes. This architecture compresses maintenance intervals while enabling grid-responsive load management.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is forcing compressor cooling circuit redesigns across European terminals. Equipment vendors are qualifying natural refrigerant alternatives and low-global-warming-potential synthetic blends for bearing and seal temperature management. Liquefaction projects in the Netherlands and Germany now specify F-Gas-compliant cooling systems as bid prerequisites.
Aftermarket service unbundling is fragmenting the traditional bundled maintenance model that tied operators to original equipment vendors for decades. Third-party specialist firms in Texas and Louisiana now offer independent overhaul services with performance guarantees, pressuring incumbent pricing structures. Floating LNG operators are driving this shift, seeking operational flexibility absent long-term geographic commitments to vendor service networks.
LNG Compressor Market Segmentation
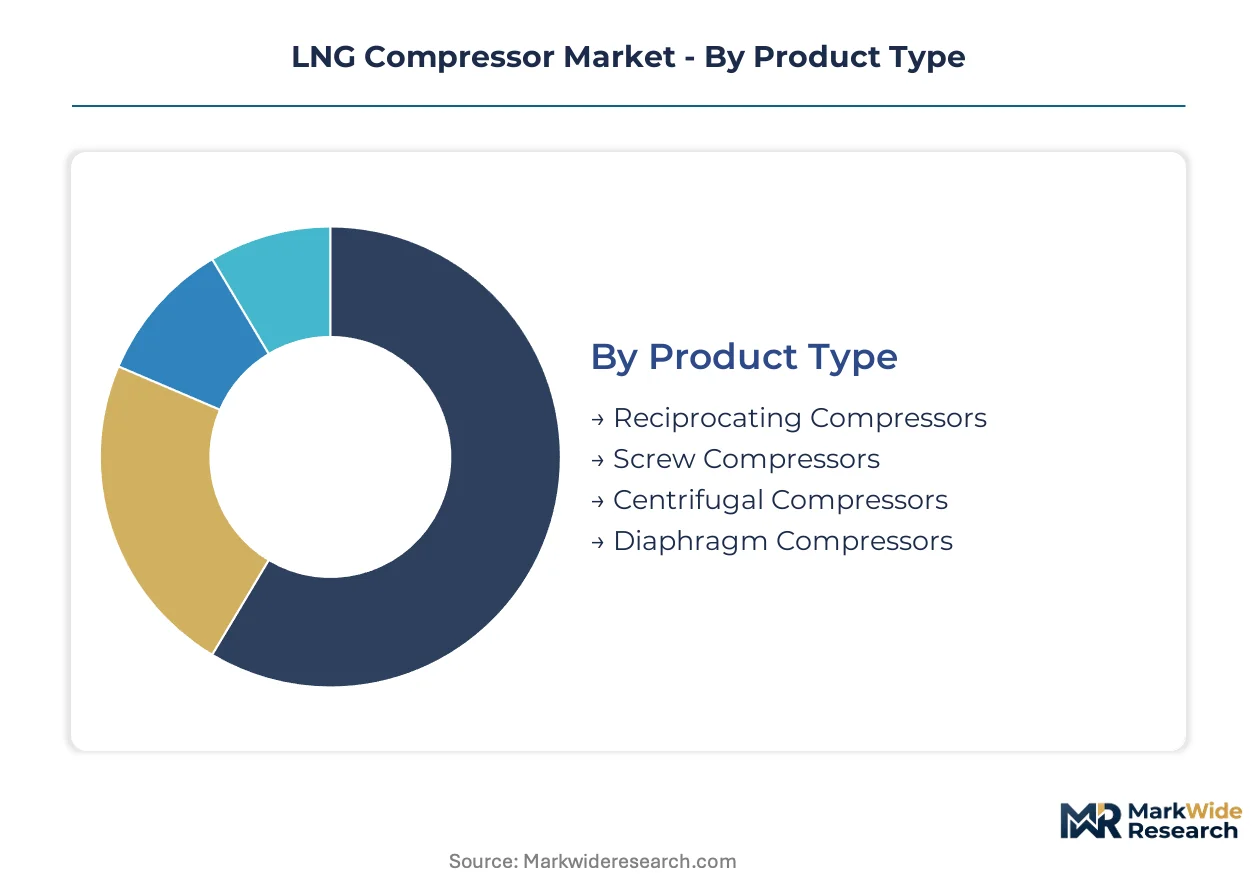
Segmentation in the LNG compressor market determines procurement pathways, certification burdens, and vendor selection criteria. Compressor specification varies dramatically across liquefaction scale, refrigerant chemistry, and marine versus terrestrial deployment contexts.
Product Type:
API 617 certification governs centrifugal and reciprocating designs for large-frame liquefaction, while screw and diaphragm compressors face less stringent but more fragmented approval landscapes across marine and industrial regulators.
- Centrifugal Compressors:Continuous-flow impeller designs handle inlet volumes exceeding 500,000 cubic meters per hour in Qatar's mega-train expansions. Demand concentrates in baseload liquefaction facilities across Qatar, Australia, and the United States where thermal efficiency and extended maintenance intervals outweigh capital intensity.
- Screw Compressors:Positive-displacement rotary configurations deliver compressed gas through intermeshing helical rotors with compact footprints below 50,000 cubic meters per hour capacity. Floating LNG terminals and small-scale modular liquefaction for mining operations in Western Australia drive procurement, with marine certification requirements from classification societies adding compliance layers.
- Reciprocating Compressors:Piston-driven positive-displacement systems achieve high pressure ratios through staged compression cylinders.
- Diaphragm Compressors:Hydraulically actuated membrane designs isolate process gas from mechanical components, serving specialized high-purity and leak-sensitive applications.
Centrifugal compressors sit at the top of the volume ranking, with screw compressors climbing the fastest as modular liquefaction scales.
Technology:
Technology selection maps directly to thermal efficiency targets and methane containment obligations under evolving emission protocols.
- Multi-Stage:Sequential compression across intercooled stages reduces refrigerant charge volumes and improves coefficient of performance in large-scale trains. Qatar North Field expansion projects specify multi-stage architectures to meet carbon intensity benchmarks while maximizing throughput per train.
- Cryogenic:Sub-minus-100-degree Celsius operation demands specialized metallurgy and dry gas seal configurations for minus 162 degrees Celsius liquefaction temperatures. European terminals under EU F-Gas Regulation increasingly specify cryogenic-optimized designs to minimize refrigerant leakage and comply with phasedown mandates.
- Single-Stage:Uninterrupted compression without intercooling suits lower-capacity or lower-pressure-ratio applications.
- Hybrid:Combined driver and compression technologies integrate electric motors with traditional gas turbine configurations.
Multi-stage systems dominate installed capacity, with cryogenic configurations expanding most quickly as emission standards tighten.
Application:
Application context determines driver selection, packaging constraints, and maintenance accessibility throughout asset lifecycles.
- Liquefaction:Natural gas pressurization and cooling to minus 162 degrees Celsius represents the most compressor-intensive value chain segment. Qatar, Australia, and the United States account for the majority of new capacity, with electrification pilots in Western Australia and the US Gulf Coast reshaping driver specifications.
- Regasification:Pressurization of LNG to pipeline specifications after offshore unloading requires robust marine-environment packaging. Floating storage and regasification units off Italy, Turkey, and Brazil drive demand for compact, modular compression with rapid deployment timelines.
- Transportation:Marine and road tanker boil-off gas management demands specialized compressor packages.
- Storage:Tank pressure maintenance and vapor recovery systems serve peak-shaving and strategic reserve facilities.
Liquefaction commands the largest equipment volume, with regasification gaining share fastest as floating terminal deployment accelerates.
End User:
End-user category shapes redundancy requirements, remote monitoring specifications, and service contract structures.
- Industrial:Petrochemical feedstock, fertilizer production, and steel manufacturing facilities require reliable gas supply with backup compression capacity. Industrial complexes in Texas, Louisiana, and Rotterdam integrate LNG compressors into process steam and power cogeneration systems.
- Shipping:LNG-fueled vessel propulsion and bunkering infrastructure demands marine-certified packages with compact footprints. Singapore, Rotterdam, and Houston port authorities are expanding LNG bunkering capacity, driving screw and centrifugal compressor orders for fuel gas supply systems.
- Power Plants:Gas turbine fuel gas pressurization for combined-cycle generation.
- Commercial:Distributed energy and peak-shaving applications in urban environments.
Industrial end users represent the largest installed base, with shipping applications showing the steepest expansion trajectory as maritime decarbonization mandates take effect.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar's mega-train liquefaction expansions and Australia's electrification pilots are advancing on parallel tracks, while the United States leverages Gulf Coast infrastructure density to capture export capacity growth.
Qatar
North Field expansion projects drive procurement of high-capacity centrifugal compressors exceeding 500,000 cubic meters per hour throughput. The Qatar Energy framework prioritizes carbon intensity benchmarks in equipment specifications. Ras Laffan Industrial City concentrates mega-train construction activity with multiple liquefaction trains under simultaneous development.
United States
Gulf Coast LNG export terminals in Texas and Louisiana are electrifying compressor trains to eliminate combustion-related methane leakage. EPA New Source Performance Standards compel seal upgrades and leak detection protocols at liquefaction facilities. The Port Arthur and Lake Charles industrial clusters host the densest concentration of new capacity additions under construction.
Australia
Western Australia mining operations and offshore liquefaction trains are piloting all-electric compressor configurations with variable frequency drives. The country's national energy regulator integrates methane containment obligations into facility licensing conditions. The Pilbara region and Browse Basin anchor both baseload liquefaction and small-scale modular deployments for remote resource extraction.
Germany
EU F-Gas Regulation mandates are forcing cooling circuit redesigns across import terminal infrastructure at Wilhelmshaven and Brunsbüttel. ECHA compliance requirements for refrigerant phase-down reshape procurement specifications for regasification compressor packages. The northern coastal corridor is expanding floating storage and regasification capacity with F-Gas-compliant equipment bids.
Japan
METI incorporates LNG infrastructure resilience into national energy security planning, influencing compressor redundancy specifications at import terminals. The country's industrial standards body mandates enhanced seismic resilience in coastal liquefaction and regasification equipment. Tokyo Bay and Osaka Bay industrial zones concentrate strategic reserve and peak-shaving facility upgrades.
LNG Compressor Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with full-system vendors commanding liquefaction train procurement while component specialists capture modular and aftermarket niches. The vendor base concentrates among industrial conglomerates with integrated rotating machinery portfolios and cryogenic engineering capabilities. Three archetypes dominate: full-train system integrators, component specialists with marine certification, and aftermarket service unbundlers. Competitive dynamics center on electrification technology licensing and long-term service contract capture.
Among diversified industrial conglomerates, Siemens and Mitsubishi Heavy Industries occupy positions exemplifying the full-system integrator archetype, anchoring procurement relationships through bundled compression and power generation offerings. Baker Hughes represents the technology-licensing vector, with digital platform integration reshaping how vendors capture lifetime value from installed base assets. Atlas Copco sits within the component specialist tier, with compressed air and gas handling expertise translating into modular package opportunities.
| Leading Market Players |
|---|
| Atlas Copco |
| Baker Hughes |
| Cameron |
| Emerson Electric |
| Cryostar |
| Siemens |
| Mitsubishi Heavy Industries |
| Kobelco |
| GE Oil & Gas |
| Others |
Value Chain & Pricing Dynamics
Cryogenic sealing specialists concentrated in Houston, Texas and Rotterdam command wage premiums that widen spreads between premium-tier OEM service contracts and third-party overhaul pricing. Labor-cost differentials between these technician hubs and emerging service centers in Singapore and Dubai directly feed into tiered aftermarket pricing structures across liquefaction and regasification assets.
Pricing Analysis
Capacity additions in Qatar are reshaping price floors for high-throughput centrifugal trains as procurement volume concentrates among mega-train developers. Three-tier pricing structure across API 617-certified premium packages, standard industrial configurations, and economy modular units stratifies by certification grade and after-sales bundling intensity. Cost compression in economy-tier screw compressor packages is intensifying because independent overhaul specialists in Texas and Louisiana now guarantee performance without OEM captive service agreements. Floating LNG operators show highest price sensitivity due to project financing constraints, while Qatar Energy and similar national champions prioritize thermal efficiency guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Houston, Rotterdam, and Singapore anchor hub-and-spoke patterns for spare impellers, dry gas seal kits, and cryogenic bearings. Manufacturing concentrates in Germany, Japan, and the United States for precision-machined impellers and specialized castings. Nickel-based superalloys for cryogenic service draw from limited specialty alloy producers in the United States and Germany. Single-source vulnerability around Inconel 718 and similar aerospace-grade materials creates exposure to mining output fluctuations from Indonesian nickel operations. Distribution runs through OEM-authorized service depots for warranty-critical components, with independent channels capturing non-critical consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LNG compressor market functions as a regulatory compounder where EU F-Gas Regulation phasedown mandates and EPA methane performance standards continuously refresh equipment replacement cycles and upgrade demand.
For Market Incumbents: Deploy digital twin diagnostics as the anchor lever for long-term service contract capture. Siemens and Baker Hughes exemplify bundling predictive maintenance subscriptions with compression train procurement to lock out independent overhaul challengers. Backward integration into nickel-based superalloy recycling secures input cost stability against volatile specialty alloy markets. Capacity additions in Qatar and Australia create service network density requirements that favor incumbents with established technician training pipelines. For New Entrants and Emerging Players: Begin with small-scale modular LNG applications in Western Australian mining operations and Singapore bunkering infrastructure where OEM service networks remain thin. Marine-certified screw compressor packages below 50,000 cubic meters per hour offer the most penetrable white space, with classification society approvals serving as the primary barrier rather than manufacturing scale. Target independent overhaul services for floating LNG operators seeking operational flexibility absent geographic vendor commitments. For Investors and Strategic Acquirers: Valuations sit cheapest among component specialists with marine certification but limited liquefaction train integration capabilities. Long-term viability hinges on electrification technology licensing positions as motor-driven architectures displace gas turbine-compressor pairings. Acquisition targets should display cryogenic engineering depth and API 617 compliance testing infrastructure. The signal to watch is F-Gas Regulation compliance certification velocity among European terminal operators as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Technology Licensing | Motor-driven compressor trains at Australian and US Gulf Coast facilities eliminate methane leakage from combustion drivers. |
| Long-term Service Agreement Bundling | Siemens anchors procurement relationships by wrapping digital twin diagnostics with multi-year predictive maintenance subscriptions. |
| Marine Certification Investment | Classification society approvals from DNV and ABS unlock floating LNG and bunkering infrastructure opportunities. |
| Specialty Alloy Recycling Integration | In-house superalloy reclamation reduces exposure to nickel price volatility and Indonesian mining output fluctuations. |
| F-Gas Compliance Certification | Natural refrigerant qualification for cooling circuits secures bid eligibility at EU terminals under phasedown mandates. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct segment-level demand estimates. Primary fieldwork engaged liquefaction project developers, EPC contractors, compressor OEM procurement teams, and aftermarket service directors across Qatar, Australia, the United States, and Germany. Secondary validation drew from EPA New Source Performance Standards filings, EU F-Gas Regulation implementation reports, API 617 certification databases, and FERC LNG export facility construction tracking. Bottom-up project pipeline enumeration and top-down macro energy demand modeling were cross-referenced to anchor volume assumptions.
Historical reference periods spanning installed base composition and replacement cycle timing informed projection anchor points across the modeling period. Segmentation dimensions modeled include compressor product type, technology configuration, application context, and end-user category, with regional regulatory framework clusters as an additional cross-cutting dimension. CAGRs were derived from capacity addition schedules and emission-driven upgrade cycles. Industry-specific forecast inputs incorporated methane containment technology adoption curves and electrification infrastructure buildout timelines.
Several conditions sit outside the modeled scope, including geopolitical disruption to Qatari expansion timelines, abrupt refrigerant chemistry bans beyond current EU phasedown schedules, and breakthrough solid-state liquefaction technologies. Forecasts reflect documented assumptions regarding carbon intensity benchmark evolution and technician workforce availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Industrial Air Compressor Market
Compressors
Centrifugal Air Compressor Market
Compressors
Air Compressor Market
Compressors
Middle East and Africa Booster Compressor Market
Compressors
Russia Reciprocating Compressor Market
Compressors
Liquid Ring Compressors Market
Compressors
Integrally Geared Centrifugal Compressor Market
Compressors
Process Gas Compressors Market
Compressors
PAG Compressor Oil Market
Compressors
Oil and Gas Industry Gas Compressor Market
Compressors
Compressed Air Filtration and Dryer System Market
Compressors
Rental Air Compressors Market
Compressors
North America Centrifugal Compressor Market
Compressors
North America Air Compressor Market
Compressors
Oil-Free Air Compressor Market
Compressors
Positive-Displacement Hydrogen Compressor Market