
 Automotive Compressors Market | 2026-2036
Automotive Compressors Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Compressors Market Analytics
A capital-intensity divergence between integrated manufacturers and component assemblers is rotating competitive dynamics across the supply base. Denso Corporation leverages in-house semiconductor and motor production to control cost architecture for electric compressor modules. Hanon Systems sustains geographic dominance through dedicated climate-system plants in Eastern Europe and Southeast Asia. Valeo differentiates via scroll compressor expertise for hybrid thermal management platforms.
An automotive compressor is a mechanical device that pressurizes refrigerant or air through displacement or dynamic action, typically operating at pressures between 15 and 35 bar in passenger vehicle air conditioning circuits, to enable heat transfer, engine cooling, or forced induction. Scroll compressors lead technology adoption for electric vehicles due to superior efficiency at variable speeds and reduced noise signatures compared to reciprocating alternatives. OEM end users capture the dominant value pool as vehicle electrification mandates deepen factory-installed thermal system complexity. Aftermarket providers occupy a mature, price-sensitive channel concentrated on reciprocating unit replacements for internal combustion fleets.
The EPA regulates refrigerant leakage rates and SNAP-approved substances under Section 612 of the Clean Air Act, directly constraining compressor design chemistry and sealing standards. The EU F-Gas Regulation and REACH framework impose phasedown quotas on hydrofluorocarbon content, compelling manufacturers to qualify CO2 and low-GWP alternative systems. China's GB standards and MIIT new-energy vehicle catalog requirements enforce domestic compressor efficiency benchmarks that shape market access. Stakeholders must monitor refrigerant chemistry transitions and powertrain electrification timelines to align R&D portfolios with shifting compliance thresholds.
Market Dynamics
Powertrain electrification is fragmenting compressor architectures, forcing suppliers to abandon unified platforms and develop parallel electric and thermal management systems that serve incompatible voltage ranges and refrigerant chemistries.
Growth Catalysts
- EU F-Gas Regulation Phase-down:Mandated hydrofluorocarbon quotas are compelling OEMs to qualify CO2 transcritical systems, expanding procurement of high-pressure compressor designs rated above 100 bar.
- MIIT New-Energy Vehicle Catalog:China's efficiency benchmarks for factory-installed thermal systems are accelerating domestic compressor qualification cycles for electric vehicle platforms.
- Scroll compressor adoption:Variable-speed electric compressors are displacing fixed-displacement reciprocating units in hybrid thermal management due to superior part-load efficiency.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and dysprosium price swings constrain motor cost architecture for electric compressor modules, compressing assembler margins.
- Semiconductor supply concentration:Power electronics for inverter-driven compressors depend on fabrication capacity concentrated in Taiwan and South Korea, exposing production schedules to geographic risk.
- REACH chemical compliance:The EU framework's substance restrictions are extending qualification timelines for sealing materials and lubricants, delaying platform launches.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced automotive systems are attracting compressor module assembly investment to serve domestic electric vehicle manufacturing.
- Thermal battery conditioning:Integration of compressors into battery thermal management circuits opens incremental content per vehicle beyond cabin air conditioning.
- Heat pump convergence:Combining cabin heating and cooling functions through reversible refrigerant circuits is enabling single-compressor architectures that reduce system mass.
Industry Challenges
- Power electronics integration:Embedding motor drives within compressor housings requires rare cross-functional expertise spanning refrigerant thermodynamics and electromagnetic design.
- Dual refrigerant qualification:OEMs demand simultaneous validation of R-134a and R-1234yf systems, doubling test cell utilization and engineering headcount.
Report Scope
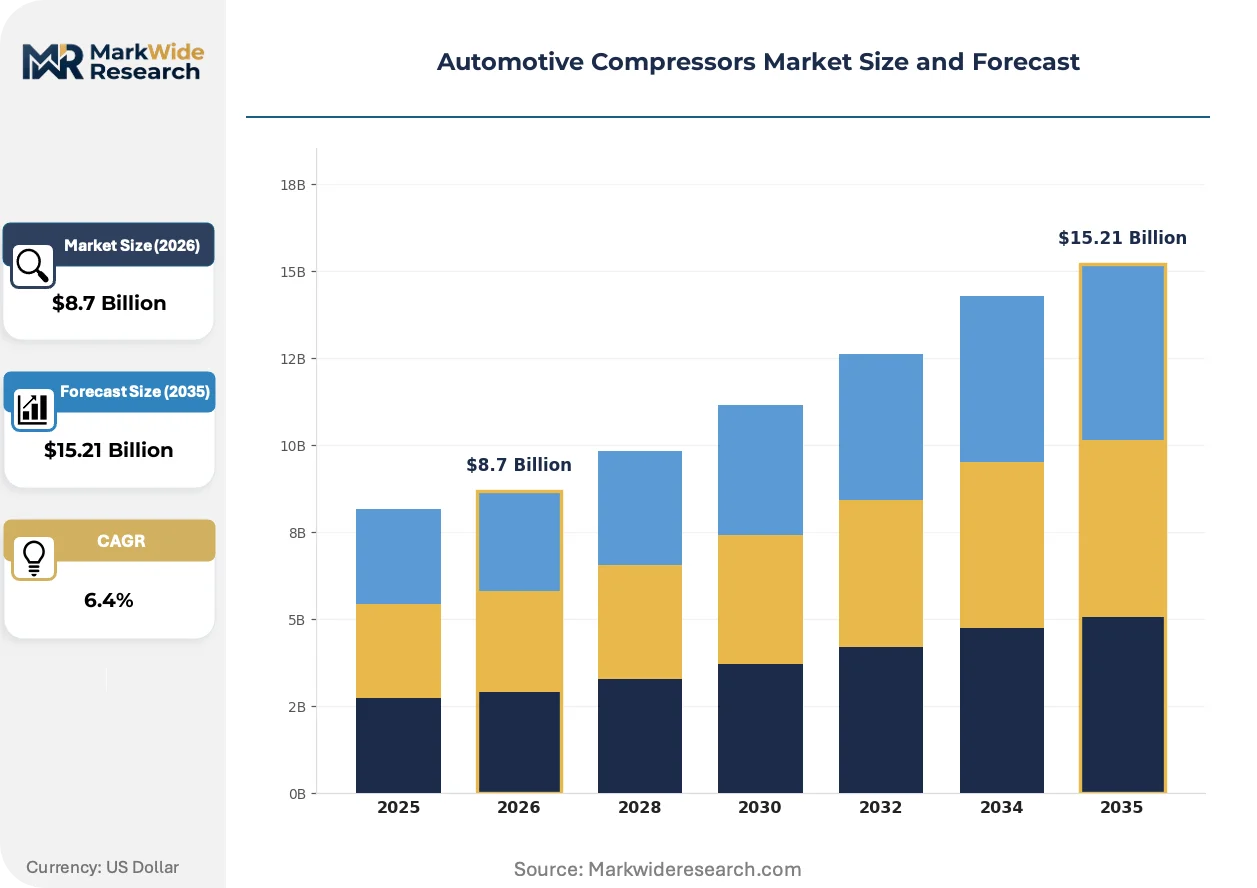
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Compressors Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Reciprocating, Scroll, Rotary, Centrifugal End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Air Conditioning, Engine Cooling, Fuel Injection, Turbocharging Power Rating: Low Power, Medium Power, High Power, Variable Power |
| Companies Covered | Denso Corporation, Hanon Systems, Valeo, Sanden Corporation, MAHLE GmbH, Toyota Industries Corporation, Mitsubishi Heavy Industries, Bosch, BorgWarner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Compressors Market Evolving Landscape
Refrigerant chemistry transitions and electrification mandates are collapsing legacy platform commonality, compelling suppliers to maintain parallel development tracks for incompatible thermal system architectures.
Scroll compressor technology is decomposing the historical dominance of reciprocating designs in passenger vehicle applications. Electric vehicle manufacturers are adopting variable-speed scroll units at accelerated qualification cycles for hybrid and battery-electric platforms. This shift is decomposing the aftermarket replacement pipeline for conventional compressor architectures as factory-installed scroll units extend service intervals beyond vehicle ownership horizons.
EPA SNAP approval requirements under Section 612 of the Clean Air Act are constraining refrigerant selection for compressor sealing compatibility. The regulatory framework mandates leakage rate thresholds and approved substance lists that disqualify legacy lubricant chemistries. Compressor manufacturers serving the United States market are responding with accelerated qualification of HFO-compatible elastomer compounds and revised port geometries.
Fleet procurement centralization among electric vehicle specialists is compressing supplier negotiation cycles and unbundling traditional tiered supply arrangements. Direct sourcing contracts between OEM thermal system divisions and compressor module integrators are displacing distributor-mediated procurement channels. This restructuring is most visible in Germany, where established climate-system suppliers are establishing captive engineering offices adjacent to OEM development centers.
Automotive Compressors Market Segmentation
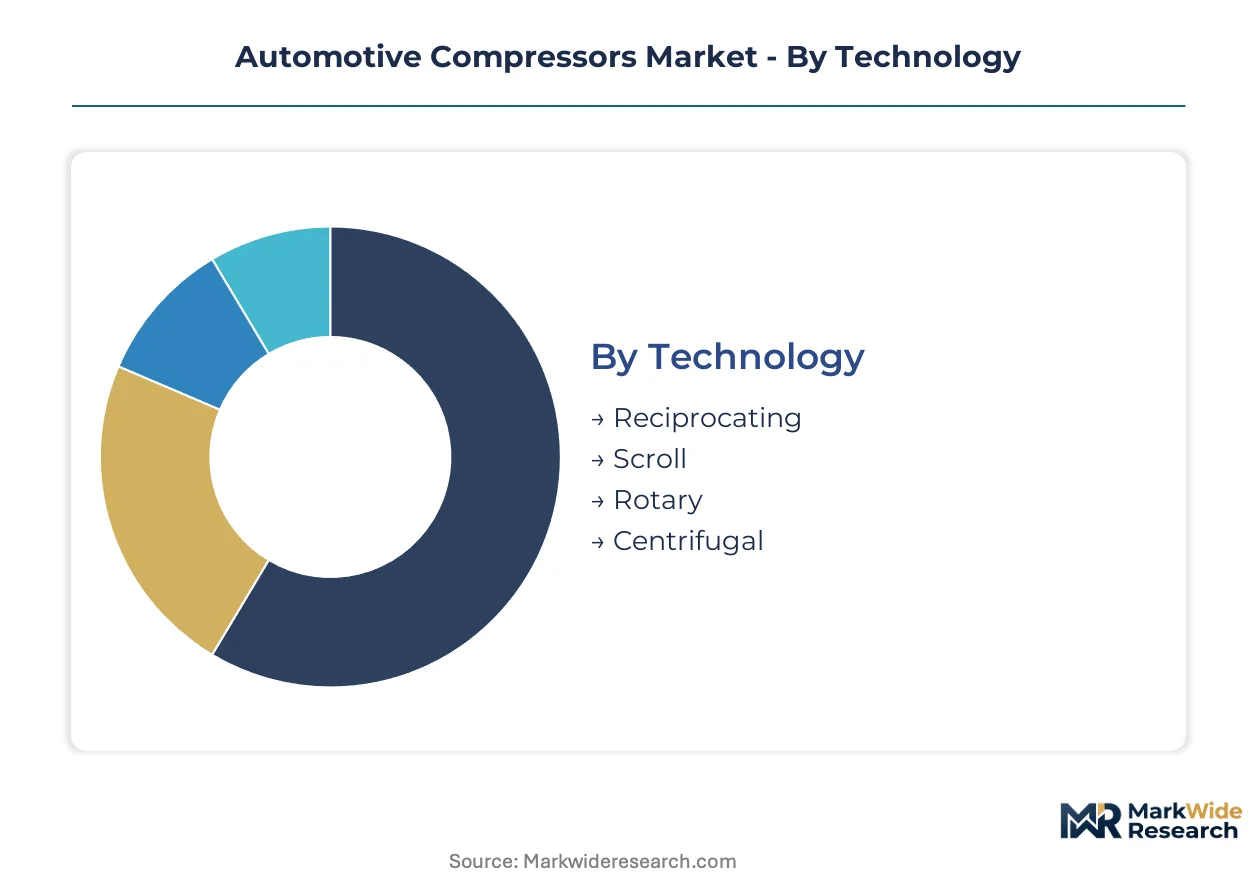
Technology and end-user fragmentation in automotive compressors creates distinct margin architectures that reward specialized capabilities over scale. Suppliers must align R&D investments with electrification trajectories and refrigerant transitions rather than pursuing coverage across all segment combinations.
Technology:
Margin pools concentrate in electric-compatible architectures as thermal management complexity rises with vehicle electrification.
- Scroll:Variable-speed scroll compressors operate with superior part-load efficiency and reduced noise signatures compared to reciprocating alternatives. Demand concentrates among electric vehicle manufacturers in Germany and China, where MIIT efficiency benchmarks and EU F-Gas Regulation phase-downs accelerate qualification cycles for high-pressure CO2-compatible designs.
- Reciprocating:These compressors utilize piston-cylinder displacement mechanisms and dominate legacy internal combustion air conditioning circuits. Aftermarket providers in the United States capture residual value as EPA SNAP requirements under Section 612 of the Clean Air Act constrain refrigerant selection and extend replacement intervals for sealed systems.
- Rotary:Vane-based rotary compressors serve compact vehicle segments where packaging constraints prioritize cylindrical form factors over efficiency optimization.
- Centrifugal:Dynamic compression principles suit heavy-duty commercial applications requiring continuous high-volume refrigerant circulation at stable operating points.
The dominant share belongs to reciprocating designs, while scroll technology is closing the gap fastest.
End User:
Volume concentration varies sharply between factory-installed systems and replacement channels, with electrification collapsing commonality between them.
- OEMs:Original equipment manufacturers specify compressor modules as integrated thermal system components, capturing value through direct sourcing contracts that bypass traditional tiered distribution. German and Chinese electric vehicle specialists centralize procurement decisions adjacent to development centers.
- Tier-1 Suppliers:These climate-system integrators assemble compressor modules from subcomponents, facing margin compression from rare-earth magnet cost volatility and semiconductor supply concentration in Taiwan and South Korea.
- Vehicle Assemblers:Final assembly operations source pre-validated compressor modules for platform-specific integration, with India's PLI scheme for auto components attracting investment to serve domestic electric vehicle manufacturing.
- Aftermarket Providers:Replacement channel operators focus on reciprocating unit availability for internal combustion fleets, with scroll compressor adoption decomposing the historical replacement pipeline as factory-installed units extend service intervals.
OEMs command the largest value pool, though Tier-1 Suppliers are expanding their share through module integration capabilities.
Application:
Content-per-vehicle expansion is most pronounced in thermal management functions beyond traditional cabin comfort.
- Air Conditioning:Cabin cooling remains the primary application, with reversible heat pump circuits combining heating and cooling functions to reduce system mass in electric vehicle platforms.
- Engine Cooling:Thermal management of battery packs and power electronics is displacing legacy engine-focused cooling architectures, creating incremental compressor content per vehicle.
- Fuel Injection:Compressed natural gas and hydrogen fuel systems require specialized compressor designs for high-pressure fuel delivery.
- Turbocharging:Forced induction systems utilize compressor stages to increase intake air density, though electrification is reducing penetration in passenger vehicle segments.
Air Conditioning retains the dominant position, while Engine Cooling applications are climbing the fastest as battery thermal management becomes standard.
Power Rating:
Architectural divergence between electric and thermal management systems is fragmenting power requirements across incompatible voltage ranges.
- Variable Power:Inverter-driven compressors modulate motor speed to match thermal load, delivering superior efficiency across operating conditions. Integration of motor drives within compressor housings requires cross-functional expertise spanning refrigerant thermodynamics and electromagnetic design.
- High Power:CO2 transcritical systems rated above 100 bar serve EU F-Gas Regulation compliance requirements, with OEMs qualifying high-pressure designs for next-generation thermal platforms.
- Medium Power:Fixed-displacement architectures serve hybrid platforms requiring compatibility with both electric and belt-driven operation modes.
- Low Power:Compact compressors address auxiliary cooling needs in commercial vehicle sleeper cabs and specialty vehicle applications.
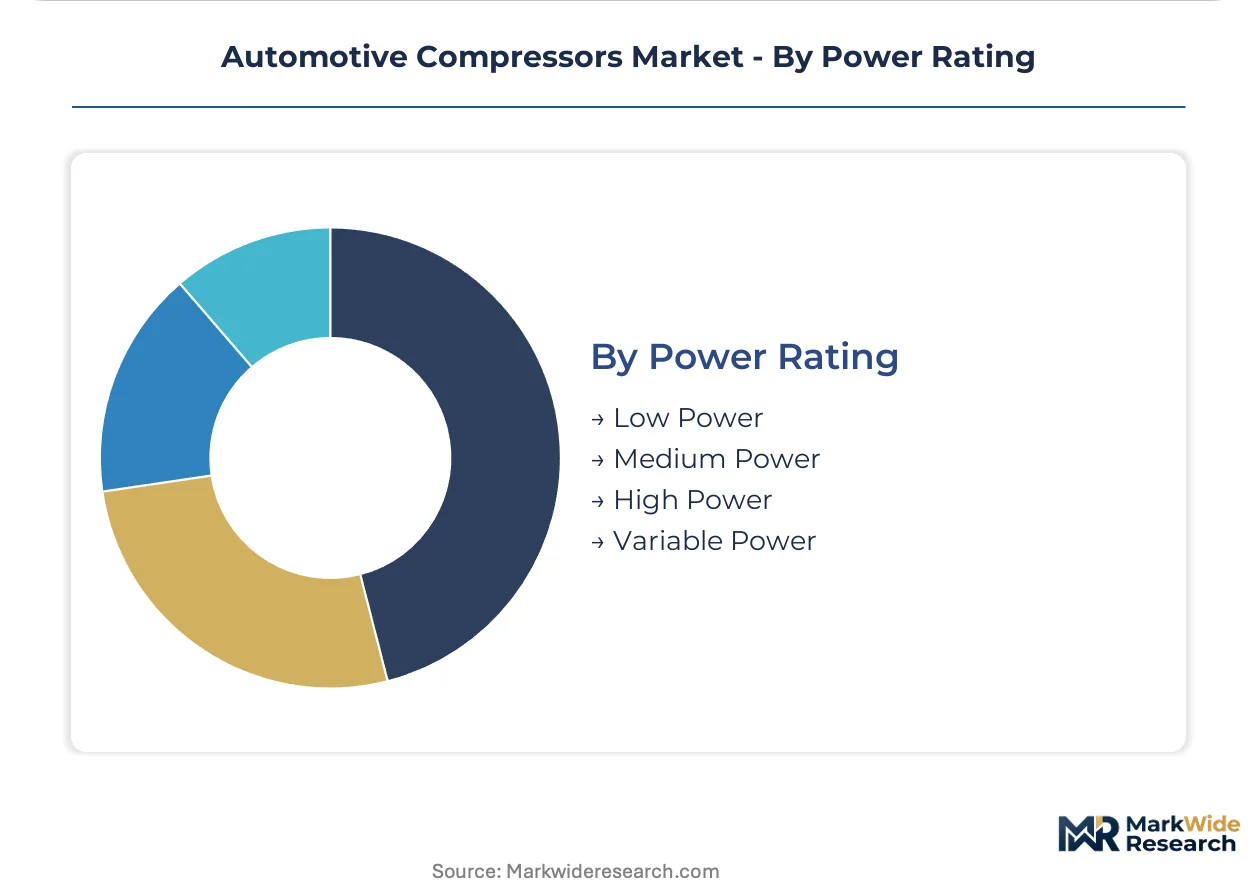
Variable Power systems hold the dominant share, with High Power designs gaining share fastest under refrigerant chemistry transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German engineering centers while procurement leverage shifts toward Chinese manufacturing hubs. Compressor qualification cycles diverge sharply between EU F-Gas compliance deadlines and MIIT efficiency mandates. Regional regulatory fragmentation is fragmenting platform commonality across major supply corridors.
Germany
OEM thermal system divisions centralize procurement decisions adjacent to development centers in Stuttgart and Munich. The EU F-Gas Regulation mandates hydrofluorocarbon phase-down quotas that accelerate CO2 transcritical system qualification. Climate-system suppliers establish captive engineering offices in Baden-Württemberg to serve electric vehicle platform development.
China
Domestic electric vehicle manufacturing scales compressor demand across multiple voltage architectures and refrigerant chemistries. MIIT new-energy vehicle catalog requirements enforce factory-installed thermal system efficiency benchmarks. Manufacturing clusters in Shanghai and Guangdong attract module assembly investment under domestic content incentives.
United States
EPA SNAP approval requirements under Section 612 of the Clean Air Act constrain sealing material selection and lubricant compatibility. Aftermarket replacement channels concentrate on reciprocating unit availability for legacy internal combustion fleets. Supplier engineering presence clusters near Detroit and Southern California OEM development centers.
Japan
Integrated compressor and motor production capabilities serve hybrid platform thermal management requirements. METI efficiency standards and JIS certification frameworks shape domestic qualification protocols. Industrial concentration in Aichi Prefecture supports captive supply relationships with major automotive groups.
India
Production-linked incentive schemes for advanced automotive components attract compressor module assembly investment. Domestic electric vehicle manufacturing expansion creates demand for localized thermal system supply. Manufacturing activity concentrates in Tamil Nadu and Maharashtra to serve emerging OEM platform requirements.
Automotive Compressors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating tiered competitive dynamics across the supply base. Integrated manufacturers with in-house semiconductor and motor production control cost architecture for electric compressor modules. Component assemblers face margin compression from rare-earth magnet volatility and semiconductor supply concentration. Strategic moves concentrate on geographic expansion through dedicated climate-system plants and portfolio diversification into battery thermal management circuits.
Within the integrated manufacturing tier, Denso Corporation and Toyota Industries Corporation exemplify archetypes combining captive component supply with module integration capabilities. Hanon Systems and Valeo occupy positions as climate-system specialists leveraging scroll compressor expertise for hybrid thermal management platforms. MAHLE GmbH and BorgWarner represent diversified automotive suppliers extending powertrain component capabilities into electrified thermal systems. Sanden Corporation and Mitsubishi Heavy Industries anchor positions in compressor-specific engineering with regional manufacturing footprints.
| Leading Market Players |
|---|
| Denso Corporation |
| Hanon Systems |
| Valeo |
| Sanden Corporation |
| MAHLE GmbH |
| Toyota Industries Corporation |
| Mitsubishi Heavy Industries |
| Bosch |
| BorgWarner |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between German OEM thermal system divisions and compressor module integrators lock in supply access and price visibility across refrigerant chemistry transitions, insulating procurement from rare-earth magnet cost volatility while constraining flexibility for platform pivots.
Pricing Analysis
The customization-premium spread separates configured-to-order electric compressor modules from standard reciprocating units, with OEM direct-sourcing contracts commanding price premiums for CO2-compatible high-pressure designs. Price differentiation rests on certification grade for EU F-Gas compliance and volume scale for Tier-1 supplier negotiations. Cost compression in standard reciprocating architectures is intensifying because aftermarket replacement demand concentrates on legacy internal combustion fleets with extended service intervals. Tier-1 suppliers exhibit highest price sensitivity due to semiconductor and magnet input volatility, while integrated manufacturers with captive component supply maintain pricing power.
Supply Chain Analysis
Inventory lead-times for power electronics stretch across fabrication capacity concentrated in Taiwan and South Korea, exposing compressor production schedules to geographic concentration risk. Manufacturing draws from rare-earth magnet supply anchored in China, semiconductor wafer output centered in East Asia, and precision-machined housings sourced from Germany and Japan. Single-source vulnerability in inverter-grade chip supply creates systemic exposure. Distribution runs through OEM thermal system divisions that bypass traditional tiered channels, with aftermarket reciprocating units flowing through specialized climate-system distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification fragments compressor architectures into incompatible voltage ranges and refrigerant chemistries, creating specialized niches for suppliers with cross-functional expertise spanning refrigerant thermodynamics and electromagnetic design.
For Market Incumbents: Shield scroll compressor margins by deepening backward integration into in-house semiconductor and motor production, countering rare-earth magnet cost volatility that compresses assembler returns. Denso Corporation's captive component supply model demonstrates how upstream control over cost architecture defends position against climate-system specialists lacking equivalent integration. Prioritize certification investment for CO2 transcritical systems ahead of EU F-Gas Regulation phase-down deadlines. For New Entrants and Emerging Players: EPA SNAP fast-track approval for HFO-compatible sealing compounds opens white-space entry in United States aftermarket channels constrained by refrigerant chemistry transitions. India's PLI scheme for auto components offers the most penetrable geography, with Tamil Nadu and Maharashtra manufacturing clusters attracting module assembly investment to serve domestic electric vehicle platform requirements. Pursue direct sourcing contracts with emerging OEM thermal system divisions bypassing established distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers with captive semiconductor and motor production capabilities, as these archetypes control cost architecture for electric compressor modules across the analysis window. Acquisition targets should demonstrate scroll compressor expertise for hybrid thermal management platforms and established engineering presence adjacent to German OEM development centers. Monitor MIIT new-energy vehicle catalog expansion as inflection indicator for Chinese domestic demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Transcritical System Qualification | EU F-Gas Regulation phase-down mandates hydrofluorocarbon quota compliance, expanding procurement of high-pressure compressor designs. |
| Rare-Earth Magnet Supply Agreement | Neodymium and dysprosium price volatility constrains motor cost architecture, requiring locked-in material sourcing for margin protection. |
| Semiconductor Fabrication Partnership | Taiwan and South Korea concentration in power electronics exposes production schedules, necessitating geographic diversification. |
| Battery Thermal Management Integration | Compressors serving battery conditioning circuits open incremental content per vehicle beyond cabin air conditioning applications. |
| Captive Engineering Office Expansion | Proximity to Stuttgart and Munich OEM development centers accelerates qualification cycles for electric vehicle platform procurement. |
Research Methodology
Desk research of regulatory filings from EPA, ECHA, and MIIT preceded structured interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and climate-system R&D directors. Secondary validation drew from vehicle production databases, customs trade records for compressor module flows, SEC filings of integrated manufacturers, and EU F-Gas Regulation implementation reports. Bottom-up segment sizing triangulated against top-down market reconstruction across technology, end-user, application, and power rating dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation layer. The analytical framework models propulsion architecture transitions, refrigerant chemistry shifts, and regional regulatory compliance deadlines as primary forecast inputs. CAGRs derive from fitted growth curves calibrated to disclosed OEM platform timelines and supplier capacity announcements, with cross-segment consistency checks against vehicle electrification penetration trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained EU F-Gas phase-down enforcement, MIIT efficiency benchmark maintenance, and semiconductor supply concentration persistence; material deviation in any base assumption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Chlorine Compressors Market
Compressors
PAG Compressor Oil Market
Compressors
North America Air Compressor Market
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Portable Compressor Market
Compressors
Oil-Free Air Compressor Market
Compressors
Air and Gas Compressor Market
Compressors
Gas Compressors Market
Compressors
Rotary Air Compressor Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Reciprocating Compressor Market
Compressors
Tandem Piston Compressors Market
Compressors
High Speed Blowers Market
Compressors
Compressor Wheel Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Positive-Displacement Hydrogen Compressor Market