
 Root Blower Market | 2026-2036
Root Blower Market Size, Share, and Industry Trends Forecast 2026-2036
Root Blower Market Analytics
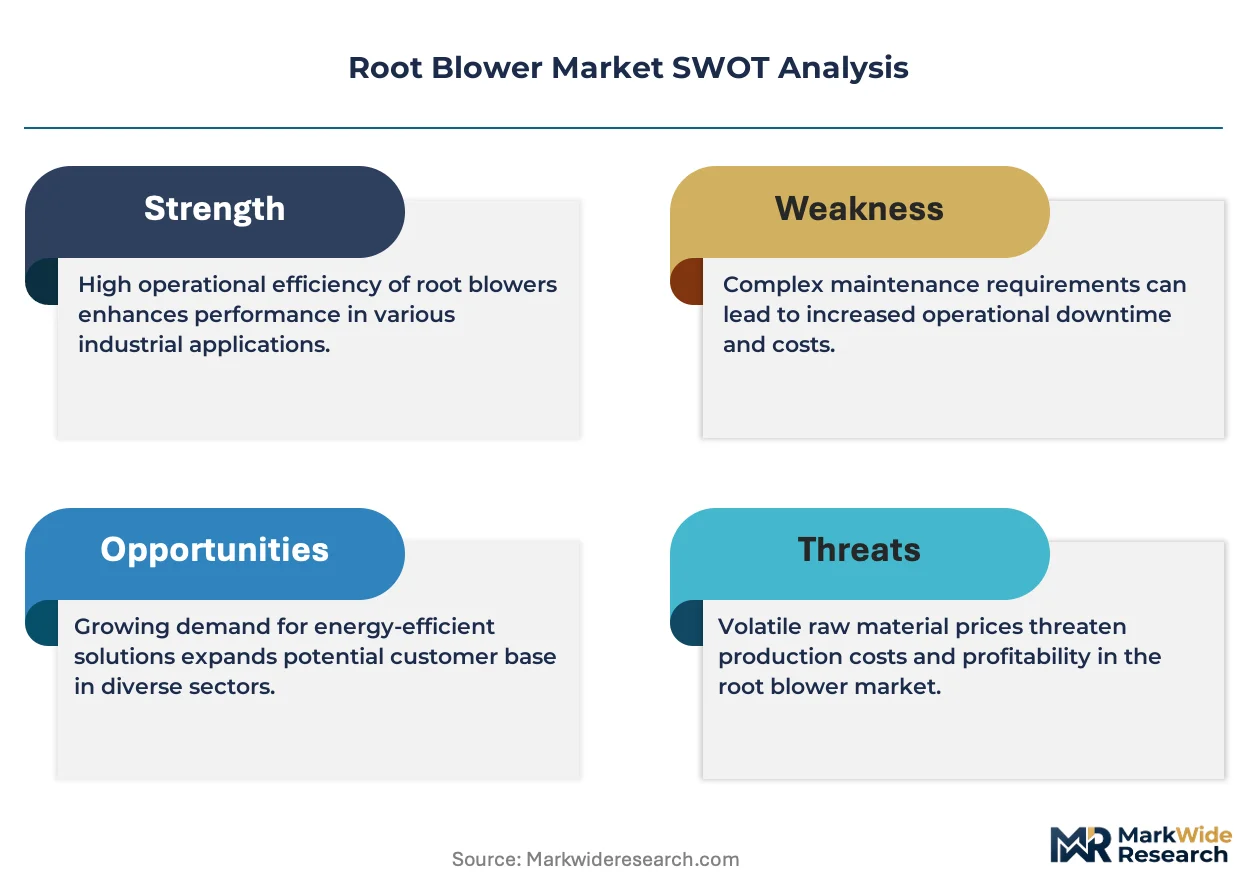
Aftermarket service channels for industrial blowers is reshaping how capital equipment reaches end users. Ingersoll Rand leverages its global compressor service network to cross-sell blower maintenance contracts. Atlas Copco sustains premium positioning through predictive diagnostics bundled with rotary lobe units. Howden competes on heavy-duty engineering for chemical and power generation clients.
A root blower is a positive displacement rotary machine using two meshed lobes to move fixed volumes of air or gas against moderate pressure differentials, typically achieving pressure ratios up to 2.0 bar and flow rates from 10 to 15,000 cubic meters per hour. Its primary industrial purpose centers on continuous aeration, pneumatic conveying, and vacuum applications where oil-free, pulsation-tolerant gas handling remains essential. Positive displacement configurations anchor current revenue given their reliability in wastewater aeration, while twin lobe designs capture expanding share in pneumatic conveying for food processing. Electric drive technology dominates new installations as facilities phase out hydraulic systems for energy efficiency compliance.
EPA effluent guidelines in the United States mandate upgraded aeration intensity at municipal treatment plants, directly stimulating blower replacement cycles. Ecodesign requirements under EU regulations and China's GB energy efficiency standards for rotating machinery constrain import access for non-compliant equipment. Stakeholders must monitor how regional efficiency benchmarks and carbon border adjustments recalibrate sourcing decisions for lobe materials and drive systems.
Market Dynamics
Electric drive retrofits are displacing hydraulic blower systems across municipal wastewater infrastructure, forcing incumbent manufacturers to reengineer lobe geometries for variable-speed compatibility while service networks absorb the technical transition burden.
Growth Catalysts
- EU Green Deal aeration mandates:Germany's wastewater treatment plants must expand oxygen transfer capacity by specified deadlines, triggering equipment replacement cycles for aging positive displacement blowers.
- Twin lobe pneumatic conveying:China's chemical processing corridors in Jiangsu and Shandong provinces are standardizing oil-free gas handling for food-grade powder transport applications.
- GB energy efficiency standards:China's national rotating machinery efficiency benchmarks are filtering import access and accelerating domestic blower manufacturer certification programs.
Market Restraints
- Specialized alloy supply concentration:Precision-cast lobe materials depend on concentrated European and Japanese foundry capacity, exposing procurement timelines to single-source bottlenecks.
- High-precision machining capex:Twin lobe profile grinding equipment requires substantial capital deployment, elevating breakeven thresholds for regional manufacturers.
- Magnetic bearing substitution:Oil-free turbo blower technology is capturing low-pressure aeration applications previously served by rotary lobe designs.
Strategic Opportunities
- India's Smart Cities Mission:Urban wastewater infrastructure expansion in Maharashtra and Gujarat states is generating tender volume for packaged aeration systems.
- Predictive diagnostics convergence:Vibration monitoring algorithms fused with rotary lobe blower architectures are enabling condition-based maintenance contracts.
- Carbon border adjustment mechanism:EU CBAM compliance documentation is creating service revenue streams for equipment lifecycle carbon accounting.
Industry Challenges
- Rotordynamics specialist scarcity:Lobe profile optimization and bearing configuration engineering require niche expertise concentrated among aging practitioner cohorts.
- Legacy control system integration:Variable frequency drive retrofits must interface with existing SCADA architectures without triggering full automation replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Root Blower Market |
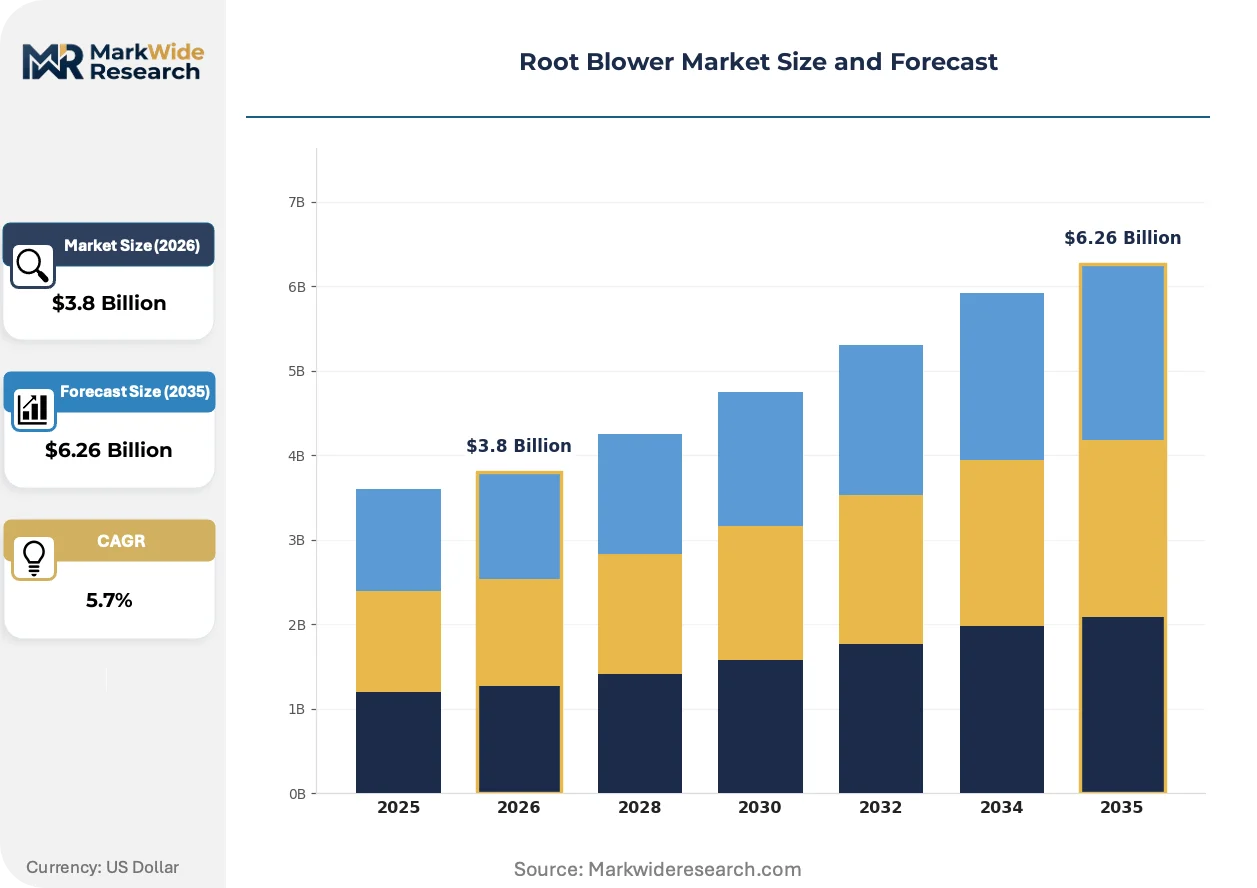
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Displacement, Rotary Lobes, Screw Type, Twin Lobe End User: Waste Water Treatment, Pneumatic Conveying, Food Processing, Chemical Industry Application: Aeration, Vacuum Generation, Dust Control, Odor Control Technology: Electric, Hydraulic, Pneumatic, Magnetic |
| Companies Covered | Ingersoll Rand, Atlas Copco, Howden, AERZEN, Baker Hughes, Tuthill Corporation, Dresser, Kaeser, Taiko, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Root Blower Market Evolving Landscape
Digital instrumentation and material science advances are compressing maintenance intervals while expanding the pressure-flow envelope of positive displacement architectures beyond traditional rotary lobe boundaries.
Permanent magnet synchronous motor technology is hybridizing with twin lobe blower mechanical stages, enabling direct-drive configurations that eliminate gearbox maintenance and reduce energy consumption by fifteen to twenty percent in variable-load aeration duty. Municipal treatment operators in the Netherlands and Denmark are piloting these integrated units for dissolved oxygen control loops. The convergence is compressing the addressable market for conventional induction motor plus gearbox packages.
EPA effluent limitation guidelines are tightening total nitrogen discharge thresholds for municipal treatment facilities, forcing aeration intensity upgrades that favor higher-pressure blower configurations. The regulatory pressure is accelerating replacement cycles for equipment installed during the 1990s infrastructure investment wave. Packaged blower skids with integrated dissolved oxygen control are capturing specification preference in US municipal procurement.
Service contract unbundling is fragmenting the traditional capital-plus-maintenance procurement model, with end users separating equipment purchase from aftermarket support decisions. Chemical processing operators in Germany's Ruhr industrial cluster are soliciting standalone predictive maintenance subscriptions from third-party diagnostics providers. The behavioral shift is eroding captive service revenue for original equipment manufacturers.
Root Blower Market Segmentation
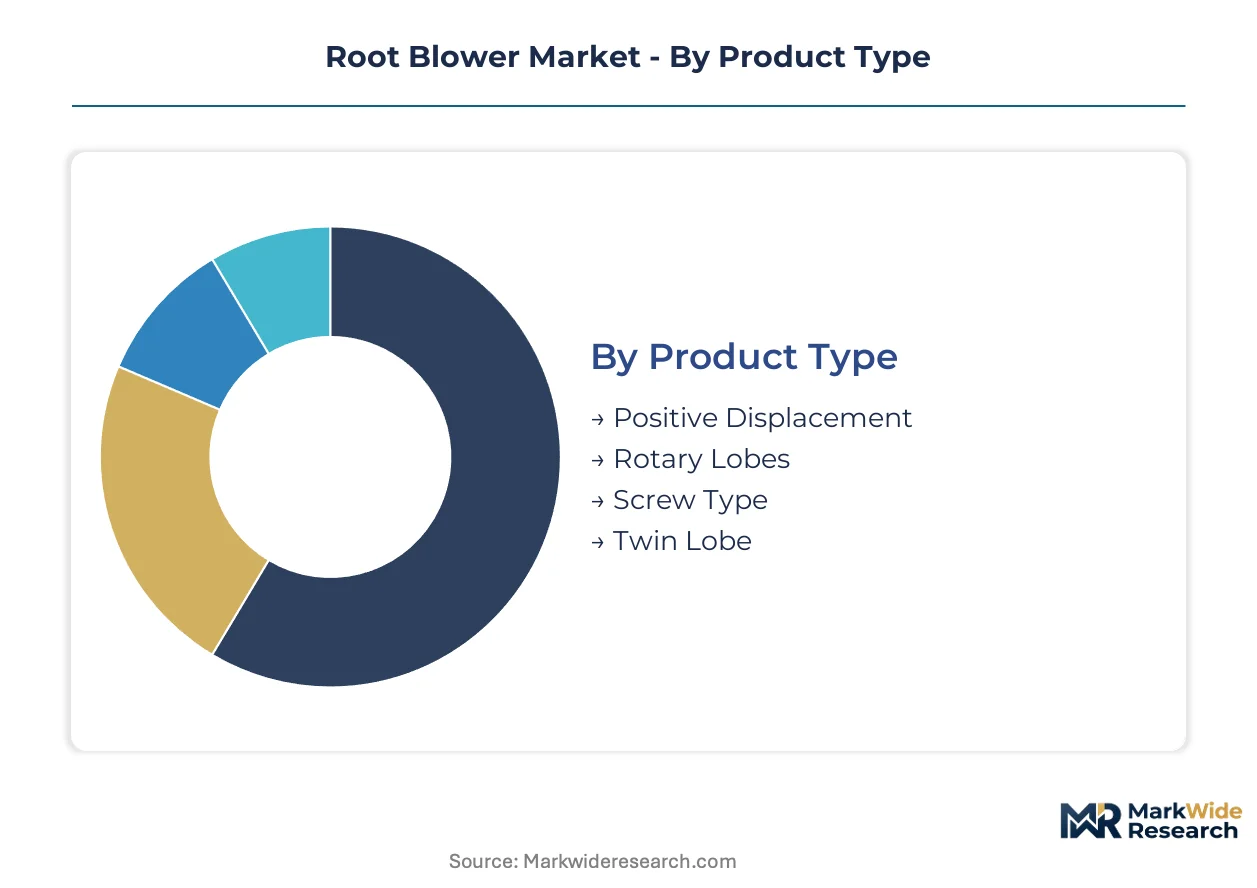
Root blower procurement patterns diverge sharply across operating environments. Municipal infrastructure cycles stretch fifteen to twenty years while chemical processing corridors refresh equipment on compressed timelines. Understanding these replacement rhythms clarifies where service revenue concentrates versus where capital sales dominate.
Product Type:
Replacement cycles stretch from five years in continuous-duty chemical service to two decades in intermittent municipal aeration. Electric drive retrofits are compressing these intervals as energy efficiency mandates force premature obsolescence on mechanically sound units.
- Positive Displacement:These units employ intermeshing rotors to trap and transport fixed gas volumes against moderate pressure differentials. Germany's Ruhr wastewater treatment cluster depends on this architecture for dissolved oxygen control loops under EU Green Deal aeration mandates.
- Rotary Lobes:Two-lobe or three-lobe configurations deliver oil-free compression essential for food-grade pneumatic conveying. Jiangsu province chemical processors specify these for powder transport systems requiring contamination-free gas handling.
- Screw Type:Helical rotor pairs achieve higher pressure ratios than conventional lobe designs. Oil-injected variants dominate vacuum generation in metallurgical applications.
- Twin Lobe:Symmetrical rotor profiles minimize pulsation for sensitive downstream processes. Shandong province food processing corridors standardize these for flour and sugar conveying systems.
Positive Displacement dominates installed base. Twin Lobe is where expansion concentrates.
End User:
Capital allocation intensity varies threefold across end-use sectors. Municipal utilities amortize equipment over regulatory compliance horizons while chemical processors depreciate against production uptime guarantees.
- Waste Water Treatment:Continuous aeration duty demands blowers rated for twenty-year service intervals. EPA effluent guidelines in the United States mandate nitrogen removal upgrades that intensify oxygen transfer requirements.
- Pneumatic Conveying:Batch-operated systems in bulk material handling tolerate higher maintenance frequencies. China's GB energy efficiency standards are filtering import access for non-compliant pneumatic systems.
- Food Processing:Oil-free compression specifications dominate powder transport and packaging line applications. Dutch dairy processors specify stainless-steel lobe materials for hygiene compliance.
- Chemical Industry:Corrosive gas handling requires specialized alloy castings for rotor and housing components. Maharashtra state's petrochemical corridor generates tender volume for corrosion-resistant blower packages.
Waste Water Treatment anchors replacement demand. Pneumatic Conveying is climbing the fastest.
Application:
Operating mode differentiation—continuous versus intermittent—drives specification divergence more than pressure or flow requirements. Aeration systems run flat-out while odor control cycles with diurnal load patterns.
- Aeration:Dissolved oxygen control loops in activated sludge processes require blowers with turndown ratios exceeding four-to-one. Denmark's municipal treatment operators pilot permanent magnet synchronous motor integration for variable-load efficiency.
- Vacuum Generation:Hold-down and material handling applications demand rapid pump-down characteristics. Gujarat state's pharmaceutical manufacturing clusters specify dry-running rotary lobe vacuum pumps for tablet packaging lines.
- Dust Control:Negative pressure containment systems in mineral processing require abrasion-resistant rotor coatings. Cement grinding facilities in Rajasthan deploy hardened steel lobes for fly ash handling.
- Odor Control:Intermittent biofilter aeration tolerates lower capital expenditure with higher maintenance acceptance. German landfill gas management operators favor simplex blower configurations for scrubber feed systems.
Aeration commands capital deployment. Vacuum Generation is gaining share fastest.
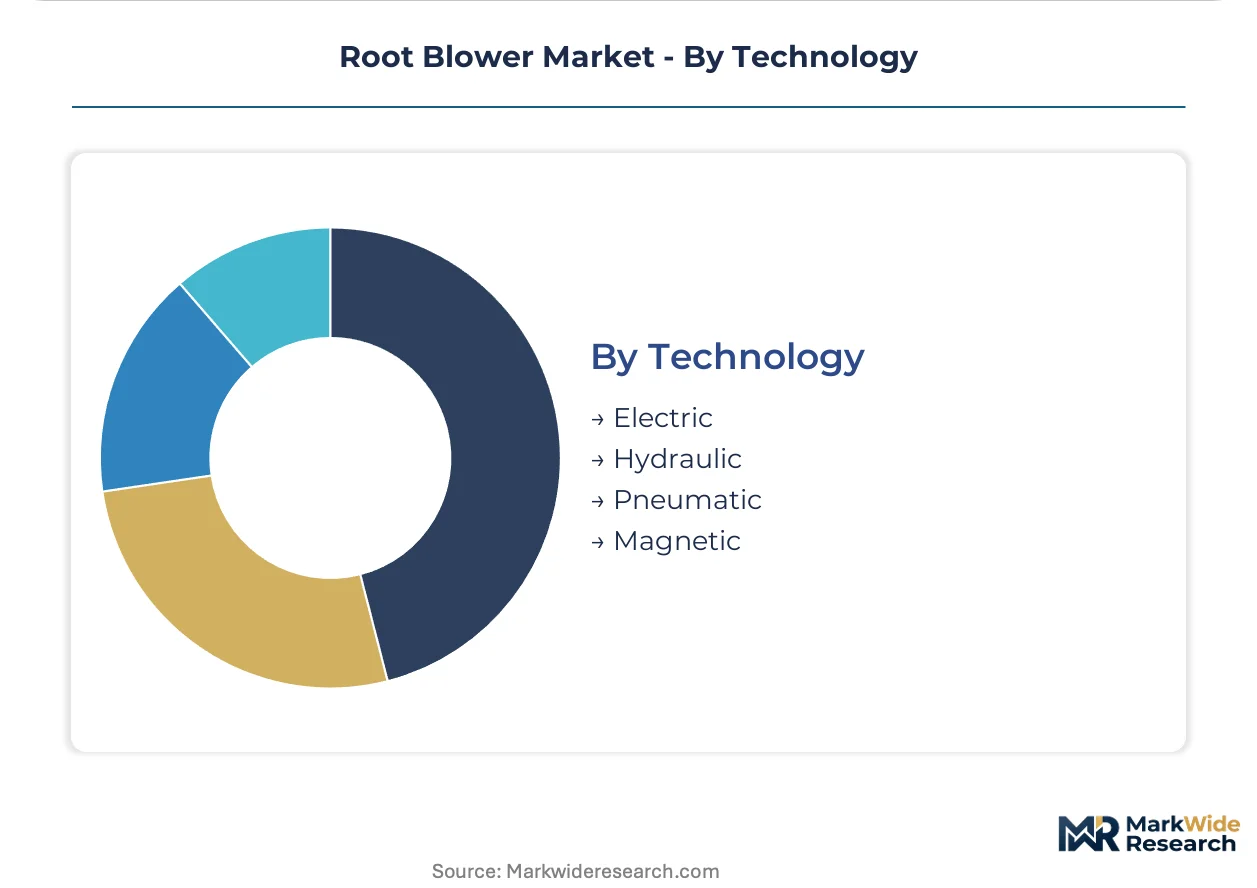
Technology:
Drive technology selection determines twenty-year operating cost trajectories. Electric systems carry higher upfront capital but eliminate hydraulic fluid maintenance and pneumatic compressor parasitic loads.
- Electric:Variable frequency drive compatibility enables precise dissolved oxygen control in municipal aeration. Netherlands treatment plants retrofit induction motor systems with permanent magnet synchronous alternatives for fifteen to twenty percent energy reduction.
- Hydraulic:Compact power density suits mobile and explosion-risk environments. Legacy installations in India's Smart Cities Mission infrastructure face replacement pressure under efficiency compliance timelines.
- Pneumatic:Compressed air drive eliminates electrical ignition hazards in volatile atmospheres. Limited to small-scale applications by compressor energy penalty.
- Magnetic:Bearingless motor technology eliminates mechanical wear components entirely. Turbo blower variants are capturing low-pressure aeration applications from rotary lobe designs.
Electric dominates new installations. Magnetic is where technology substitution threatens incumbent architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Germany's central role in European industrial blower demand, connecting Bavarian manufacturing clusters to North Sea ports and Danube basin markets.
United States
Municipal wastewater infrastructure across the Great Lakes and Ohio River basins drives replacement demand for aeration blowers. EPA effluent limitation guidelines mandate nitrogen removal upgrades that intensify oxygen transfer requirements. Chicago and Cleveland treatment authorities specify packaged blower skids with integrated dissolved oxygen control for activated sludge processes.
Germany
Ruhr industrial cluster chemical processors and Lower Saxony wastewater utilities anchor equipment refresh cycles. EU Green Deal aeration mandates force oxygen transfer capacity expansion at aging municipal plants. Bavarian precision engineering firms supply lobe profile grinding equipment to domestic blower fabricators.
China
Jiangsu and Shandong province chemical processing corridors standardize oil-free gas handling for food-grade powder transport. GB energy efficiency standards for rotating machinery filter import access and accelerate domestic manufacturer certification programs. Yangtze River Delta municipal utilities deploy electric drive retrofits under dual carbon compliance timelines.
India
Maharashtra and Gujarat state urban infrastructure expansion generates tender volume for packaged aeration systems under the Smart Cities Mission. Central Electricity Authority efficiency norms pressure legacy hydraulic blower replacements. Mumbai and Ahmedabad wastewater authorities specify variable frequency drive compatibility for dissolved oxygen control loops.
Netherlands
Randstad municipal treatment operators pilot permanent magnet synchronous motor integration for fifteen to twenty percent energy reduction in variable-load aeration duty. REACH compliance documentation requirements shape lobe material sourcing decisions. Rotterdam port industrial zone chemical processors specify stainless-steel blower configurations for corrosion-resistant gas handling.
Root Blower Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision-machined lobe assemblies and bearing configurations. Market structure concentrates around diversified industrial conglomerates with compressor service networks capable of cross-selling blower maintenance contracts. Three archetypes dominate: full-service platform providers bundling predictive diagnostics, heavy-duty engineering specialists serving chemical and power generation clients, and regional fabricators competing on delivery speed for standardized pneumatic conveying units. Competitive moves center on electric drive retrofit service capture and predictive maintenance contract unbundling.
Among diversified industrial conglomerates, Ingersoll Rand and Atlas Copco occupy positions exemplifying the full-service platform archetype, leveraging global compressor service infrastructure to anchor aftermarket revenue streams. Howden represents the heavy-duty engineering specialist tier, with AERZEN and Kaeser sitting within the precision-manufacturing segment serving municipal and chemical end-use requirements. Tuthill Corporation and Dresser exemplify mid-scale specialists focused on vacuum and pneumatic conveying applications.
| Leading Market Players |
|---|
| Ingersoll Rand |
| Atlas Copco |
| Howden |
| AERZEN |
| Baker Hughes |
| Tuthill Corporation |
| Dresser |
| Kaeser |
| Taiko |
| Others |
Value Network & Pricing Analysis
Single-source dependency on precision-cast lobe foundries in Germany and Japan compresses procurement timelines and widens pricing tier spreads between premium alloy specifications and standard-grade alternatives. This concentration forces buyers to absorb premium markups for corrosion-resistant materials or accept elongated lead times, reshaping how municipal utilities and chemical processors allocate capital across equipment refresh cycles.
Pricing Analysis
Volume-discount tiering structures separate municipal bulk procurement contracts from single-unit industrial replacements by fifteen to twenty percent at the standard grade, with premium corrosion-resistant specifications commanding additional separation. Certification under EU Ecodesign and China's GB standards filters import access, allowing certified manufacturers to sustain margin premiums while non-compliant competitors face price erosion. Cost compression in the economy tier intensifies as domestic Chinese manufacturers scale twin lobe production for pneumatic conveying applications. Municipal wastewater utilities exhibit highest price sensitivity due to budget cycle constraints, while chemical processors in corrosive gas service prioritize alloy grade over unit cost.
Supply Chain Analysis
Tariff exposure between European Union member states and third-country foundry suppliers dominates supply chain risk calculations for precision-cast rotor components. Lobe profile grinding equipment and specialized alloy feedstock concentrate manufacturing in Germany, Japan, and select Italian engineering clusters. Raw material dependencies center on nickel-based superalloys, hardened tool steels, and precision bearing assemblies sourced from concentrated metallurgical suppliers. Single-source vulnerability in European foundry capacity exposes procurement timelines to capacity allocation decisions at major casting houses. Distribution runs through OEM direct sales for large municipal contracts and authorized distributor networks for standardized pneumatic conveying units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic bearing turbo blower substitution threatens rotary lobe incumbents in low-pressure aeration applications, forcing defensive repositioning around service integration and high-pressure performance envelopes where displacement technology retains advantage.
For Market Incumbents: Harden aftermarket service capture by embedding predictive diagnostics into municipal maintenance contracts before third-party unbundling fragments revenue streams. Deepen captive supply of precision-machined lobe assemblies through backward integration into European foundry partnerships, insulating procurement timelines from single-source bottlenecks. Prioritize permanent magnet synchronous motor hybridization to defend energy efficiency positioning against magnetic bearing substitutes in variable-load aeration duty. For New Entrants and Emerging Players: India's Smart Cities Mission tender volume in Maharashtra and Gujarat represents the most penetrable geographic underpenetration for packaged aeration system specialists lacking incumbent service infrastructure. Target corrosion-resistant blower specifications for Maharashtra's petrochemical corridor where alloy casting capabilities concentrate among aging practitioner cohorts and capability scarcity creates specification gaps. Pursue joint venture structures with domestic Indian fabricators to satisfy local content requirements and accelerate certification under Central Electricity Authority efficiency norms. For Investors and Strategic Acquirers: EU Green Deal implementation timelines reshape the acquisition landscape by concentrating replacement demand in German wastewater infrastructure through specified compliance deadlines. Mid-scale precision engineering specialists with captive lobe grinding capabilities and established municipal service networks represent the optimal target archetype for platform consolidation. Monitor carbon border adjustment mechanism documentation requirements as the signal to watch for service revenue inflection, as equipment lifecycle carbon accounting creates new contractable value streams.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Integration | Netherlands and Denmark municipal pilots validate fifteen to twenty percent energy reduction in variable-load aeration duty. |
| Predictive Diagnostics Convergence | Vibration monitoring algorithms fused with rotary lobe architectures enable condition-based maintenance contract unbundling. |
| Corrosion-Resistant Alloy Development | Specialized castings for chemical industry gas handling defend premium positioning against standard-grade competitors. |
| Electric Drive Retrofit Service Capture | Municipal infrastructure replacement cycles under EPA effluent guidelines generate recurring revenue from efficiency compliance mandates. |
| Carbon Border Adjustment Documentation | EU CBAM compliance requirements create service revenue streams for equipment lifecycle carbon accounting. |
Research Methodology
The analysis maps positive displacement, rotary lobe, screw type, and twin lobe product categories, each validated through maintenance directors at municipal wastewater utilities, plant engineers in chemical processing corridors, OEM procurement teams specifying aeration equipment, and aftermarket service heads managing blower fleets. Primary interviews with these stakeholders triangulated against customs and trade data, rotating machinery association reports, SEC filings from diversified industrial conglomerates, and national energy efficiency standard databases. Bottom-up equipment shipment tallies and top-down infrastructure investment flows were reconciled to establish market sizing boundaries.
Assumptions held fixed include regulatory compliance timelines under EU Green Deal and EPA effluent guidelines, while variable conditions encompassed electric drive retrofit penetration rates and magnetic bearing substitution velocity across the analysis window. Segmentation modeling incorporated product type, end user industry, application mode, and drive technology dimensions. CAGRs were derived from equipment replacement cycle analysis and infrastructure tender pipeline tracking, with inputs from dissolved oxygen control intensity requirements and GB standard certification velocity in Chinese domestic manufacturing.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic manufacturers or accelerated magnetic bearing adoption by Netherlands and Denmark municipal operators would shift outcomes beyond projected ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Oil Filled Air Compressor Market
Compressors
Reciprocating Air Compressor Market
Compressors
Rental Air Compressors Market
Compressors
North America Air Compressor Market
Compressors
Scroll Compressor Market
Compressors
Asia-Pacific Booster Compressor Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Air Compressor Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
Bus Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Stationary Air Compressor Market
Compressors
Hydrogen Compressor Market
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Centrifugal Compressors Market