
 Portable Air Compressor Market | 2026-2036
Portable Air Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Air Compressor Market Analysis
Aluminum is decoupling from cast iron in pump housing construction, trimming weight by roughly one-third without sacrificing pressure ratings. Ingersoll Rand leverages captive foundry capacity to anchor its North American production network. Atlas Copco sustains technology leadership through variable-speed drive integration across its portable lineup. Kaeser Kompressoren specializes in oil-free rotary screw architectures for contamination-sensitive job sites.
A portable air compressor is a self-contained, mobilized pneumatic power unit typically rated between 1 and 400 CFM discharge flow, employing reciprocating piston or rotary screw mechanisms driven by electric motors, gasoline engines, or battery packs to generate compressed air for tools and processes away from fixed infrastructure. Electric models now lead the product type category on the back of lithium-ion battery density improvements and indoor emissions restrictions, while battery-powered units represent the fastest-expanding sub-segment as runtime per charge doubles every hardware generation. The construction end user segment commands the deepest margin pools due to fleet replacement cycles and rental channel premiums, though home applications show the steepest volume trajectory from DIY tool ecosystem expansion.
The US EPA enforces Tier 4 Final particulate and NOx limits on diesel-driven compressors above 25 horsepower, redirecting rental fleet procurement toward gasoline and electric alternatives. OSHA mandates hearing conservation programs where operator exposure exceeds 85 dBA, accelerating demand for quiet operation feature sets below 70 dBA at one meter. The EU F-Gas Regulation restricts fluorinated refrigerants in associated air drying equipment, tightening supply chains for moisture-sensitive applications. Stakeholders must weigh battery chemistry commitments against the pace of charging infrastructure buildout at remote job sites.
Market Dynamics
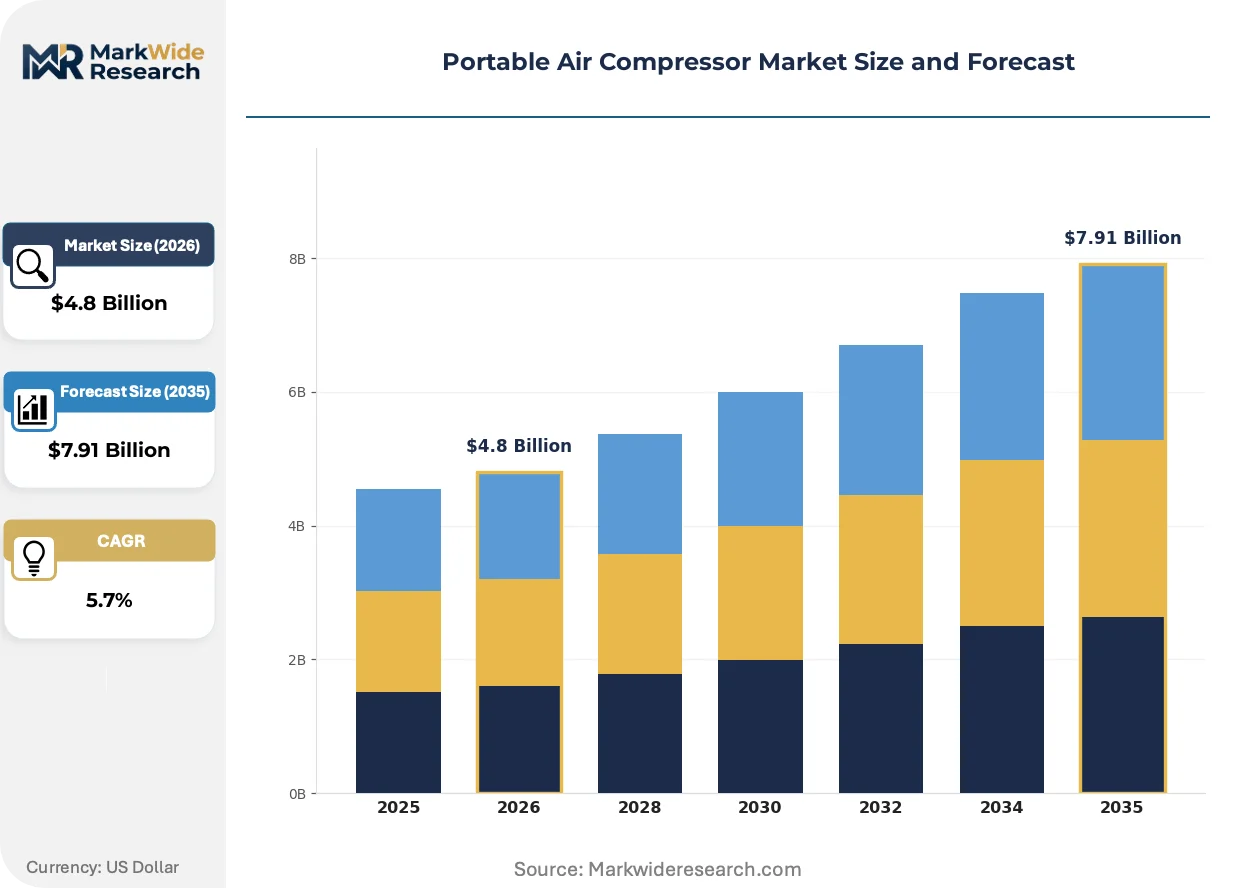
Portable air compressor demand is bifurcating around powertrain architecture as EPA Tier 4 Final emissions standards render diesel units uneconomical below 50 horsepower, forcing rental fleets and contractors to reconstitute procurement criteria around electric and gasoline alternatives.
Growth Catalysts
- Emissions Compliance Deadlines:US EPA Tier 4 Final enforcement above 25 horsepower redirects capital expenditure toward compliant gasoline and battery-electric models, accelerating fleet turnover in North American rental channels.
- Lithium-Ion Energy Density Gains:Battery chemistry improvements are doubling runtime per charge across hardware generations, enabling cordless units to displace engine-driven alternatives in indoor finishing and renovation work.
- Industrial Corridor Expansion:Construction contractors across India's Pune and Chennai manufacturing belts are deploying portable pneumatic infrastructure to support automotive and electronics assembly plant construction.
Market Restraints
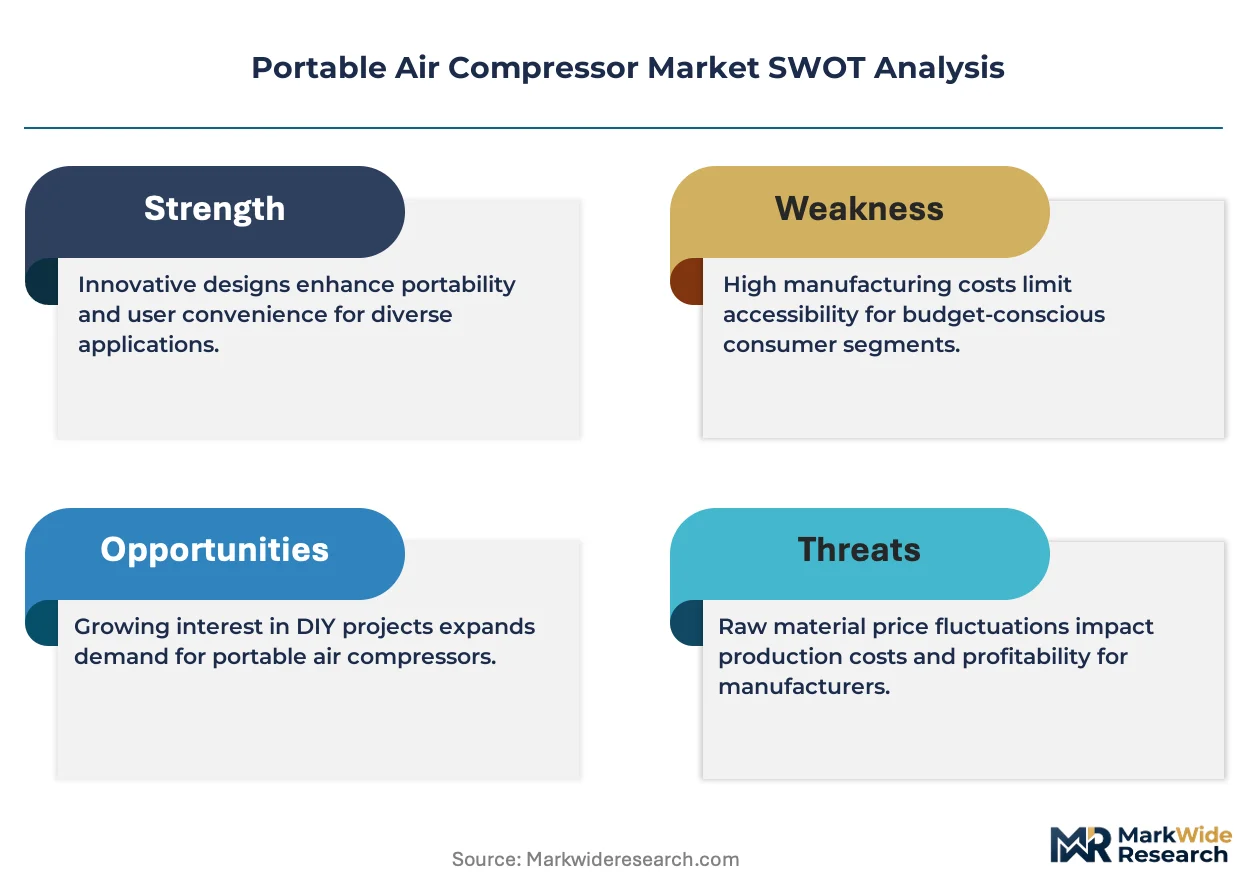
- Raw Material Cost Volatility:Aluminum ingot price swings directly compress pump housing margins, with die-cast components representing 18-22% of bill-of-materials for mid-range reciprocating units.
- Foundry Concentration Risk:Captive casting capacity anchors production networks in specific geographies, exposing supply chains to localized energy cost spikes and labor availability constraints.
- Acoustic Performance Ceilings:OSHA hearing conservation mandates at 85 dBA exposure limits impose engineering constraints that add 15-20% to unit cost for sub-70 dBA quiet-operation feature sets.
Strategic Opportunities
- Underpenetrated Southeast Asian Job Sites:Indonesia and Vietnam construction markets show low portable compressor penetration relative to GDP growth in infrastructure, presenting first-mover positioning for electric unit suppliers.
- EU F-Gas Regulation Tailwind:Restrictions on fluorinated refrigerants in associated air drying equipment create demand for integrated oil-free rotary screw architectures that eliminate downstream moisture contamination.
- Telematics-Driven Rental Models:IoT-enabled fleet management platforms allow rental houses to unbundle utilization-based pricing from ownership, capturing margin from contractors seeking operational flexibility over capital deployment.
Industry Challenges
- Charging Infrastructure Gaps:Remote construction sites lack standardized high-amperage power distribution, forcing battery-electric unit operators to haul supplemental charging equipment or accept runtime limitations.
- Cross-Border Certification Complexity:Divergent pressure vessel standards between US ASME, EU PED, and Indian BIS regimes fragment product development roadmaps and extend time-to-market for unified global platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Air Compressor Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gasoline, Pneumatic, Battery-powered End User: Automotive, Construction, Home, Industrial Application: Tire Inflation, Cleaning, Painting, Power Tools Features: Portable, Oil-free, Quiet Operation, High Pressure |
| Companies Covered | Ingersoll Rand, Atlas Copco, Doosan Portable Power, Gardner Denver, Kaeser Kompressoren, Sullair, Stanley Black & Decker, Elgi Compressors USA, Husky Cooperation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Air Compressor Market Emerging Trajectories
Powertrain electrification is compressing the traditional reciprocating-rotary screw hierarchy as battery energy density and variable-speed drive integration redefine performance benchmarks across portable categories.
Lithium-ion battery packs are electrifying the sub-10 CFM portable segment previously dominated by small gasoline engines. Finish carpentry and interior renovation contractors in California and New York metropolitan areas are specifying cordless units for 60-70% of new fleet additions. This transition is compressing the addressable market for sub-25 horsepower gasoline reciprocating models while expanding serviceable hours per shift through eliminated refueling downtime.
The EU F-Gas Regulation is tightening supply chains for moisture-sensitive compressed air applications by restricting fluorinated refrigerants in desiccant dryers. European rental fleets are responding by specifying oil-free rotary screw compressors with integrated membrane or deliquescent drying stages. This regulatory pressure is accelerating technology transfer from stationary industrial applications into portable form factors previously served by simpler piston architectures.
Equipment-as-a-service contracting is displacing traditional capital purchase models in North American construction rental channels. National rental houses are bundling telematics-enabled compressors with predictive maintenance and guaranteed uptime commitments, capturing multi-year revenue streams from contractors seeking balance sheet flexibility. This procurement evolution is most visible in Texas and Florida metropolitan construction markets where fleet utilization data supports outcome-based pricing structures.
Portable Air Compressor Market Segmentation
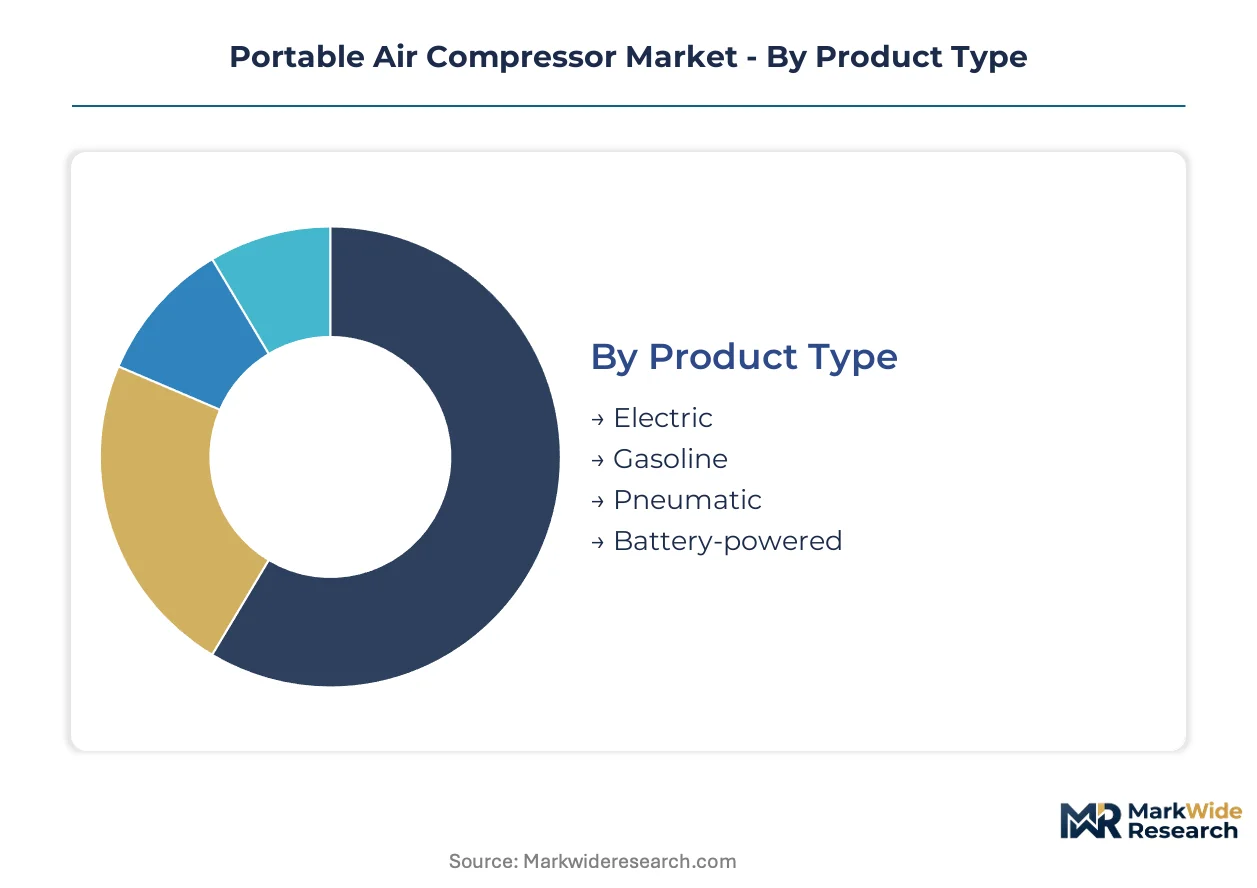
Portable air compressor procurement decisions pivot on powertrain compatibility with job site constraints and regulatory exposure. Segment boundaries are blurring as battery energy density improvements enable electric architectures to displace gasoline units in applications previously defined by mobility requirements.
Product Type:
Powertrain selection hinges on balancing runtime autonomy against emissions compliance and indoor access permissions.
- Electric:Corded units draw from grid or generator power, delivering continuous output without refueling cycles. Demand clusters in California and New York metro construction markets where indoor emissions restrictions and OSHA hearing conservation mandates favor plug-in architectures over combustion alternatives.
- Battery-powered:Lithium-ion packs now enable 4-6 hour continuous runtime in sub-10 CFM configurations, eliminating tethering constraints for finish carpentry and renovation contractors. Adoption is climbing the fastest in residential construction corridors where generator noise restrictions and fuel hauling costs compound operational friction.
- Gasoline:Reciprocating piston architectures dominate remote job sites lacking electrical infrastructure, particularly in Texas and Florida infrastructure projects.
- Pneumatic:Engine-driven rotary screw units serve high-CFM continuous-duty applications in mining and heavy civil construction.
Electric leads on scale; battery-powered leads on momentum.
End User:
Margin profiles diverge sharply between fleet-based rental channels and discretionary consumer purchase patterns.
- Construction:Rental fleet procurement drives volume concentration, with national chains specifying telematics-enabled units for utilization-based pricing models. Pune and Chennai industrial corridors in India anchor emerging market demand as automotive and electronics assembly plant construction accelerates pneumatic infrastructure deployment.
- Industrial:Manufacturing maintenance departments specify oil-free rotary screw architectures for contamination-sensitive production environments, particularly in EU markets where F-Gas Regulation restricts fluorinated refrigerants in associated drying equipment.
- Automotive:Service shops and collision repair centers favor portable units for tire inflation and pneumatic tool operation in bay configurations lacking fixed compressed air drops.
- Home:DIY ecosystem expansion through retail hardware channels is expanding the addressable consumer base for compact reciprocating units.
Construction commands the deepest margin pools; home applications show the steepest volume trajectory.
Application:
Air consumption rates and duty cycle intensity determine compressor sizing and architecture selection.
- Power Tools:Continuous-duty nail guns, impact wrenches, and grinders demand sustained CFM delivery, favoring gasoline or high-capacity electric rotary screw configurations in commercial framing and structural steel erection.
- Tire Inflation:Intermittent-duty requirements suit compact reciprocating or battery-powered units with pressure cutoff controls, prevalent in automotive service and roadside assistance fleets.
- Painting:HVLP spray systems require moisture-free air delivery, driving specification of integrated drying stages in finishing contractor equipment.
- Cleaning:Blow-gun and surface preparation applications span the full product range from consumer-grade inflation units to industrial abrasive blast systems.
Power tools anchor commercial revenue; tire inflation spans the broadest customer base.
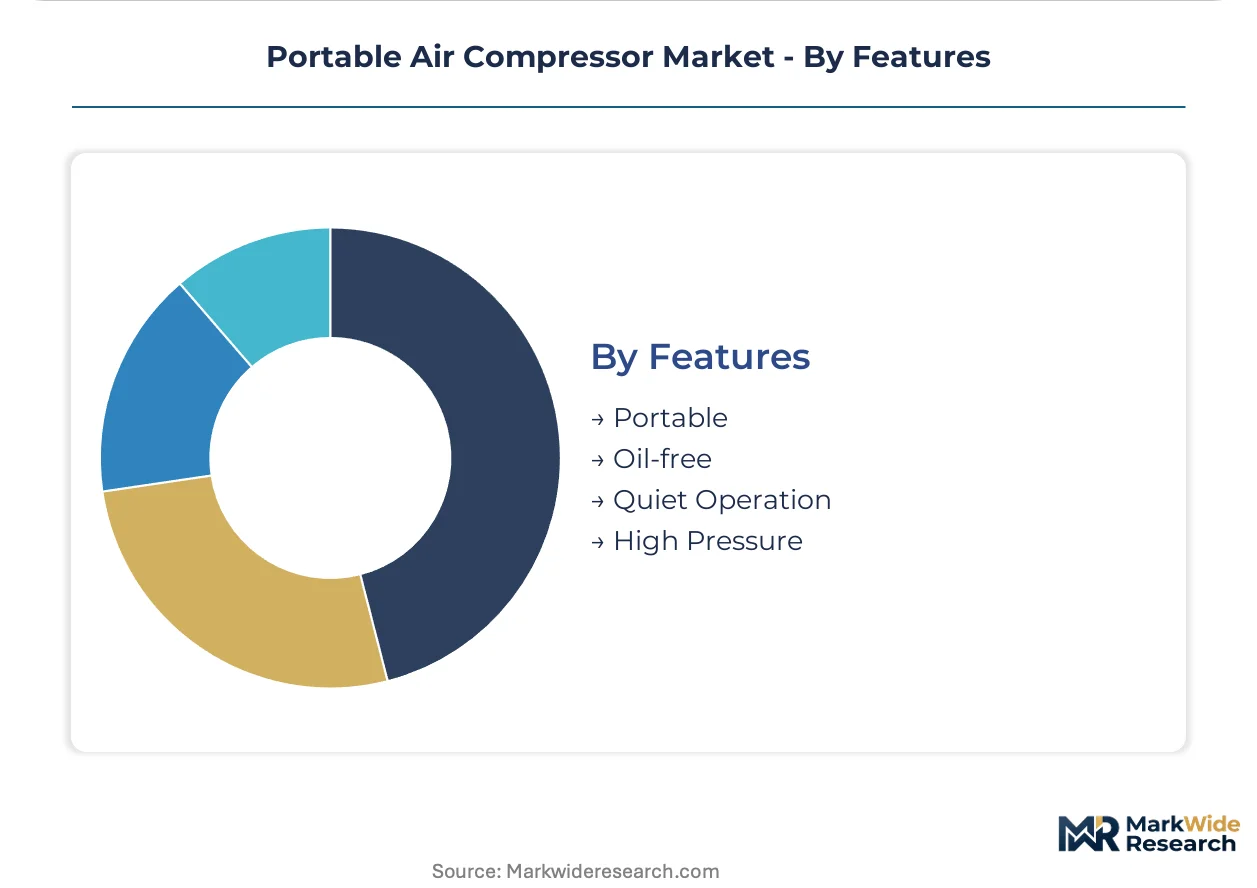
Features:
Specification premiums concentrate on acoustic performance and contamination control where regulatory or contractual constraints apply.
- Quiet Operation:Sub-70 dBA at one meter configurations command 15-20% price premiums to satisfy OSHA hearing conservation programs and urban noise ordinances in dense metropolitan construction markets.
- Oil-free:Rotary screw architectures eliminate downstream contamination risks for food processing, electronics assembly, and medical device manufacturing applications, particularly in EU and North American regulatory environments.
- High Pressure:Specialized reciprocating configurations serve diving, breathing air, and industrial process requirements beyond standard 125-150 PSI shop air standards.
- Portable:Wheeled, skid-mounted, and towable form factors define the core market category, with weight reduction through aluminum pump housings enabling single-operator mobility.
Portable is the baseline category entry; quiet operation captures the steepest specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pune and Chennai industrial corridors anchor portable compressor procurement across India's automotive and electronics construction belt. Rental fleet operators in Texas and Florida metropolitan markets are specifying telematics-enabled electric units for utilization-based contracting. German manufacturers face EU F-Gas Regulation compliance costs for integrated drying equipment.
United States
EPA Tier 4 Final enforcement above 25 horsepower redirects rental capital toward gasoline and battery-electric models. OSHA mandates hearing conservation programs where operator exposure exceeds 85 dBA, accelerating demand for sub-70 dBA configurations. Texas and Florida metropolitan construction markets show the strongest telematics-enabled fleet adoption for outcome-based pricing structures.
India
Construction contractors across Pune and Chennai manufacturing belts deploy portable pneumatic infrastructure for automotive and electronics assembly plant construction. BIS pressure vessel certification requirements fragment product development timelines against US and EU standards. The Delhi-Mumbai Industrial Corridor and Tamil Nadu electronics manufacturing clusters concentrate emerging market demand.
Germany
Industrial maintenance departments specify oil-free rotary screw architectures for contamination-sensitive production environments. EU F-Gas Regulation restrictions on fluorinated refrigerants in desiccant dryers tighten supply chains for moisture-sensitive applications. Bavaria and Baden-Württemberg manufacturing regions anchor demand for integrated oil-free portable systems.
China
Domestic construction equipment rental channels are electrifying sub-10 CFM segments previously served by small gasoline engines. MEE emissions enforcement and dual carbon goals accelerate battery-powered unit adoption in indoor finishing work. Yangtze River Delta and Pearl River Delta manufacturing belts concentrate production capacity for lithium-ion powered portable compressors.
Brazil
Mining and heavy civil contractors in Minas Gerais and Pará states sustain demand for high-CFM engine-driven rotary screw units. ANVISA industrial equipment safety requirements add certification complexity for imported portable systems. São Paulo state construction markets show early electric unit penetration in residential finishing applications.
Portable Air Compressor Market Vendor Landscape
Global majors compete with regional champions across powertrain technology and rental channel access. The vendor base stratifies between consolidated multinational portfolios and specialized regional fabricators serving captive foundry networks. Three archetypes dominate: diversified industrial conglomerates with captive casting capacity, pure-play compressor specialists with oil-free technology leadership, and power tool ecosystem integrators leveraging battery platform synergies. Capacity expansion in aluminum die-casting and strategic partnerships for telematics integration represent the dominant competitive moves.
Within the diversified industrial tier, Ingersoll Rand and Atlas Copco exemplify scale-driven positions anchored by captive foundry networks and variable-speed drive integration. Kaeser Kompressoren occupies a specialist position focused on oil-free rotary screw architectures. These three companies represent distinct strategic postures: foundry-anchored production control, technology leadership through drive integration, and contamination-sensitive application specialization.
| Leading Market Players |
|---|
| Ingersoll Rand |
| Atlas Copco |
| Doosan Portable Power |
| Gardner Denver |
| Kaeser Kompressoren |
| Sullair |
| Stanley Black & Decker |
| Elgi Compressors USA |
| Husky Cooperation |
| Others |
Supply Flow & Price Mechanics
OSHA hearing conservation mandates and EPA Tier 4 Final emissions deadlines are compressing procurement criteria toward sub-70 dBA and battery-electric configurations, forcing manufacturers to absorb acoustic engineering and lithium-ion pack costs while defending position in rental fleet negotiations. This specification creep fragments pricing power across compliance tiers.
Pricing Analysis
Aluminum ingot cost pass-through governs mid-range reciprocating unit pricing, with die-cast pump housing components representing a substantial bill-of-materials share. Three-tier pricing structure across premium, standard, and economy levels separates telematics-enabled rental fleet specifications from bare-tool retail offerings. Cost compression in gasoline reciprocating tiers is intensifying because lithium-ion runtime improvements displace sub-25 horsepower engine models. Rental channels show least price sensitivity due to utilization-based contracting, while DIY retail buyers concentrate elasticity.
Supply Chain Analysis
ASME, EU PED, and Indian BIS pressure vessel certification divergence gates component sourcing and fragments global platform development. Manufacturing capacity concentrates in China, Germany, and the United States, with aluminum die-casting and variable-speed drive production anchoring regional networks. Supply chains draw from lithium-ion cell suppliers, aluminum foundries, and precision machining centers. Single-source vulnerability sits with captive foundry networks exposed to localized energy cost spikes. Distribution runs through national rental houses, regional equipment dealers, and retail hardware channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery chemistry cost curves and telematics bundling are expanding premium-tier capture rates, converting capital equipment procurement into recurring revenue streams with superior margin retention.
For Market Incumbents: Extend telematics-enabled fleet management platforms into guaranteed uptime contracting, capturing multi-year revenue streams from contractors seeking balance sheet flexibility. Deepen backward integration into aluminum die-casting to anchor production networks against ingot price volatility. Defend against power tool ecosystem integrators by locking rental channel exclusivity through predictive maintenance bundling. For New Entrants and Emerging Players: E-commerce direct-to-contractor channels bypass incumbent rental house gatekeepers for battery-powered sub-10 CFM units in residential finishing markets. Target Indonesia and Vietnam construction corridors where portable compressor penetration lags GDP growth in infrastructure. Penetrate through specification of cordless platforms for interior renovation contractors facing generator noise restrictions. For Investors and Strategic Acquirers: Asymmetric upside sits with oil-free rotary screw specialists possessing EU F-Gas Regulation-compliant integrated drying architectures. Five-to-ten year viability favors contamination-sensitive application expertise over commodity reciprocating exposure. Watch lithium-ion charging infrastructure buildout at remote job sites as inflection indicator for battery-electric displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables utilization-based pricing for rental houses in Texas and Florida metropolitan markets. |
| Backward Integration into Aluminum Die-Casting | Secures pump housing supply against ingot price volatility and foundry concentration risk. |
| Oil-Free Rotary Screw Capacity Expansion | Captures EU F-Gas Regulation tailwind for moisture-sensitive compressed air applications. |
| Battery Chemistry Partnership | Doubles runtime per charge across hardware generations for cordless unit displacement. |
| Southeast Asian Distribution Buildout | Positions first-mover advantage in Indonesia and Vietnam infrastructure markets. |
Methodological Framework
Direct dialogue with rental fleet procurement managers, construction contractor operations directors, OEM aftermarket service heads, and aluminum foundry technical directors grounded qualitative findings in operational reality. Secondary validation drew from EPA enforcement records, OSHA inspection databases, EU F-Gas Regulation implementation guidance, and customs trade data for compressor imports. Bottom-up unit economics triangulated against top-down market sizing across powertrain, end-user, and regional dimensions.
Segment-level outputs across the analysis window reflect modeled interactions between lithium-ion energy density improvements, emissions compliance deadlines, and rental channel contracting evolution. Powertrain architecture, application intensity, and regional regulatory cluster segmentation framed volume and value projections. CAGRs derived from hardware replacement cycles, fleet turnover rates, and infrastructure investment correlations. Forecast inputs included contractor hiring indices and charging infrastructure deployment trajectories.
Raw material cost volatility, regulatory enforcement timing shifts, and battery chemistry substitution curves are the dominant revision risks for model outputs. Forecasts reflect documented assumptions regarding rental fleet electrification pace and Southeast Asian infrastructure execution. A model refresh is warranted upon material change in EPA enforcement stringency or lithium-ion cell pricing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Middle East and Africa Booster Compressor Market
Compressors
Chlorine Compressors Market
Compressors
Process Gas Compressors Market
Compressors
Gas Compressors Market
Compressors
Asia-Pacific Booster Compressor Market
Compressors
Positive Displacement Gas Compressor Market
Compressors
Oil and Gas Industry Gas Compressor Market
Compressors
Hydrogen Compressor Market
Compressors
Europe Centrifugal Compressor Market
Compressors
CNG Compressor Market
Compressors
North America Air Compressor Market
Compressors
Russia Reciprocating Compressor Market
Compressors
Reciprocating Air Compressor Market
Compressors
USA Scroll Compressor Market
Compressors
Compressed Air Lubricators Market
Compressors
Oil-Injected Screw Compressor Market