
 Positive Displacement Gas Compressor Market | 2026-2036
Positive Displacement Gas Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Positive Displacement Gas Compressor Market Analysis
Buyer consolidation among integrated oil majors and national hydrogen utilities is recalibrating procurement volumes and service-term expectations for compressor OEMs. Atlas Copco leverages its aftermarket service density to sustain recurring revenue across installed bases in Nordic hydrogen hubs. Ingersoll Rand anchors its position through rotary screw specialization in North American food and beverage processing. Ariel Corporation dominates the high-pressure reciprocating segment for natural gas processing and chemical feedstock applications.
Positive displacement gas compressors trap discrete volumes of gas and mechanically reduce chamber size to raise pressure, with reciprocating units achieving discharge pressures exceeding 3,000 bar through crank-driven piston motion. These machines serve critical functions in natural gas transmission, industrial gas handling, and process gas recovery where flow rate control and pressure ratio precision matter more than continuous throughput. Rotary screw compressors lead the product type landscape due to lower maintenance intensity and pulsation-free delivery in continuous-duty environments. Reciprocating compressors retain margin concentration in high-pressure applications such as hydrogen fueling stations and offshore gas reinjection. Diaphragm compressors occupy a defensible niche in pharmaceutical and electronics-grade gas handling where oil-free contamination control is mandatory.
EPA New Source Performance Standards and the EU F-Gas Regulation are tightening methane and fluorinated gas leakage thresholds, compelling end users to replace legacy sealed compressors with advanced low-emission designs. ISO 10494 and API 618 standards govern mechanical integrity and pulsation control in high-risk installations, creating compliance barriers for non-certified suppliers. OSHA process safety management requirements in the US and the EU's Industrial Emissions Directive enforce mandatory inspection intervals that expand the aftermarket service addressable space. Stakeholders must monitor regulatory harmonization between North American and European emission protocols, as diverging certification requirements threaten to fragment product development roadmaps and inflate compliance costs for multinational operators.
Market Dynamics
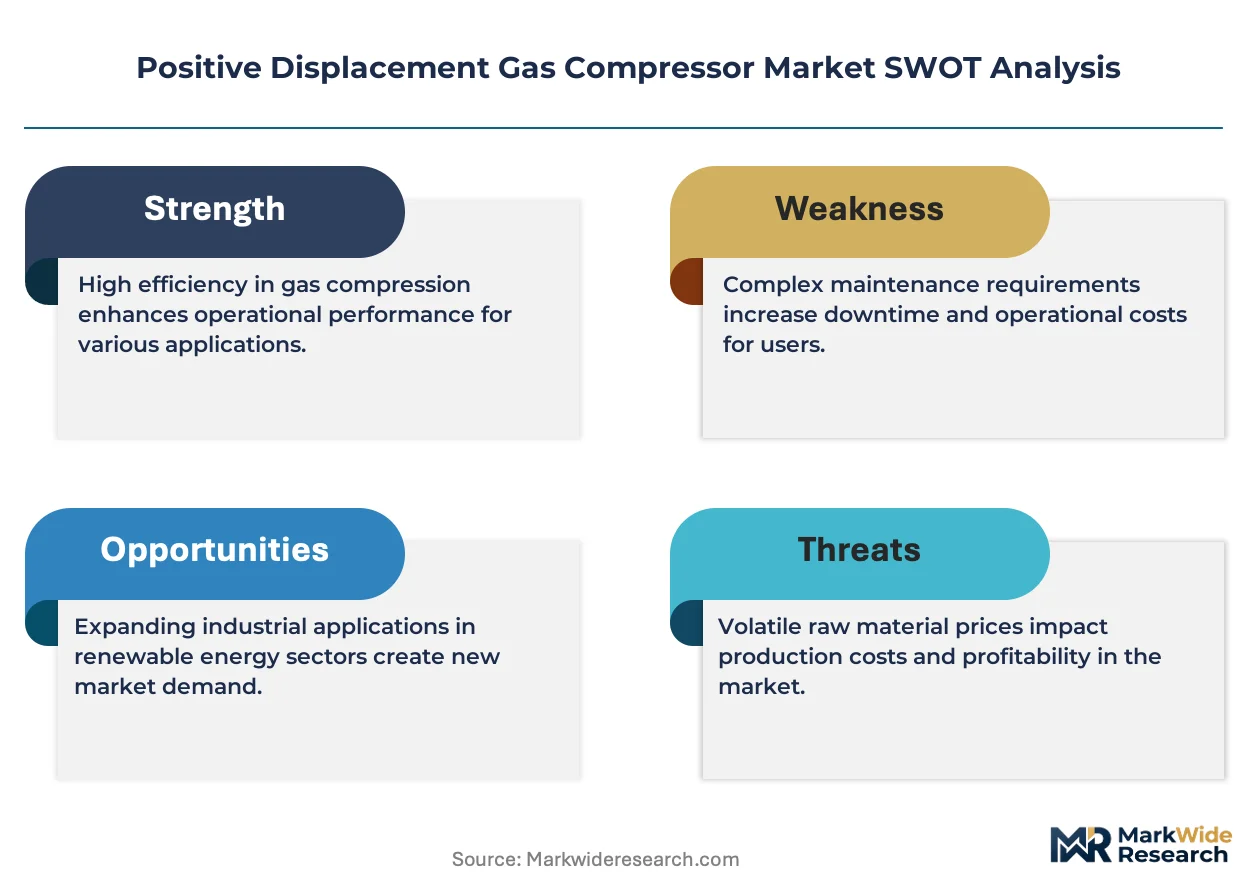
EPA New Source Performance Standards and the EU F-Gas Regulation are compressing allowable methane leakage thresholds, forcing end users to retire legacy sealed compressors and adopt advanced low-emission designs across natural gas processing and hydrogen fueling infrastructure.
Growth Catalysts
- Hydrogen infrastructure buildout:National hydrogen utilities in Germany, China, and the US Gulf Coast are scaling electrolyzer and fueling station deployments, driving demand for high-pressure reciprocating and diaphragm compressor systems.
- EU F-Gas Regulation revisions:Tightening fluorinated gas containment mandates are accelerating equipment replacement cycles in industrial refrigeration and process gas recovery applications.
- Rotary screw technology maturation:Lower maintenance intensity and pulsation-free continuous delivery are displacing reciprocating units in food and beverage processing and general industrial gas handling.
Market Restraints
- Specialized alloy input volatility:Nickel and cobalt price swings in aerospace-grade stainless steels are compressing margins for high-pressure reciprocating compressor manufacturers serving hydrogen fueling applications.
- Supply concentration in precision machining:Critical crankshaft and piston ring production concentrates in German and Japanese tier-two suppliers, creating single-source vulnerability for OEMs.
- Technical ceiling on pressure ratios:Rotary screw compressors face hard thermodynamic limits above 50 bar discharge pressure, ceding high-pressure hydrogen and offshore gas reinjection markets to reciprocating alternatives.
Strategic Opportunities
- Underpenetrated hydrogen fueling in India:National hydrogen mission targets and PLI scheme incentives are opening compressor procurement windows as the country builds electrolyzer manufacturing clusters.
- Electronics-grade gas handling:Semiconductor fab expansion in South Korea and Taiwan is creating demand for oil-free diaphragm compressors with contamination control below 1 ppb.
- Digital predictive maintenance convergence:Vibration analytics and edge computing integration are enabling compressor-as-a-service models that capture recurring revenue from installed base monitoring.
Industry Challenges
- API 618 certification timelines:Reciprocating compressor pulsation and mechanical integrity testing for high-risk installations extends qualification cycles by 12-18 months, delaying project revenue recognition.
- Legacy control system integration:Brownfield petrochemical sites in the US Gulf Coast require custom protocol bridging to connect modern variable-speed drives with existing DCS architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Positive Displacement Gas Compressor Market |
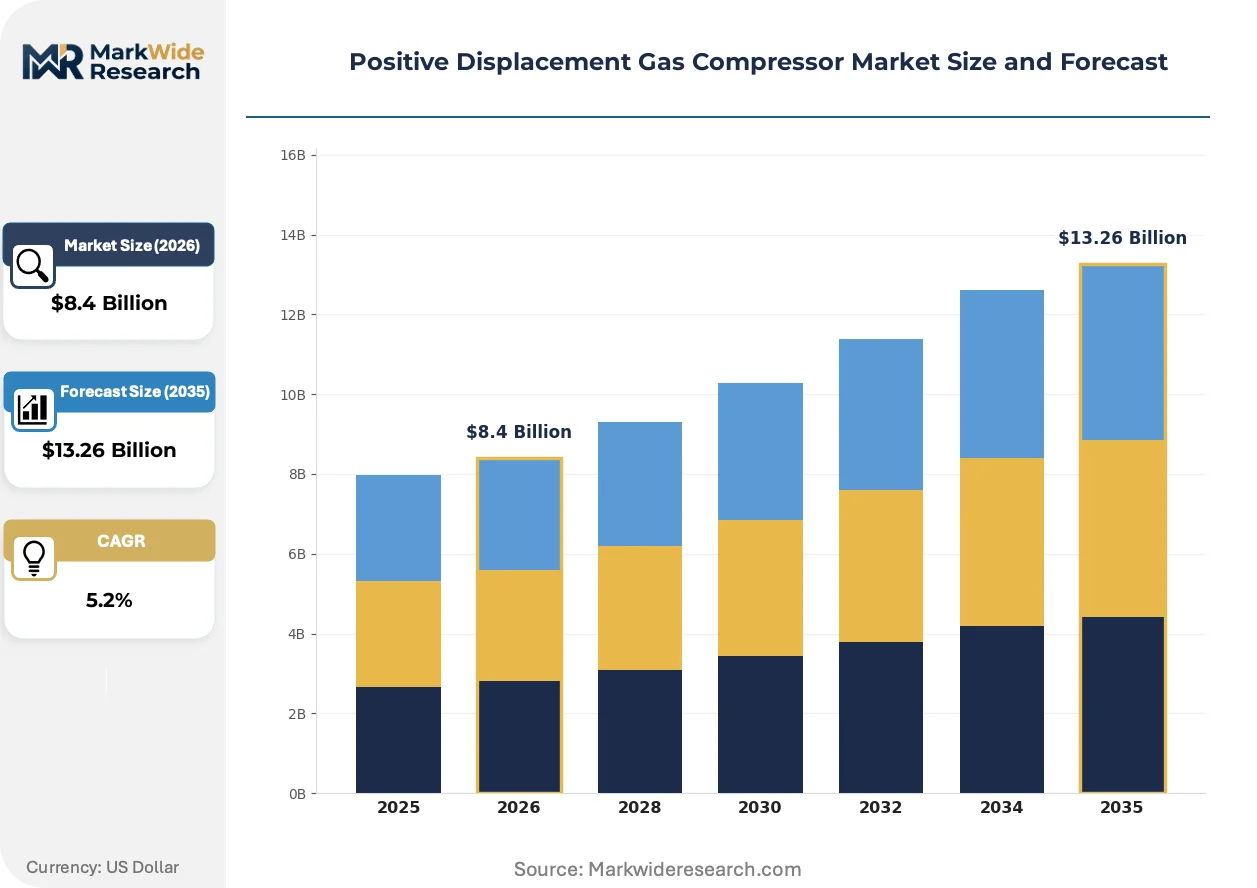
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Compressors, Rotary Screw Compressors, Vane Compressors, Reciprocating Compressors End User: Oil & Gas, Chemical Manufacturing, Food & Beverage, Pharmaceuticals Application: Natural Gas Processing, Wastewater Treatment, Refrigeration, Pneumatic Conveying Installation Type: Onshore, Offshore, Mobile, Stationary |
| Companies Covered | Atlas Copco, Ingersoll Rand, Ariel Corporation, Burckhardt Compression, Siemens Energy, Baker Hughes, Gardner Denver, Bauer Compressors, SIAD Macchine Impianti, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Positive Displacement Gas Compressor Market Emerging Trajectories
Electrification of compressor drivetrains and embedded sensor architectures is reshaping product development roadmaps, while regulatory leakage mandates and buyer consolidation are compressing traditional equipment procurement cycles.
Integrated permanent magnet motors with variable frequency drives are electrifying the compressor drivetrain landscape by eliminating gearbox losses and enabling precise flow control. Hydrogen fueling station operators and offshore platform engineers are specifying these packages for their 15-20% efficiency gains over conventional induction motor setups. This electrification is compressing the addressable market for mechanical drive compressors in continuous-duty applications below 100 bar.
The EU F-Gas Regulation's 2024 amendment tightening fluorinated gas containment thresholds is mandating double-mechanical seal conversions and real-time leakage monitoring retrofits across process gas installations. Industrial refrigeration and chemical feedstock handlers face compliance deadlines that compress equipment replacement budgets into 24-36 month windows. German and Dutch process operators are responding by bundling compressor upgrades with full system refrigerant transitions to natural working fluids.
Aftermarket service unbundling is fragmenting traditional OEM captive maintenance relationships as independent service providers gain API 618 and ISO 10494 certification. Hydrogen utilities and integrated oil majors are disaggregating spare parts procurement from technical service contracts, compressing OEM service margins while expanding third-party addressable space. This pattern concentrates in the North American petrochemical corridor where buyer consolidation has concentrated negotiating leverage among a handful of supermajors.
Positive Displacement Gas Compressor Market Segmentation
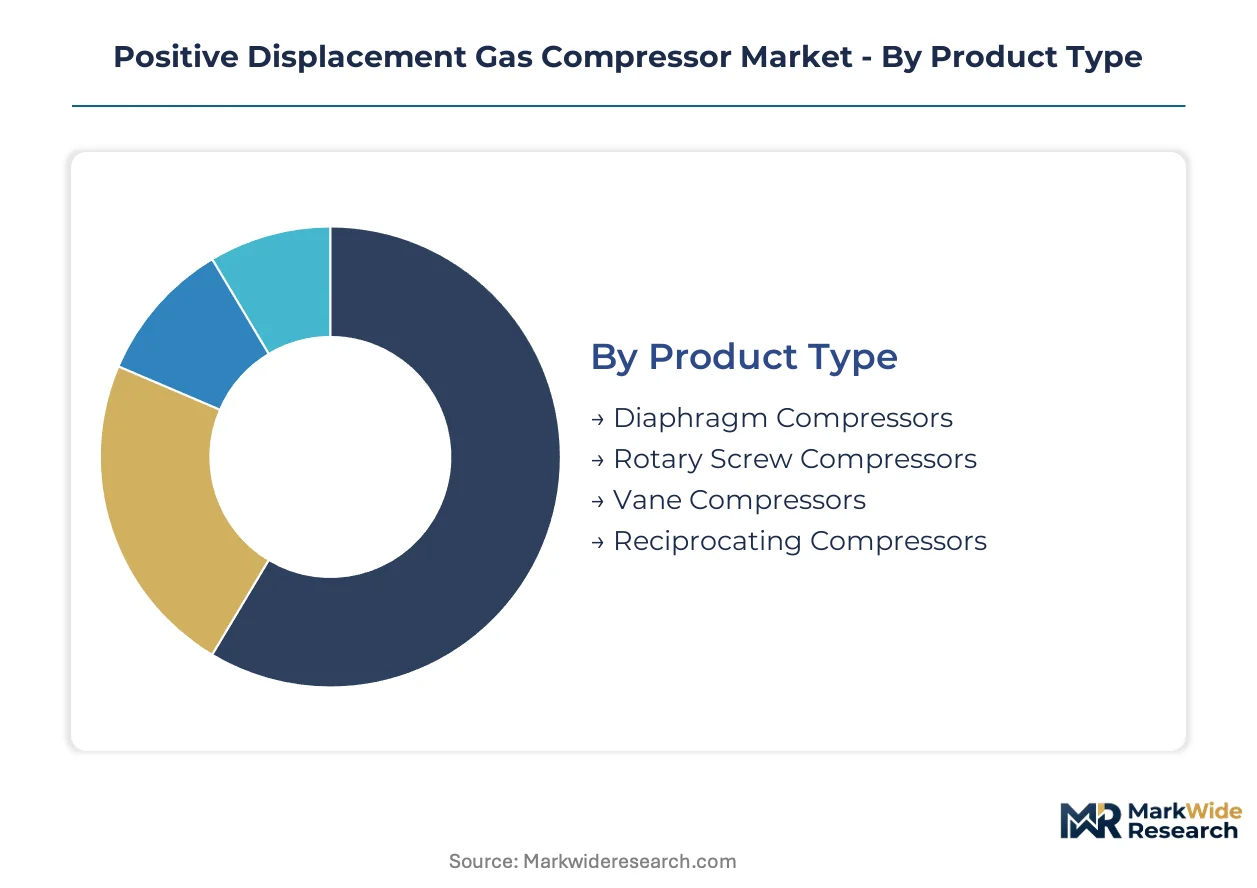
Segmentation in positive displacement gas compressors reveals divergent capital intensity profiles and regulatory exposure across product architectures. Understanding these fault lines enables OEMs to align R&D budgets with end-use procurement cycles and compliance-driven replacement windows.
Product Type:
Capital intensity varies sharply across compressor architectures, with high-pressure reciprocating systems demanding the most substantial upfront engineering investment.
- Reciprocating Compressors:Crank-driven piston mechanisms achieve discharge pressures exceeding 3,000 bar through precision-machined alloy components. Hydrogen fueling stations in Germany and the US Gulf Coast specify these units for their pressure ratio precision, though nickel and cobalt input volatility compresses manufacturer margins.
- Rotary Screw Compressors:Intermeshing helical rotors deliver pulsation-free continuous flow with lower maintenance intensity than reciprocating alternatives. Food and beverage processors across North America favor these systems for their operational continuity and reduced downtime exposure.
- Diaphragm Compressors:Oil-free compression through flexible membrane displacement serves pharmaceutical and electronics-grade gas handling where contamination control below 1 ppb is mandatory. Semiconductor fabs in Taiwan and South Korea drive procurement concentration.
- Vane Compressors:Eccentric rotor with sliding vanes suits lower-pressure pneumatic applications and mobile installations where weight and footprint constraints dominate specification criteria.
Rotary screw compressors absorb the bulk of installed capacity; diaphragm compressors are expanding most quickly.
End User:
Procurement scale and service-term expectations diverge substantially across end-use verticals, with integrated operators commanding volume discounts and extended warranty negotiations.
- Oil & Gas:Natural gas processing, transmission, and reinjection operations specify API 618-certified reciprocating packages for high-risk installations. EPA New Source Performance Standards and EU F-Gas Regulation compliance deadlines are compressing replacement cycles across legacy infrastructure.
- Chemical Manufacturing:Process gas recovery and feedstock handling demand corrosion-resistant materials and real-time leakage monitoring. German and Dutch operators are bundling compressor upgrades with full system refrigerant transitions to natural working fluids.
- Pharmaceuticals:Sterile gas handling and API manufacturing require oil-free diaphragm systems with validated contamination protocols. Regulatory inspection intervals under the EU's Industrial Emissions Directive expand aftermarket service addressable space.
- Food & Beverage:Packaging, carbonation, and pneumatic conveying favor rotary screw technology for its continuous-duty reliability and lower total cost of ownership in high-volume production environments.
Oil and gas commands the largest share of equipment procurement value; chemical manufacturing is climbing the fastest on hydrogen feedstock transition.
Application:
Pressure ratio requirements and duty cycle profiles determine technology selection, with continuous-flow applications favoring rotary architectures and batch processes tolerating reciprocating pulsation.
- Natural Gas Processing:Upstream gathering, dehydration, and compression for pipeline injection require robust mechanical integrity under variable inlet conditions. Offshore platform electrification is specifying integrated permanent magnet motor packages for efficiency gains.
- Refrigeration:Industrial cooling and cold chain logistics face EU F-Gas Regulation containment mandates that mandate double-mechanical seal conversions and real-time monitoring retrofits.
- Wastewater Treatment:Aeration and biogas recovery applications favor lower-pressure vane and rotary screw configurations for their tolerance of humid inlet streams and intermittent duty cycles.
- Pneumatic Conveying:Bulk material handling in food processing and chemical plants requires oil-free air delivery, with rotary screw systems dominating specification for their flow stability.
Natural gas processing retains the deepest installed base; refrigeration is gaining share fastest on regulatory-driven equipment turnover.
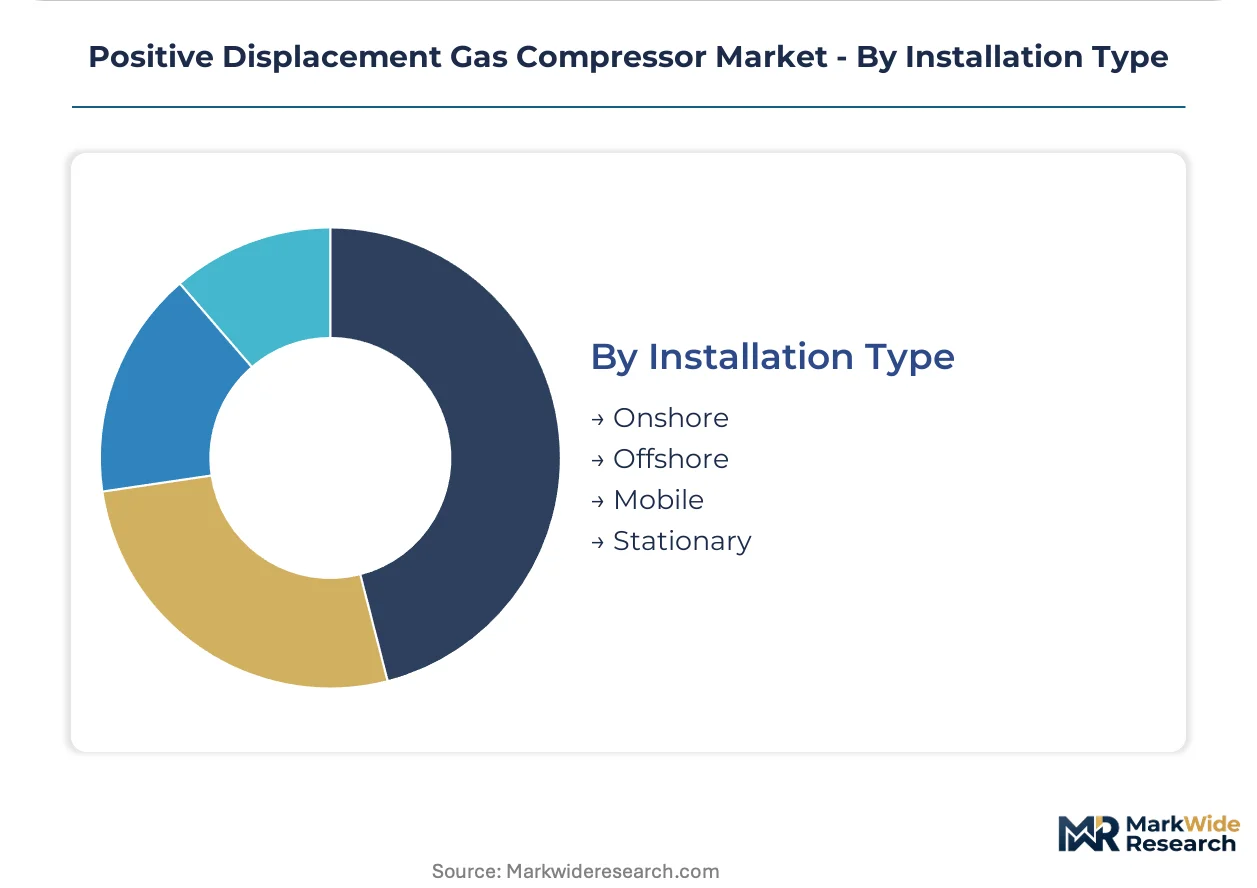
Installation Type:
Environmental exposure and mobility requirements dictate enclosure specifications, with offshore and mobile applications commanding premium engineering margins.
- Stationary:Fixed industrial installations in petrochemical corridors and hydrogen hubs allow optimized foundation mounting and integrated utility connections. These systems capture the highest share of aftermarket service contract value.
- Onshore:Field-deployed units for pipeline compression and remote gas processing balance portability against durability, with modular skid mounting accelerating deployment timelines.
- Offshore:Platform-mounted compressors for gas reinjection and export compression require marine-grade corrosion protection and compact footprints. Electrification trends are displacing mechanical drive configurations.
- Mobile:Trailer-mounted and containerized systems serve temporary production, maintenance, and emergency backup roles where rapid relocation outweighs efficiency optimization.
Stationary installations anchor the revenue base; offshore is expanding most quickly on platform electrification and hydrogen export infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, China, and the US Gulf Coast petrochemical corridor, with national hydrogen utilities and integrated oil majors recalibrating procurement volumes across these hubs.
United States
Hydrogen fueling station deployments and offshore platform electrification drive specification for high-pressure reciprocating packages. EPA New Source Performance Standards tighten methane leakage thresholds, compelling equipment replacement across legacy natural gas infrastructure. The US Gulf Coast petrochemical corridor anchors procurement volume as supermajors consolidate vendor relationships.
Germany
National hydrogen mission targets and electrolyzer manufacturing clusters accelerate demand for diaphragm and reciprocating compressor systems. EU F-Gas Regulation amendments mandate double-mechanical seal conversions and real-time leakage monitoring retrofits. The Ruhr industrial region and Bavarian hydrogen hubs concentrate deployment timelines for low-emission equipment.
China
Electrolyzer capacity buildout and hydrogen fueling network expansion drive procurement of high-pressure compression systems. Dual carbon goals under MEE oversight compress allowable emissions intensity across process gas applications. Yangtze River Delta manufacturing clusters integrate compressor procurement with domestic electrolyzer supply chains.
South Korea
Semiconductor fab expansion creates demand for oil-free diaphragm compressors with sub-ppb contamination control. KOSHA process safety requirements and national hydrogen economy roadmaps shape equipment specification criteria. Gyeonggi-do and Chungcheongnam-do industrial zones concentrate electronics-grade gas handling procurement.
India
National hydrogen mission targets and PLI scheme incentives open compressor procurement windows as electrolyzer manufacturing clusters emerge. CEA technical standards and state-level hydrogen policies frame equipment qualification requirements. Gujarat and Maharashtra industrial corridors attract initial deployment of fueling station infrastructure.
Positive Displacement Gas Compressor Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue hydrogen-specific specialization and aftermarket service unbundling. The market structures around three tiers: full-line industrial conglomerates with dense service networks, mid-scale specialists in high-pressure or oil-free applications, and regional fabricators serving price-sensitive procurement. Competitive moves concentrate on API 618 certification acquisition and predictive maintenance platform integration.
Among European-headquartered industrial groups, Atlas Copco and Burckhardt Compression exemplify the full-line archetype with installed base density across Nordic and Central European hydrogen hubs. Ingersoll Rand occupies a position within the North American rotary screw specialization tier, serving continuous-duty industrial applications. These three entities represent contrasting geographic anchors and technology emphases without exhaustive portfolio overlap.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Ariel Corporation |
| Burckhardt Compression |
| Siemens Energy |
| Baker Hughes |
| Gardner Denver |
| Bauer Compressors |
| SIAD Macchine Impianti |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up aftermarket service specialists have consolidated independent repair networks across the US Gulf Coast and German hydrogen corridors, compressing OEM captive pricing power while fragmenting spare parts procurement into competitive spot markets. This ownership pattern tightens margin discipline for compressor manufacturers forced to unbundle service contracts from equipment sales.
Pricing Analysis
High-volume rotary screw deployments capture thinner margins per unit than low-volume reciprocating packages for hydrogen fueling stations, creating a bifurcated margin structure across the product spectrum. Three-tier pricing structure across premium, standard, and economy levels separates API 618-certified systems from ISO-compliant industrial units and non-certified regional fabricators. Cost compression in standard-tier rotary equipment is intensifying because Chinese electrolyzer OEMs are driving procurement scale and demanding vendor price concessions. Chemical manufacturers exhibit the sharpest price sensitivity due to compressed capital budgets under EU F-Gas compliance deadlines, while offshore platform operators absorb premium pricing for marine-grade specifications.
Supply Chain Analysis
API 618 and ISO 10494 certification requirements gate supplier entry for critical crankshaft and piston ring components, concentrating precision machining capacity in Germany and Japan. Aerospace-grade stainless steel supply draws from nickel and cobalt feedstock anchored in Indonesian and Congolese extraction, exposing high-pressure compressor manufacturers to commodity volatility. Single-source vulnerability permeates tier-two precision forging, where German and Japanese specialists dominate without qualified alternatives. Distribution runs through OEM-direct channels for large project sales and authorized distributor networks for standard industrial replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The positive displacement gas compressor market sits in a technology-transition phase as integrated permanent magnet motor packages displace conventional mechanical drive configurations across continuous-duty applications below 100 bar.
For Market Incumbents: Deploy aftermarket service density as a retention lever by embedding vibration analytics and edge computing into installed base monitoring platforms. Consolidate tier-two machining suppliers through equity partnerships or long-term offtake agreements to secure crankshaft and piston ring supply against single-source disruption. Counter independent service provider encroachment by bundling predictive maintenance subscriptions with extended warranty coverage for hydrogen fueling station deployments. For New Entrants and Emerging Players: The premium-to-economy price gap in high-pressure reciprocating equipment creates entry space for mid-tier specialists offering API 618-compliant systems at 15-25% discount to established OEMs. Target India's electrolyzer manufacturing clusters under PLI scheme incentives, where domestic content requirements favor local assembly partnerships over fully imported units. Pursue semiconductor fab gas handling in South Korea through contamination-control certification partnerships with existing diaphragm compressor technology licensors. For Investors and Strategic Acquirers: Distressed-cycle entries favor independent aftermarket service providers with API 618 and ISO 10494 certification in the North American petrochemical corridor, where buyer consolidation among supermajors has compressed OEM service margins and created acquisition targets. Long-term viability hinges on hydrogen infrastructure buildout maturation across Germany, China, and the US Gulf Coast. Watch for inflection in nickel and cobalt price stabilization as the signal to accelerate deployment of capital into high-pressure reciprocating manufacturing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| API 618 Certification Acquisition | Qualification for high-risk hydrogen fueling and offshore gas reinjection projects under EPA and EU F-Gas mandates. |
| Predictive Maintenance Platform Integration | Enables compressor-as-a-service recurring revenue models through vibration analytics and edge computing deployment. |
| Backward Integration into Precision Forging | Secures captive supply of critical crankshaft and piston ring components against German and Japanese supplier concentration. |
| Electronics-Grade Contamination Control Partnership | Opens semiconductor fab procurement in Taiwan and South Korea through sub-ppb diaphragm compressor validation. |
| Electrolyzer Manufacturing Cluster Co-Location | Aligns compressor assembly capacity with hydrogen hub development in Gujarat, Maharashtra, and Yangtze River Delta zones. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and hydrogen utility planning officers. EPA New Source Performance Standards documentation, EU F-Gas Regulation amendment texts, and API 618 certification databases provided compliance-driven demand quantification. Bottom-up equipment shipment tallies triangulated against top-down hydrogen infrastructure investment forecasts to validate market sizing.
Granularity-level modeling deployed product-type, end-user vertical, application, and installation-type dimensions at country-level resolution across the analysis window. CAGRs derived from weighted average of electrolyzer capacity buildout trajectories, regulatory compliance deadline clustering, and replacement cycle acceleration in industrial refrigeration. Hydrogen fueling station deployment pipelines and semiconductor fab construction schedules served as industry-specific demand proxies.
Underlying measurement precision varies by segment; rotary screw compressor volumes carry tighter precision than diaphragm compressor projections due to more consolidated supplier reporting. Forecasts reflect assumptions around regulatory harmonization between North American and European emission protocols and sustained nickel-cobalt alloy pricing within historical bands. A model refresh is warranted upon material change in EPA methane leakage threshold enforcement or EU F-Gas Regulation amendment timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Axial Compressor Market
Compressors
Centrifugal Compressors Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Chlorine Compressors Market
Compressors
Industrial Air Compressor Market
Compressors
LNG Compressor Market
Compressors
Booster Compressor Market
Compressors
Scroll Compressor Market
Compressors
Portable Air Compressor Market
Compressors
Centrifugal Air Compressor Market
Compressors
Process Gas Compressors Market
Compressors
Asia-Pacific Compressor Oil Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Oil Filled Air Compressor Market
Compressors
CNG Compressor Market
Compressors
Root Blower Market