
 Multi-Stage Centrifugal Pumps Market | 2026-2036
Multi-Stage Centrifugal Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Stage Centrifugal Pumps Market Foresight
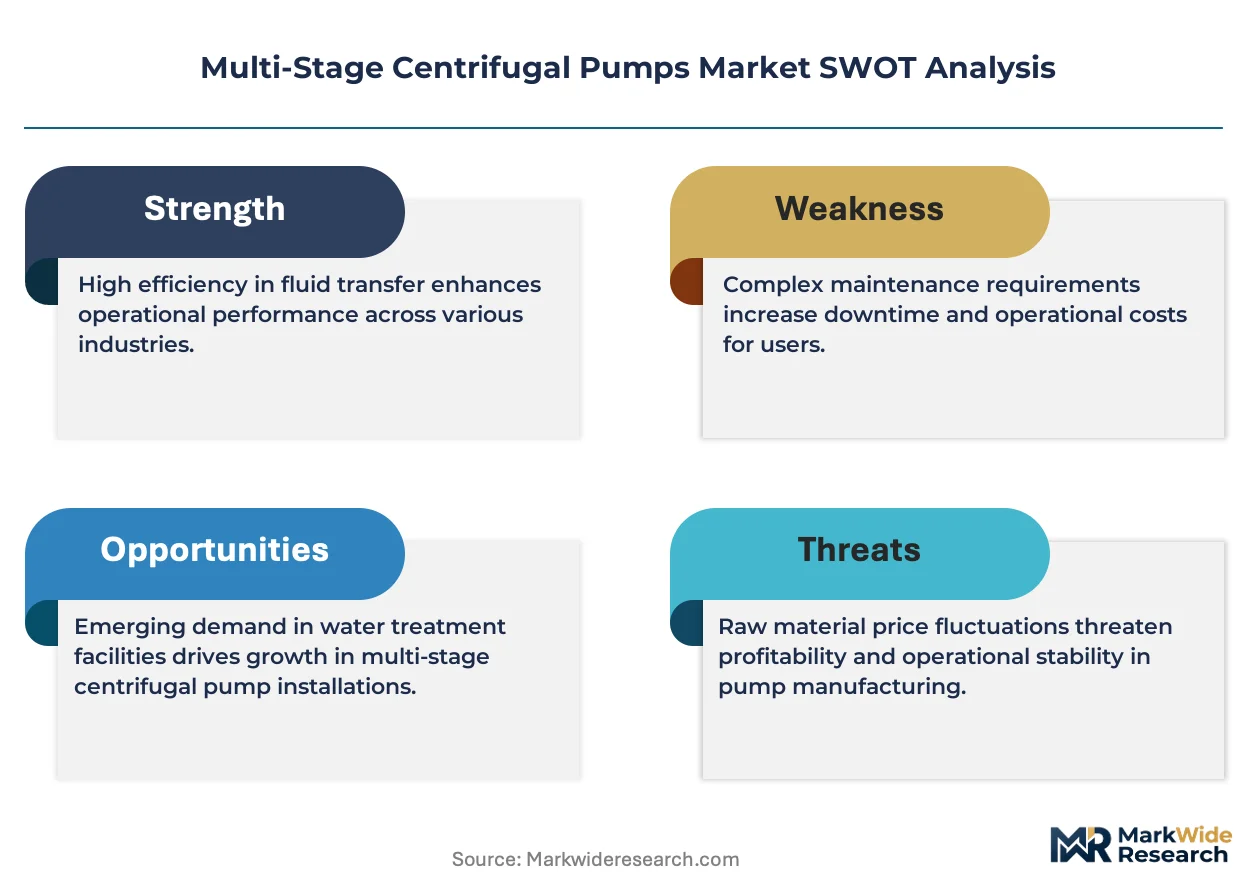
Direct distribution through OEM-aligned channel partners is reconfiguring how multi-stage centrifugal pumps reach industrial buyers in North America and Europe. Grundfos leverages its vertically integrated manufacturing network to control lead times for custom-configured vertical pump skids. Flowserve Corporation competes through aftermarket service contracts that anchor long-term revenue streams in oilfield and power generation accounts.
Multi-stage centrifugal pumps are pressure-boosting devices containing two or more impellers mounted on a common shaft within a single casing, with each successive stage increasing discharge pressure through serial energy addition; flow rates typically range from 5 to 30,000 cubic meters per hour depending on stage count and impeller diameter. These pumps serve critical fluid transport duties in water distribution networks, boiler feed systems, and hydrocarbon processing where single-stage designs cannot achieve required head pressures. Stainless steel product configurations command premium positioning due to corrosion resistance requirements in chemical handling and desalination pre-treatment stages. Horizontal installation formats dominate mature industrial retrofit markets where existing foundation footprints constrain equipment selection, while submersible configurations capture fastest-growing share in deep-well water extraction and offshore platform seawater lift applications.
EPA energy efficiency standards under the Clean Water Act and EU Ecodesign Directive shape minimum performance requirements for pumps sold into municipal and industrial water systems, forcing manufacturers to redesign hydraulic sections and motor couplings. China's GB standards for pump efficiency and NPSH performance create separate certification pathways for equipment entering state-owned utility procurement programs. Stakeholders must monitor how regional efficiency mandates diverge and determine whether platform standardization or market-specific product variants better protect margin structures across regulatory jurisdictions.
Market Dynamics
Water infrastructure operators are consolidating procurement specifications around energy efficiency metrics, forcing pump manufacturers to redesign hydraulic geometries and motor systems to meet tightening EPA and EU Ecodesign thresholds.
Growth Catalysts
- EPA Clean Water Act mandates:Municipal utilities in the United States face binding energy conservation requirements that accelerate replacement of aging vertical turbine installations with high-efficiency multi-stage systems.
- China's industrial corridor expansion:Municipal water infrastructure upgrades across the Yangtze River Delta and Pearl River Delta are compressing replacement cycles for aging pump stations.
- Stainless steel corrosion resistance:Chemical handling and desalination pre-treatment stages specify super-duplex and 316L configurations that command sustained premium positioning.
Market Restraints
- Specialized alloy input volatility:Nickel and chromium price swings compress margin predictability for stainless steel pump configurations.
- Foundry capacity concentration:Large casting production for multi-stage casings clusters in select Asian manufacturing zones, creating supply vulnerability.
- Positive displacement substitution:Progressing cavity and diaphragm pumps capture niche high-viscosity applications where centrifugal efficiency degrades.
Strategic Opportunities
- Sub-Saharan municipal water gaps:Underpenetrated distribution networks in Nigeria and Kenya present retrofit potential for solar-powered submersible multi-stage units.
- Hydrogen electrolyzer feedwater:Green hydrogen production facilities require ultra-high-pressure boiler feed pumps at scales not previously served by standard product lines.
- EU F-Gas Regulation phase-down:Refrigeration and HVAC system conversions create demand for seal-less magnetic drive configurations in hydrocarbon handling.
Industry Challenges
- Hydraulic engineer scarcity:Specialized computational fluid dynamics expertise required for custom impeller design concentrates at legacy OEM engineering centers.
- Legacy foundation incompatibility:Horizontal installation retrofits confront dimensional constraints from 1960s-era concrete footprints that resist modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Stage Centrifugal Pumps Market |
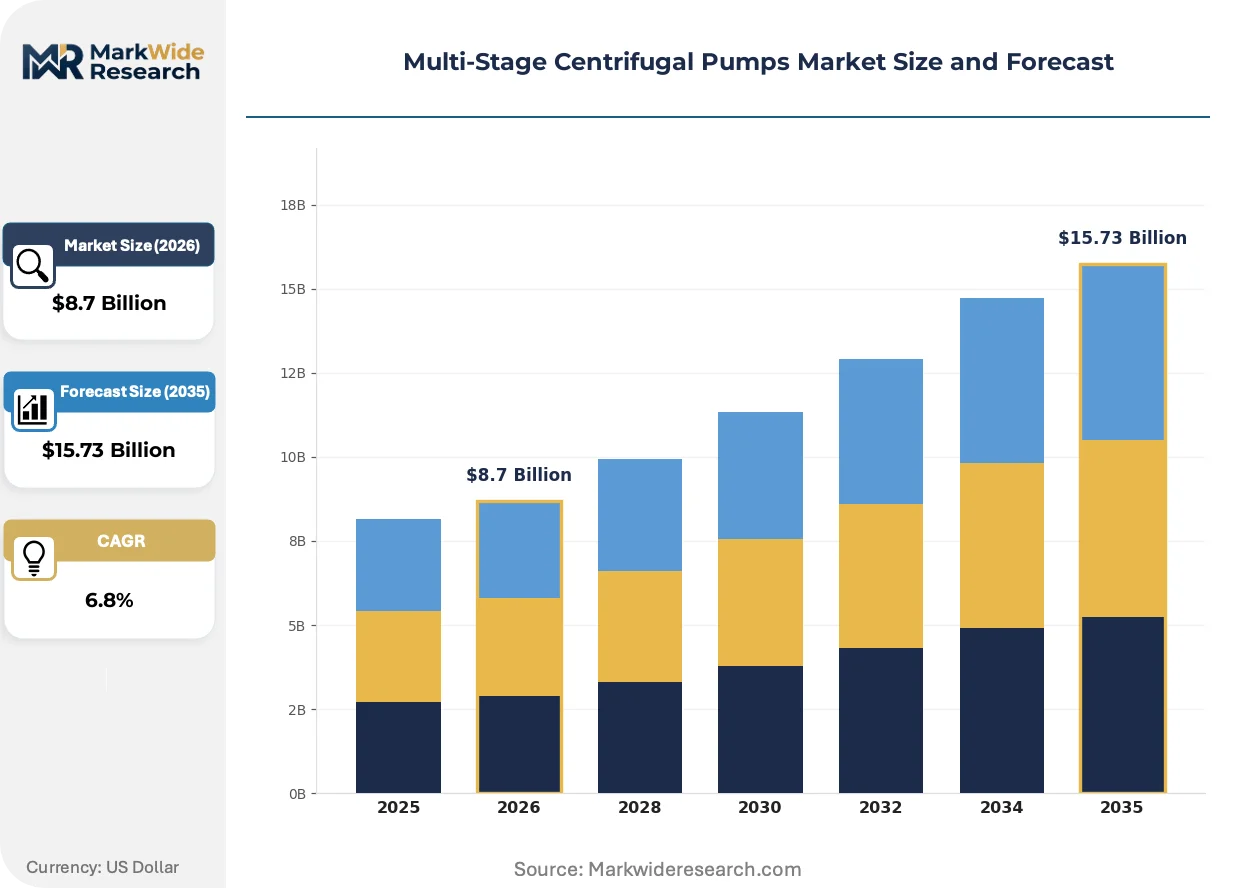
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Cast Iron, Bronze, Plastic Application: Agricultural, Industrial, Municipal, HVAC End User: Energy, Water Treatment, Manufacturing, Fire Protection Installation: Horizontal, Vertical, Submersible, Portable |
| Companies Covered | Grundfos, Xylem, Flowserve Corporation, Ebara Corporation, KSB, The Weir Group, Sulzer, Kirloskar Brothers Limited, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Stage Centrifugal Pumps Market Shifts & Advancements
Digital monitoring systems and advanced metallurgy are converging to redefine performance benchmarks across municipal and industrial pump installations.
Variable frequency drive integration with permanent magnet synchronous motors is hybridizing traditional fixed-speed multi-stage architectures. Water treatment utilities in Germany and the Netherlands specify these packages for demand-responsive pressure management. The technology is hybridizing aftermarket service models toward predictive maintenance contracts that displace scheduled overhaul intervals.
The EU Ecodesign Directive's 2025 pump efficiency tier upgrades are mandating minimum hydraulic efficiency index thresholds for clean water pumps above 10 kW. Manufacturers serving European municipal accounts must redesign impeller vane geometries and optimize surface roughness. Stainless steel product configurations face the steepest compliance cost given material removal constraints during finishing operations.
Integrated pump-motor-control skid procurement is displacing component-by-component specification among North American industrial buyers. EPC contractors and end-users now source complete vertical pump packages with pre-programmed control logic. This pattern is most pronounced in Texas and California oilfield waterflood applications where commissioning speed determines project economics.
Multi-Stage Centrifugal Pumps Market Segmentation
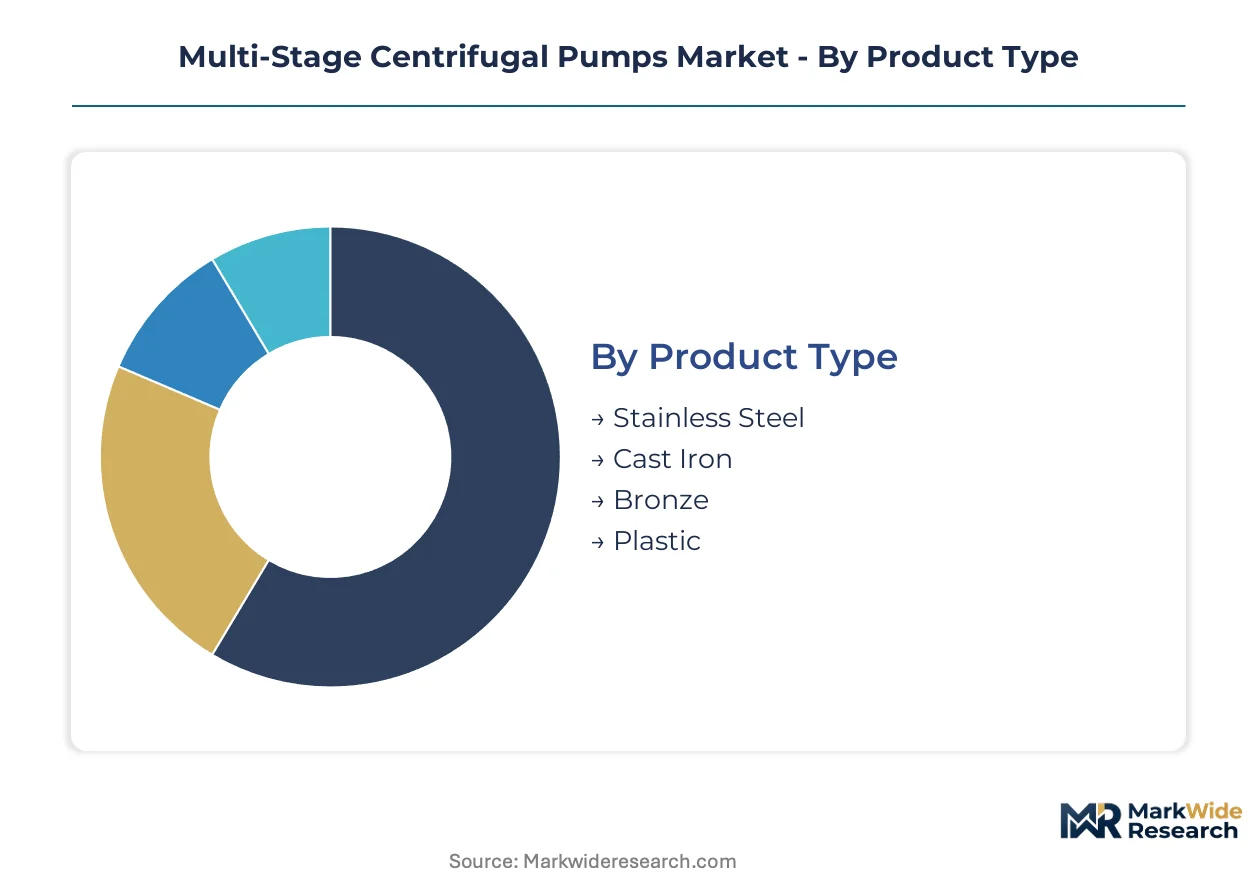
Segmentation in multi-stage centrifugal pumps reveals how material selection, duty cycle intensity, and installation constraints fragment procurement patterns across municipal utilities and industrial operators. Product configuration choices cascade through specification chains, determining which manufacturers qualify for project bids.
Product Type:
Maturity varies sharply across metallurgical tiers, with legacy materials defending installed base positions while corrosion-resistant alloys capture specification upgrades in chemical and desalination service.
- Stainless Steel:Super-duplex and 316L grades dominate chemical handling, seawater lift, and desalination pre-treatment where chloride attack degrades lesser alloys. Municipal utilities in Florida and Saudi Arabia specify these configurations for coastal intake stations facing accelerated corrosion cycles.
- Cast Iron:Gray and ductile iron castings retain cost advantage in clean water distribution and agricultural irrigation where chemical exposure remains minimal. Foundry capacity concentration in China's Hebei and Shandong provinces controls global supply availability for this segment.
- Bronze:Naval bronze alloys serve marine applications and select fire protection systems requiring galling resistance and moderate seawater tolerance.
- Plastic:Reinforced thermoset polymers capture niche chemical dosing and ultrapure water loops where metallic ion contamination must be eliminated entirely.
Cast iron retains volume leadership across agricultural and legacy municipal installations; stainless steel holds the steepest expansion curve as corrosion specifications tighten in coastal and chemical processing environments.
Application:
Customer archetypes diverge by capital intensity and specification authority, with municipal procurement governed by public tender protocols while industrial buyers prioritize lifecycle cost optimization.
- Agricultural:Center-pivot and flood irrigation systems in India's Punjab region and California's Central Valley drive demand for medium-head cast iron configurations. Groundwater depletion regulations in these jurisdictions are compressing replacement intervals as pumping depths increase.
- Industrial:Boiler feed, process water, and cooling circuits in Texas petrochemical complexes and Germany's Rhine-Ruhr manufacturing belt specify high-pressure multi-stage architectures. Energy recovery mandates in these geographies are forcing hydraulic efficiency upgrades during scheduled turnarounds.
- Municipal:Water distribution networks and wastewater lift stations in Nigeria's Lagos corridor and Kenya's Nairobi metropolitan area present retrofit potential for solar-powered submersible units.
- HVAC:Chilled water circulation and district heating substations in Nordic countries favor compact vertical inline configurations with integrated variable frequency drives.
Industrial applications command the highest average selling prices; municipal infrastructure in emerging economies represents the most rapidly expanding addressable base.
End User:
Operational criticality and regulatory exposure shape purchasing behavior, with energy sector buyers prioritizing reliability metrics while manufacturing facilities emphasize capital efficiency.
- Energy:Thermal power plants and combined cycle facilities in Indonesia and Vietnam require boiler feed pumps achieving discharge pressures above 200 bar. National utility procurement frameworks in these markets mandate local content thresholds that filter supplier eligibility.
- Water Treatment:Desalination plants in Israel's Mediterranean corridor and Australia's Perth region specify energy recovery turbine integration with high-pressure feed pumps. Reverse osmosis membrane fouling sensitivity demands precise flow control and minimal pressure pulsation.
- Manufacturing:Automotive paint circulation and semiconductor ultrapure water systems in Japan's Kyushu region and South Korea's Gyeonggi Province require seal-less magnetic drive configurations.
- Fire Protection:High-rise building sprinkler systems and industrial facility deluge networks in Dubai's commercial district specify vertical turbine pumps with listed approval from the country's civil defense authority.
Water treatment end users are expanding procurement fastest as desalination capacity scales; energy sector demand remains concentrated in capacity replacement rather than greenfield expansion.
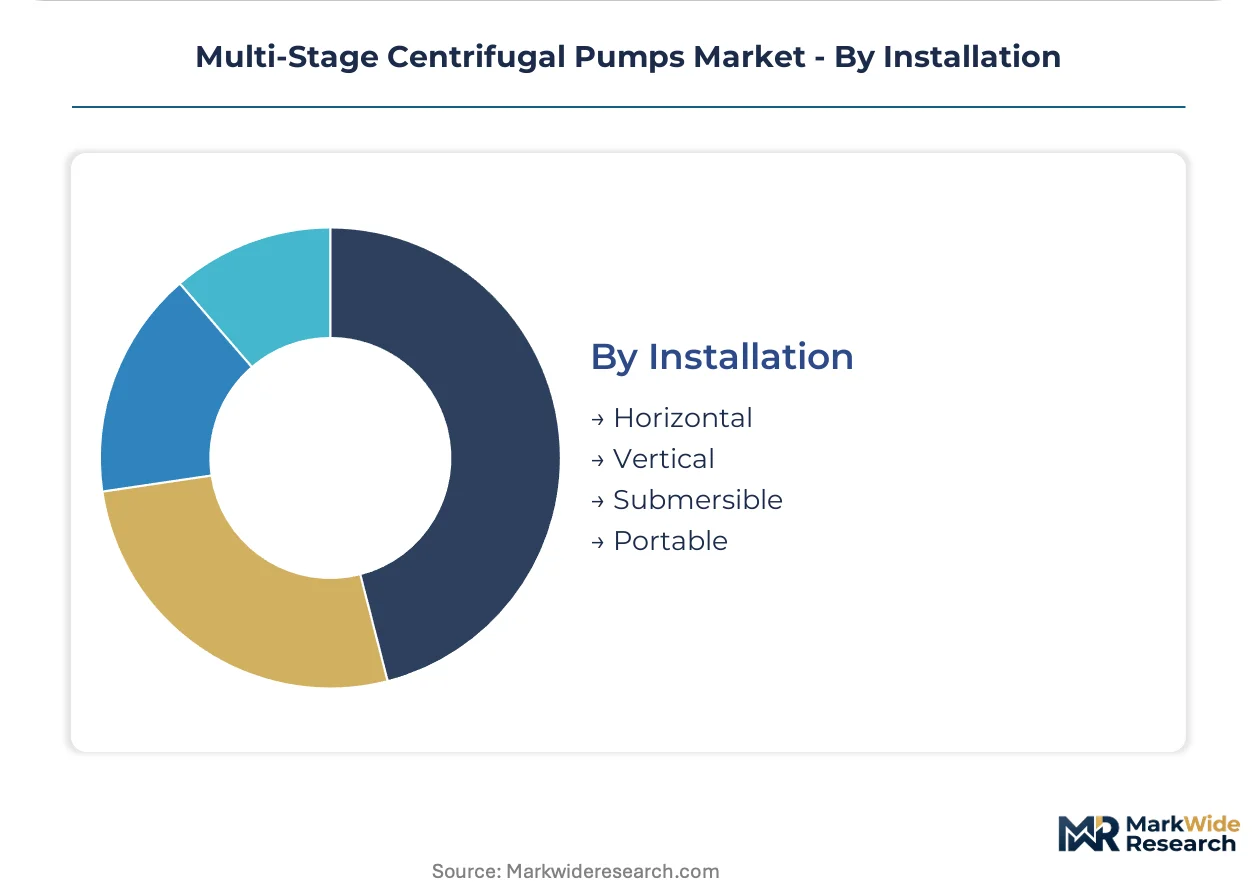
Installation:
Physical configuration constraints derive from existing civil infrastructure, with retrofit projects often dictating format selection regardless of hydraulic optimization preferences.
- Horizontal:Split-case and barrel designs dominate North American industrial retrofit markets where 1960s-era concrete foundations resist modification. Texas Permian Basin waterflood operators favor these formats for ease of bearing access and impeller adjustment.
- Vertical:Inline and turbine configurations serve space-constrained municipal pump stations and building services applications in Japan's dense urban corridors. Deep well installations in India's agricultural belt leverage these formats for borehole compatibility.
- Submersible:Motor-pump integrated units capture offshore platform seawater lift and deep groundwater extraction in Australia's Great Artesian Basin. Saltwater ingress protection and pressure-balanced motor designs distinguish premium offerings in this segment.
- Portable:Skid-mounted and trailer-based packages serve emergency dewatering, construction site temporary water supply, and military field operations requiring rapid deployment capability.
Horizontal formats defend installed base positions in mature industrial markets; submersible configurations are climbing the fastest as offshore oilfield and deep aquifer applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums for corrosion-resistant stainless steel configurations command 40-60% spreads in Germany and the Netherlands versus 15-25% in China's Hebei manufacturing belt, creating arbitrage pressure on procurement strategies.
United States
EPA Clean Water Act mandates compress replacement cycles for aging vertical turbine installations across Texas Permian Basin waterflood operations and California agricultural districts. Municipal utilities in Phoenix and Las Vegas face binding energy conservation thresholds that disqualify legacy pump specifications. Industrial buyers in Houston's petrochemical corridor consolidate procurement around integrated pump-motor-control skids.
Germany
The EU Ecodesign Directive's 2025 efficiency tier upgrades force hydraulic section redesigns for clean water pumps above 10 kW. Ruhr manufacturing belt utilities specify variable frequency drive integration with permanent magnet synchronous motors for demand-responsive pressure management. Stuttgart's automotive paint circulation systems require seal-less magnetic drive configurations.
China
GB standards for pump efficiency and NPSH performance create separate certification pathways for state-owned utility procurement programs. Yangtze River Delta municipal water infrastructure upgrades accelerate replacement cycles for aging pump stations in Shanghai and Suzhou. Foundry capacity concentration in Hebei and Shandong provinces controls global cast iron casing supply.
Saudi Arabia
Desalination capacity expansion along the Red Sea coast drives specification for super-duplex stainless steel configurations resisting chloride attack. The country's civil defense authority mandates listed approval for vertical turbine pumps in high-rise sprinkler systems across Riyadh's commercial district. NEOM development projects source submersible configurations for deep-well seawater extraction.
India
Groundwater depletion regulations in Punjab and Haryana compress replacement intervals as pumping depths increase for center-pivot irrigation systems. Bureau of Indian Standards certification requirements filter supplier eligibility for national agricultural pump subsidy programs. Bangalore's semiconductor fabrication parks specify plastic-lined configurations for ultrapure water loops.
Multi-Stage Centrifugal Pumps Market Competitive Landscape
Vertically integrated hydraulic specialists and regional foundry-integrated fabricators split the market between premium custom-engineered packages and standardized cast iron volumes. Consolidation concentrates among European and Japanese engineering groups controlling permanent magnet motor integration, while Chinese and Indian metalcasters defend cost positions in agricultural and legacy municipal segments. Two dominant competitive moves anchor rivalry: backward integration into foundry operations and aftermarket service contract anchoring. Technology licensing for computational fluid dynamics impeller optimization and strategic partnerships for solar-powered submersible distribution represent secondary vectors.
Within the premium engineering tier, Grundfos and Flowserve Corporation exemplify archetypes of vertically controlled manufacturing networks and aftermarket-anchored revenue streams respectively. Sulzer occupies a position bridging custom-engineered industrial packages with municipal water treatment specifications. These three entities represent divergent strategic postures rather than direct comparable competitors.
| Leading Market Players |
|---|
| Grundfos |
| Xylem |
| Flowserve Corporation |
| Ebara Corporation |
| KSB |
| The Weir Group |
| Sulzer |
| Kirloskar Brothers Limited |
| Baker Hughes Company |
| Others |
Supply & Pricing Matrix
Shanghai-to-Rotterdam container freight corridors impose volatile landed cost differentials on stainless steel pump configurations, amplifying price spreads between Hebei foundry outputs and European fabrication centers while forcing procurement managers to arbitrage inventory timing against alloy price cycles.
Pricing Analysis
Configured-to-order pricing commands substantial premiums over standard catalog configurations in multi-stage centrifugal pumps. Project-based pricing dominates municipal utility tenders where hydraulic customization and site-specific foundation constraints require engineering hours. Price differentiation hinges on corrosion-resistant alloy grades and EPA or EU Ecodesign certification tiers. Cost compression in cast iron segments is intensifying because Hebei foundry overcapacity feeds aggressive export pricing. Agricultural buyers in India's groundwater-depleted districts exhibit highest price sensitivity, while desalination operators in Saudi Arabia and Israel show least sensitivity given lifecycle cost optimization mandates.
Supply Chain Analysis
Upstream nickel and chromium feedstock markets in Indonesia, South Africa, and Russia anchor super-duplex stainless steel cost structures for corrosion-resistant pump configurations. Hebei and Shandong provinces in China supply gray and ductile iron castings, while German and Japanese engineering centers concentrate permanent magnet motor integration. Single-source vulnerability clusters in Asian foundry zones expose lead time volatility when environmental compliance inspections interrupt production. Distribution runs through OEM-aligned channel partners in North America and Europe, with direct specification authority consolidating among EPC contractors for integrated skid packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-stage centrifugal pumps sit in early-cycle expansion as hydrogen electrolyzer feedwater specifications and sub-Saharan municipal water gaps open addressable demand segments not served by legacy product architectures.
For Market Incumbents: Insulate margin structures by securing captive foundry capacity in Hebei or Shandong provinces against nickel price volatility and supply interruption risks. Anchor aftermarket service contracts with predictive maintenance telemetry to displace scheduled overhaul intervals and lock out progressing cavity pump substitutes in high-viscosity niches. For New Entrants and Emerging Players: Solar-powered submersible configurations for Nigerian and Kenyan municipal distribution networks represent the most penetrable entry point given underdeveloped local fabrication capacity and donor-funded procurement pipelines. Target hydrogen electrolyzer boiler feed specifications as a specification-influence opportunity before incumbent product lines adapt to ultra-high-pressure requirements. For Investors and Strategic Acquirers: Regional foundry-integrated fabricators with GB standards certification and state-owned utility procurement relationships in China offer asymmetric exposure to Yangtze River Delta infrastructure replacement cycles. Monitor F-Gas Regulation phase-down implementation velocity in EU refrigeration conversions as a demand inflection signal for seal-less magnetic drive configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Operations | Captive casting capacity in Hebei insulates margin predictability against nickel price cycles. |
| Predictive Maintenance Service Contracts | Digital telemetry integration with German municipal utilities displaces scheduled overhaul revenue models. |
| Hydrogen Electrolyzer Feedwater Specialization | Ultra-high-pressure pump development addresses green hydrogen facility specifications in Texas and Rotterdam. |
| GB Standards Certification Investment | China state-owned utility procurement eligibility requires separate NPSH performance testing protocols. |
| Solar-Powered Submersible Distribution Partnerships | Donor-funded municipal water projects in Lagos and Nairobi favor integrated renewable-powered packages. |
Research Methodology
A spread of perspectives from plant engineers at Texas petrochemical complexes, procurement leads at Saudi desalination operators, aftermarket service heads at European OEMs, and hydraulic R&D directors at Japanese engineering groups converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, SEC 10-K filings, EPA enforcement databases, and EU Ecodesign compliance registries. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Demand-supply balance modeling anchored volume projections across product type, application intensity, installation format, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers including water infrastructure capital expenditure cycles and industrial energy efficiency mandate implementation schedules. Forecast inputs incorporated foundry capacity utilization rates in Hebei and Shandong provinces alongside permanent magnet motor cost curves.
Practitioners should monitor nickel and chromium price volatility, EPA enforcement intensity on Clean Water Act compliance deadlines, and GB standards certification pathway changes for early signals requiring forecast revision. Cross-checking against IEA water infrastructure investment databases and national utility procurement announcement trackers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Twin Screw Pumps Market
Pumps and Control Devices
Europe Asia Submerged Pump Market
Pumps and Control Devices
Automatic Water Level Controller Market
Pumps and Control Devices
Solar Pump Market
Pumps and Control Devices
Turbomolecular Pumps Market
Pumps and Control Devices
Global Hydraulic Gear Pump Market
Pumps and Control Devices
Drum Pump Market
Pumps and Control Devices
Europe, Middle-East and Africa Diaphragm Pump Market
Pumps and Control Devices
Axial and Mixed Flow Pumps Market
Pumps and Control Devices
Global Vacuum Pump Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Global Mobile Hydraulic Pump Market
Pumps and Control Devices
Sanitary Pumps Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Domestic Booster Pump Market