
 Oil-Free Air Compressor Market | 2026-2036
Oil-Free Air Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Oil-Free Air Compressor Market Analysis
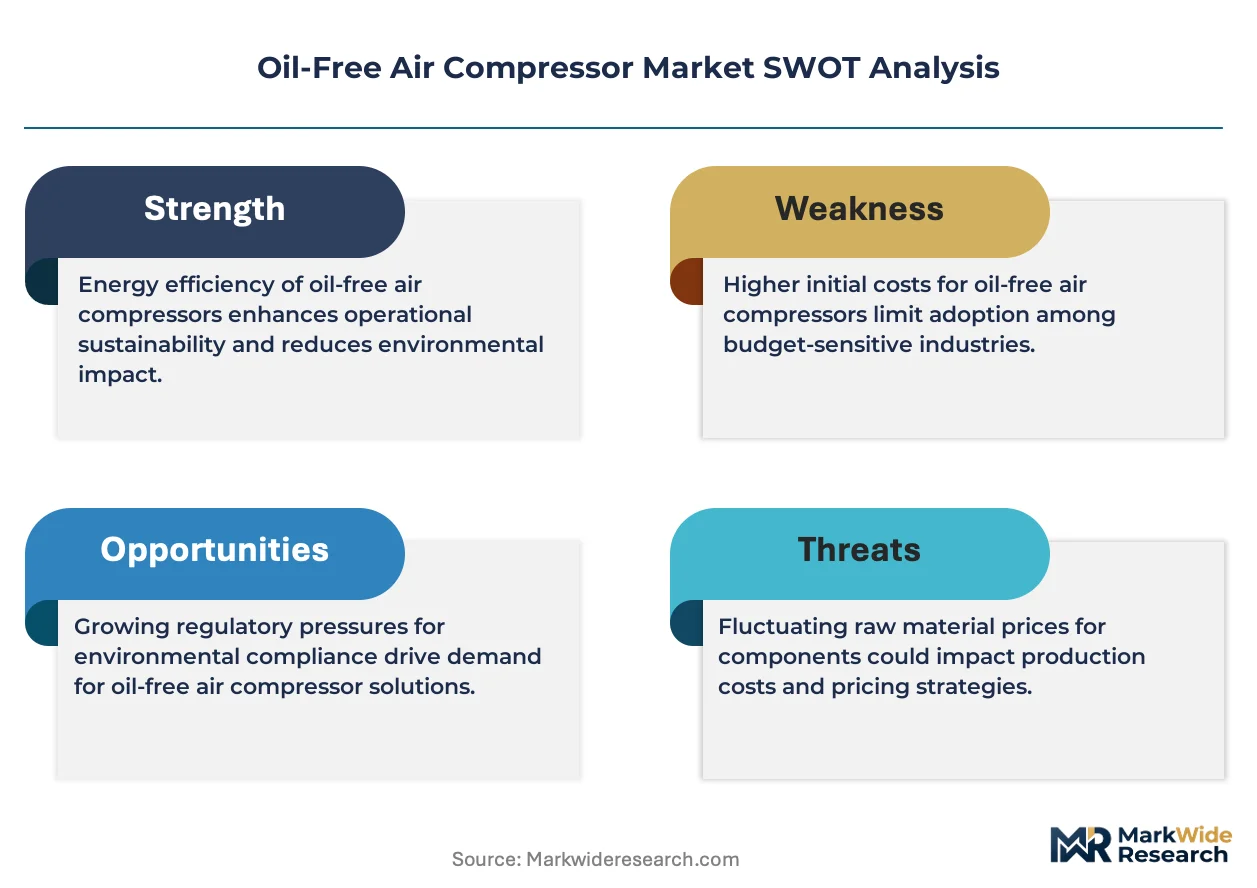
Pharmaceutical manufacturing is expanding its share of oil-free compressor procurement as aseptic processing standards harden across regulated markets. Atlas Copco leverages its water-injected rotary screw portfolio to anchor European pharmaceutical demand. Ingersoll Rand sustains North American market presence through dedicated cleanroom-certified product lines. KAESER KOMPRESSOREN competes on energy efficiency ratings that differentiate its offerings in cost-sensitive manufacturing segments.
An oil-free air compressor delivers compressed air without lubricant contact with the airstream, typically achieving ISO 8573-1 Class 0 certification through water-injected, dry-running, or centrifugal designs operating at discharge pressures from 7 to 13 bar. Rotary screw compressors dominate unit volume in manufacturing and food processing where continuous duty cycles predominate. Centrifugal compressors lead in absolute power delivery above 200 HP for petrochemical and large-scale electronics fabrication. Scroll compressors occupy the lower power tier below 50 HP where laboratory and point-of-use pharmaceutical applications demand minimal pulsation and near-silent operation.
FDA mandates on compressed air purity in pharmaceutical and food processing directly shape product certification requirements and validation documentation burdens for suppliers. EMA's Annex 1 revisions on sterile manufacturing and EPA energy efficiency standards for industrial equipment collectively force technology upgrades across installed bases. Stakeholders must monitor how evolving ISO 8573-1 test protocols and regional carbon intensity regulations reshape total cost-of-ownership calculations and retrofit timelines.
Market Dynamics
Water-injected rotary screw technology is compressing total cost-of-ownership advantages against dry-running designs, forcing incumbent suppliers to reconfigure product architectures and validation documentation for pharmaceutical cleanroom certification.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revisions:European pharmaceutical facilities face mandatory compressed air purity upgrades, accelerating replacement cycles for legacy lubricated systems.
- Food processing automation:USDA and FDA hazard analysis mandates in meat, dairy, and beverage packaging drive oil-free specification in high-volume continuous production lines.
- Electronics fabrication clustering:Semiconductor and battery cell manufacturing concentration in Germany, China, and the United States generates concentrated demand for ISO 8573-1 Class 0 systems.
Market Restraints
- Specialized alloy input costs:Stainless steel and corrosion-resistant coatings for airstream components expose manufacturers to commodity volatility and extended procurement lead times.
- Technical performance ceiling:Water-injected designs face pressure ratio limitations above 13 bar, restricting addressable markets in heavy petrochemical and mining applications.
- Validation documentation burden:FDA and EMA pharmaceutical qualification protocols extend sales cycles and inflate pre-revenue engineering costs for suppliers.
Strategic Opportunities
- India pharmaceutical manufacturing expansion:CDSCO alignment with international GMP standards creates demand for certified oil-free infrastructure in active pharmaceutical ingredient production.
- Carbon intensity regulations:EU Green Deal industrial decarbonization targets position high-efficiency oil-free compressors as qualifying equipment for green capital subsidies.
- Predictive maintenance convergence:Integration of IoT sensor arrays with compressor control systems enables outcome-based service monetization and remote performance optimization.
Industry Challenges
- ISO 8573-1 test protocol evolution:Expanding purity measurement requirements force recertification investments and create temporary competitive uncertainty during standard transition periods.
- Cleanroom integration complexity:Pharmaceutical and electronics buyers demand seamless interoperability with existing HVAC, filtration, and monitoring infrastructure, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil-Free Air Compressor Market |
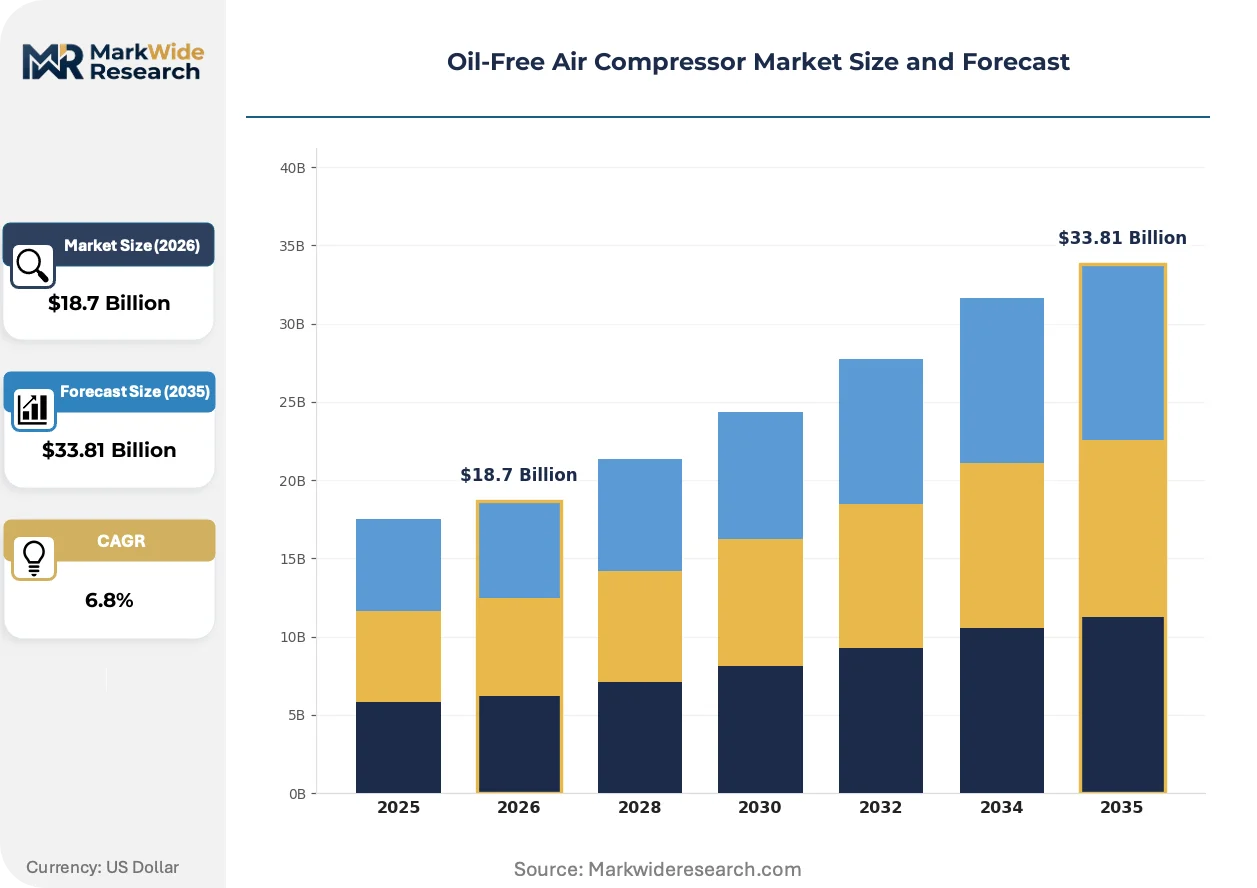
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scroll Compressors, Reciprocating Compressors, Centrifugal Compressors, Rotary Screw Compressors End User: Manufacturing, Pharmaceuticals, Food & Beverage, Electronics Installation: Fixed Installation, Portable Installation, Stationary Installation, Modular Installation Power Rating: Less than 50 HP, 50-100 HP, 100-200 HP, Above 200 HP |
| Companies Covered | Atlas Copco, Ingersoll Rand, KAESER KOMPRESSOREN, Sullair, Gardner Denver, Aerzen, ELGi Equipments Limited, Boge Compressors, Hitachi Industrial Equipment Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil-Free Air Compressor Market Emerging Trajectories
Equipment architecture is fragmenting into standardized subsystems that permit rapid reconfiguration, while regulatory pressure and buyer sophistication compress traditional specification cycles.
Water-injected rotary screw compressor design is modularizing around standardized airend, drive, and control subsystems. Pharmaceutical and food processing buyers in Germany and Switzerland specify these configurations for accelerated validation and reduced spare parts inventory. This architecture compresses supplier engineering margins while enabling faster product line extensions across power ratings.
EPA energy efficiency standards for industrial equipment are tightening minimum performance thresholds for compressors above 200 HP. Petrochemical and electronics fabrication facilities in the United States face retrofit timelines or replacement obligations. Equipment suppliers are responding with permanent magnet motor integration and variable speed drive optimization to maintain eligibility for federal procurement contracts.
Buyer specification behavior is fragmenting between total cost-of-ownership modeling and first-cost minimization. Large pharmaceutical and semiconductor manufacturers in China and South Korea now mandate lifecycle energy analysis, while mid-tier food processors in Brazil and Mexico prioritize acquisition price. This bifurcation forces suppliers to maintain parallel product tiers with diverging feature sets and service bundling.
Oil-Free Air Compressor Market Segmentation
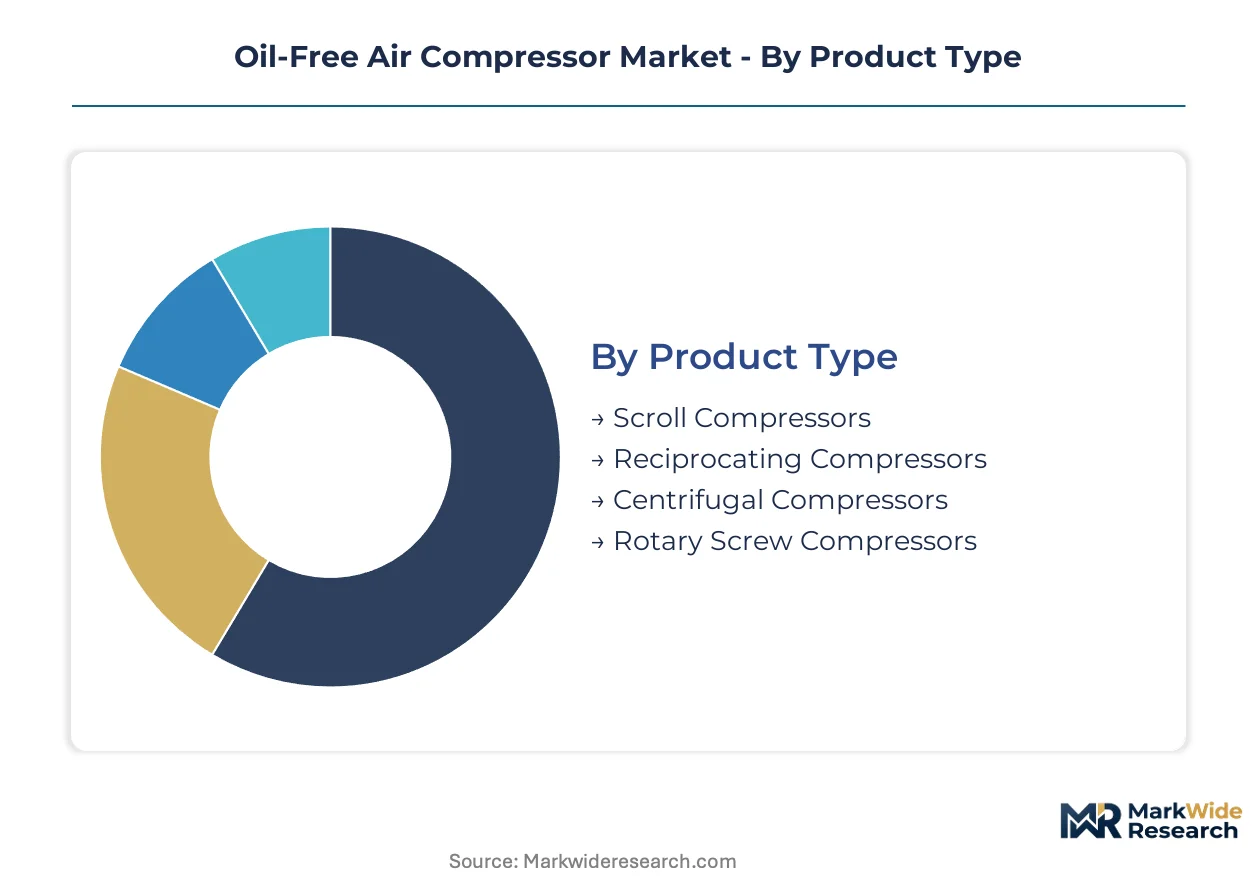
Segmentation in the oil-free air compressor market reflects divergent technical requirements across purity-critical applications and operational environments. Buyers select configurations based on integration depth, from standalone point-of-use units to embedded plant-wide systems. Understanding these divides exposes where suppliers can capture premium positioning versus commodity procurement cycles.
Product Type:
Standalone oil-free compressor systems operate independently with dedicated controls, while embedded designs integrate into larger process architectures requiring synchronized airflow management.
- Rotary Screw Compressors:Twin-rotor positive displacement mechanisms deliver continuous airflow at 7-13 bar discharge pressures through oil-free airend designs. Water-injected variants dominate pharmaceutical cleanrooms in Germany and Switzerland where FDA validation protocols mandate documented purity assurance. Dry-running configurations persist in food processing lines where water contamination risks outweigh efficiency trade-offs.
- Centrifugal Compressors:Dynamic compression through impeller stages achieves mass flow rates above 200 HP thresholds with absolutely oil-free airstreams. Semiconductor fabrication clusters in the United States and South Korea specify these for central plant air systems where single-point failure risks demand redundant staging and ISO 8573-1 Class 0 certification.
- Scroll Compressors:Orbiting spiral plate geometry generates pulsation-free output below 50 HP for laboratory and analytical instrumentation. Point-of-use pharmaceutical sampling stations and metrology labs favor these for near-silent operation.
- Reciprocating Compressors:Piston-driven positive displacement suits intermittent duty cycles and portable deployment scenarios. Maintenance-intensive valve systems limit adoption in continuous manufacturing environments.
Rotary screw compressors lead volumes today; centrifugal designs are gaining share fastest in high-capacity electronics fabrication.
End User:
Cost tier stratification separates capital-intensive precision manufacturing from price-sensitive volume processing segments.
- Pharmaceuticals:Aseptic filling lines, lyophilization, and sterile packaging operations require validated oil-free air systems with full traceability documentation. EMA Annex 1 revisions and FDA guidance on compressed air quality drive replacement of legacy lubricated infrastructure across European and North American facilities.
- Electronics:Semiconductor wafer fabrication, battery cell assembly, and flat-panel display manufacturing demand particulate-free and oil-free environments. Cleanroom specifications in Taiwan, South Korea, and the United States mandate centralized compressor architectures with redundant filtration trains.
- Food & Beverage:High-volume packaging lines for dairy, meat, and beverage products face USDA hazard analysis mandates. Mid-tier processors prioritize acquisition cost over lifecycle efficiency, fragmenting supplier pricing strategies.
- Manufacturing:General industrial automation and precision machining applications span the widest specification range. Automotive component plants in Mexico and Brazil drive volume procurement with standardized performance requirements.
Pharmaceuticals commands the steepest expansion trajectory; manufacturing retains the largest installed base.
Installation:
Volume concentration varies sharply between permanent plant infrastructure and mobile or reconfigurable deployment models.
- Fixed Installation:Permanent mounting with hard-piped distribution networks serves centralized plant air systems. Petrochemical and large-scale electronics facilities favor these for operational stability and minimal maintenance access requirements.
- Stationary Installation:Skid-mounted or pad-mounted configurations without permanent anchoring permit relocation within facility boundaries. Contract manufacturing and multi-product pharmaceutical plants specify these for production line flexibility.
- Modular Installation:Standardized subsystem architectures enable rapid reconfiguration across power ratings and purity grades. German and Swiss pharmaceutical buyers prioritize these for accelerated validation and reduced spare parts inventory.
- Portable Installation:Wheel-mounted or trailer-based units serve construction, mining, and temporary process applications. Oil-free specification remains limited to contamination-sensitive repair and maintenance scenarios.
Fixed installation dominates capital expenditure; modular configurations are climbing the fastest among regulated manufacturing segments.
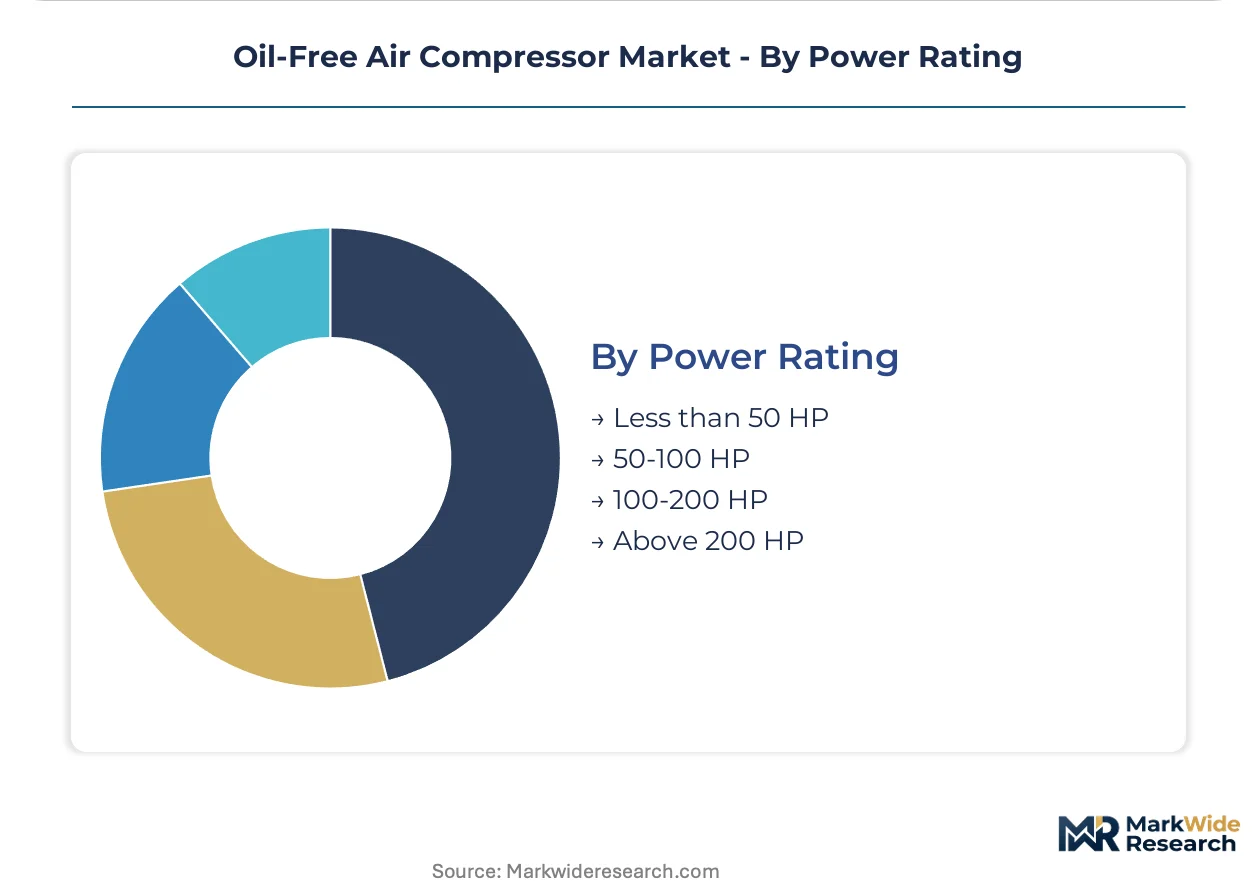
Power Rating:
Customer type fragmentation separates large-scale integrated manufacturers from distributed small-facility operators.
- Above 200 HP:Multi-stage centrifugal and large rotary screw systems serve central plant air stations. Electronics fabrication and petrochemical complexes in the United States face EPA energy efficiency retrofit timelines for equipment above this threshold.
- 100-200 HP:Mid-range rotary screw configurations balance capital efficiency with operational scale. Regional pharmaceutical manufacturing and food processing clusters in India and Southeast Asia concentrate procurement here.
- 50-100 HP:Compact rotary screw and large scroll designs serve standalone production lines. Automotive supplier parks and contract packaging operations favor this bracket for dedicated air independence.
- Less than 50 HP:Scroll and small reciprocating units dominate point-of-use and laboratory applications. Distributed pharmaceutical quality control labs and electronics assembly stations drive specification.
Above 200 HP systems anchor revenue concentration; below 50 HP segments are expanding most quickly in distributed manufacturing networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as pharmaceutical and electronics producers migrate toward jurisdictions with aligned certification standards and subsidy access. Cost-of-compliance gaps between mature and emerging markets are accelerating facility relocation decisions.
United States
Semiconductor fabrication clusters in Arizona and Texas drive concentrated demand for ISO 8573-1 Class 0 central plant systems. EPA energy efficiency standards for equipment above 200 HP mandate retrofit timelines for petrochemical and electronics facilities. Intel's Arizona fabs and Samsung's Taylor expansion anchor procurement volumes for large-scale centrifugal configurations.
Germany
Pharmaceutical manufacturing in Baden-Württemberg and Bavaria sustains premium demand for water-injected rotary screw systems with accelerated validation protocols. EMA Annex 1 sterile manufacturing revisions force compressed air purity upgrades across European facilities. Stuttgart and Munich precision engineering clusters prioritize modular subsystem architectures for reduced spare parts inventory.
China
Battery cell manufacturing concentration in Fujian and Jiangsu provinces generates demand for high-capacity oil-free infrastructure. MIIT industrial equipment efficiency guidelines and dual carbon goals incentivize technology upgrades across installed bases. CATL's Ningdao operations and BYD's Shenzhen facilities anchor regional procurement for electronics-grade air systems.
India
Active pharmaceutical ingredient production expansion in Maharashtra and Gujarat creates demand for CDSCO-aligned GMP certification. The PLI scheme for pharmaceutical manufacturing subsidizes infrastructure upgrades including compressed air systems. Mumbai-Pune and Ahmedabad-Vadodara pharmaceutical corridors concentrate specification activity for validated oil-free equipment.
South Korea
Semiconductor wafer fabrication in Gyeonggi Province and memory chip production in Icheon sustain demand for redundant-staged centrifugal architectures. MFDS pharmaceutical manufacturing standards and national carbon neutrality targets compress replacement cycles for legacy equipment. Samsung and SK Hynix facility expansions in Yongin and Icheon anchor central plant air system procurement.
Oil-Free Air Compressor Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in pharmaceutical-grade systems and fragmented competition in general industrial applications. The vendor landscape organizes around three archetypes: diversified industrial conglomerates with compressor divisions, dedicated compressed air specialists, and regional fabricators serving price-sensitive procurement. Capacity expansion and technology licensing represent the dominant competitive vectors as suppliers reposition around water-injected rotary screw architectures.
Among diversified industrial conglomerates, Atlas Copco and Ingersoll Rand exemplify scale-driven positioning across multiple power tiers and purity grades. KAESER KOMPRESSOREN occupies a specialist position within the German Mittelstand tier, representing energy-efficiency-focused competition in European pharmaceutical and food processing segments. These three anchors illustrate divergent strategic postures: conglomerate breadth versus specialist depth versus regional fabrication agility.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| KAESER KOMPRESSOREN |
| Sullair |
| Gardner Denver |
| Aerzen |
| ELGi Equipments Limited |
| Boge Compressors |
| Hitachi Industrial Equipment Systems |
| Others |
Supply Flow & Price Mechanics
Family-owned German Mittelstand specialists anchor supply-side discipline through generational capital structures that resist quarterly margin pressure, while their concentrated Baden-Württemberg and Bavaria manufacturing bases transmit localized input-cost volatility directly into pharmaceutical-grade pricing premiums.
Pricing Analysis
Distributor margin layers compress final pricing by 15-25 points below direct-OEM contracts, though pharmaceutical buyers absorb this markup for validation documentation and local service presence. Three-tier pricing structure across pharmaceutical-certified, food-grade, and general industrial levels separates ISO 8573-1 Class 0 systems from Class 1-3 alternatives. Cost compression in mid-tier food processing intensifies because Brazilian and Mexican buyers prioritize acquisition price over lifecycle efficiency. Contract manufacturing organizations exhibit highest price sensitivity; semiconductor fabs in Taiwan and South Korea demonstrate least sensitivity given single-point failure risks.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Chicago feed hub-and-spoke patterns that concentrate inventory risk with authorized distributors. Manufacturing draws from Germany, China, and the United States for precision-machined airends, with stainless steel castings sourced from India and specialty coatings from Japan. Single-source vulnerability persists in permanent magnet motors above 200 HP where Chinese rare-earth processing dominates. Distribution runs through OEM-direct channels for large electronics fabrication projects and authorized dealer networks for mid-tier manufacturing replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oil-free air compressor market reads as a late-cycle quality story as pharmaceutical and semiconductor buyers harden specifications around EMA Annex 1 and ISO 8573-1 Class 0 certification, displacing price-minimization behavior in procurement committees.
For Market Incumbents: Deepen backward integration into permanent magnet motor production to insulate margins from Chinese rare-earth volatility, while accelerating water-injected rotary screw certification documentation to defend against emerging Korean and Chinese specialists. Channel control through captive service networks represents the critical defensive lever against modular subsystem competitors. For New Entrants and Emerging Players: Begin with India pharmaceutical manufacturing corridors where CDSCO alignment with international GMP standards creates certified infrastructure demand without entrenched incumbent relationships. Contract packaging operations in Maharashtra and Gujarat offer the most penetrable entry point; lead with rapid validation documentation and localized spare parts inventory as the go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators serving price-sensitive Latin American and Southeast Asian food processing segments, where margin compression has outpaced operational restructuring. Five-to-ten year viability hinges on technology licensing access for water-injected architectures; monitor EMA and FDA guidance document releases as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Injected Rotary Screw Certification | EMA Annex 1 compliance validates pharmaceutical cleanroom positioning against dry-running alternatives. |
| Permanent Magnet Motor Integration | EPA efficiency thresholds above 200 HP mandate retrofit eligibility for federal procurement contracts. |
| Predictive Maintenance Platform Launch | IoT sensor convergence enables outcome-based service monetization at semiconductor fabrication clusters. |
| Regional Distribution Center Expansion | Localized inventory in Stuttgart and Shanghai compresses pharmaceutical validation timelines and spare parts lead times. |
| Modular Subsystem Standardization | Swiss and German pharmaceutical buyers prioritize rapid reconfiguration across power ratings and purity grades. |
Methodological Framework
Bottom-up pharmaceutical and electronics manufacturing modeling reconciled against top-down compressor production tracking forms the analytical core of this study. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads combined with secondary validation from EPA energy efficiency filings, EMA guidance documents, MIIT industrial equipment standards, and SEC 10-K disclosures from diversified industrial conglomerates. Triangulation across these sources ensures segmentation integrity across power ratings, purity grades, and regional regulatory clusters.
Input-output matrices connect airend production volumes, motor supply constraints, and validation documentation throughput to end-use demand across semiconductor fabrication, pharmaceutical sterile manufacturing, and food processing automation. Segmentation dimensions span product type, installation configuration, power rating tier, and end-use industry vertical. CAGRs derive from installed base replacement cycles, regulatory mandate timelines, and efficiency upgrade elasticity. Forecast inputs include EPA retrofit obligation schedules and EMA Annex 1 implementation phasing across European pharmaceutical facilities.
Several conditions sit outside the modeled scope, including tariff rate revisions affecting rare-earth magnet imports, unannounced ISO 8573-1 test protocol amendments, and sovereign subsidy program modifications in India and China. Forecasts reflect documented assumptions around regulatory enforcement consistency and commodity price stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Scroll Compressor Market
Compressors
Rotary Air Compressor Market
Compressors
Axial Compressor Market
Compressors
Compressed Air Lubricators Market
Compressors
Tandem Piston Compressors Market
Compressors
Stationary Air Compressor Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Positive-Displacement Hydrogen Compressor Market
Compressors
CNG Compressor Market
Compressors
Air and Gas Compressor Market
Compressors
Portable Air Compressor Market
Compressors
Industrial Air Compressor Market
Compressors
Rotary Lobe Compressor Market
Compressors
Compressed Air Filtration and Dryer System Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
High Speed Blowers Market