
 Compressor Wheel Market | 2026-2036
Compressor Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Compressor Wheel Market Intelligence
Modular turbocharger packaging is hardening as the dominant procurement format, with fleet operators and industrial buyers favoring pre-integrated compressor wheel-cartridge assemblies over standalone component sourcing. Garrett Motion Inc. leverages its captive foundry network to control titanium alloy supply for aerospace-grade wheels. BorgWarner Inc. anchors North American automotive OEM relationships through backward integration into precision casting operations. Cummins Turbo Technologies specializes in heavy-duty compressor wheel geometries calibrated for off-highway torque profiles.
A compressor wheel is a bladed impeller that accelerates and pressurizes intake air through centrifugal or axial force, typically machined from aluminum, titanium, or nickel-based superalloys to tolerances within microns for rotational balance at speeds exceeding 100,000 RPM. Its primary function is to deliver compressed air into combustion chambers or process systems, directly determining thermal efficiency and power density. Centrifugal compressor wheels occupy the largest volume share due to their dominance in automotive turbocharging, where cost-optimized aluminum castings sustain high-volume production economics. Titanium wheels represent the fastest-expanding material category as aerospace OEMs mandate weight reduction for next-generation turbofan architectures, while mixed-flow geometries are capturing margin pools in marine propulsion systems requiring surge tolerance across variable load bands.
EPA emissions benchmarks enforce compressor wheel efficiency thresholds for on-highway diesel platforms, compelling redesigns of blade aerodynamics and tip clearance controls. Euro 7 standards from EMA-aligned frameworks will extend these requirements to gasoline direct-injection systems, tightening alloy specifications and dimensional certification protocols. China's MIIT administers GB standards that prescribe material traceability and fatigue testing for domestically manufactured turbocharger components, shaping market access for foreign suppliers. Stakeholders must monitor regulatory divergence between EPA Tier 4, Euro 7, and China's evolving GB standards to align R&D pipelines with divergent certification timelines and avoid stranded tooling investments.
Market Dynamics
Material substitution toward titanium and Inconel alloys is compressing legacy aluminum supply chains as EPA Tier 4 and Euro 7 emissions mandates harden thermal efficiency requirements across commercial vehicle platforms.
Growth Catalysts
- EPA Tier 4 mandates:On-highway diesel platforms must achieve stricter nitrogen oxide thresholds, forcing compressor wheel redesigns with tighter tip clearances and advanced blade aerodynamics.
- China's eastern coastal clusters:Domestic turbocharger assembly capacity in Jiangsu and Zhejiang provinces is scaling rapidly, pulling component demand toward localized supply networks.
- Titanium alloy adoption:Aerospace OEMs pursuing next-generation turbofan weight reduction are specifying forged titanium wheels for high-RPM endurance at reduced mass.
Market Restraints
- Titanium sponge volatility:Primary titanium input costs fluctuate with aerospace demand cycles, squeezing margin stability for wheel producers without captive smelter arrangements.
- Superalloy supply concentration:Inconel feedstock for extreme-duty wheels concentrates among a narrow base of specialty foundries in Germany and the United States.
- Casting yield limitations:Precision investment casting of thin-section compressor blades maintains scrap rates above fifteen percent, constraining unit economics at volume.
Strategic Opportunities
- Marine mixed-flow geometries:Surge-tolerant wheel designs for variable-load propulsion systems remain underpenetrated outside European shipbuilding corridors.
- India's commercial vehicle fleet modernization:BS-VI emission parity with Euro 6 is accelerating turbocharger penetration in heavy-duty trucking routes.
- Digital twin integration:Convergence of computational fluid dynamics with additive manufacturing is enabling topology-optimized wheel architectures bypassing traditional forging constraints.
Industry Challenges
- Five-axis machining specialization:Complex blade geometries require operators proficient in simultaneous multi-axis programming, a skill set scarce in traditional automotive supplier bases.
- Divergent certification timelines:EPA Tier 4, Euro 7, and China's evolving GB standards maintain non-synchronized validation windows, stranding tooling investments for multi-market suppliers.
- Legacy ERP integration:Material traceability mandates from China's MIIT clash with established quality management systems, forcing expensive middleware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressor Wheel Market |
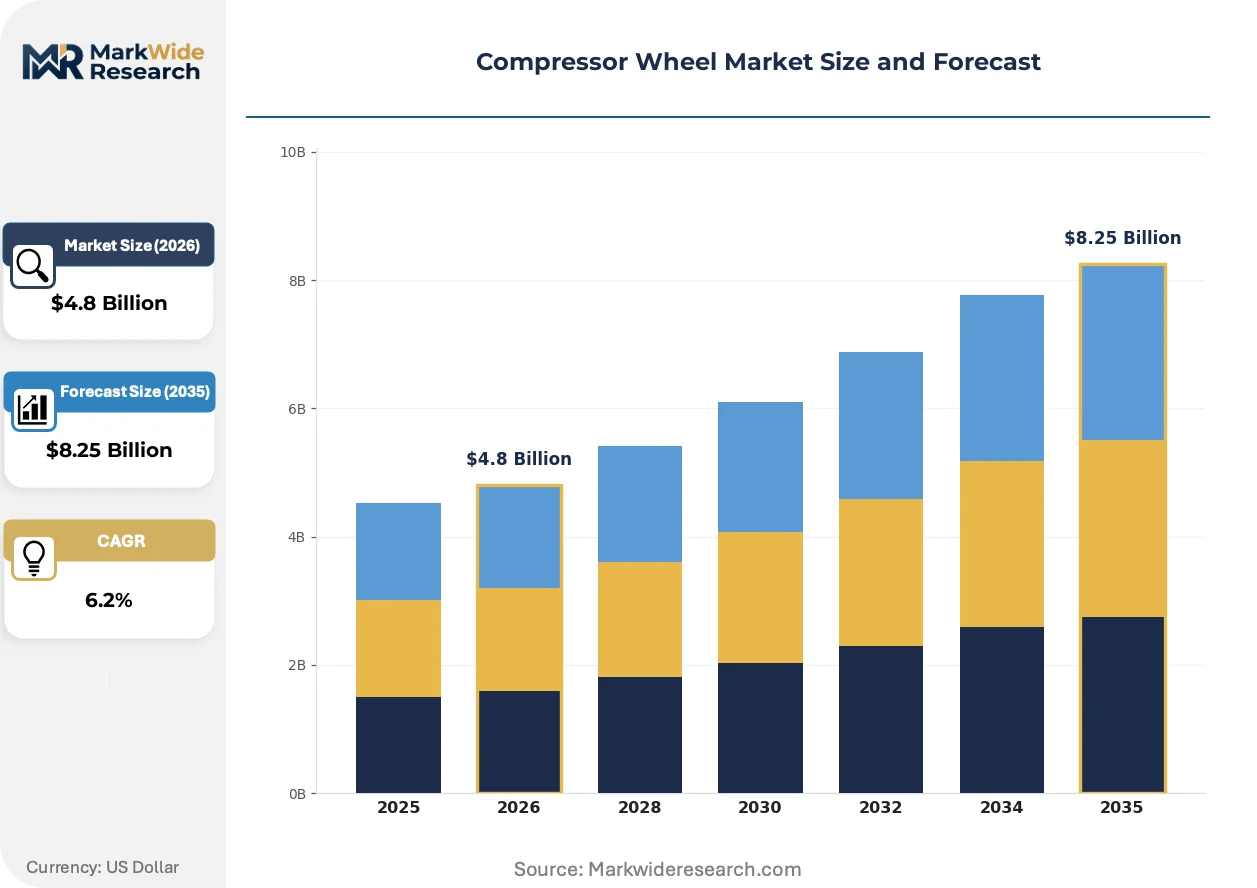
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal, Axial, Mixed Flow, Turbo Material: Aluminum, Titanium, Steel, Composite Application: Aerospace, Automotive, Industrial Machinery, Marine End User: OEMs, Aftermarket, Manufacturing, Energy |
| Companies Covered | BorgWarner Inc., Garrett Motion Inc., Honeywell International Inc., Wabtec Corporation, UACJ Corporation, Melett Ltd., Doncasters Group Ltd, Atlas Copco AB, Cummins Turbo Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressor Wheel Market Strategic Shifts & Innovations
Additive manufacturing is absorbing qualification workflows for prototype compressor wheels, compressing design iteration cycles from months to weeks. Three developments are restructuring competitive capability requirements.
Electron beam melting of titanium aluminide intermetallics is absorbing aerospace qualification protocols for low-pressure compressor stages. GE Aviation and Pratt & Whitney suppliers are advancing these alloys toward production volumes, displacing conventional nickel superalloys in intermediate temperature regimes. The technology is absorbing thermal barrier coating integration challenges that previously required separate process lines.
REACH restrictions on hexavalent chromium surface treatments are forcing conversion to trivalent alternatives or physical vapor deposition coatings across European supply chains. Wheel producers serving EU-registered vehicles must recertify corrosion resistance under ECHA-aligned protocols, compressing supplier qualification timelines. German and Czech foundries are responding with in-house vacuum coating investments to preserve OEM access.
Fleet operators are consolidating compressor wheel procurement through turbocharger cartridge assemblies rather than standalone component sourcing. This behavior concentrates specification authority with tier-one integrators, marginalizing independent wheel suppliers lacking cartridge assembly capability. The pattern is most visible in North American long-haul trucking, where maintenance interval standardization favors pre-integrated subsystems.
Compressor Wheel Market Segmentation
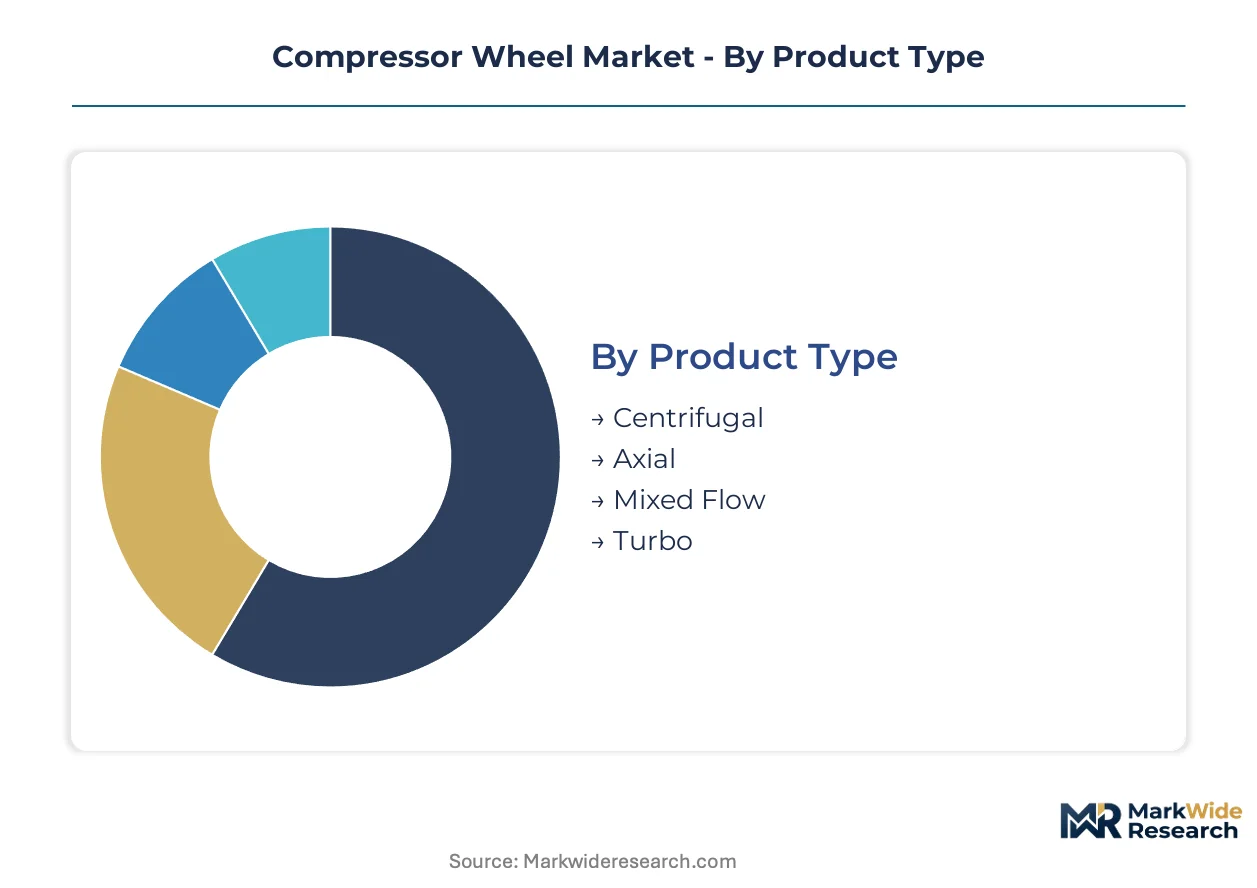
Compressor wheel segmentation reveals divergent margin structures across material grades and duty cycles. Product architecture and alloy specification together determine thermal thresholds, rotational speed tolerance, and OEM qualification pathways.
Product Type:
Volume concentration sits with centrifugal geometries, while premium positioning clusters around mixed-flow innovations for variable-load environments.
- Centrifugal:Radial blade configurations machined from aluminum castings dominate automotive turbocharging due to cost-optimized production economics. Demand concentrates in China's Jiangsu and Zhejiang assembly corridors where domestic OEMs scale passenger vehicle turbocharger capacity.
- Mixed Flow:Hybrid geometries combining radial and axial flow characteristics deliver surge tolerance across marine propulsion load bands. European shipbuilders specify these wheels for variable-speed diesel-electric systems where stall margin determines operational safety.
- Axial:Multi-stage blade rows serve large-frame industrial gas turbines requiring staged compression ratios.
- Turbo:Integrated wheel-cartridge assemblies capture fleet procurement consolidation in North American long-haul trucking.
Today's leader: Centrifugal. Tomorrow's challenger: Mixed Flow.
Material:
Aluminum sustains high-volume production, while titanium commands aerospace specification premiums.
- Aluminum:Cast and forged aluminum alloys maintain production economics for automotive turbochargers under 150,000 RPM operational ceilings. China's MIIT-administered GB standards prescribe fatigue testing protocols that shape domestic supplier qualification.
- Titanium:Forged titanium wheels specified for next-generation turbofan architectures achieve weight reduction at high-RPM endurance thresholds. Aerospace OEMs in the United States and France mandate these alloys for low-pressure compressor stages.
- Steel:Martensitic stainless grades serve industrial machinery applications where corrosion resistance outweighs mass considerations.
- Composite:Polymer matrix formulations remain developmental for auxiliary turbocharger applications.
Aluminum captures current volume. Titanium climbs the fastest.
Application:
Automotive volume anchors production planning, while aerospace margins justify alloy development investment.
- Automotive:Passenger and commercial vehicle turbochargers consume centrifugal aluminum wheels at scale. EPA Tier 4 and Euro 7 emissions mandates force blade aerodynamic redesigns with tighter tip clearances.
- Aerospace:Turbofan engine OEMs specify titanium and Inconel wheels for high-temperature, high-RPM duty cycles. GE Aviation and Pratt & Whitney suppliers advance electron beam melting qualification for titanium aluminide intermetallics.
- Industrial Machinery:Process gas compressors and power generation turbines require mixed-flow geometries for surge stability.
- Marine:Variable-load propulsion systems in European shipbuilding corridors adopt mixed-flow wheels for diesel-electric hybrid architectures.
Automotive dominates unit economics. Aerospace defines material frontier.
End User:
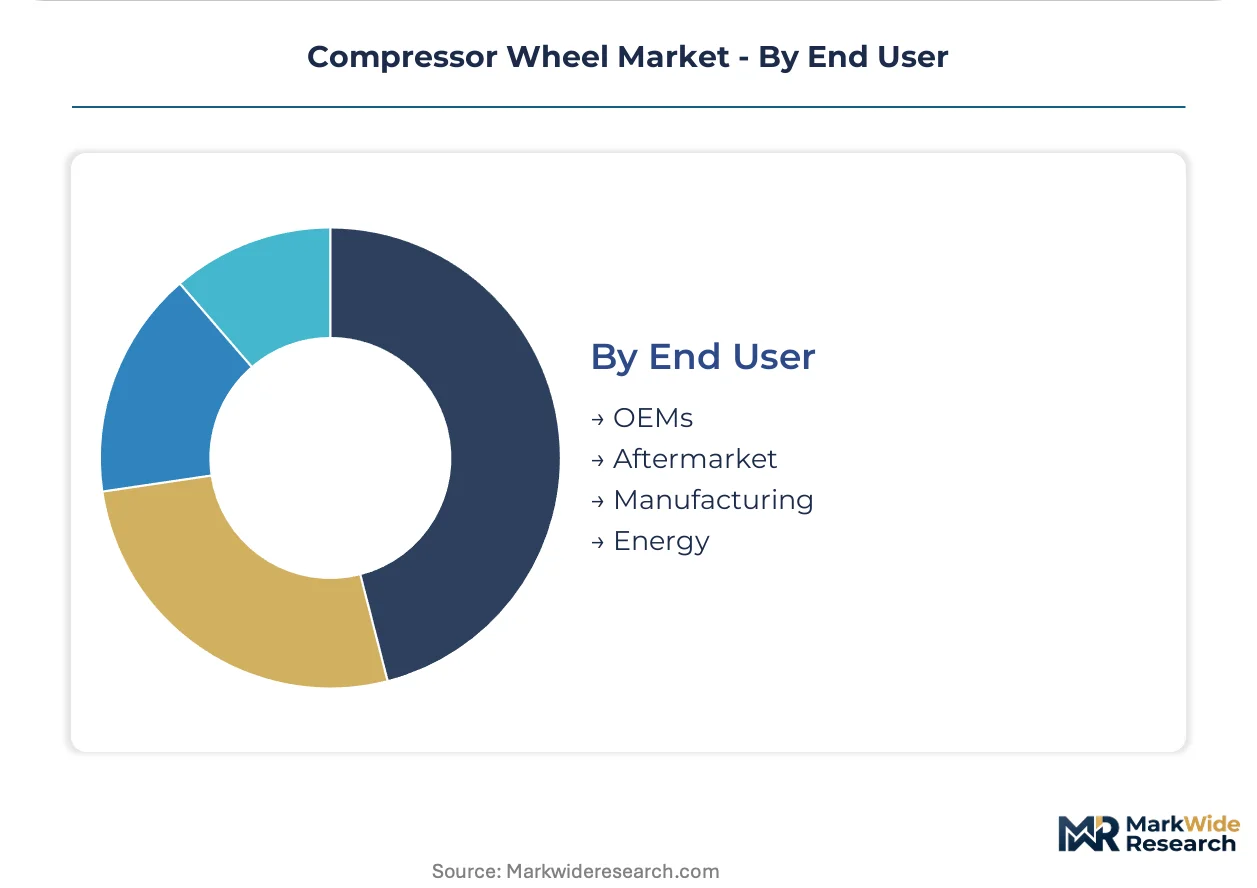
OEM relationships concentrate specification authority, while aftermarket procurement patterns favor cartridge-level integration.
- OEMs:Tier-one turbocharger integrators source wheels through captive foundry networks or precision casting partnerships. Garrett Motion and BorgWarner anchor North American and European automotive supply relationships.
- Aftermarket:Fleet operators and independent service channels consolidate procurement through pre-integrated compressor wheel-cartridge assemblies rather than standalone component sourcing.
- Manufacturing:Industrial compressor OEMs specify custom wheel geometries for process air and refrigeration systems.
- Energy:Power utility procurement of gas turbine components follows long-cycle qualification timelines with superalloy traceability requirements.
OEMs control specification. Aftermarket shifts toward subsystem integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compressor wheel manufacturing originated in German precision engineering corridors during the post-war turbocharger development era, with subsequent scaling across Japanese automotive supply chains and Chinese coastal manufacturing belts.
United States
Commercial vehicle OEMs in Michigan and Indiana drive turbocharger demand for heavy-duty diesel platforms. EPA Tier 4 emissions mandates enforce nitrogen oxide thresholds that force compressor wheel redesigns with advanced blade aerodynamics. The Detroit-Windsor corridor concentrates precision casting operations serving North American automotive supply networks.
Germany
European automotive OEMs in Baden-Württemberg and Bavaria specify mixed-flow geometries for variable-load propulsion systems. ECHA-aligned REACH restrictions on hexavalent chromium surface treatments compel conversion to trivalent alternatives or physical vapor deposition coatings. Stuttgart-based foundries invest in vacuum coating capabilities to preserve OEM qualification pathways.
China
Domestic turbocharger assembly capacity in Jiangsu and Zhejiang provinces scales rapidly, pulling component demand toward localized supply networks. MIIT-administered GB standards prescribe material traceability and fatigue testing protocols for domestically manufactured components. Shanghai-Ningbo manufacturing clusters integrate backward into precision casting to serve passenger vehicle OEMs.
Japan
Automotive turbocharger producers in Aichi and Kanagawa prefectures sustain high-volume aluminum casting economics for passenger vehicle applications. METI industrial standards coordinate with global emissions frameworks while preserving domestic supplier qualification protocols. Nagoya-based manufacturing networks supply centrifugal wheel geometries to Asian automotive assembly corridors.
India
BS-VI emission parity with Euro 6 accelerates turbocharger penetration in Maharashtra and Gujarat heavy-duty trucking routes. The Central Pollution Control Board enforces particulate matter thresholds that demand compressor wheel efficiency upgrades. Pune-Ahmedabad industrial belts attract precision casting investments to serve commercial vehicle fleet modernization.
Compressor Wheel Market Key Industry Players
The competitive structure tilts toward tier-one integrators with captive foundry networks controlling titanium alloy supply chains. Precision casting specialists and aerospace-grade forging operations occupy distinct capability tiers. Dominant competitive moves include backward integration into superalloy smelting and strategic partnerships with electron beam melting qualification programs.
Among US-based automotive suppliers, BorgWarner Inc. and Garrett Motion Inc. exemplify the tier-one integrator archetype with upstream control over precision casting operations. Honeywell International Inc. anchors the aerospace-grade materials tier. Cummins Turbo Technologies represents the heavy-duty specialization vector calibrated for off-highway torque profiles.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Garrett Motion Inc. |
| Honeywell International Inc. |
| Wabtec Corporation |
| UACJ Corporation |
| Melett Ltd. |
| Doncasters Group Ltd |
| Atlas Copco AB |
| Cummins Turbo Technologies |
| Others |
Cost & Logistics Intelligence
Additive manufacturing qualification for titanium aluminide compressor wheels is simultaneously compressing prototype iteration costs and concentrating supply authority among electron beam melting specialists with aerospace certification pathways. This production-method transition feeds directly into pricing power dynamics, as foundries without captive additive capability face margin compression against integrated tier-one suppliers.
Pricing Analysis
Three-tier pricing structure across aerospace-grade titanium, automotive aluminum, and industrial steel specifications dominates procurement negotiations. Price differentiation hinges on alloy certification grade and captive foundry integration, with EPA Tier 4-compliant wheels commanding premiums over legacy designs. Cost compression in aluminum castings is intensifying because Chinese domestic assembly capacity is scaling rapidly in Jiangsu and Zhejiang. Fleet operators demonstrate highest price sensitivity through cartridge-level procurement consolidation, while aerospace OEMs exhibit lowest sensitivity due to performance-critical specifications.
Supply Chain Analysis
Direct-to-OEM channels handle tier-one turbocharger integrator demand, while aftermarket distribution runs through authorized service networks and independent distributors. Geographic supply concentration centers on China, Germany, and the United States, with precision casting operations clustering in specific industrial corridors. Raw material dependencies rest on titanium sponge from aerospace demand cycles, Inconel feedstock from German and US specialty foundries, and aluminum alloys from smelter networks. Single-source vulnerability in superalloy supply creates structural exposure for extreme-duty wheel producers without backward integration into specialty foundry partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compressor wheel economics favor margin expansion through titanium alloy adoption curves and additive manufacturing cost-down trajectories. Material substitution premiums and production-method efficiencies create dual pathways for profitability improvement.
For Market Incumbents: Anticipate electron beam melting qualification requirements by securing partnerships with aerospace-tier additive specialists before capacity constraints harden. Defensive consolidation through captive titanium smelter arrangements mitigates sponge price volatility exposure. Precision casting yield improvements represent the priority operational lever against fifteen percent scrap rate headwinds. For New Entrants and Emerging Players: Marine mixed-flow geometries for European diesel-electric propulsion systems offer accessible white-space penetration outside established automotive supply relationships. India's BS-VI commercial vehicle fleet modernization presents the most penetrable geography for aluminum casting specialists with cost-optimized production economics. Tier-two turbocharger integrators lacking in-house wheel manufacturing capability provide the strongest channel partnership angle for qualification-fast entrants. For Investors and Strategic Acquirers: Valuations sit cheapest among precision casting specialists with automotive certification but absent aerospace-grade titanium capability. Long-term viability over the next decade hinges on electron beam melting qualification progress and titanium aluminide intermetallic development pipelines. The specific signal to watch is electron beam melting capacity absorption rates at GE Aviation and Pratt & Whitney supplier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Electron Beam Melting Qualification | Absorbs aerospace certification protocols for titanium aluminide wheels at GE Aviation and Pratt & Whitney suppliers. |
| Captive Titanium Smelter Integration | Controls sponge input costs against aerospace demand cycle volatility for margin stability. |
| Mixed-Flow Geometry Development | Captures marine propulsion surge-tolerance requirements in European diesel-electric shipbuilding corridors. |
| Cartridge Assembly Capability Addition | Preserves OEM access as fleet procurement consolidates through pre-integrated subsystems in North American trucking. |
| Five-Axis Machining Workforce Investment | Addresses simultaneous multi-axis programming scarcity constraining complex blade geometry production. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each regional manufacturing corridor. The analytical approach combines structured interviews with turbocharger platform engineers, tier-one procurement directors, precision casting operations managers, and aftermarket service channel heads with secondary validation from EPA regulatory filings, ECHA REACH substance restrictions, MIIT GB standard publications, and customs trade data. Bottom-up demand modeling from OEM production schedules triangulates against top-down market sizing from alloy consumption patterns.
Rate-of-change decomposition isolates volume growth from price-mix effects across the projection horizon. The analytical framework segments by material grade, product geometry, application duty cycle, and end-user procurement archetype. CAGRs derive from regression analysis against vehicle production forecasts, turbofan engine delivery schedules, and industrial gas turbine installation pipelines. Specific forecast inputs include EPA Tier 4 compliance timelines, Euro 7 implementation windows, and China's MIIT domestic content trajectory.
Revisions become necessary when regulatory divergence between EPA, EMA-aligned, and MIIT frameworks accelerates, or when titanium sponge demand cycles decouple from aerospace production. Forecasts reflect assumptions about electron beam melting qualification timelines and mixed-flow geometry adoption curves in marine applications. Periodic stress-testing of base assumptions is recommended against foundry capacity expansion announcements and tier-one integrator backward integration moves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Hydrogen Compressor Market
Compressors
Rotary Lobe Compressor Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Gas Compressors Market
Compressors
Compressor Rental Market
Compressors
Rotary Air Compressor Market
Compressors
Centrifugal Compressors Market
Compressors
Industrial Air Compressor Market
Compressors
PAG Compressor Oil Market
Compressors
Oil-Free Air Compressor Market
Compressors
Axial Compressor Market
Compressors
Positive Displacement Gas Compressor Market
Compressors
Liquid Ring Compressors Market
Compressors
Europe Compressor Market
Compressors
Bus Compressor Market
Compressors
Process Gas Compressors Market