
 Reciprocating Hydrogen Compressor Market | 2026-2036
Reciprocating Hydrogen Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Reciprocating Hydrogen Compressor Market Analytics
The gap between diaphragm and multi-stage reciprocating architectures is narrowing as OEMs pursue higher discharge pressures for 700-bar vehicle refueling. Burckhardt Compression AG leverages its Swiss engineering heritage to dominate ultra-high-pressure sealing technologies. Siemens AG anchors large-scale electrolysis-integrated projects across European hydrogen valleys. Ariel Corporation specializes in API 618-compliant frames for North American petrochemical hydrogen loops.
A reciprocating hydrogen compressor is a positive-displacement machine that uses crankshaft-driven pistons within cylindrical chambers to raise hydrogen gas pressure through volume reduction, typically achieving discharge pressures from 200 to 900 bar with leakage rates below 50 ppm through specialized packing and ring designs. Its primary purpose is to enable hydrogen transport, storage, and end-use in applications where purity preservation and high-pressure delivery are critical. Multi-stage configurations lead the product type landscape due to their thermodynamic efficiency in high-pressure hydrogen service, while oil-free designs command premium positioning in fuel cell applications where lubricant contamination would poison proton exchange membranes. Stationary installations dominate the installation category, though mobile units are gaining traction for distributed refueling and backup supply scenarios.
The U.S. EPA and OSHA jointly govern hydrogen compressor safety through 29 CFR 1910.103 and process safety management standards, while the EU's F-Gas Regulation and CE marking under the Pressure Equipment Directive shape product compliance for European deployment. Japan's METI hydrogen roadmap and South Korea's MFDS pressure equipment codes further fragment certification requirements for cross-border suppliers. Stakeholders must monitor how divergent national hydrogen purity standards and pressure equipment codes affect modular platform strategies and aftermarket service architectures.
Market Dynamics
The U.S. Inflation Reduction Act's clean hydrogen production tax credits are compressing project timelines and forcing OEMs to accelerate domestic manufacturing commitments ahead of credit phase-out deadlines. This regulatory pressure is reshaping supply chain geography and procurement patterns simultaneously.
Growth Catalysts
- Heavy-duty fuel cell truck deployment:Fleet operators in California and Germany are scaling 700-bar refueling infrastructure, creating sustained demand for high-pressure compression systems.
- CE marking under the EU Pressure Equipment Directive:Harmonized certification is reducing cross-border deployment friction for modular compressor skids across European hydrogen valleys.
- Electrolysis-integrated project architectures:Green hydrogen producers are specifying compression systems with direct coupling to PEM electrolyzer output pressures.
Market Restraints
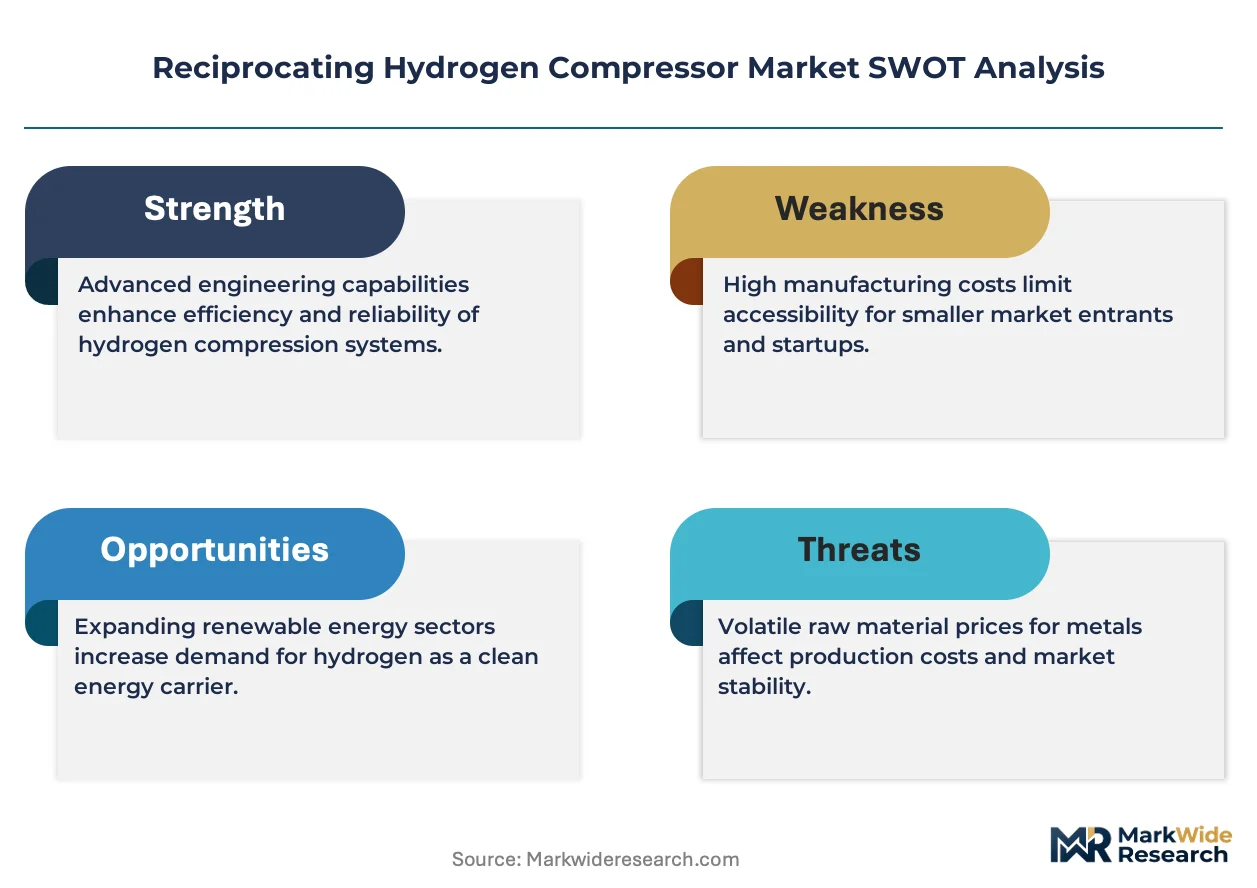
- Specialized metallurgy costs:Austenitic stainless steel and Inconel alloys for high-pressure hydrogen service face price volatility tied to nickel supply concentration in Indonesia.
- Sealing technology supplier concentration:Ultra-high-pressure packing systems rely on a narrow base of Swiss and German component specialists.
- Hydrogen embrittlement limitations:Material compatibility constraints prevent direct adaptation of natural gas compressor designs without complete metallurgical redesign.
Strategic Opportunities
- Saudi Arabia's NEOM hydrogen city:Integrated green ammonia export projects require massive compression capacity with 30-year service contracts.
- Japan's METI hydrogen roadmap:Import terminal specifications for hydrogen-derived fuels are creating demand for marine-compatible compression systems.
- Digital twin convergence with predictive maintenance:Real-time condition monitoring is enabling power-by-the-hour contracting models for refueling station operators.
Industry Challenges
- API 618 compliance timeline compression:Certification cycles for large-frame reciprocating units now exceed 18 months, delaying project financial close.
- Hydrogen purity certification complexity:Fuel cell applications require third-party validation to ISO 14687 standards, adding procurement lead time.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reciprocating Hydrogen Compressor Market |
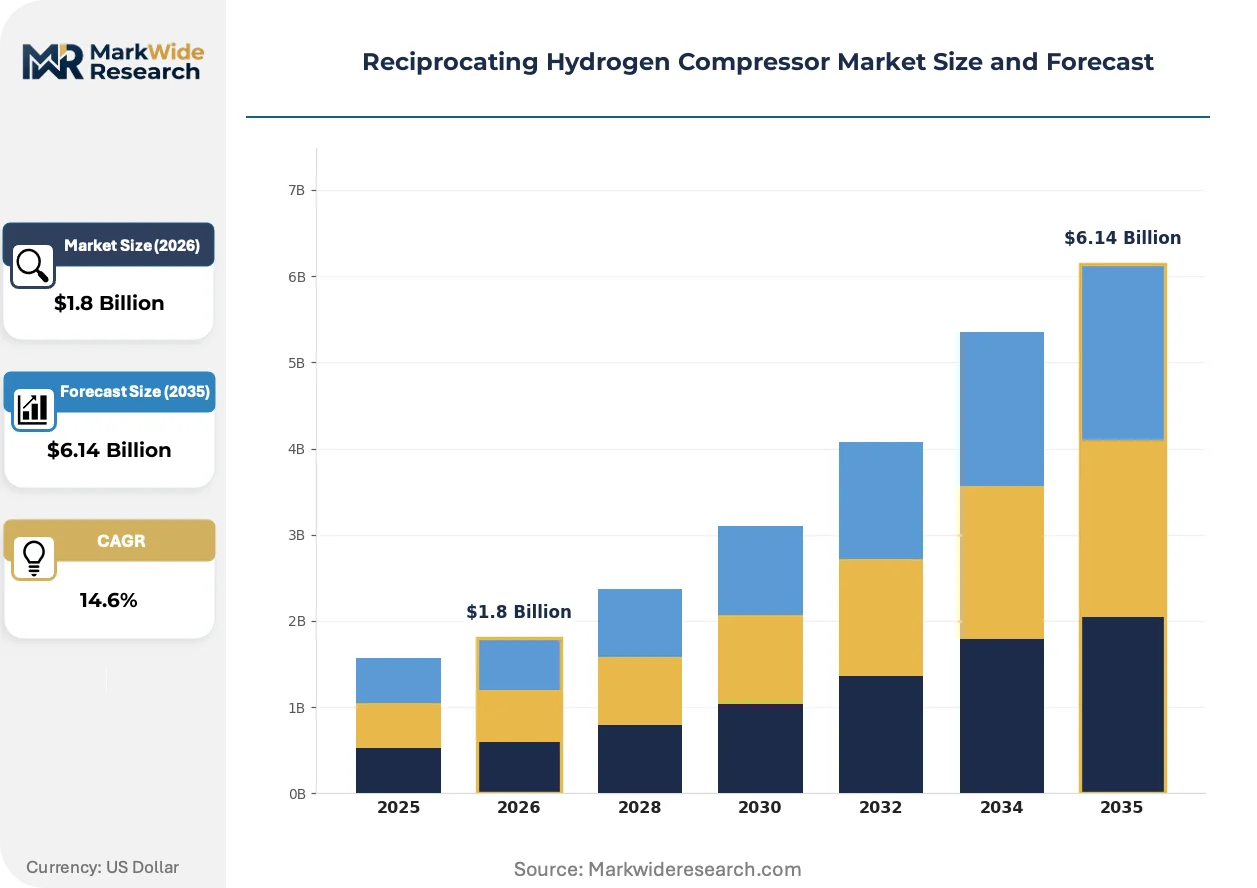
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Stage, Multi-Stage, Oil-Free, Diaphragm End User: Industrial Manufacturing, Energy Sector, Transportation, Chemical Processing Installation: Onshore, Offshore, Mobile, Stationary Technology: Electromechanical, Hydraulic, Pneumatic, Others |
| Companies Covered | Siemens AG, Kobe Steel Ltd., Burckhardt Compression AG, IHI Corporation, Hitachi Ltd., Ariel Corporation, Ingersoll Rand Inc., Elliott Group, Atlas Copco AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reciprocating Hydrogen Compressor Market Evolving Landscape
Digitalization is penetrating compressor control systems faster than mechanical redesign, creating divergence between hardware platforms and software-enabled service models. This separation is redefining how value is captured across the equipment lifecycle.
Digital twin technology for reciprocating hydrogen compressors is virtualizing maintenance scheduling and performance optimization. Refueling station operators in Germany and California are deploying these systems to minimize unplanned downtime at 700-bar dispensing points. The technology is virtualizing traditional time-based overhaul intervals into condition-triggered interventions, compressing service revenue recognition cycles.
The EU's F-Gas Regulation is tightening containment requirements for hydrogen compression systems with fluorinated sealing materials. Equipment suppliers must now validate alternative polymer formulations or face exclusion from public procurement frameworks. European OEMs are responding with accelerated R&D partnerships to qualify hydrogen-compatible perfluoroelastomer substitutes ahead of enforcement deadlines.
Asset-light contracting is displacing capital purchase models among hydrogen refueling network developers. Station operators in South Korea and the Netherlands now specify availability guarantees rather than equipment ownership, transferring operational risk to compressor suppliers. This shift is most visible in projects backed by national hydrogen roadmaps where public funding requires performance-linked payment structures.
Reciprocating Hydrogen Compressor Market Segmentation
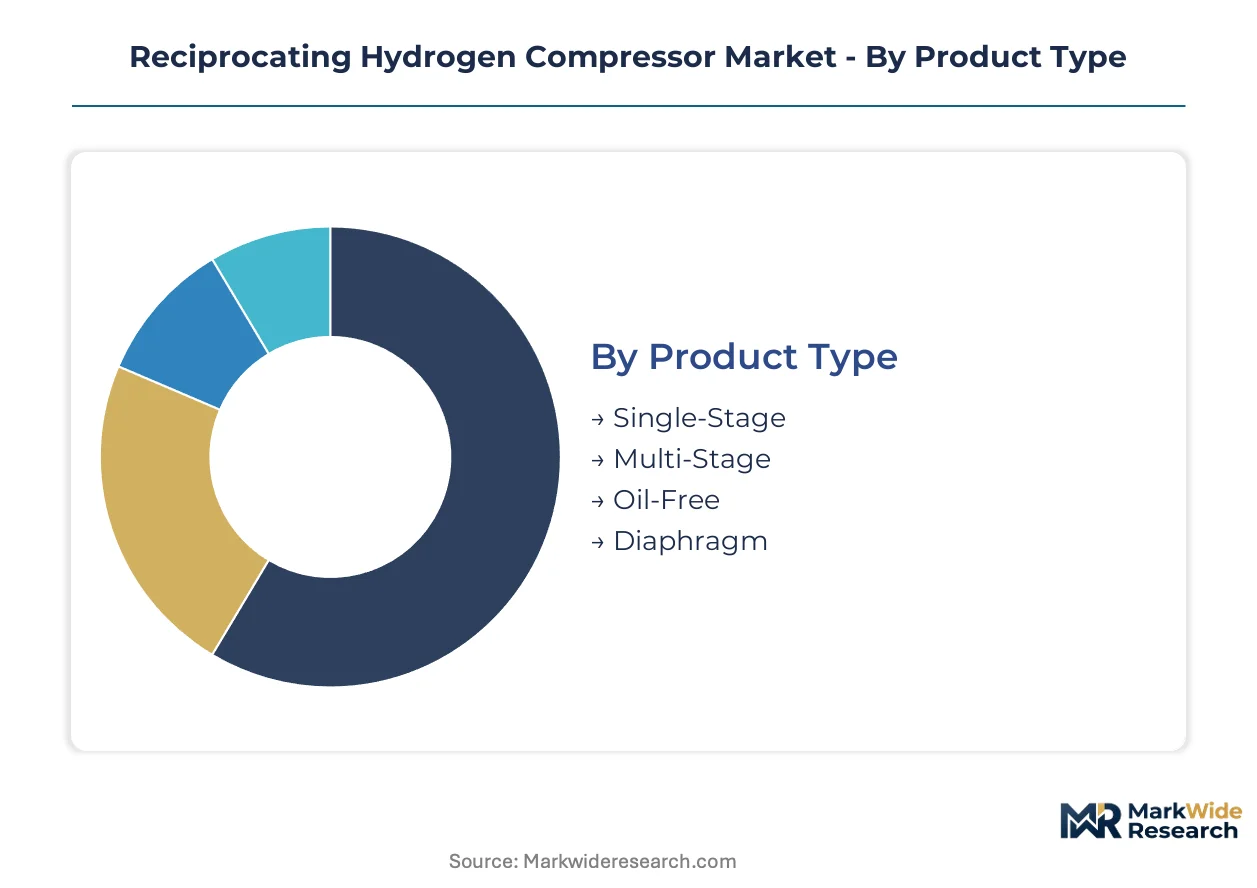
Segmentation in the reciprocating hydrogen compressor market reveals how pressure requirements, purity standards, and deployment contexts fragment procurement patterns across hydrogen value chains. Each dimension carries distinct metallurgical, certification, and service implications that shape supplier positioning.
Product Type:
Use-case spectrum spans laboratory-scale purity preservation to industrial-scale high-pressure throughput, with thermodynamic efficiency and contamination risk as the pivot points.
- Multi-Stage:Thermodynamically optimized configurations compress hydrogen through successive cylinders with intercooling, achieving discharge pressures above 700 bar for heavy-duty vehicle refueling. Demand concentrates in German industrial clusters building dedicated pipeline networks, driven by the need to minimize energy losses across high pressure ratios.
- Oil-Free:Eliminates lubricant contact through piston rings and guide bands of specialized polymer composites, preserving ISO 14687-grade purity for PEM fuel cell applications. Procurement is accelerating at California hydrogen refueling stations serving fuel cell truck fleets, where membrane poisoning from hydrocarbon traces would void warranties.
- Single-Stage:Simpler crankshaft-driven architecture suited to moderate pressure ratios below 200 bar.
- Diaphragm:Metal or elastomeric membranes isolate process gas from hydraulic drive fluid, serving ultra-high-purity laboratory and semiconductor applications.
Established volume favors Multi-Stage; emerging adoption favors Oil-Free.
End User:
Cost tier segmentation separates capital-intensive integrated projects from distributed infrastructure buildouts with diverging payment structures.
- Transportation:700-bar vehicle refueling infrastructure demands compression systems with rapid cycling capability and 99.999% availability guarantees. Fleet operators in South Korea and the Netherlands are shifting from capital purchase to power-by-the-hour contracting, transferring operational risk to OEMs under national hydrogen roadmap funding requirements.
- Energy Sector:Grid-scale hydrogen storage and power-to-gas applications require compression integrated with electrolyzer output pressures. Projects in the U.S. are compressing procurement timelines to capture Inflation Reduction Act clean hydrogen production tax credits ahead of phase-out deadlines.
- Industrial Manufacturing:Steel and cement decarbonization drives demand for high-volume, medium-pressure compression.
- Chemical Processing:Ammonia and methanol synthesis require compression systems meeting API 618 standards for continuous duty.
Transportation commands premium pricing; Energy Sector represents the steepest expansion trajectory.
Installation:
Geography of deployment dictates modularization requirements, with marine and remote specifications fragmenting standard platform strategies.
- Stationary:Fixed installations at production facilities, terminals, and refueling stations dominate current procurement, leveraging concrete foundations for vibration isolation and long service intervals. Saudi Arabia's NEOM hydrogen city is specifying 30-year service contracts for massive stationary compression capacity serving green ammonia export.
- Mobile:Containerized or trailer-mounted units enable distributed refueling and backup supply scenarios where pipeline infrastructure is absent. Adoption is gaining traction in Japan for hydrogen import terminal pre-cooling and buffer storage ahead of marine fueling operations under METI roadmap specifications.
- Onshore:Land-based installations at production and consumption points.
- Offshore:Platform-mounted compression for offshore hydrogen production and pipeline injection.
Stationary anchors current revenue; Mobile is climbing the fastest.
Technology:
Customer type segmentation separates integrated project developers specifying complete systems from component buyers assembling custom architectures.
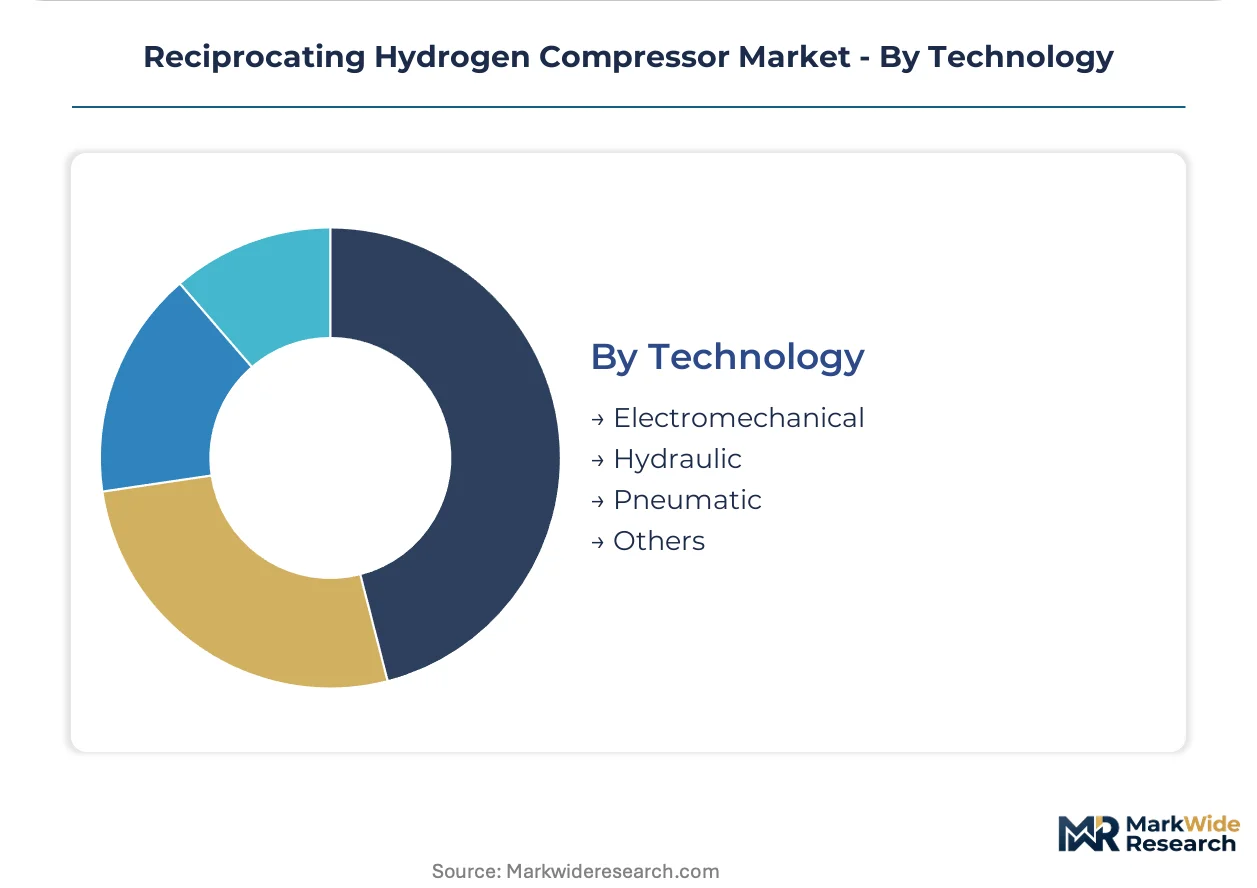
- Electromechanical:Crankshaft-driven electric motors deliver precise speed control and efficiency optimization through variable frequency drives. European OEMs are embedding digital twin capabilities for predictive maintenance, enabling condition-triggered interventions that compress service revenue cycles.
- Hydraulic:Fluid power actuation provides smooth pressure profiles and pulsation damping for sensitive downstream processes. Demand concentrates in chemical processing applications where API 618 pulsation limits are stringent.
- Pneumatic:Compressed air or nitrogen drive systems for explosion-risk environments.
- Others:Emerging linear motor and magnetic drive architectures.
Electromechanical holds installed base dominance; hydraulic serves niche precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports compression systems to hydrogen valleys across the Netherlands and Denmark, while Japanese manufacturers supply marine-compatible units to South Korean import terminals under bilateral technology agreements.
United States
California fleet operators are scaling 700-bar refueling infrastructure for heavy-duty fuel cell trucks. The Inflation Reduction Act's clean hydrogen production tax credits are compressing project timelines ahead of phase-out deadlines. Industrial clusters in Texas and the Gulf Coast are building dedicated hydrogen pipeline networks connecting refineries to export terminals.
Germany
Ruhr industrial clusters and Hamburg port authorities are procuring multi-stage compression systems for dedicated hydrogen pipeline networks. CE marking under the EU Pressure Equipment Directive is reducing cross-border deployment friction for modular compressor skids. The country's hydrogen valleys in North Rhine-Westphalia are integrating compression directly with electrolyzer output pressures.
Japan
METI's hydrogen roadmap is driving demand for marine-compatible compression systems at hydrogen import terminals. The country's pressure equipment codes under MFDS alignment are shaping certification requirements for cross-border suppliers. Kanto region developers are deploying containerized units for distributed refueling ahead of marine fueling operations.
Saudi Arabia
NEOM hydrogen city is specifying massive stationary compression capacity with 30-year service contracts for green ammonia export. The country's national industrial development program is attracting OEM manufacturing commitments to serve Middle East and African markets. Integrated projects in the Eastern Province are coupling compression systems directly to gigawatt-scale electrolyzer installations.
South Korea
National hydrogen roadmap funding requires power-by-the-hour contracting structures for refueling station operators. MFDS pressure equipment codes are fragmenting certification requirements for European and Japanese suppliers. Station operators in the Seoul Capital Area are shifting from capital purchase to availability guarantee models under public procurement frameworks.
Reciprocating Hydrogen Compressor Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: Swiss-German specialists in ultra-high-pressure sealing, Japanese conglomerates with electrolysis integration expertise, and North American fabricators serving API 618 petrochemical specifications. Strategic archetypes include heritage engineering houses with century-long compression legacies, diversified industrial groups leveraging energy division synergies, and mid-scale independents focused on modular skid packaging. Capacity expansion and strategic partnerships dominate competitive moves as OEMs race to localize production ahead of tax credit deadlines.
Among European heritage engineering houses, Burckhardt Compression AG and Siemens AG exemplify divergent strategic positions—one anchored in ultra-high-pressure sealing specialization, the other in large-scale electrolysis-integrated project architectures. Ariel Corporation represents the North American API 618 compliance tier serving petrochemical hydrogen loops.
| Leading Market Players |
|---|
| Siemens AG |
| Kobe Steel Ltd. |
| Burckhardt Compression AG |
| IHI Corporation |
| Hitachi Ltd. |
| Ariel Corporation |
| Ingersoll Rand Inc. |
| Elliott Group |
| Atlas Copco AB |
| Others |
Value Network & Pricing Analysis
Indonesian nickel concentration for Inconel and austenitic stainless steel production funnels margin capture toward Swiss-German sealing technology specialists, compressing downstream OEM profitability unless secured through long-term offtake structures.
Pricing Analysis
Prior-generation API 618-compliant frames trade at commodity-equivalent levels while current-generation oil-free and multi-stage systems command substantial premia, and next-generation electrolysis-integrated architectures with embedded digital twin capabilities sit at the apex. Three-tier pricing structure across premium electrolysis-coupled systems, standard multi-stage refueling units, and economy-grade single-stage equipment stratifies procurement budgets. Cost compression in the standard tier intensifies because nickel price volatility transmits directly through specialized metallurgy bills. Fleet operators in California demonstrate highest price sensitivity due to capital purchase model constraints, while Saudi integrated project developers show lowest sensitivity under 30-year service contract frameworks.
Supply Chain Analysis
Contract manufacturing for ultra-high-pressure packing systems concentrates among Swiss and German component specialists, with secondary capacity in Japan for marine-compatible architectures. Geographic supply concentration spans Germany for precision-engineered frames, Switzerland for sealing technology, and Japan for electrolysis-integrated skids. Raw material dependencies center on Indonesian nickel for corrosion-resistant alloys, specialized polymer composites for oil-free piston rings, and rare earth elements for high-efficiency electric drives. Single-source vulnerability in Swiss-German sealing technology suppliers creates structural concentration risk. Distribution runs through OEM direct sales for large integrated projects and authorized service networks for refueling station aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where CE marking under the EU Pressure Equipment Directive and API 618 certification cycles exceeding 18 months create sticky incumbent positions difficult for unqualified challengers to replicate.
For Market Incumbents: Pre-empt margin erosion in standard-tier equipment by securing backward integration into nickel alloy supply through Indonesian offtake partnerships. Deepen certification entrenchment by accelerating R&D partnerships for hydrogen-compatible perfluoroelastomer substitutes ahead of EU F-Gas Regulation enforcement deadlines, raising barriers for unqualified entrants.
For New Entrants and Emerging Players: Mobile containerized units for Japan's hydrogen import terminal pre-cooling operations represent the most penetrable entry point, given METI roadmap specifications and absence of established domestic suppliers. South Korean power-by-the-hour contracting structures offer a second white-space target, as national hydrogen roadmap funding requirements favor availability-guarantee business models over capital sales. A go-to-market angle anchored in digital twin-enabled predictive maintenance differentiates against heritage engineering houses with slower software adoption.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale independents with modular skid packaging capabilities and established CE marking pathways, positioned for acquisition by diversified industrial groups seeking energy division synergies. Long-term viability across the projection horizon hinges on electrolysis integration expertise and software-enabled service revenue streams. The signal to watch is acceleration in power-by-the-hour contract penetration at German and South Korean refueling stations, indicating inflection toward asset-light market structures favoring service-architecture players over pure hardware vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Supply | Secures Inconel cost stability against Indonesian export volatility for frame manufacturers. |
| Digital Twin Platform Development | Enables condition-triggered interventions that compress service revenue cycles for European OEMs. |
| CE Marking Acceleration for Modular Skids | Reduces cross-border deployment friction across Netherlands and Danish hydrogen valleys. |
| Power-by-the-Hour Contracting Expansion | Transfers operational risk to suppliers under South Korean public procurement frameworks. |
| Marine-Compatible Compression Qualification | Captures Japan METI import terminal specifications ahead of bilateral technology agreements. |
Research Methodology
A spread of perspectives from OEM engineering directors, refueling station procurement managers, electrolyzer project developers, and aftermarket service heads converged on the working assumptions. Primary interviews across these stakeholder categories combined with secondary validation from SEC filings, customs and trade data, FERC project filings, and EU hydrogen valley development databases. Bottom-up unit economics and top-down market sizing triangulated volume and value estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include product type architecture, end-use sector, installation geography, and technology drive mechanism, with pressure tier and purity specification as industry-specific cross-cuts. CAGRs were derived from installed base growth trajectories and replacement cycle analysis, incorporating electrolyzer capacity buildout schedules and hydrogen refueling station deployment pipelines as forecast inputs.
Practitioners should monitor nickel price volatility, EU F-Gas Regulation enforcement timing, and power-by-the-hour contract penetration rates for early signals of forecast revision. Quarterly review of OEM order backlog composition and certification cycle duration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Positive Displacement Gas Compressor Market
Compressors
PAG Compressor Oil Market
Compressors
Axial Compressor Market
Compressors
Root Blower Market
Compressors
Tandem Piston Compressors Market
Compressors
Reciprocating Air Compressor Market
Compressors
Scroll Compressor Market
Compressors
Rotary Lobe Compressor Market
Compressors
Bus Compressor Market
Compressors
Integrally Geared Centrifugal Compressor Market
Compressors
Compressor Wheel Market
Compressors
Oil Filled Air Compressor Market
Compressors
USA Scroll Compressor Market
Compressors
Booster Compressor Market
Compressors
Portable Compressor Market
Compressors
Middle East and Africa Booster Compressor Market