
 China Oil and Gas Midstream Market | 2026-2036
China Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
China Oil and Gas Midstream Market Outlook
Pipeline throughput allocation between state-backed trunk lines and provincial distribution networks is tilting toward centralized dispatch under PipeChina's national grid consolidation. PetroChina Pipeline Company leverages its legacy Daqing-to-Dalian corridor to sustain dominant crude throughput volumes across northeast China. CNOOC Gas & Power competes aggressively in coastal LNG receiving terminal capacity, while Sinopec anchors refined products distribution through its Yangtze River petrochemical belt. ENN Natural Gas differentiates via city-gate integration strategies that extend its downstream capture in tier-two industrial clusters.
China oil and gas midstream encompasses the transportation, storage, processing, and distribution infrastructure bridging upstream extraction with downstream consumption, operating through steel pipelines typically rated at 6.4 MPa to 12 MPa design pressure for natural gas trunk systems and incorporating compressor stations spaced every 80-150 kilometers to maintain flow dynamics. Its primary commercial purpose centers on volume aggregation, quality standardization, and temporal arbitrage between production basins and demand centers. Transportation services dominate value capture given the scale of west-to-east pipeline corridors, while natural gas pipeline type segments outpace crude oil equivalents as shale gas output from Sichuan and Ordos basins requires dedicated gathering and trunk infrastructure. Storage infrastructure maintains strategic petroleum reserve mandates but yields thinner margins than processing services where gas plant fractionation extracts higher-value NGL components.
China's Ministry of Ecology and Environment enforces dual carbon targets that tighten methane emission standards across compressor stations and processing facilities, while GB standards mandate pipeline steel grades and welding protocols that shape procurement specifications for new construction. The National Energy Administration coordinates interprovincial transmission tariffs that directly influence investor returns on cross-basin pipeline projects. Stakeholders must monitor how provincial carbon intensity benchmarks reshape gas plant retrofit priorities and whether PipeChina's third-party access reforms open contracted capacity to private distributors.
Market Dynamics
PipeChina's national grid consolidation is collapsing legacy provincial dispatch hierarchies into centralized throughput allocation, redistributing rent capture from regional distributors to trunk-line operators and forcing wholesale restructuring of tariff-setting mechanisms across Sichuan-to-coastal corridors.
Growth Catalysts
- Sichuan Basin shale corridors:Dedicated gathering infrastructure for Ordos and Sichuan tight gas deposits requires parallel trunk-line expansion, pulling steel demand and compressor station deployment.
- MEE methane emission standards:Dual carbon enforcement mandates retrofit of leak-detection systems at compressor stations, creating hardware upgrade cycles across the national grid.
- Carbon capture integration:Gas processing facilities face MEE-mandated retrofit timelines for post-combustion capture, opening engineering procurement construction contracts for amine-based separation systems.
Market Restraints
- High-grade steel input volatility:X80 and X100 pipeline steel procurement faces alloy cost pressure from nickel and molybdenum spot markets, compressing contractor margins on fixed-price EPC contracts.
- Trunk-line concentration risk:PipeChina's monopoly over west-to-east corridors limits third-party shipper access, constraining private distributor participation in tariff-regulated throughput.
- Geographic demand-supply asymmetry:Coastal LNG terminal capacity outpaces interior pipeline takeaway, stranding Sichuan shale gas production during peak injection seasons.
Strategic Opportunities
- Yangtze River Delta petrochemical belt:Refined products distribution networks seek last-mile connectivity upgrades, opening city-gate integration contracts for private distributors.
- Third-party access reforms:NEA tariff restructuring may unbundle contracted capacity on legacy PetroChina corridors, creating entry points for ENN-style downstream capture models.
- Digital twin convergence:SCADA-integrated pipeline monitoring combined with predictive maintenance AI offers asset management contracts to provincial distribution operators.
Industry Challenges
- Welding technician scarcity:GB-standard qualified automatic welders for high-pressure trunk construction remain concentrated in state-owned contractor pools, constraining private EPC scaling.
- Legacy compressor station integration:Retrofitting 1980s-vintage Daqing corridor infrastructure with modern turbine drives requires custom engineering without standardized component availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Oil and Gas Midstream Market |
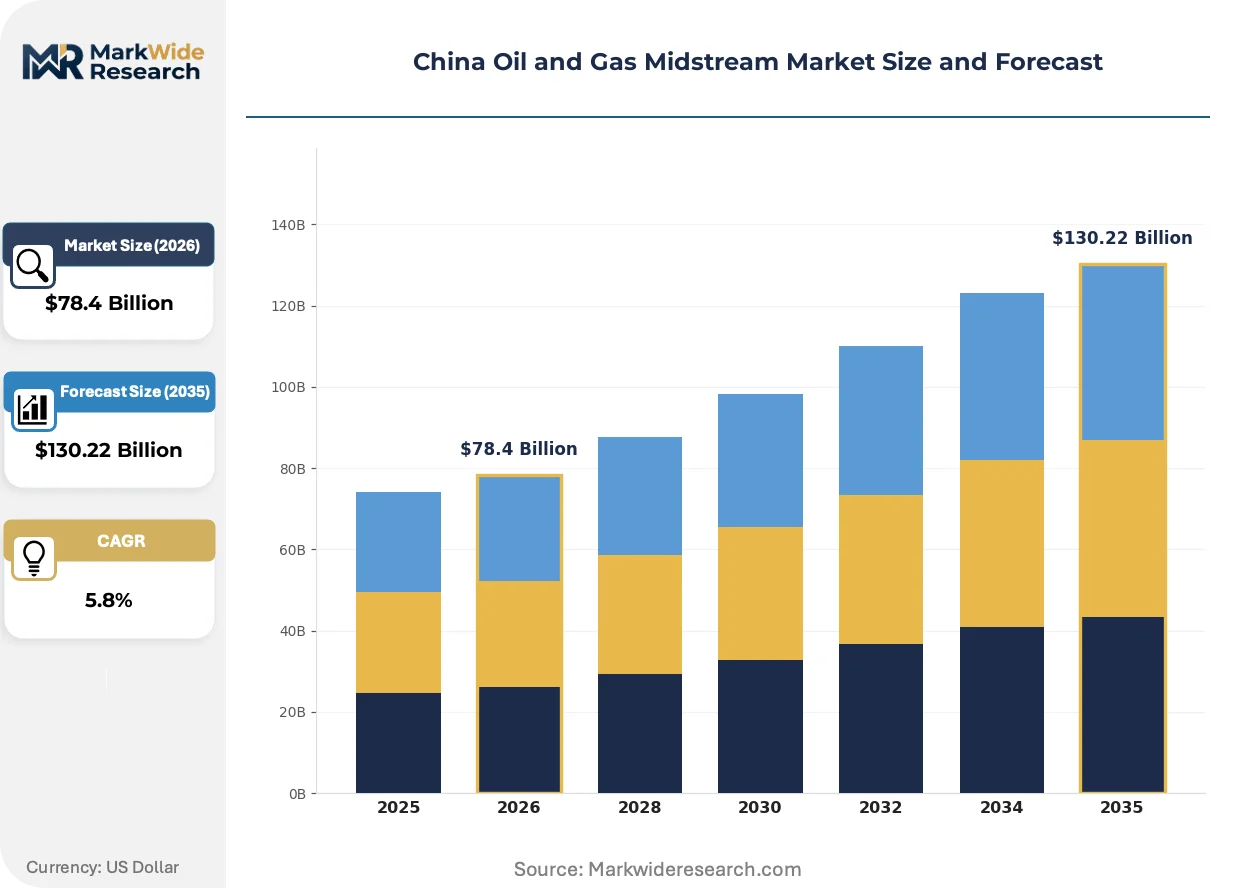
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Processing, Distribution Pipeline Type: Crude Oil, Natural Gas, NGL, Refined Products Infrastructure: Gas Plants, Compressor Stations, Pump Stations, Terminals Customer Type: Producers, Distributors, Traders, Industrial Users |
| Companies Covered | PetroChina Pipeline Company, CNOOC Gas & Power, China National Petroleum Corporation, Kunlun Energy, ENN Natural Gas, PipeChina, China Petroleum Pipeline Engineering Co., Guanghui Energy, Sinopec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Oil and Gas Midstream Market Strategic Shifts
Digital instrumentation and carbon accounting protocols are collapsing traditional operational boundaries between pipeline control rooms and environmental compliance departments, forcing concurrent technology and organizational redesign across midstream operators.
Intelligent pigging systems equipped with magnetic flux leakage sensors and ultrasonic crack detection are collapsing manual inspection schedules for trunk-line integrity management. PetroChina Pipeline Company and provincial distributors are adopting continuous-monitoring contracts that replace biennial shutdown-based surveys. This is collapsing the historical trade-off between throughput maximization and safety-margin maintenance, compressing insurance premiums and regulatory penalty exposure into unified risk models.
MEE enforcement of dual carbon targets tightens methane emission monitoring mandates across compressor stations and processing facilities. GB standards now require continuous emissions monitoring systems at all facilities above designated throughput thresholds. Gas plant operators in Sichuan and Ordos basins are responding by procuring optical gas imaging hardware and integrating leak-detection data into NEA-mandated environmental reporting portals.
Industrial offtakers along the Yangtze River Delta are consolidating procurement through long-term tolling agreements rather than spot-indexed pipeline contracts. This concentrates volume commitments among fewer petrochemical refiners while displacing traditional monthly nomination systems. The shift is most visible in Zhejiang and Jiangsu provinces, where state-owned refiners leverage storage-tank equity to negotiate preferential trunk-line access terms.
China Oil and Gas Midstream Market Segmentation
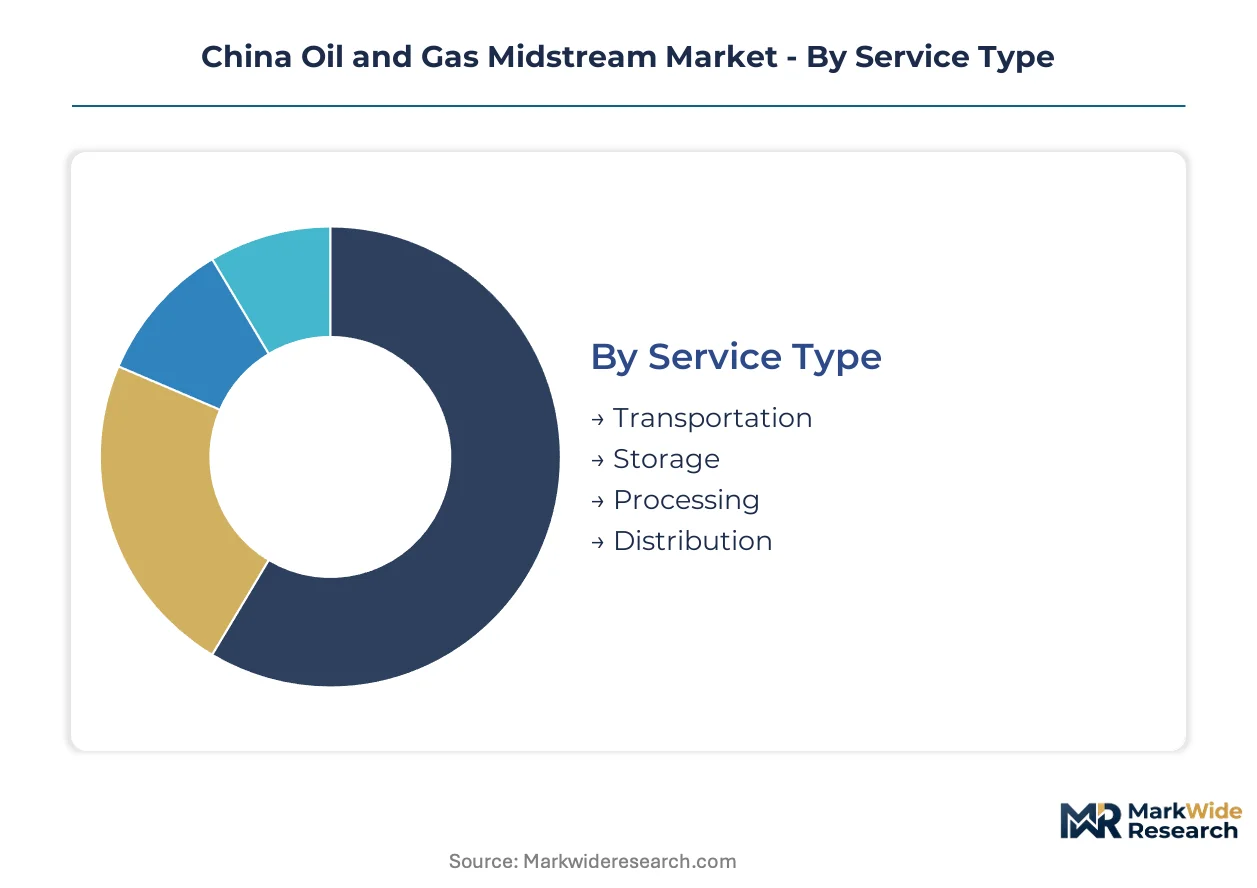
Midstream segmentation in China reflects the structural split between state-controlled trunk infrastructure and provincial distribution networks. PipeChina's consolidation has redefined how service categories compete for capital allocation and regulatory favor across Sichuan-to-coastal corridors.
Service Type:
After-sales service intensity varies sharply across these categories, with processing facilities requiring continuous MEE compliance monitoring while transportation contracts run on fixed tariff schedules with minimal ongoing technical support.
- Transportation:Trunk-line services aggregate volumes across west-to-east corridors at 6.4-12 MPa design pressure, with compressor stations spaced every 80-150 kilometers. Demand concentrates in Sichuan Basin shale corridors where PipeChina's national grid consolidation pulls dedicated gathering infrastructure investment; MEE methane standards force continuous hardware retrofit cycles at compressor stations.
- Storage:Strategic petroleum reserve mandates dominate crude tankage economics, while underground gas storage facilities serve seasonal peak-shaving for Yangtze River Delta industrial offtakers. Coastal LNG terminal capacity outpaces interior pipeline takeaway, stranding Sichuan production during injection seasons and compressing storage utilization rates.
- Processing:Gas plant fractionation extracts higher-value NGL components from Sichuan and Ordos basin feedstock. MEE-mandated carbon capture retrofits open EPC contracts for amine-based separation systems.
- Distribution:City-gate integration strategies extend downstream capture into tier-two industrial clusters, with ENN Natural Gas competing against provincial distributors for last-mile connectivity.
Transportation holds the largest share; momentum sits with Processing as carbon capture integration accelerates.
Pipeline Type:
Cost tier differentiation separates high-pressure trunk construction from lower-specification gathering lines, with X80/X100 steel grades commanding premium procurement budgets against standard X65 distribution networks.
- Crude Oil:PetroChina Pipeline Company leverages legacy Daqing-to-Dalian infrastructure to sustain dominant northeast throughput. High-grade steel input volatility from nickel and molybdenum spot markets compresses contractor margins on fixed-price EPC contracts.
- Natural Gas:Shale gas output from Sichuan and Ordos basins requires dedicated gathering and trunk infrastructure, outpacing crude equivalents in new construction permits. PipeChina's monopoly over west-to-east corridors limits third-party shipper access.
- NGL:Fractionation-bound liquids move through lower-pressure parallel systems tied to gas plant complexes in Sichuan Basin corridors.
- Refined Products:Sinopec anchors distribution through its Yangtze River petrochemical belt, with Zhejiang and Jiangsu refiners consolidating procurement through long-term tolling agreements.
Natural Gas commands the dominant capital allocation; refined products distribution networks are expanding most quickly through city-gate integration contracts.
Infrastructure:
Application-specific engineering requirements separate continuous-process gas plants from discrete compressor station retrofits, with GB-standard welding protocols shaping procurement specifications across all categories.
- Gas Plants:Post-combustion capture retrofits face MEE-mandated timelines, with Ordos and Sichuan operators procuring optical gas imaging hardware for leak-detection integration.
- Compressor Stations:1980s-vintage Daqing corridor infrastructure requires custom turbine drive retrofits without standardized component availability; welding technician scarcity constrains private EPC scaling.
- Pump Stations:Crude pipeline flow dynamics depend on spaced pumping capacity across PetroChina's legacy northeast networks.
- Terminals:CNOOC Gas & Power competes aggressively in coastal LNG receiving capacity, with storage-tank equity leveraged for preferential trunk-line access negotiations.
Gas Plants absorb the heaviest regulatory compliance investment; Compressor Stations face the steepest retrofit backlog.
Customer Type:
Volume concentration distinguishes large-scale producers from fragmented industrial offtakers, with tariff-regulated throughput allocation favoring state-backed entities over private distributors seeking third-party access reforms.
- Producers:Sichuan Basin shale operators depend on PipeChina trunk-line connectivity to coastal markets, facing stranded production risk during peak injection seasons.
- Distributors:Provincial networks seek digital twin convergence through SCADA-integrated monitoring contracts, with predictive maintenance AI offering asset management opportunities.
- Traders:Spot-indexed pipeline contract displacement concentrates volume commitments among fewer petrochemical refiners through long-term tolling structures.
- Industrial Users:Yangtze River Delta petrochemical belt offtakers consolidate procurement through storage-tank equity positions, negotiating preferential access terms.
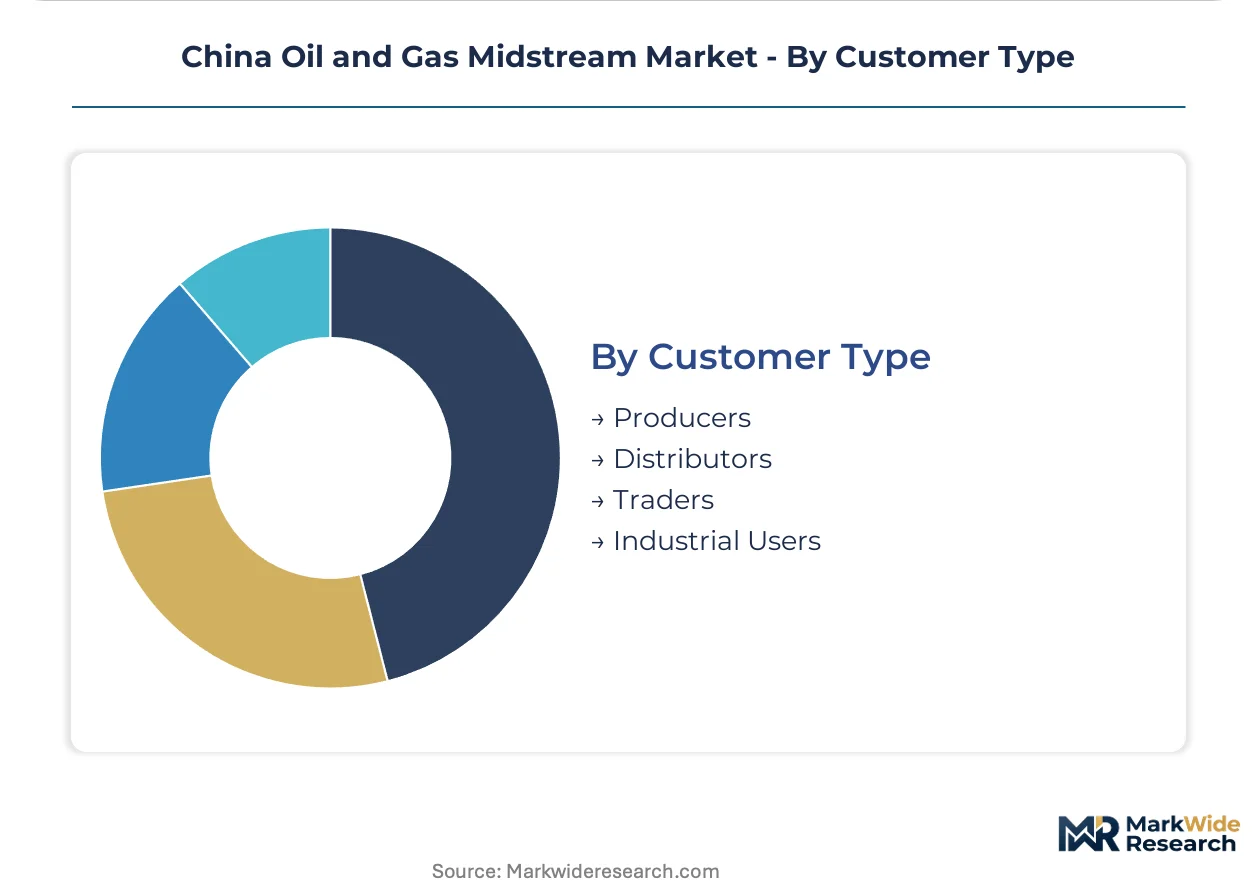
Industrial Users anchor volume commitments; Distributors are gaining share fastest through digital infrastructure upgrades and third-party access reform positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The West-East Gas Pipeline trunk system underwrites China's midstream dominance, anchoring cross-basin flows from Sichuan and Ordos production centers to coastal demand clusters. This infrastructure backbone shapes regional investment patterns and tariff allocation across provincial boundaries.
Sichuan-Chongqing
Shale gas output from the Fuling and Weirong fields drives gathering infrastructure expansion through the Sichuan Basin. MEE methane emission standards mandate leak-detection retrofits at compressor stations across the corridor. Chengdu anchors processing facility investment where amine-based carbon capture systems face mandated deployment timelines.
Yangtze River Delta
Petrochemical refiners in Zhejiang and Jiangsu provinces consolidate procurement through long-term tolling agreements displacing spot-indexed contracts. NEA interprovincial transmission tariffs reshape trunk-line access negotiations for industrial offtakers. Ningbo and Zhoushan LNG terminals leverage storage-tank equity to secure preferential throughput allocation.
Beijing-Tianjin-Hebei
Coal-to-gas switching policies in Hebei industrial zones sustain natural gas demand growth for heating and process applications. GB standards for pipeline steel grades shape procurement specifications for new distribution networks. Tianjin's LNG receiving terminal competes with Tangshan port infrastructure for northern supply security.
Shandong Peninsula
Refined products distribution networks seek last-mile connectivity upgrades to chemical processing clusters in Qingdao and Dongying. PipeChina's third-party access reforms create entry points for private distributors seeking city-gate integration contracts. Provincial carbon intensity benchmarks reshape gas plant retrofit priorities across the region.
Western China
The Daqing-to-Dalian corridor sustains dominant crude throughput volumes across Xinjiang and Gansu transit routes. Legacy compressor station integration challenges constrain retrofit timelines for 1980s-vintage infrastructure. Urumqi and Lanzhou anchor maintenance and logistics support for west-to-east trunk operations.
China Oil and Gas Midstream Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. State-backed trunk-line operators consolidate throughput allocation under PipeChina's national grid unification, collapsing legacy provincial hierarchies into centralized dispatch. Three archetypes dominate: pipeline engineering contractors, gas distribution integrators, and LNG terminal operators. Competitive moves concentrate on capacity expansion through EPC contracting and strategic positioning for third-party access reforms.
Within the state-backed platform tier, PetroChina Pipeline Company and CNOOC Gas & Power occupy anchor positions. ENN Natural Gas exemplifies the private distribution integrator archetype, pursuing city-gate capture strategies. PipeChina represents the consolidated national grid operator, unifying formerly fragmented provincial dispatch systems under centralized tariff regulation.
| Leading Market Players |
|---|
| PetroChina Pipeline Company |
| CNOOC Gas & Power |
| China National Petroleum Corporation |
| Kunlun Energy |
| ENN Natural Gas |
| PipeChina |
| China Petroleum Pipeline Engineering Co. |
| Guanghui Energy |
| Sinopec |
| Others |
Value Chain & Pricing Dynamics
The Daqing-to-Dalian crude corridor anchors freight cost differentials that cascade through supply concentration and downstream price tiers. PipeChina's centralized dispatch creates volume-based pricing power at trunk-line level while provincial distributors absorb margin compression in last-mile segments.
Pricing Analysis
Volume-discount tiering structures separate state-backed trunk-line contracts from provincial distribution agreements. Long-term tolling agreements with Yangtze River Delta petrochemical refiners command premium throughput allocation, while spot-indexed nominations face tariff volatility under NEA restructuring. Cost compression in gathering infrastructure intensifies from X80/X100 steel alloy volatility. Provincial distributors exhibit highest price sensitivity due to thin margins on city-gate integration contracts.
Supply Chain Analysis
Upstream feedstock flows concentrate in Sichuan Basin shale corridors and Ordos tight gas deposits, with steel mills in Hebei and Jiangsu provinces supplying pipeline grades. Nickel and molybdenum alloy inputs draw from global spot markets, while compressor station components source from domestic turbine manufacturers. Single-source vulnerability sits with high-grade steel procurement for trunk-line construction. Distribution runs through PipeChina's national grid consolidation into provincial dispatch hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial buyer power is concentrating through long-term tolling agreements that displace fragmented spot procurement, with Yangtze River Delta petrochemical refiners consolidating volume commitments among fewer counterparties.
For Market Incumbents: Pre-empt private distributor encroachment by securing city-gate integration contracts in tier-two industrial clusters before third-party access reforms open legacy corridors. Accelerate carbon capture retrofit timelines at Sichuan and Ordos gas plants to capture MEE compliance premiums ahead of mandated deadlines. Backward integration into optical gas imaging hardware procurement reduces leak-detection system vulnerability. For New Entrants and Emerging Players: Establish a beachhead in digital twin asset management services for provincial distribution operators seeking SCADA-integrated predictive maintenance. Target welding technician training partnerships with state-owned contractors to overcome GB-standard qualification scarcity. Position for third-party access reform positioning through ENN-style downstream capture models in Shandong Peninsula chemical clusters. For Investors and Strategic Acquirers: Carve-out targets emerge from provincial distributor networks facing margin pressure under PipeChina consolidation, particularly in Beijing-Tianjin-Hebei distribution corridors. Five-to-ten year viability favors operators with carbon capture retrofit completion and digital infrastructure deployment. Watch for NEA tariff restructuring announcements as inflection indicators for private participation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Deployment | MEE-mandated timelines at Sichuan and Ordos gas plants open EPC contracting windows for amine-based separation systems. |
| Third-Party Access Reform Positioning | NEA tariff restructuring may unbundle PipeChina legacy corridor capacity for private distributor entry. |
| Digital Twin Convergence | SCADA-integrated predictive maintenance AI offers asset management contracts to provincial distribution operators. |
| City-Gate Integration Expansion | Last-mile connectivity upgrades in Yangtze River Delta petrochemical belt capture downstream volume aggregation. |
| High-Grade Steel Procurement Hedging | X80/X100 alloy cost volatility from nickel and molybdenum spot markets demands contractor margin protection. |
Study Parameters
Initial hypotheses were tested against primary input from pipeline engineering directors, NEA regulatory affairs officers, EPC procurement leads, and gas plant operations managers and refined through secondary validation across NEA tariff filings, MEE emission compliance databases, PipeChina infrastructure disclosures, and customs steel import records. Bottom-up project pipeline assessment triangulated against top-down sectoral demand modeling.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across service type, pipeline type, infrastructure category, and customer archetype dimensions. CAGRs derived from infrastructure deployment schedules and throughput capacity expansion trajectories. Shale gas output projections from Sichuan and Ordos basins and MEE retrofit compliance timelines served as key forecast inputs.
Stress conditions across steel alloy spot volatility, NEA tariff restructuring pace, and MEE enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding PipeChina consolidation trajectory and dual carbon target adherence. Cross-checking against IEA China gas demand projections and PipeChina annual throughput disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Natural Gas Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
Oman Directional Drilling Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Flare Gas Recovery System Market
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Nigeria Wireline Logging Services Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Brazil Wireline Logging Services Market
Oil & Gas
Asia-Pacific Well Intervention Market
Oil & Gas
Hydraulic Fracturing Market