
 Oil-Injected Screw Compressor Market | 2026-2036
Oil-Injected Screw Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Oil-Injected Screw Compressor Market Insights
Pharmaceutical manufacturing is broadening its share of oil-injected screw compressor procurement as sterile process requirements tighten. Atlas Copco leverages its variable speed portfolio to anchor positions in FDA-validated facilities. Kaeser Kompressoren sustains dominance across German chemical parks through direct-drive efficiency programs. Ingersoll Rand competes on aftermarket service density in North American food processing corridors.
Oil-injected screw compressors are positive displacement machines where lubricating oil seals rotor clearances, typically operating at discharge pressures of 7–13 bar and flow rates from 0.3 to over 100 m³/min for industrial process air. The injected oil absorbs compression heat, enabling single-stage pressure ratios impossible in dry-running designs. Variable speed technology leads investment cycles as manufacturers seek load-matching efficiency below 70% utilization. Two-stage configurations command margin pools in petrochemical applications where discharge pressures exceed 10 bar. Single-stage units remain the volume base across general manufacturing.
EPA NESHAP standards for compressor station emissions shape product architecture in US oil and gas corridors. Ecodesign Directive Lot 31 mandates minimum efficiency thresholds for compressors sold across EU member states, accelerating variable frequency drive penetration. China's GB 19153 efficiency grades force redesigns for units imported or manufactured domestically. Stakeholders must monitor how refrigerant phase-down schedules under the Kigali Amendment redirect cooling application demand toward alternative compression architectures.
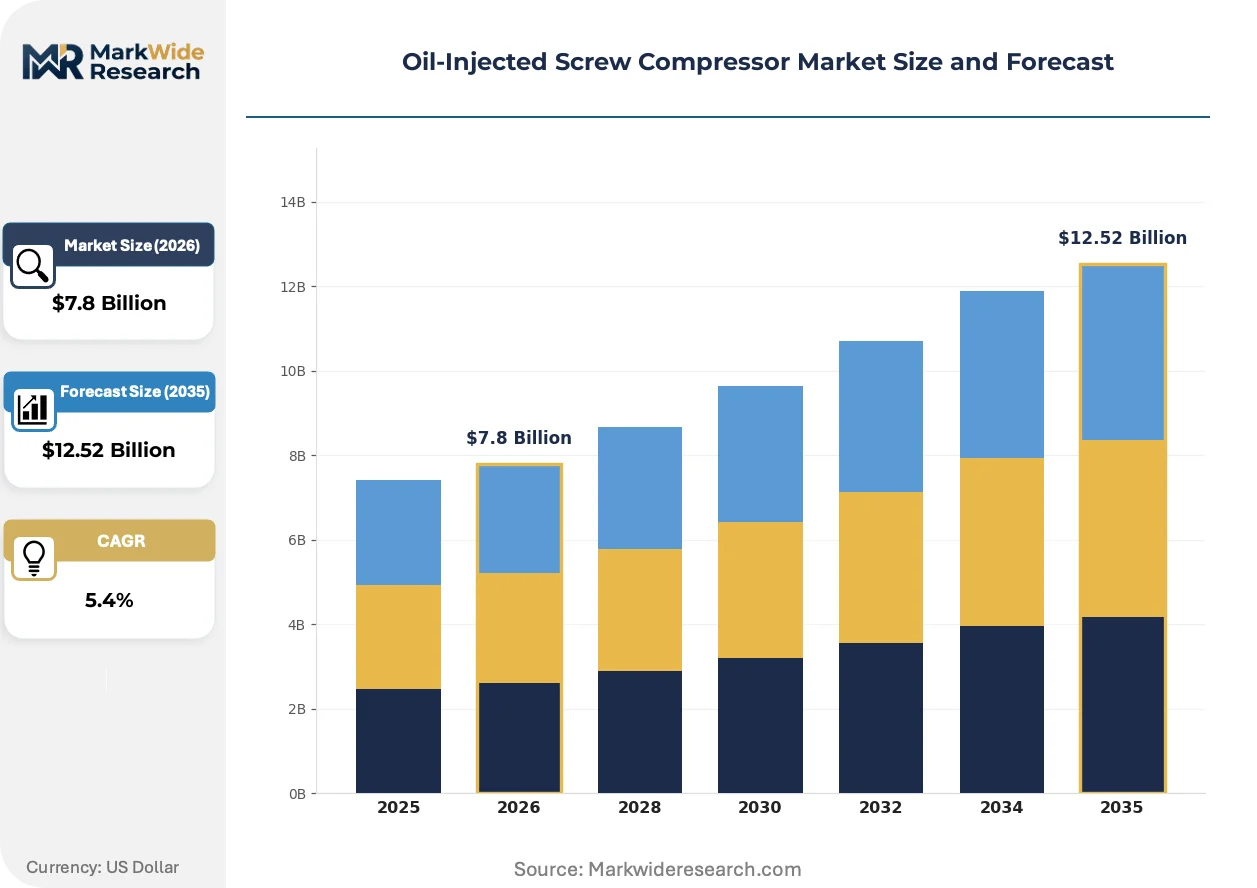
Market Dynamics
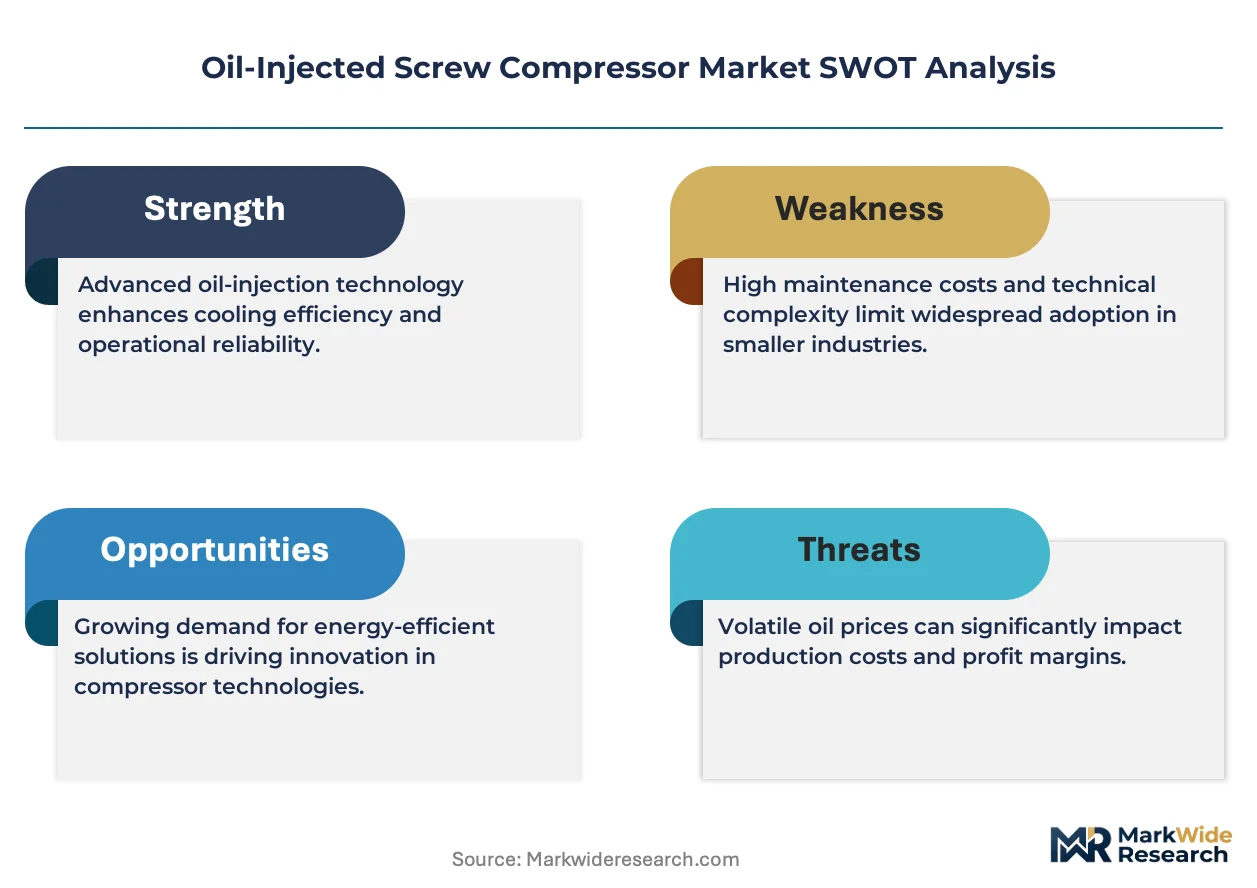
Variable frequency drive penetration is compressing single-stage unit margins while EU F-Gas retrofit cycles and pharmaceutical sterile process requirements pull two-stage configurations into premium positioning.
Growth Catalysts
- EU F-Gas Regulation phase-down:Refrigerant-based cooling retrofits are redirecting demand toward oil-injected screw architectures in German chemical parks and food processing corridors.
- Pharmaceutical sterile air requirements:FDA-validated facilities are specifying oil-injected units with integrated filtration trains for process air integrity.
- Variable speed technology maturation:Load-matching efficiency below 70% utilization is displacing fixed-speed legacy installations across general manufacturing.
Market Restraints
- Specialized steel and rare earth magnet costs:Rotor alloy specifications and permanent magnet supply concentration create input volatility for high-efficiency motor assemblies.
- Single-stage efficiency ceiling:Thermodynamic limits at discharge pressures above 10 bar force two-stage capital commitments in petrochemical applications.
- China GB 19153 efficiency grades:Domestic redesign requirements for imported units add compliance friction and extend product certification timelines.
Strategic Opportunities
- US oil and gas compressor station retrofits:EPA NESHAP emissions standards are creating replacement demand across Permian and Appalachian gathering systems.
- Heat recovery integration:Converging oil-cooling circuits with process heat networks is opening industrial decarbonization procurement channels.
- Aftermarket service unbundling:Predictive maintenance contracts and remote monitoring subscriptions are capturing lifetime value beyond initial equipment sales.
Industry Challenges
- Rotor profile grinding specialization:Precision machining expertise for asymmetric screw geometries concentrates in German and Swiss tooling corridors, constraining supplier scaling.
- FDA 21 CFR Part 11 validation:Pharmaceutical compressor installations require extensive documentation cycles that extend order-to-revenue timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil-Injected Screw Compressor Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Two Stage, Variable Speed, Oil-Free End User: Manufacturing, Chemical, Pharmaceuticals, Food & Beverage Application: Cooling, Pneumatic Tools, Drying, Packaging Technology: Direct Drive, Variable Frequency Drive, Rotary, Centrifugal |
| Companies Covered | Atlas Copco, Ingersoll Rand, Kaeser Kompressoren, Hitachi, Sullair, ELGi Equipments, Gardner Denver, Quincy Compressor, BOGE Kompressoren, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil-Injected Screw Compressor Market Trends and Innovations
Permanent magnet motor integration is compressing drivetrain footprints while regulatory efficiency mandates accelerate control system replacement cycles across installed bases.
Integrated permanent magnet synchronous motors are eliminating gearbox losses and reducing bearing count in compact package designs. Food processing facilities in the Netherlands and dairy cooperatives in Wisconsin are specifying these configurations for washdown environments. The technology is electrifying demand for cabinet-integrated units that displace separate motor-compressor assemblies.
EPA NESHAP standards for hazardous air pollutants are mandating leak detection and repair protocols at compressor stations. US midstream operators are retrofitting oil-injected screw packages with sealed bearing housings and improved shaft seals. The rule most affects gathering and boosting stations in Texas and North Dakota, where operators are consolidating vendor relationships to streamline compliance documentation.
Performance-based service agreements are replacing time-and-material maintenance contracts in industrial compressed air procurement. Automotive tier-one suppliers in Bavaria and electronics assemblers in South Korea are adopting kilowatt-per-cubic-meter pricing models. Equipment vendors are responding with IoT-enabled monitoring platforms that shift revenue toward guaranteed availability outcomes rather than spare parts margins.
Oil-Injected Screw Compressor Market Segmentation
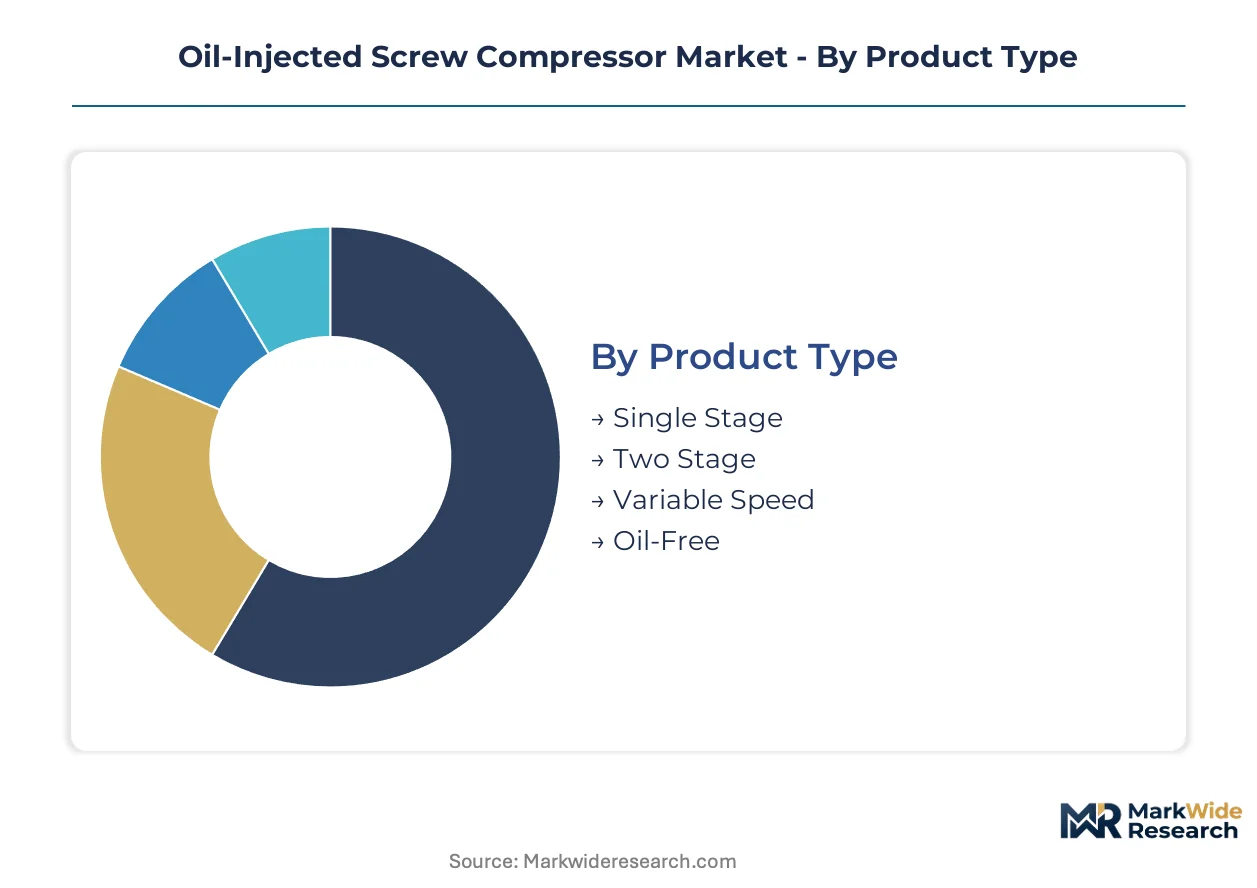
Oil-injected screw compressor procurement hinges on discharge pressure requirements, sterile process validation, and load-matching efficiency profiles. Buyers segment selections by thermodynamic stage, end-use contamination tolerance, and motor-drive architecture to optimize lifecycle cost against capital outlay.
Product Type:
Pressure ratio requirements and utilization patterns dictate whether buyers absorb single-stage capital efficiency or commit to two-stage thermodynamic performance.
- Single Stage:Delivers discharge pressures of 7–10 bar through one compression cycle with oil-flooded rotor sealing. General manufacturing facilities in Germany's Ruhr corridor deploy these for intermittent pneumatic tool networks where capital constraints outweigh efficiency premiums.
- Two Stage:Achieves discharge pressures exceeding 10 bar through intercooled compression sequences. Petrochemical complexes along the US Gulf Coast specify these configurations for process air demands that single-stage thermodynamics cannot satisfy.
- Variable Speed:Matches motor output to fluctuating demand profiles through integrated frequency control.
- Oil-Free:Eliminates lubricant contact with compressed air stream via timing gear synchronization.
Volume sits with Single Stage; growth tilts toward Variable Speed.
End User:
Contamination tolerance thresholds and regulatory validation burdens fragment demand across industrial sectors with divergent air quality specifications.
- Manufacturing:Encompasses automotive stamping, metal fabrication, and assembly operations requiring 7–8 bar process air. Bavarian automotive tier-one suppliers favor cabinet-integrated units with permanent magnet motors for floor-space efficiency.
- Pharmaceuticals:Demands FDA-validated compressed air systems with integrated filtration trains and 21 CFR Part 11 documentation. Sterile manufacturing suites in New Jersey and North Carolina specify oil-injected architectures with redundant coalescing stages.
- Chemical:Process air for reactor agitation and instrument purging across chlor-alkali and specialty chemical production.
- Food & Beverage:Packaging line pneumatics and product contact applications subject to USDA and EU hygiene codes.
Procurement volume concentrates in Manufacturing; Pharmaceuticals command the steepest expansion trajectory.
Application:
Heat rejection characteristics and moisture tolerance determine whether oil-injected architectures displace refrigerant-based alternatives.
- Cooling:Industrial process cooling and climate control applications where EU F-Gas Regulation phase-down redirects demand from hydrofluorocarbon systems. German chemical parks retrofit cooling circuits with oil-injected screw packages to circumvent refrigerant quota constraints.
- Pneumatic Tools:Assembly line power transmission requiring 6–7 bar supply pressure with intermittent demand spikes. Korean electronics assemblers specify variable speed units to dampen compressor cycling below 70% utilization.
- Drying:Desiccant regeneration and moisture removal processes in pharmaceutical packaging suites.
- Packaging:Form-fill-seal operations and conveyor actuation in food processing corridors.
Cooling applications absorb the largest installed base; Pneumatic Tools show the fastest technology refresh cycles.
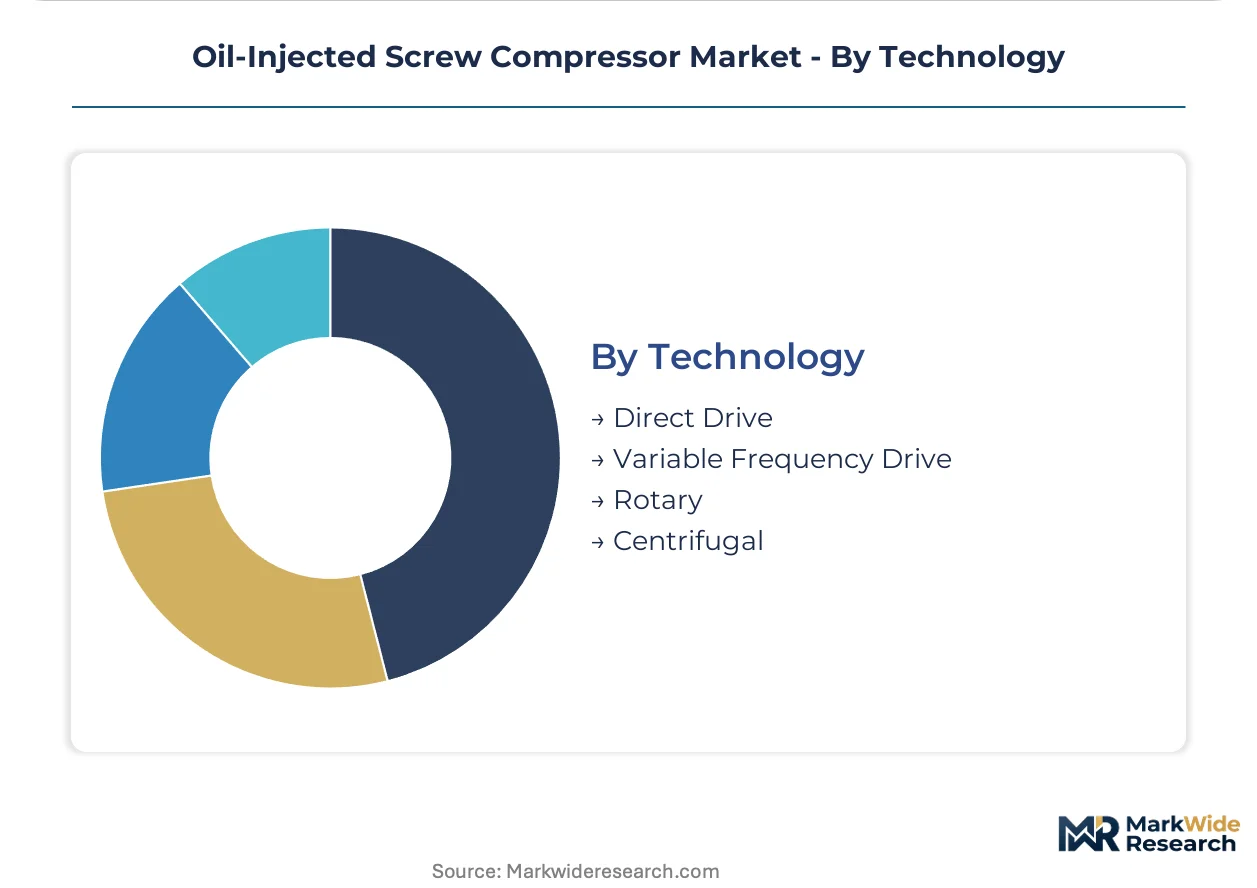
Technology:
Motor-drive integration depth and control precision separate premium configurations from commodity packages.
- Variable Frequency Drive:Modulates motor speed to match real-time demand, eliminating unload cycles. Wisconsin dairy cooperatives specify these for washdown environments where permanent magnet motors reduce bearing count and cabinet footprint.
- Direct Drive:Eliminates gearbox losses through shaft-coupled motor-compressor assemblies. Kaeser Kompressoren anchors German chemical park positions with efficiency programs built on this architecture.
- Rotary:Positive displacement compression through intermeshing helical rotors.
- Centrifugal:Dynamic compression for high-flow, moderate-pressure applications outside oil-injected screw sweet spots.
Direct Drive dominates current procurement; Variable Frequency Drive gains share fastest as efficiency mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial parks around the Ruhr and Bavaria anchor European demand concentration, with EU F-Gas Regulation retrofit cycles redirecting chemical processing facilities toward oil-injected screw architectures.
United States
EPA NESHAP emissions standards mandate leak detection protocols at compressor stations across Permian and Appalachian gathering systems. Midstream operators in Texas and North Dakota consolidate vendor relationships to streamline compliance documentation for oil-injected screw retrofits.
Germany
Chemical parks in North Rhine-Westphalia and Bavaria absorb two-stage configurations for process air demands exceeding 10 bar discharge pressure. EU F-Gas Regulation phase-down quotas push refrigerant-based cooling retrofits toward oil-injected screw packages in Ruhr corridor facilities.
China
GB 19153 efficiency grades force redesigns for imported and domestically manufactured compressor units. Manufacturing clusters in Yangtze River Delta and Pearl River Delta extend product certification timelines as compliance friction intensifies for variable speed portfolios.
India
Pharmaceutical manufacturing corridors in Maharashtra and Gujarat specify FDA-validated compressed air systems with integrated filtration trains. BIS efficiency mandates accelerate variable frequency drive penetration across general manufacturing installations in Tamil Nadu and Karnataka.
South Korea
Electronics assemblers in Seoul Capital Area and Busan-Ulsan specify variable speed units to dampen compressor cycling below 70% utilization. Korean industrial efficiency programs push load-matching technology into packaging line pneumatics and semiconductor fabrication facilities.
Oil-Injected Screw Compressor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in premium two-stage configurations and fragmented supply in single-stage commodity packages. European and North American specialists dominate high-efficiency motor-drive integration, while Asian fabricators concentrate on volume manufacturing of fixed-speed units. Three archetypes define competitive positioning: full-line industrial specialists with aftermarket service density, regional champions anchored in domestic chemical and pharmaceutical corridors, and component-focused OEMs supplying private-label distributors. M&A activity targets predictive maintenance platform capabilities, while capacity expansion concentrates in permanent magnet motor assembly lines.
Among European full-line specialists, Atlas Copco and Kaeser Kompressoren occupy positions defined by variable speed portfolio depth and direct-drive efficiency programs respectively. Ingersoll Rand represents the aftermarket service density archetype across North American food processing and industrial corridors. These three anchors illustrate how geographic origin and organizational structure map to divergent competitive vectors without converging on identical capability investments.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Kaeser Kompressoren |
| Hitachi |
| Sullair |
| ELGi Equipments |
| Gardner Denver |
| Quincy Compressor |
| BOGE Kompressoren |
| Others |
Pricing and Supply Chain Analysis
Rare earth magnet costs cascade from Chinese processing facilities through permanent magnet motor assemblies into premium-tier compressor pricing, with rotor alloy specifications from German and Swiss tooling corridors anchoring mid-tier positioning and spot-market steel from Indian mills feeding economy configurations.
Pricing Analysis
Short lead-time premiums compress margins for spot inventory holders while standard-contract pricing anchors volume procurement. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical installations from general manufacturing and intermittent pneumatic tool networks. Price differentiation rests on permanent magnet motor integration and certification grade for sterile process applications. Cost compression in single-stage units is intensifying because variable frequency drive penetration displaces fixed-speed legacy stock. General manufacturing facilities in Germany's Ruhr corridor exhibit highest price sensitivity; pharmaceutical suites in New Jersey and North Carolina demonstrate lowest sensitivity due to validation documentation burdens.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth magnet processors, where permanent magnet synchronous motor supply concentrates. Manufacturing draws from Germany and Switzerland for precision rotor profile grinding equipment, China for magnet alloys and motor laminations, and India for structural steel castings. Raw material dependencies include neodymium-iron-boron magnets, specialized rotor alloy steels, and high-grade copper windings. Tariff exposure on Chinese magnet exports creates supply chain risk for variable speed portfolios. Distribution runs through direct OEM channels for pharmaceutical and petrochemical accounts, with distributor networks serving general manufacturing and food processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oil-injected screw compressor market sits in a technology-transition phase where permanent magnet motor integration is displacing gearbox-coupled legacy architectures across installed bases.
For Market Incumbents: Anticipate margin compression in single-stage commodity tiers by accelerating permanent magnet motor capacity additions in German and Chinese assembly corridors. Defend pharmaceutical segment positioning through FDA 21 CFR Part 11 validation documentation investments that extend order-to-revenue timelines and lock out unqualified competitors. Channel control through certified service networks represents the critical lever for aftermarket revenue capture.
For New Entrants and Emerging Players: Launch via predictive maintenance platform subscriptions rather than equipment-only sales to bypass capital-intensive manufacturing scale requirements. White-space targets include heat recovery integration for industrial decarbonization procurement in Netherlands food processing facilities and EPA NESHAP compliance retrofit bundles for Permian basin midstream operators. The most penetrable segment is aftermarket service unbundling for installed bases above ten years of age.
For Investors and Strategic Acquirers: Atlas Copco's variable speed portfolio expansion in FDA-validated facilities is the leading indicator that pharmaceutical sterile process requirements are structurally upgrading market margins. Long-term viability favors full-line specialists with captive aftermarket service density over component-focused OEMs supplying private-label distributors. Acquisition target archetype: predictive maintenance platform capabilities with existing IoT-enabled monitoring deployments. Watch heat recovery integration contract announcements as the inflection signal for industrial decarbonization channel maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Integration | Eliminates gearbox losses and reduces bearing count in compact cabinet-integrated designs for washdown environments. |
| Backward Integration into Magnet Supply | Captures rare earth magnet cost volatility and secures variable speed motor assembly line feedstock stability. |
| Heat Recovery System Development | Opens industrial decarbonization procurement channels through converged oil-cooling and process heat networks. |
| Predictive Maintenance Platform Acquisition | Shifts revenue from spare parts margins toward guaranteed availability outcome-based contracts. |
| Long-term Service Agreement Expansion | Locks pharmaceutical and petrochemical accounts through kilowatt-per-cubic-meter pricing models with IoT monitoring. |
Research Methodology
Independent corroboration across maintenance directors at German chemical parks, plant engineers in US food processing corridors, OEM procurement teams, and aftermarket service heads underwrites the qualitative findings in this study. Primary interviews with these stakeholders combined with secondary validation from customs and trade data, compressed air industry association reports, SEC filings of listed compressor manufacturers, and EU Ecodesign Directive compliance databases established segment-level demand patterns. Bottom-up triangulation from installed base estimates and top-down cross-check against capital expenditure disclosures anchored the market sizing.
Comparable-period anchoring to historical efficiency regulation implementation cycles structured the projection methodology across the analysis window. The analytical framework modeled demand by product type, end-use sector, application, and motor-drive technology, with regional regulatory cluster as an additional dimension. CAGRs were derived from segment-level growth rate convergence against macro industrial production indices. Forecast inputs included EU F-Gas Regulation phase-down schedules, China GB 19153 efficiency grade adoption curves, and pharmaceutical sterile process validation timelines.
The model assumes a particular technology adoption path; alternative pathways for permanent magnet motor integration would alter the outlook if rare earth supply constraints accelerate or relax faster than baseline assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and industrial efficiency program funding levels. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Compressor Wheel Market
Compressors
Stationary Air Compressor Market
Compressors
Liquid Ring Compressors Market
Compressors
Air and Gas Compressor Market
Compressors
North America Hydrogen Compressor Market
Compressors
Rotary Lobe Compressor Market
Compressors
Industrial Air Compressor Market
Compressors
Compressor Rental Market
Compressors
Oil-Free Air Compressor Market
Compressors
Automotive Compressors Market
Compressors
High Speed Blowers Market
Compressors
Russia Reciprocating Compressor Market
Compressors
CNG Compressor Market
Compressors
Asia-Pacific Booster Compressor Market
Compressors
Regenerative Blowers Market
Compressors
Process Gas Compressors Market