
 Compressed Air Filtration and Dryer System Market | 2026-2036
Compressed Air Filtration and Dryer System Market Size, Share, and Industry Trends Forecast 2026-2036
Compressed Air Filtration and Dryer System Market Outlook
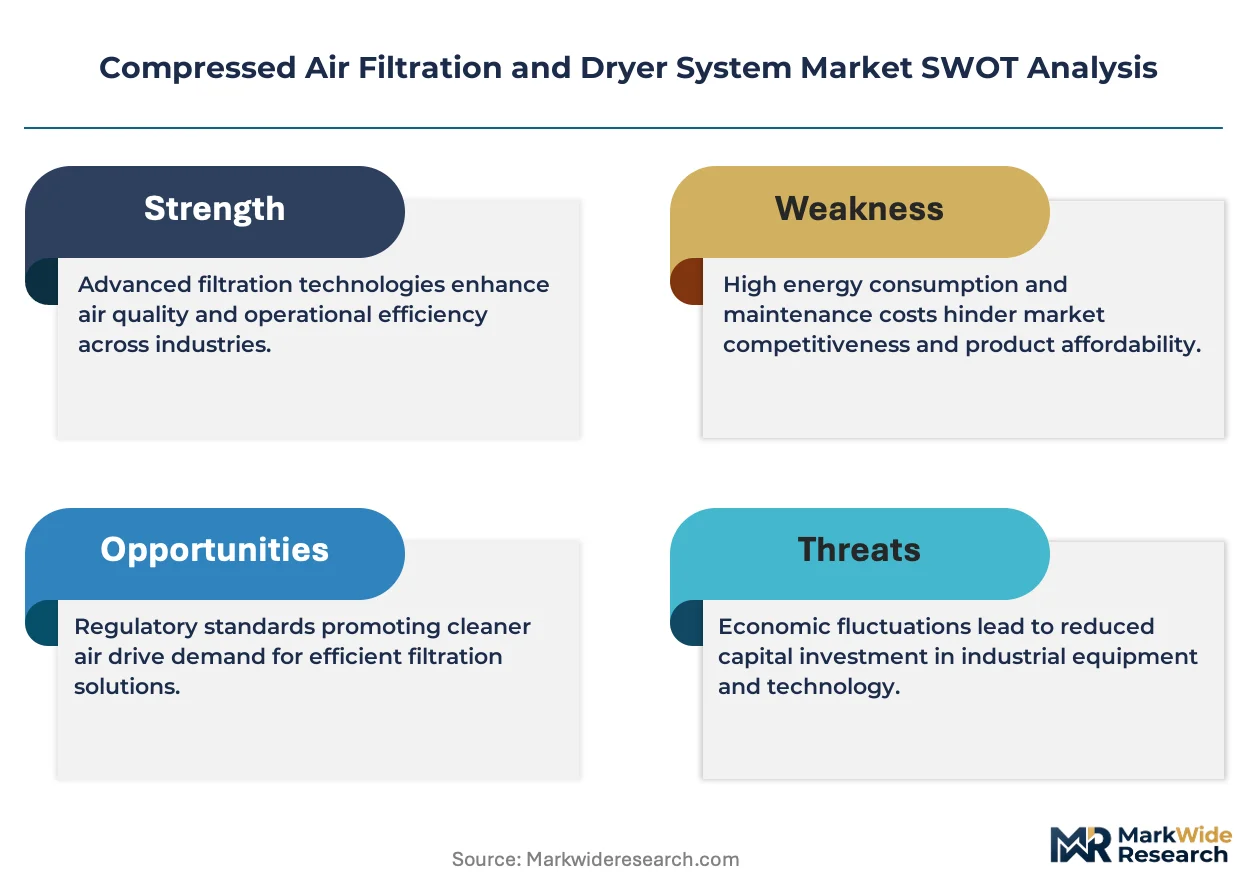
Distribution through industrial distributors and OEM bundling is fragmenting as direct-to-factory digital channels gain share. Atlas Copco leverages its aftermarket service network to sustain recurring revenue streams. Ingersoll Rand anchors North American demand through integrated compressor-dryer packages. Parker Hannifin Corporation differentiates via filtration membrane technology leadership across multiple end-use verticals.
Compressed air filtration and dryer systems remove moisture, particulate, and oil contaminants from compressed air streams, typically achieving pressure dew points ranging from -40°C to +3°C depending on dryer technology selected. These systems protect pneumatic tools, instrumentation, and process equipment from corrosion and contamination failure across manufacturing operations. Refrigerated dryers dominate volume shipments due to lower capital cost, while desiccant dryers command premium positioning in pharmaceutical and electronics applications where ISO 8573-1 Class 1.2.1 air quality proves mandatory. Membrane dryers represent the fastest-growing product category, benefiting from maintenance-free operation and point-of-use deployment flexibility.
ISO 8573 air quality classes, FDA cGMP guidelines for pharmaceutical manufacturing, and EPA energy efficiency standards collectively shape equipment specification requirements and market access conditions across major economies. The EU Green Deal and F-Gas Regulation increasingly constrain refrigerant selection in refrigerated dryer designs, redirecting R&D investment toward alternative drying technologies. Stakeholders must monitor evolving refrigerant phase-down schedules and energy labeling requirements to align product portfolios with compliance trajectories.
Market Dynamics
ISO 8573 air quality mandates and the EU F-Gas Regulation are compressing refrigerant-based dryer designs while redirecting capital toward membrane and heat-of-compression alternatives. Equipment buyers now specify dew point guarantees in procurement contracts rather than accepting nominal catalog ratings.
Growth Catalysts
- Pharmaceutical purity mandates:FDA cGMP guidelines for sterile manufacturing require ISO 8573-1 Class 1.2.1 compressed air, forcing facility upgrades across injectables and biologics production.
- Electronics miniaturization:Semiconductor fabs in Taiwan and South Korea demand -70°C pressure dew points for lithography tools, expanding desiccant dryer deployment.
- EU Green Deal enforcement:The F-Gas Regulation's refrigerant phase-down schedule accelerates R&D investment in alternative drying technologies across German and Italian industrial corridors.
Market Restraints
- Aluminum and copper price volatility:Heat exchanger fabrication depends on non-ferrous metals whose commodity swings compress OEM margins and delay project approvals.
- Refrigerant supply concentration:EU-based fluorochemical producers control low-GWP refrigerant supply, creating bottleneck risk for refrigerated dryer manufacturers.
- Desiccant bed degradation:Activated alumina and molecular sieve replacement cycles impose lifecycle cost penalties that membrane technologies exploit.
Strategic Opportunities
- India pharmaceutical clusters:CDSCO enforcement of international GMP standards at Hyderabad and Ahmedabad bulk drug parks creates first-time specification demand.
- Heat-of-compression integration:Converging variable-speed compressor controls with thermal regeneration dryers eliminates purge air loss in large automotive plants.
- Direct-to-factory digital channels:OEM-configurator platforms bypass industrial distributors, capturing margin and installation data for aftermarket service attachment.
Industry Challenges
- Field service technician scarcity:Refrigeration and pneumatic system cross-training requirements outpace vocational pipeline output in Midwest US manufacturing zones.
- Legacy controller integration:Modbus and Profinet protocol mismatches between new dryers and existing SCADA architectures extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressed Air Filtration and Dryer System Market |
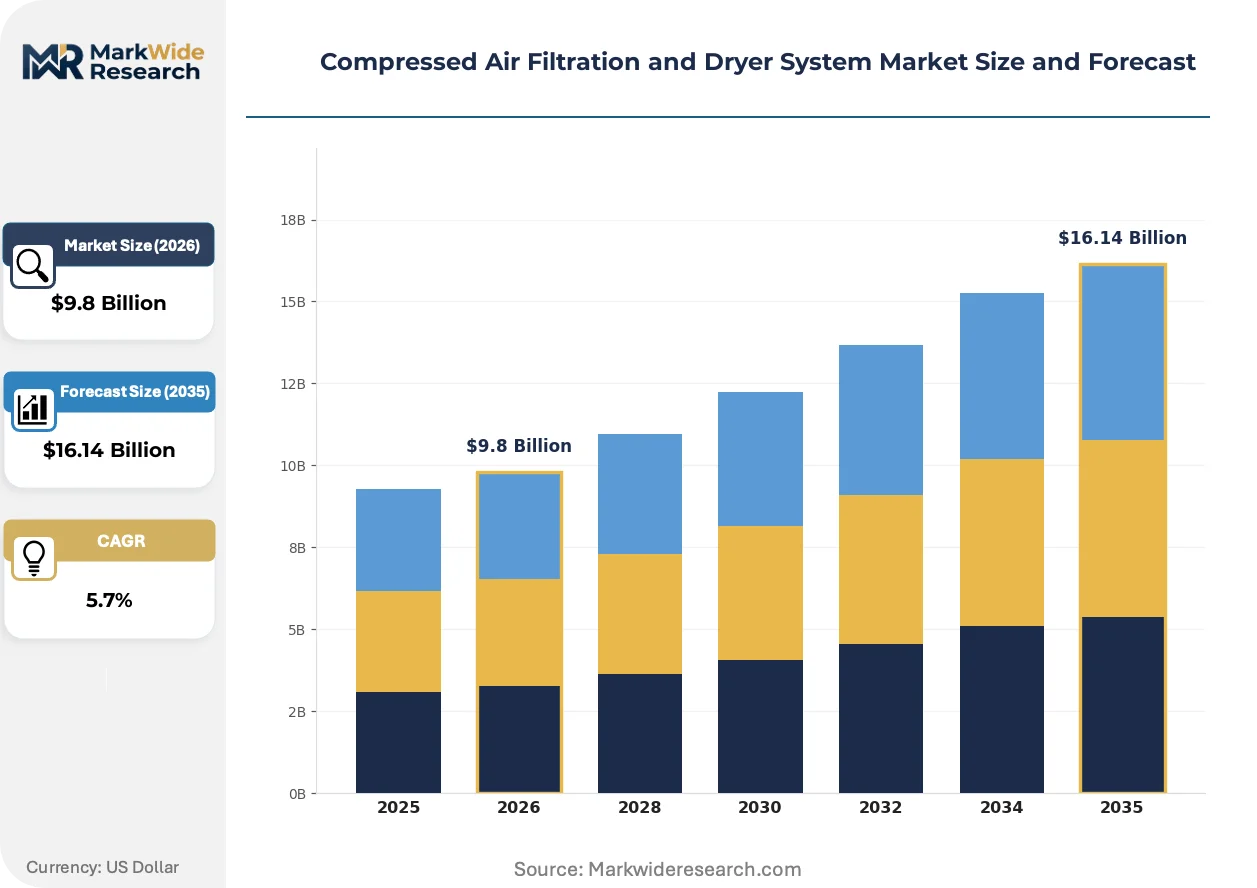
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Dryers, Refrigerated Dryers, Desiccant Dryers, Coalescing Filters End User: Manufacturing, Food & Beverage, Pharmaceuticals, Automotive Technology: Activated Carbon, Cyclone Separation, Filtration Membrane, Pressure Swing Adsorption Application: Pneumatic Tools, Process Control, Packaging, Quality Assurance |
| Companies Covered | Atlas Copco, Ingersoll Rand, Parker Hannifin Corporation, Donaldson Company, Inc., Sullair, Gardner Denver, Pentair, SPX Flow, Inc., Kaeser Kompressoren, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressed Air Filtration and Dryer System Market Strategic Shifts
Membrane materials and smart monitoring architectures are collapsing the traditional boundary between centralized drying infrastructure and point-of-use purification. Equipment intelligence now enables predictive maintenance contracts that shift revenue from hardware to uptime guarantees.
Hollow-fiber membrane dryers are collapsing the capital cost gap with refrigerated units while eliminating moving parts and refrigerant compliance burden. Food and beverage packagers in the Netherlands and Belgium are specifying these systems for bottling line point-of-use deployment. The technology is collapsing preventive maintenance schedules and technician dispatch requirements across mid-scale manufacturing operations.
The EU F-Gas Regulation's 2024 step-down in HFC refrigerant quotas forces refrigerated dryer OEMs to qualify propane and CO2 alternatives. Heat exchanger redesigns and safety certification delays are compressing product launch timelines. German TÜV and Italian IMQ certification bodies report extended queue lengths for pressure equipment approvals.
Compressed air audit services are unbundling from equipment sales as independent energy consultants capture facility assessment contracts. Automotive tier-one suppliers in Stuttgart and Wolfsburg now procure drying specifications separately from compressor packages. This bifurcation is visible across German automotive supplier parks where energy managers retain direct vendor relationships.
Compressed Air Filtration and Dryer System Market Segmentation
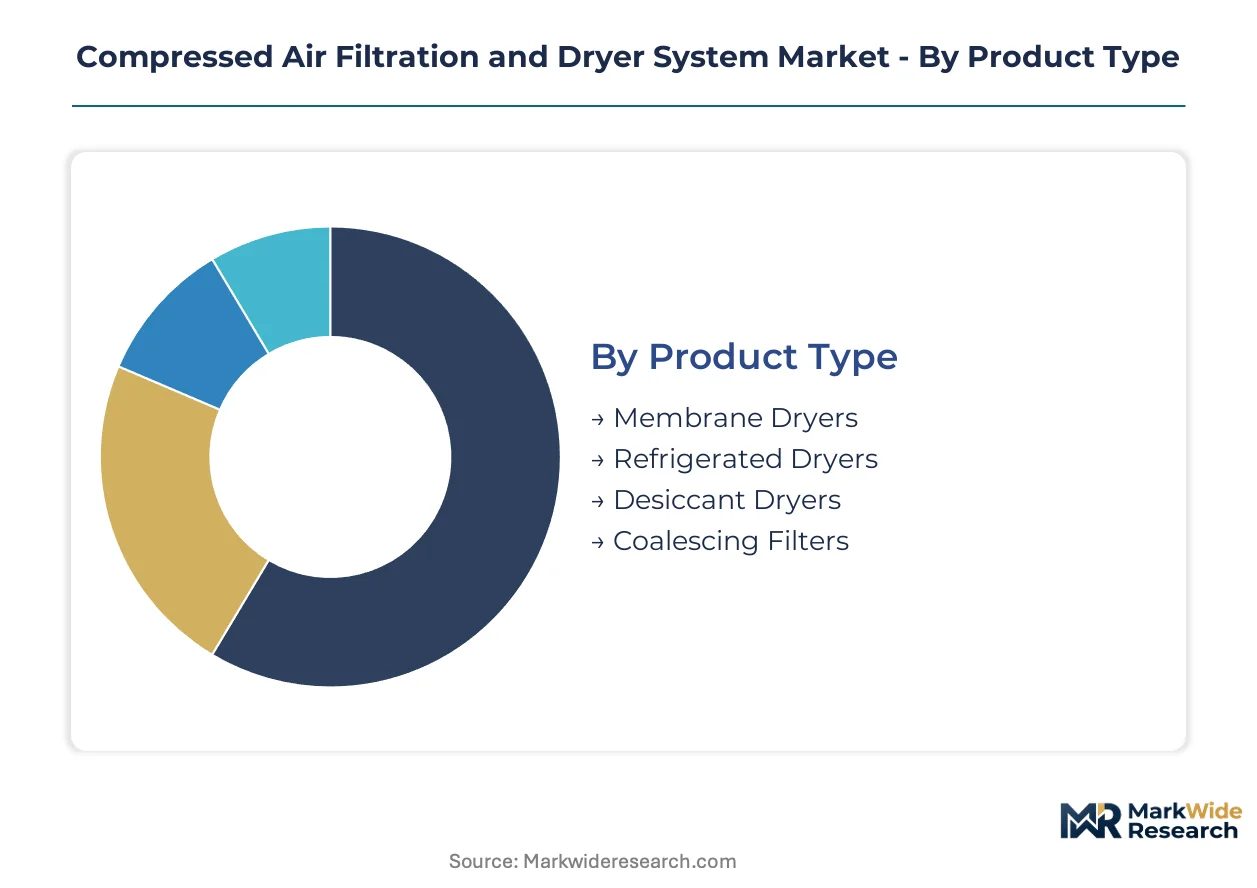
Technology selection in compressed air treatment hinges on dew point requirements, energy constraints, and regulatory compliance costs. Segmentation reveals how membrane materials and smart architectures are collapsing traditional boundaries between centralized infrastructure and point-of-use deployment.
Product Type:
Cost tier differentiation separates capital-intensive centralized systems from maintenance-light point-of-use alternatives.
- Membrane Dryers:Hollow-fiber polymer membranes separate water vapor through selective permeation without moving parts or refrigerants. Food and beverage packagers in the Netherlands specify these for bottling line point-of-use deployment where F-Gas compliance costs dominate lifecycle economics.
- Refrigerated Dryers:Mechanical refrigeration circuits cool compressed air to condense moisture, typically achieving +3°C pressure dew points. German automotive suppliers in Stuttgart retain these for high-volume assembly lines despite EU refrigerant phase-down pressures.
- Desiccant Dryers:Activated alumina or molecular sieve beds adsorb moisture through pressure swing or thermal regeneration cycles. Semiconductor fabs in Taiwan demand these for -70°C dew point guarantees.
- Coalescing Filters:Borosilicate microfiber media capture oil aerosols and sub-micron particulates downstream of compression. These protect pneumatic instrumentation across process industries.
Refrigerated dryers hold installed capacity. Membrane dryers are rotating up the share rankings.
End User:
Application-specific purity mandates create divergent specification intensity across verticals.
- Manufacturing:General fabrication tolerates ISO 8573-1 Class 4.2.2 air quality, driving volume shipments of refrigerated units. Midwest US metalworking clusters prioritize capital efficiency over dew point precision.
- Pharmaceuticals:FDA cGMP sterile manufacturing mandates ISO 8573-1 Class 1.2.1 compressed air, forcing desiccant dryer deployment with continuous monitoring. Hyderabad and Ahmedabad bulk drug parks drive specification upgrades as CDSCO enforces international GMP standards.
- Food & Beverage:Packaging line hygiene requirements favor membrane point-of-use systems for their oil-free operation and minimal maintenance. Belgian breweries specify these for bottling integrity.
- Automotive:Paint shop robotics and assembly pneumatics demand stable dew points to prevent corrosion in precision tooling. Wolfsburg supplier parks integrate heat-of-compression regeneration to eliminate purge air losses.
Manufacturing dominates unit shipments. Pharmaceuticals command the steepest expansion trajectory.
Technology:
Maturity gradients separate established mechanical methods from emerging materials science approaches.
- Filtration Membrane:Asymmetric hollow-fiber structures achieve dew point suppression through water vapor partial pressure differentials. These eliminate refrigerant compliance burdens entirely.
- Pressure Swing Adsorption:Twin-tower desiccant configurations alternate between drying and regeneration cycles using compressed air purge or external heat. Electronics miniaturization in South Korea drives demand for -70°C capability.
- Activated Carbon:Adsorbent media remove oil vapor and hydrocarbon contaminants downstream of coalescing stages. These protect sensitive instrumentation.
- Cyclone Separation:Centrifugal force extracts bulk liquid water and large particulates as pretreatment. These extend downstream component life in high-humidity environments.
Pressure swing adsorption holds installed capacity. Filtration membrane is climbing the fastest.
Application:
Criticality tiers separate uptime-sensitive process control from intermittent tool operation.
- Process Control:Instrument air for valves and transmitters demands continuous dew point stability to prevent freeze-ups. Petrochemical complexes in the US Gulf Coast specify redundant desiccant trains.
- Quality Assurance:Metrology and testing equipment requires ISO 8573-1 Class 2.1.1 air to prevent measurement drift. Semiconductor lithography tools represent the most stringent specification envelope.
- Pneumatic Tools:Impact wrenches and actuators tolerate higher moisture content, prioritizing flow capacity over dew point precision. General machine shops dominate this segment.
- Packaging:Form-fill-seal operations and aseptic filling require oil-free, dry air to prevent product contamination. Pharmaceutical blister packaging lines drive specification intensity here.
Pneumatic tools hold installed capacity. Quality assurance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight rail network underwrites Germany's industrial machinery export dominance. Taiwan's Kaohsiung container port anchors semiconductor supply chains feeding desiccant dryer demand. India's Dedicated Freight Corridors are redrawing pharmaceutical distribution geography.
Germany
Automotive paint shops and precision tooling clusters drive specification intensity. The EU F-Gas Regulation's HFC phase-down schedule forces refrigerant substitution in refrigerated dryer designs. Stuttgart and Wolfsburg supplier parks integrate heat-of-compression regeneration to eliminate purge air losses.
United States
Petrochemical instrument air redundancy and Midwest metalworking automation sustain refrigerated dryer volumes. EPA energy efficiency standards shape equipment procurement specifications for federal contractors. The US Gulf Coast chemical corridor specifies redundant desiccant trains for process control uptime.
China
Semiconductor localization drives -70°C dew point demand for lithography tools. MIIT industrial upgrading guidelines accelerate compressed air system efficiency retrofits. Yangtze River Delta fabs expand desiccant capacity for domestic chip self-sufficiency targets.
India
Hyderabad and Ahmedabad bulk drug parks face first-time ISO 8573-1 Class 1.2.1 enforcement. CDSCO's international GMP alignment mandates force facility upgrades across injectables production. Western pharmaceutical clusters drive specification demand previously absent in domestic manufacturing.
South Korea
Memory and logic semiconductor fabrication sustains premium desiccant dryer procurement. MFDS pharmaceutical manufacturing guidelines align with FDA cGMP for export-oriented production. Pyeongtaek and Hwaseong fab complexes anchor regional demand for ultra-dry compressed air systems.
Compressed Air Filtration and Dryer System Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in filtration media and membrane materials. Market structure concentrates around bundled compressor-dryer packages and point-of-use purification modules. Three archetypes dominate: diversified industrial conglomerates with aftermarket service networks, filtration-focused technology licensors, and regional compressor OEMs with captive dryer lines. Competitive moves center on refrigerant technology qualification races and direct-to-factory digital channel construction.
Among diversified industrial conglomerates, Atlas Copco and Ingersoll Rand exemplify platform integration strategies. Parker Hannifin Corporation occupies a position within the component specialist tier. These three anchors represent divergent approaches to recurring revenue capture—aftermarket service attachment, integrated package bundling, and materials technology licensing respectively.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Parker Hannifin Corporation |
| Donaldson Company, Inc. |
| Sullair |
| Gardner Denver |
| Pentair |
| SPX Flow, Inc. |
| Kaeser Kompressoren |
| Others |
Value Chain & Pricing Dynamics
Stuttgart's automotive supplier concentration shapes downstream pricing power for compressed air treatment systems, with OEM procurement clusters extracting volume concessions that ripple through membrane and desiccant dryer tiers. Heat exchanger fabrication costs in the Rhine-Ruhr corridor feed directly into refrigerated dryer pricing negotiations across European industrial distributors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 8573-1 Class 1.2.1 certified desiccant systems from refrigerated units and point-of-use membrane modules. Certification grade and after-sales service bundling drive price differentiation, with pharmaceutical buyers accepting premium positioning for FDA cGMP compliance. Cost compression in standard-tier refrigerated dryers intensifies because aluminum and copper commodity swings compress OEM margins. Midwest US metalworking clusters exhibit highest price sensitivity, while semiconductor fabs in Taiwan show lowest.
Supply Chain Analysis
Export-control restrictions on hollow-fiber membrane manufacturing equipment limit technology transfer to emerging production hubs. Supply concentrates in Germany, China, and the United States for compressor-dryer integrated systems. Heat exchanger aluminum, activated alumina desiccant media, and fluorochemical refrigerants constitute critical input dependencies. Single-source vulnerability runs through EU-based low-GWP refrigerant producers controlling F-Gas Regulation-compliant chemistries. Distribution runs through industrial distributors and direct-to-factory digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation's refrigerant phase-down schedule triggers a high-growth disruption as heat-of-compression and membrane technologies displace legacy refrigerated dryer architectures.
For Market Incumbents: Insulate aftermarket service revenue by embedding predictive maintenance IoT architectures that lock in multi-year uptime contracts. Deepen backward integration into hollow-fiber membrane production to capture margin from fastest-growing product category. Atlas Copco and Ingersoll Rand service networks face substitution threat from independent energy consultants unbundling compressed air audits. For New Entrants and Emerging Players: Build out point-of-use membrane dryer deployment for food and beverage packaging lines in Belgium and the Netherlands where F-Gas compliance costs dominate lifecycle economics. Target India's Hyderabad and Ahmedabad pharmaceutical clusters facing first-time ISO 8573-1 Class 1.2.1 enforcement. Pursue direct-to-factory digital channel partnerships bypassing established industrial distributor networks. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because environmental and pharmaceutical purity mandates structurally expand addressable market for premium drying technologies. Acquisition target archetype: membrane materials specialists with TÜV or IMQ certification traction. Watch refrigerant substitution approval timelines at German and Italian pressure equipment bodies as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-of-Compression Integration | Eliminates purge air losses in Stuttgart automotive supplier parks under EU energy efficiency directives. |
| Membrane Materials R&D Investment | Collapses capital cost gap with refrigerated dryers while sidestepping F-Gas Regulation compliance burden. |
| Direct-to-Factory Digital Channel | Bypasses industrial distributors to capture installation data for aftermarket service attachment. |
| Predictive Maintenance Platform | Shifts revenue model from hardware sales to uptime guarantees with pharmaceutical manufacturers. |
| Refrigerant Substitution Qualification | Propane and CO2 alternatives require TÜV and IMQ certification queue navigation. |
Study Parameters
The analysis maps refrigerated dryer, desiccant dryer, membrane dryer, and filtration system segments, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interviews combined with secondary validation from customs/trade data, SEC 10-K filings, and EU F-Gas Regulation implementation reports. Bottom-up equipment shipment tallies and top-down industrial energy consumption estimates undergo triangulation.
Assumptions held fixed include EU F-Gas Regulation phase-down schedules and ISO 8573 air quality class enforcement intensity across the projection horizon. Segmentation dimensions span technology type, end-use vertical, dew point specification tier, and regional production cluster. CAGRs derive from equipment replacement cycle analysis and facility expansion pipelines. Industry-specific inputs include semiconductor fab capacity additions and pharmaceutical GMP certification timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by membrane technology specialists or refrigerant chemistry disruptors would shift outcomes. Material shifts in EU refrigerant quota allocations or CDSCO enforcement intensity in Indian pharmaceutical clusters would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
North America Air Compressor Market
Compressors
Liquid Ring Compressors Market
Compressors
PAG Compressor Oil Market
Compressors
Industrial Air Compressor Market
Compressors
High Speed Blowers Market
Compressors
Air Compressor Market
Compressors
Process Gas Compressors Market
Compressors
Centrifugal Compressors Market
Compressors
North America Centrifugal Compressor Market
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Asia-Pacific Booster Compressor Market
Compressors
LNG Compressor Market
Compressors
Oil and Gas Industry Gas Compressor Market
Compressors
Positive Displacement Gas Compressor Market
Compressors
Tandem Piston Compressors Market
Compressors
Hydrogen Compressor Market