
 Rotary Lobe Compressor Market | 2026-2036
Rotary Lobe Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Lobe Compressor Market Analytics
Buyer concentration across European water utilities is rebalancing as municipal procurement consolidates into framework agreements spanning multiple treatment facilities. Aerzener Maschinenfabrik GmbH leverages its heritage in positive displacement engineering to sustain premium positioning among German municipal clients. Kaeser Kompressoren SE anchors its competitiveness through extensive service networks across Central European industrial zones. Atlas Copco AB competes by extending its compressor technology portfolio into integrated vacuum and pressure solutions for process industries.
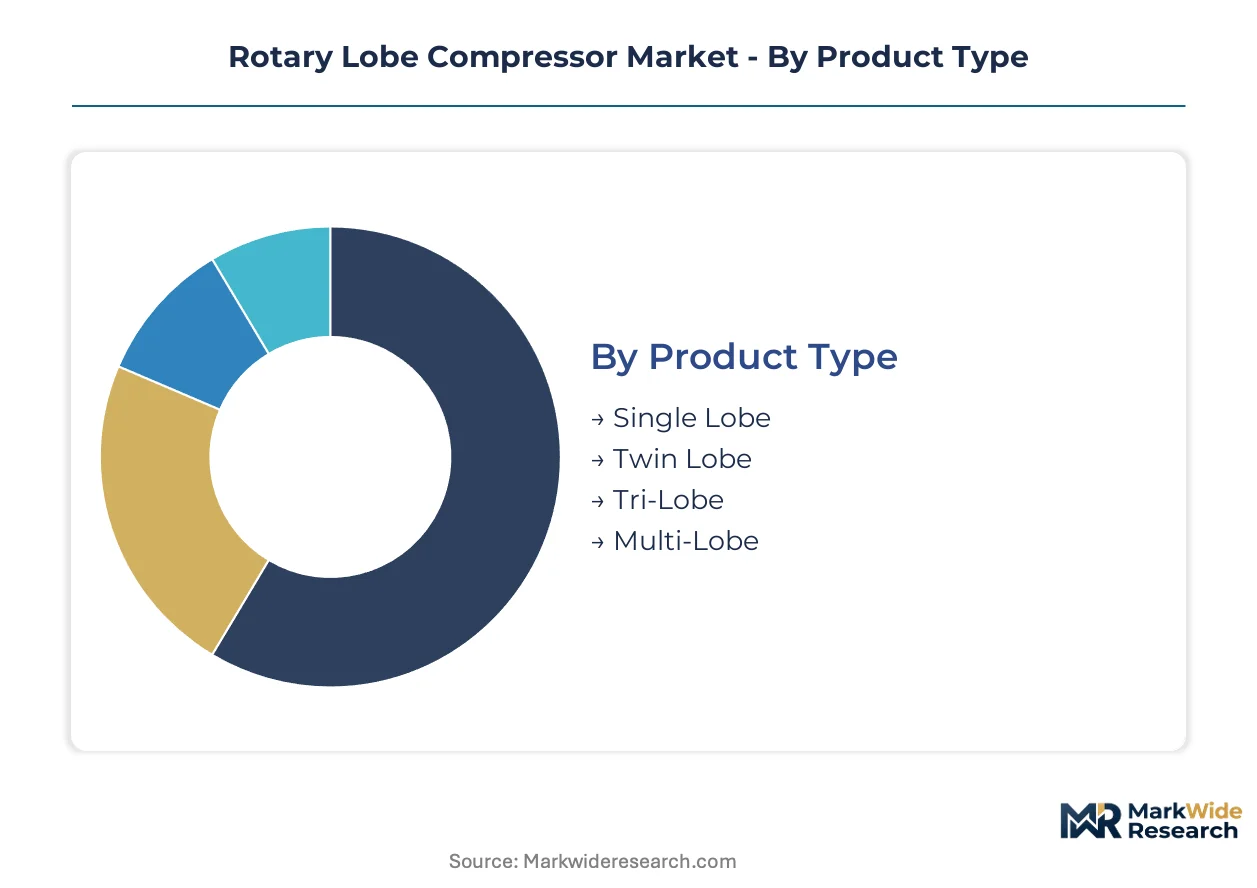
A rotary lobe compressor employs two intermeshing lobed rotors operating without internal compression to deliver pulsation-free air or gas flow at discharge pressures typically below 15 bar, serving aeration, pneumatic conveying, and vacuum hold-down applications. Twin lobe configurations dominate mature wastewater treatment installations where reliability and parts availability outweigh efficiency premiums. Tri-lobe designs lead growth in pharmaceutical cleanroom and food packaging lines where reduced pulsation protects sensitive product integrity. Multi-lobe variants occupy emerging niches in chemical vapor recovery systems demanding minimal gas contamination.
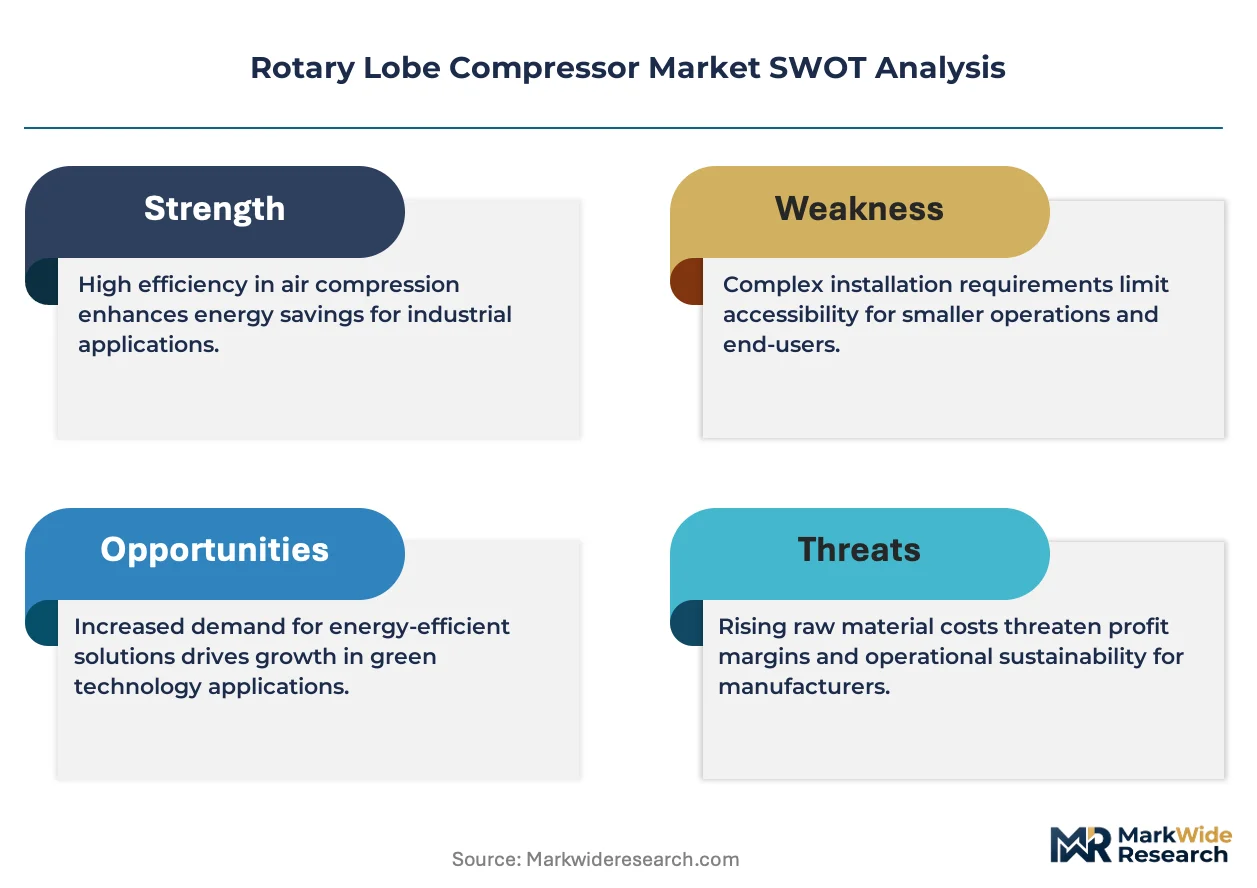
EPA effluent guidelines and EU F-Gas Regulation phase-down schedules are forcing treatment operators toward oil-free rotary lobe architectures that eliminate lubricant discharge risks. ISO 8573 air purity classes and CE marking under the Machinery Directive shape product certification requirements for cross-border equipment sales. Germany's KBA and France's ANSM enforce sector-specific compliance protocols that filter market access for non-conforming suppliers. Stakeholders must monitor evolving carbon border adjustment mechanisms and decide whether to localize assembly within regulated jurisdictions or absorb incremental certification overhead.
Market Dynamics
EPA effluent guidelines and EU F-Gas Regulation phase-down schedules are forcing wastewater treatment operators toward oil-free rotary lobe architectures that eliminate lubricant discharge risks. This regulatory compression is restructuring procurement patterns across municipal and industrial buyer segments.
Growth Catalysts
- Tightening EPA emissions standards:US wastewater facilities face mandated equipment upgrades that favor oil-free positive displacement technologies over legacy lubricated systems.
- EU F-Gas Regulation compliance:The phase-down schedule accelerates replacement demand for compressors using low-global-warming-potential refrigerants and leak-tight designs.
- Aeration system expansion:Germany and China are deploying rotary lobe compressors across expanding municipal treatment infrastructure.
Market Restraints
- Specialized alloy input costs:Nickel and cobalt price volatility affects rotor manufacturing economics for precision-engineered components.
- Regional supply concentration:Critical machining capacity clusters in southern Germany and northern Italy create geographic vulnerability.
- Centrifugal compressor substitution:Large-scale chemical plants above 500 kW demand increasingly favor dynamic compression for energy efficiency.
Strategic Opportunities
- India pharmaceutical corridor:Hyderabad and Ahmedabad manufacturing zones show underpenetrated demand for tri-lobe cleanroom-rated units.
- Biogas upgrading applications:Anaerobic digestion facilities require corrosion-resistant multi-lobe designs for raw biogas compression.
- Service network digitization:Remote condition monitoring platforms enable predictive maintenance contracts with municipal framework agreement holders.
Industry Challenges
- Precision machining talent scarcity:Five-axis CNC programming expertise for complex rotor profiles remains concentrated among aging specialist workforces in Central Europe.
- ISO 8573 certification timelines:Oil-free validation protocols extend product approval cycles by 8-14 months for cross-border equipment sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Lobe Compressor Market |
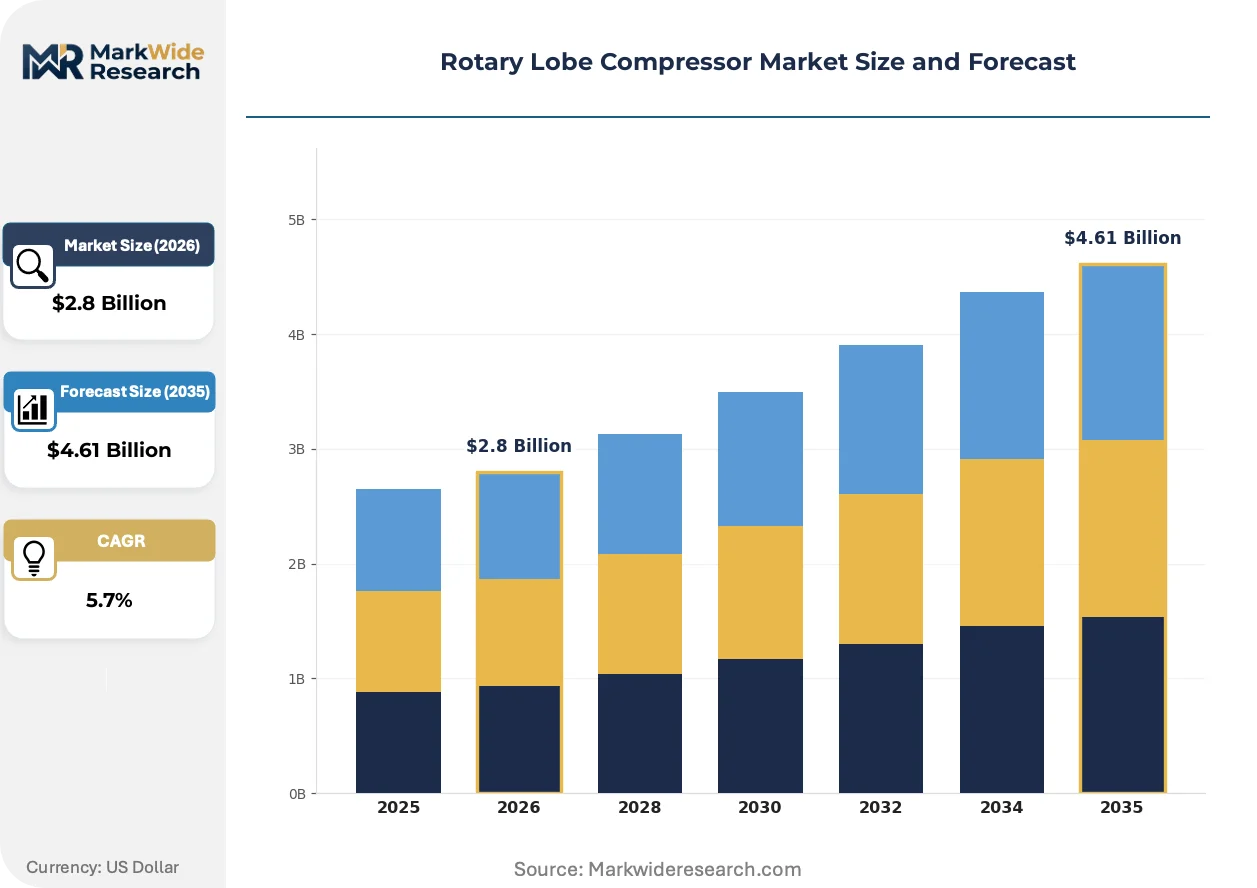
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Lobe, Twin Lobe, Tri-Lobe, Multi-Lobe Application: Food & Beverage, Water Treatment, Chemical Processing, Pharmaceutical End User: Manufacturing, Oil & Gas, Utilities, Automotive Technology: Positive Displacement, Vacuum, Low Pressure, High Pressure |
| Companies Covered | Aerzener Maschinenfabrik GmbH, Atlas Copco AB, Kaeser Kompressoren SE, Busch Vacuum International GmbH, Ingersoll Rand Inc., Gardner Denver Holding, Inc., Bauer Kompressoren Gruppe, Howden Group Ltd., Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Lobe Compressor Market Evolving Landscape
Digitalization of compressor performance monitoring and predictive maintenance capabilities is restructuring competitive differentiation. Equipment suppliers now compete on data-driven uptime guarantees rather than hardware specifications alone.
Permanent magnet synchronous motor integration with variable frequency drives is consolidating efficiency advantages across pharmaceutical and food packaging installations. Cleanroom operators in Switzerland and Singapore specify these configurations for precise airflow control. The technology is consolidating market share in applications where energy recovery justifies premium first cost.
REACH substance restrictions and EU F-Gas Regulation amendments are tightening material compliance requirements for sealing systems and coatings. Chemical processors must validate elastomer compatibility against evolving authorized substance lists. Germany's KBA and France's ANSM enforce sector-specific protocols that filter market access for non-conforming compressor suppliers.
Framework agreement consolidation among European water utilities is compressing supplier negotiation leverage. Municipal procurement teams now bundle multi-facility contracts with standardized service level requirements. Dutch and Danish water authorities lead this aggregation, demanding fleet-wide interoperability and unified spare parts logistics.
Rotary Lobe Compressor Market Segmentation
Rotary lobe compressor procurement patterns diverge sharply between standalone aeration installations and embedded process systems. Understanding these integration depths enables suppliers to align rotor configurations with buyer technical requirements and service expectations.
Product Type:
Standalone blowers for municipal water treatment operate independently with dedicated controls, while embedded units integrate into complex manufacturing lines requiring synchronized pressure management.
- Single Lobe:Simplest rotor geometry with minimal machining complexity suits low-duty pneumatic conveying in grain handling facilities. Demand clusters in Midwest US agricultural processing where capital constraints outweigh efficiency premiums.
- Twin Lobe:Two-lobe intermeshing design delivers proven reliability across Germany's wastewater treatment infrastructure. Berlin and Hamburg municipal operators specify this configuration for aeration basins where parts availability and technician familiarity reduce lifecycle risk.
- Tri-Lobe:Reduced pulsation characteristics protect pharmaceutical cleanroom integrity in Basel and Singapore manufacturing zones. FDA and Swissmedic air purity requirements favor this geometry for sterile product contact applications.
- Multi-Lobe:Complex profiles minimize gas contamination for chemical vapor recovery systems. Corrosion-resistant coatings serve biogas upgrading facilities in Denmark and the Netherlands.
Twin lobe designs lead volumes today; tri-lobe configurations are gaining share fastest.
Application:
Cost tier stratification separates premium process-critical installations from standard utility-grade deployments.
- Food & Beverage:Oil-free compression preserves product integrity across dairy processing lines in Wisconsin and cheese production in Normandy. USDA and EU hygiene regulations mandate stainless steel construction with FDA-compliant seals.
- Water Treatment:Aeration systems dominate municipal procurement in China's Yangtze River Delta and Germany's Ruhr basin. EPA effluent guidelines and EU Urban Waste Water Treatment Directive accelerate equipment replacement cycles.
- Chemical Processing:Leak-tight designs handle aggressive process gases along the US Gulf Coast. REACH substance restrictions govern elastomer selection for sealing systems.
- Pharmaceutical:ISO 8573 Class 0 air quality underpins sterile manufacturing in Hyderabad and Ahmedabad corridors. CDSCO and US FDA validation protocols extend commissioning timelines.
Water treatment leads volumes today; pharmaceutical applications are climbing the fastest.
End User:
Customer type determines service intensity and contract structure, from framework agreements with municipal utilities to spot maintenance with industrial operators.
- Manufacturing:Discrete production lines in automotive stamping and electronics assembly specify compact units for vacuum hold-down and parts conveying.
- Oil & Gas:Upstream facilities deploy corrosion-resistant models for vapor recovery and gas boosting in Permian Basin operations.
- Utilities:Consolidated procurement across Dutch and Danish water authorities demands fleet interoperability and unified spare parts logistics.
- Automotive:Paint shop applications require oil-free delivery to prevent surface contamination in Stuttgart and Detroit assembly plants.
Utilities lead volumes today; manufacturing end users are expanding most quickly.
Technology:
Pressure range and displacement mechanism define competitive positioning across efficiency-sensitive and reliability-critical buyer segments.
- Positive Displacement:Fixed volume per revolution ensures predictable flow regardless of discharge pressure. German chemical processors favor this certainty for batch reactor aeration.
- Vacuum:Dedicated suction configurations serve semiconductor wafer handling and food packaging lines in Singapore and Switzerland.
- Low Pressure:Below 1 bar discharge dominates municipal aeration where energy efficiency trumps compression ratio.
- High Pressure:Multi-stage designs reach 15 bar for pneumatic conveying of dense materials in cement and minerals processing.
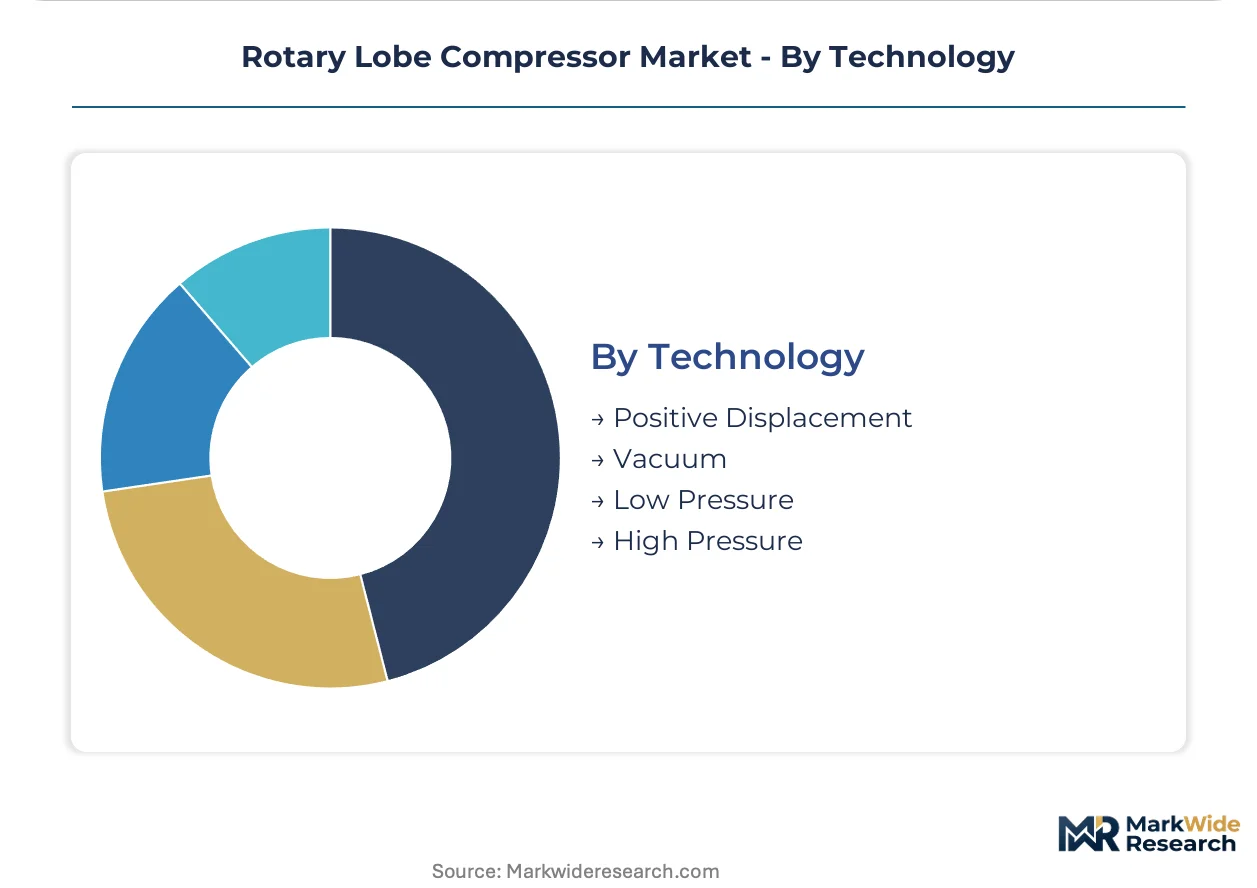
Positive displacement leads volumes today; vacuum technology is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's municipal water infrastructure sustains deeper rotary lobe compressor penetration than China's industrial expansion, though both markets now face converging regulatory pressure on oil-free architectures.
United States
EPA effluent guidelines mandate equipment upgrades across 16,000 wastewater facilities. The agency's 2023 industrial discharge rules accelerate replacement of lubricated systems along the Gulf Coast chemical corridor. Houston and Corpus Christi processors specify leak-tight designs for aggressive process gas handling.
Germany
Municipal procurement consolidation into multi-facility framework agreements compresses supplier margins. The country's KBA enforces sector-specific compliance protocols for machinery certification. Berlin and Hamburg operators rely on twin lobe configurations for aeration basin reliability.
China
Yangtze River Delta wastewater plants expand rotary lobe deployment for aeration capacity. The Ministry of Ecology and Environment tightens discharge standards under 14th Five-Year Plan water quality targets. Shanghai and Suzhou industrial zones drive demand for corrosion-resistant multi-lobe biogas upgrading units.
India
Pharmaceutical manufacturing corridors in Hyderabad and Ahmedabad show underpenetrated demand for tri-lobe cleanroom-rated compressors. CDSCO validation protocols extend commissioning timelines for sterile product contact applications. Gujarat's specialty chemical clusters adopt oil-free architectures for API manufacturing lines.
Switzerland
Precision manufacturing and pharmaceutical cleanroom operations sustain premium positioning for reduced-pulsation tri-lobe designs. Swissmedic enforces air purity requirements matching FDA standards for sterile production. Basel's Novartis and Roche supplier ecosystems specify permanent magnet synchronous motor configurations.
Rotary Lobe Compressor Market Competitive Landscape
German producers anchor the premium engineering tier; Italian and Chinese fabricators hold mid-market positions through cost-optimized machining capacity. The vendor base splits between consolidated positive displacement specialists and diversified industrial conglomerates. Three archetypes dominate: heritage engineering houses with municipal relationships, integrated compressor-vacuum portfolio players, and regional machining specialists serving price-sensitive agricultural markets. Competitive moves concentrate on predictive maintenance platform deployment and multi-lobe corrosion-resistant design licensing.
Within the heritage engineering tier, Aerzener Maschinenfabrik GmbH and Kaeser Kompressoren SE exemplify German GmbH-structured specialists with deep municipal utility relationships. Atlas Copco AB represents the diversified portfolio archetype, extending compressor technology into integrated vacuum and pressure solutions. These three occupy positions defined by service network density and rotor manufacturing precision rather than scale advantages alone.
| Leading Market Players |
|---|
| Aerzener Maschinenfabrik GmbH |
| Atlas Copco AB |
| Kaeser Kompressoren SE |
| Busch Vacuum International GmbH |
| Ingersoll Rand Inc. |
| Gardner Denver Holding, Inc. |
| Bauer Kompressoren Gruppe |
| Howden Group Ltd. |
| Mitsubishi Heavy Industries |
| Others |
Value Network & Pricing Analysis
Municipal framework agreement consolidation across Dutch and Danish water utilities forces suppliers to absorb extended warranty costs and unified spare parts logistics, compressing margins and accelerating cost recovery through premium tri-lobe configurations for pharmaceutical cleanroom operators in Switzerland and Singapore.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard twin-lobe aeration units. Three-tier pricing structure across premium oil-free architectures, standard lubricated designs, and economy agricultural blowers separates ISO 8573 Class 0 certified systems from utility-grade equipment. Cost compression in the standard tier intensifies because German and Italian machining capacity faces utilization pressure from Chinese fabricators. Agricultural processors in the US Midwest exhibit highest price sensitivity, while pharmaceutical manufacturers in Basel accept premium positioning for reduced-pulsation tri-lobe geometries.
Supply Chain Analysis
Refurbishment flows for precision-engineered rotors create secondary supply channels extending equipment lifecycle and dampening new unit demand. Critical machining capacity clusters in southern Germany, northern Italy, and eastern China, with five-axis CNC programming expertise concentrated among aging specialist workforces. Nickel and cobalt price volatility affects rotor manufacturing economics. Single-source vulnerability sits with specialized alloy suppliers serving corrosion-resistant coating requirements. Distribution runs through OEM-direct municipal procurement teams and industrial distributor networks stocking spare rotor assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rotary lobe compressor procurement offers geographic-arbitrage potential: India's pharmaceutical corridor presents lower certification overhead than EU markets, while Germany's municipal relationships command premium service pricing.
For Market Incumbents: Anticipate centrifugal compressor substitution above 500 kW in chemical processing by anchoring competitiveness through permanent magnet synchronous motor integration and predictive maintenance platform deployment. Defend municipal framework agreement positions through backward integration into precision rotor machining capacity in southern Germany. For New Entrants and Emerging Players: Direct-to-utility digital procurement portals offer lower customer acquisition cost than field sales networks for penetrating India's underpenetrated Hyderabad and Ahmedabad pharmaceutical corridors. Target biogas upgrading applications in Denmark and the Netherlands where corrosion-resistant multi-lobe designs face limited incumbent specialization. Lead with remote condition monitoring capabilities to differentiate from heritage engineering houses. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier Italian fabricators possessing five-axis CNC capacity but lacking service network density for framework agreement eligibility. Long-term viability rests on regulatory tailwinds for oil-free architectures across EPA and EU F-Gas jurisdictions. Monitor REACH substance restriction amendments for elastomer compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Remote monitoring capabilities secure multi-year municipal framework agreements with Dutch water authorities. |
| Multi-Lobe Corrosion-Resistant Design Licensing | Biogas upgrading specialization opens anaerobic digestion facilities in Denmark and the Netherlands. |
| Permanent Magnet Synchronous Motor Integration | Energy recovery justifies premium positioning among Swiss pharmaceutical cleanroom operators. |
| Backward Integration into Precision Machining | In-house rotor production defends margins against nickel and cobalt input volatility. |
| ISO 8573 Class 0 Certification Investment | Oil-free validation enables sterile product contact applications under FDA and Swissmedic protocols. |
Research Methodology
Coverage spans Germany, China, India, the United States, and Switzerland, with primary inputs from each market through structured interviews with municipal water utility procurement directors, pharmaceutical plant engineers, chemical processing maintenance managers, and aftermarket service heads at compressor OEMs. Secondary validation draws from EPA effluent guideline filings, EU F-Gas Regulation implementation reports, SEC 10-K disclosures from listed industrial conglomerates, and customs trade data for precision-engineered compressor components. Bottom-up facility-level demand estimates triangulate against top-down industry association capacity data.
Granularity-level modeling spans product type, application, end user, and technology dimensions, with additional segmentation by regional regulatory cluster and certification tier. Value projections across the analysis window derive from unit economics modeling of oil-free versus lubricated architectures, energy efficiency premiums for permanent magnet configurations, and service contract attach rates. Forecast inputs incorporate municipal capital expenditure cycles, pharmaceutical manufacturing capacity expansion in Hyderabad and Ahmedabad, and biogas facility deployment timelines in northern Europe.
The model assumes a particular technology adoption path for oil-free rotary lobe architectures; alternative pathways for centrifugal compressor substitution above 500 kW would alter the outlook for positive displacement market share. Forecasts reflect assumptions on regulatory enforcement timing for EPA effluent guidelines and EU F-Gas phase-down schedules. Practitioners should monitor REACH substance restriction amendments and carbon border adjustment mechanism developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Asia-Pacific Booster Compressor Market
Compressors
CNG Compressor Market
Compressors
Compressed Air Lubricators Market
Compressors
Axial Compressor Market
Compressors
Centrifugal Compressors Market
Compressors
Compressor Rental Market
Compressors
LNG Compressor Market
Compressors
Middle East and Africa Booster Compressor Market
Compressors
Compressor Wheel Market
Compressors
Turbocompressor Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Oil Free Compressor Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Scroll Compressor Market
Compressors
Regenerative Blowers Market