
 Vapor Recovery Units Market | 2026-2036
Vapor Recovery Units Market Size, Share, and Industry Trends Forecast 2026-2036
Vapor Recovery Units Market Intelligence
Remote monitoring and predictive maintenance subscription layers is consolidating vendor-customer relationships beyond hardware transactions. John Zink Hamworthy Combustion leverages its combustion technology heritage to anchor aftermarket service contracts across North American refinery clients. Zeeco competes through specialized flare and vapor recovery integration capabilities that extend project scope. AEREON differentiates via membrane and carbon adsorption system expertise that occupies midstream processing niches.
Vapor recovery units are engineered emissions control systems that capture volatile organic compounds from storage, loading, and process vent streams through condensation, adsorption, or membrane separation, typically achieving recovery efficiencies exceeding 95 percent depending on vapor composition and flow conditions. Their primary purpose is regulatory compliance combined with product recovery in hydrocarbon handling operations. Refrigerated condensers dominate current installed capacity due to proven reliability in high-volume natural gas processing applications. Membrane systems represent the fastest-expanding technology segment as operators prioritize modular, skid-mounted configurations that reduce footprint and installation downtime. Activated carbon units sustain steady demand from chemical producers managing intermittent, low-concentration vapor streams where capital simplicity outweighs energy efficiency trade-offs.
EPA New Source Performance Standards and NESHAP Maximum Achievable Control Technology requirements mandate vapor recovery at gasoline distribution terminals and petroleum refineries, directly shaping equipment procurement specifications and upgrade cycles. OSHA process safety management rules compound compliance obligations by requiring documented control systems for flammable vapor releases. State-level air quality regulations in California and Texas impose additional stringency that filters vendor qualification and technology selection. Stakeholders must evaluate whether captive maintenance capabilities or third-party service partnerships better align with evolving predictive analytics integration and tightening emissions enforcement trajectories.
Market Dynamics
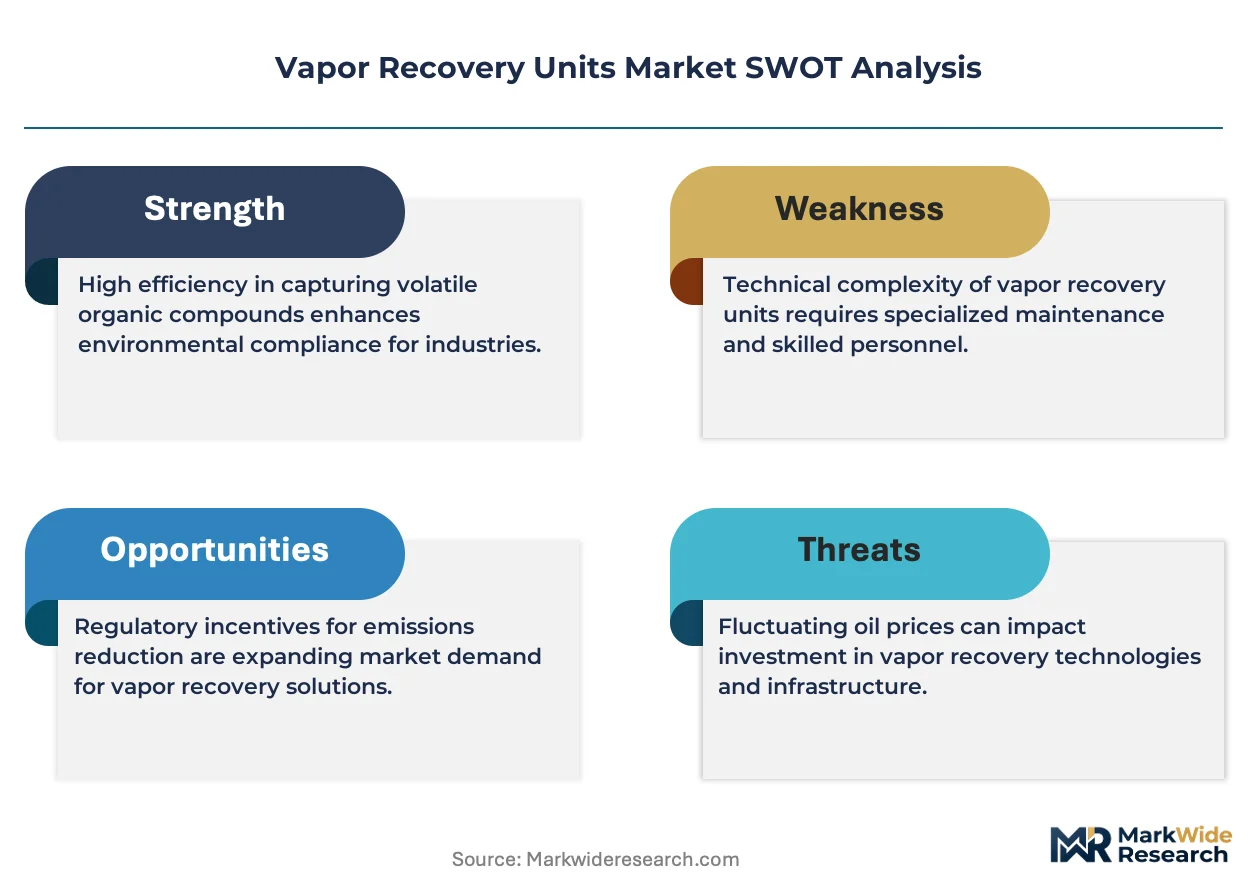
The Vapor Recovery Units Market is experiencing structural pressure from regulatory tightening on volatile organic compound emissions, compounded by the shift toward predictive maintenance service models that extend vendor relationships beyond initial equipment sales.
Growth Catalysts
- EPA NSPS Subpart XXa:Mandates vapor recovery at gasoline distribution terminals, forcing terminal operators in Texas and Louisiana to upgrade or install new systems.
- Membrane separation technology:Modular skid-mounted configurations reduce installation downtime and footprint, accelerating replacement cycles at midstream processing facilities.
- Refinery cluster density:Concentrated storage terminal development along the Gulf Coast creates procurement scale economies and standardized specification demand.
Market Restraints
- Stainless steel and specialty alloy costs:Corrosion-resistant materials for sour gas applications face price volatility tied to nickel supply fluctuations.
- Refrigeration compressor supply concentration:Dependence on a limited supplier base for high-capacity condenser units extends lead times during peak demand periods.
- Activated carbon disposal constraints:Spent carbon regeneration infrastructure gaps in certain states impose hazardous waste handling costs on chemical producers.
Strategic Opportunities
- Biogas upgrading facilities:Siloxane and VOC removal requirements at anaerobic digestion plants create application expansion beyond hydrocarbon sectors.
- Carbon capture integration:Vapor recovery units positioned upstream of amine-based CO2 capture systems offer combined emissions control value propositions.
- Remote monitoring subscription layers:Predictive analytics services generate recurring revenue streams and deepen customer lock-in across refinery maintenance contracts.
Industry Challenges
- Combustion safety engineering talent:Specialized expertise in flare and vapor recovery integration remains scarce relative to project pipeline demands.
- Legacy control system interoperability:DCS and SCADA integration with new membrane or adsorption units requires custom engineering that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vapor Recovery Units Market |
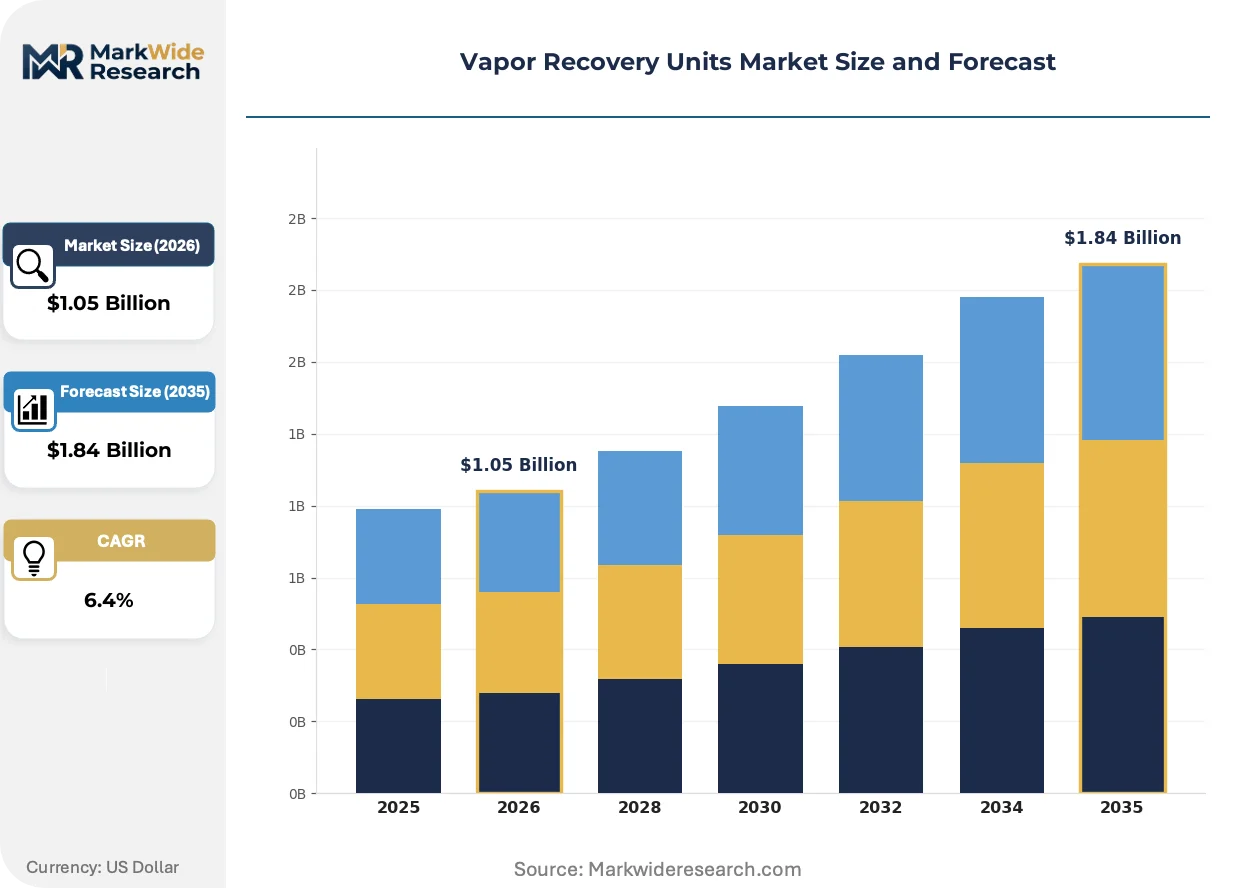
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon Units, Refrigerated Condensers, Membrane Systems, Absorption Systems, Cryogenic Units Technology: Pressure Swing Adsorption, Carbon Adsorption, Refrigeration Condensation, Membrane Separation, Cryogenic Recovery Application: Petrochemical Plants, Chemical Manufacturing, Natural Gas Processing, Fuel Storage Terminals, Paints & Coatings Production End User: Oil & Gas Refiners, Bulk Liquid Handlers, Storage Facility Operators, Chemical Producers, Terminal Operators |
| Companies Covered | John Zink Hamworthy Combustion, Zeeco, Dover Corporation, Cimarron Energy Inc., PETROGAS Systems, BORSIG Membrane Technology, AEREON, Cool Sorption A/S, Flogistix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vapor Recovery Units Market Strategic Shifts & Innovations
Technology substitution and regulatory precision are compressing equipment replacement cycles while reshaping how operators evaluate total cost of ownership across vapor recovery system portfolios.
Membrane-based vapor recovery is overtaking refrigerated condensation in midstream gas processing applications where modular deployment and reduced energy consumption outweigh capital cost premiums. Pipeline operators in the Permian Basin are specifying membrane skids for new gathering system installations. This technology shift is compressing the competitive position of traditional condenser vendors in high-volume, low-concentration vapor streams.
EPA NESHAP Maximum Achievable Control Technology updates are tightening benzene emission limits at petroleum refineries, compelling facility-wide vapor collection system audits. Refiners in California and Texas are consolidating multiple point-source controls into centralized recovery units to achieve compliance economies. The regulatory pressure is accelerating multi-year capital planning cycles and favoring vendors with integrated engineering capabilities.
After-sales service unbundling is fragmenting traditional equipment procurement patterns as operators separate hardware purchase from predictive maintenance subscriptions. Midstream companies in the Gulf Coast region are negotiating multi-year monitoring contracts independent of initial system vendors. This behavioral shift is forcing equipment manufacturers to develop standalone digital service offerings or risk margin compression in pure hardware transactions.
Vapor Recovery Units Market Segmentation
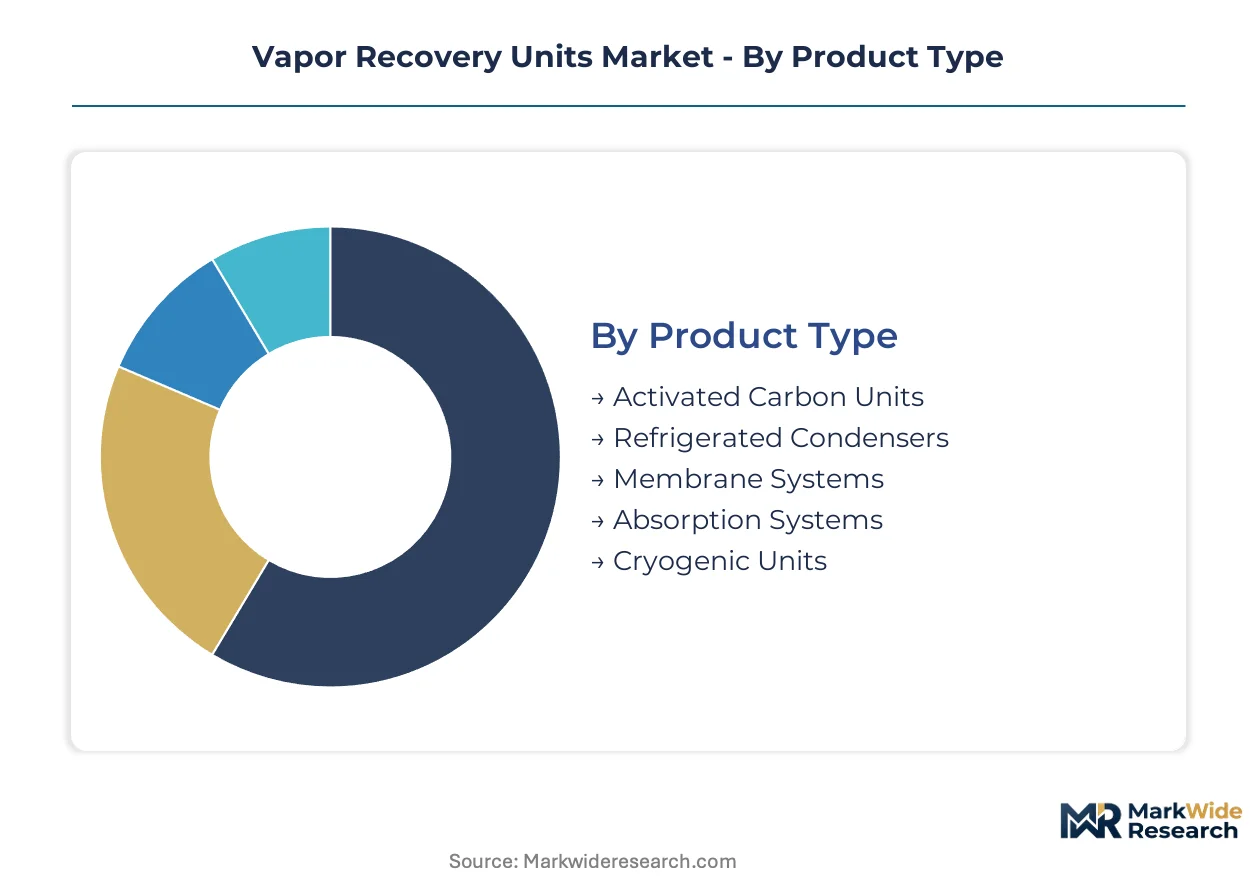
Vapor recovery unit procurement varies sharply across operational contexts. Buyers prioritize recovery efficiency, footprint constraints, and regulatory stringency differently depending on their vapor stream composition and facility scale.
Product Type:
Capital intensity and energy consumption split buyers into distinct procurement tiers with divergent total cost of ownership calculations.
- Refrigerated Condensers:These systems use mechanical refrigeration to condense hydrocarbon vapors into liquid product, achieving recovery rates above 95 percent in high-flow natural gas processing. Demand concentrates in Texas and Louisiana storage terminals where EPA NSPS mandates drive standardized specifications for gasoline distribution.
- Membrane Systems:Polymeric membranes selectively permeate hydrocarbon molecules while rejecting nitrogen, enabling modular skid-mounted deployments with minimal energy input. Pipeline operators in the Permian Basin specify these for new gathering installations where reduced installation downtime offsets capital premiums.
- Activated Carbon Units:Packed-bed adsorption systems capture intermittent low-concentration vapor streams through physisorption, favored by chemical producers prioritizing capital simplicity over energy efficiency.
- Absorption Systems:Liquid solvent scrubbing recovers polar compounds from process vents, maintaining niche demand in petrochemical complexes handling oxygenated hydrocarbons.
- Cryogenic Units:Deep refrigeration to cryogenic temperatures condenses light hydrocarbons and inerts, deployed at specialized natural gas processing facilities handling rich gas streams.
Refrigerated condensers lead volumes today; membrane systems are gaining share fastest.
Technology:
Process physics and regeneration methods determine operational suitability for specific vapor compositions and flow profiles.
- Membrane Separation:Selective permeation through hollow-fiber or spiral-wound modules separates hydrocarbons from carrier gases without phase change, enabling continuous operation with minimal moving parts. Midstream processors in the Gulf Coast region specify these for lean gas applications where energy costs dominate economics.
- Refrigeration Condensation:Mechanical cooling condenses vapors at temperatures ranging from ambient to cryogenic, depending on hydrocarbon dew point requirements. Natural gas processing facilities in Louisiana rely on these for high-volume streams where proven reliability outweighs energy intensity.
- Carbon Adsorption:Activated carbon beds capture organic vapors through surface adsorption, regenerated via steam or hot gas desorption for chemical manufacturers managing variable loading schedules.
- Pressure Swing Adsorption:Cyclic pressure changes regenerate adsorbent beds without thermal input, finding application in hydrogen recovery and light hydrocarbon purification.
- Cryogenic Recovery:Turboexpander or Joule-Thomson cooling achieves sub-zero temperatures for ethane-plus recovery, deployed at gas processing plants handling rich feedstocks.
Refrigeration condensation dominates current installed base; membrane separation is climbing the fastest.
Application:
Regulatory exposure and product value recovery potential shape investment urgency across industrial settings.
- Natural Gas Processing:Field gathering and processing facilities recover methane and natural gas liquids from production streams, with vapor recovery positioned upstream of dehydration and treating units. Operators in the Permian Basin deploy membrane skids at compressor stations to minimize methane slip and capture valuable product.
- Fuel Storage Terminals:Bulk gasoline and diesel storage facilities capture displaced vapors during tank filling and product transfer, driven by EPA Stage I and Stage II vapor recovery mandates. Terminal operators in Texas face concentrated compliance deadlines under NSPS Subpart XXa.
- Petrochemical Plants:Ethylene crackers and derivative units recover olefin and aromatic vapors from process vents and storage, integrating recovery with flare gas recovery systems.
- Chemical Manufacturing:Batch and continuous chemical producers manage solvent vapor emissions from reactors, dryers, and storage, with activated carbon units preferred for intermittent operations.
- Paints & Coatings Production:Solvent-based coating manufacture generates high-concentration vapor streams requiring thermal oxidizers or recovery systems depending on solvent value.
Fuel storage terminals lead procurement volumes today; natural gas processing is expanding most quickly.
End User:
Maintenance capabilities and captive engineering resources differentiate procurement sophistication across buyer categories.
- Oil & Gas Refiners:Integrated refineries operate complex vapor collection networks spanning process units, storage, and loading, requiring centralized recovery systems with high availability. California and Texas refiners consolidate multiple point-source controls under EPA NESHAP benzene limits.
- Terminal Operators:Independent storage and distribution terminals face discrete compliance obligations for gasoline loading racks and tankage, often outsourcing maintenance to equipment vendors.
- Chemical Producers:Specialty and commodity chemical manufacturers balance capital constraints against solvent recovery value, favoring simpler adsorption systems for variable operations.
- Bulk Liquid Handlers:Third-party logistics providers managing multiple product lines require flexible recovery systems accommodating changing vapor compositions.
- Storage Facility Operators:Crude oil and refined product tank farm operators deploy vapor recovery at fixed roof tanks and floating roof seals, with demand tied to tankage expansion cycles.
Oil and gas refiners lead capital deployment today; terminal operators are seeing the steepest compliance-driven expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys more vapor recovery capacity than any other single country, while Germany anchors European procurement through its chemical processing density and REACH enforcement stringency.
United States
EPA NSPS Subpart XXa mandates drive terminal upgrades across Texas and Louisiana, where Gulf Coast storage clusters concentrate procurement. OSHA process safety management rules compound compliance obligations for flammable vapor controls. Houston and Baton Rouge refineries consolidate point-source recovery into centralized systems under tightening benzene limits.
Germany
Chemical manufacturers along the Rhine-Ruhr corridor prioritize activated carbon units for intermittent solvent vapor streams. ECHA REACH regulations restrict volatile organic compound emissions from coatings and adhesive production. BASF and Bayer facility clusters in Ludwigshafen and Leverkusen sustain specialized recovery system demand.
China
Natural gas processing expansion in Sichuan and Xinjiang creates membrane system opportunities at field gathering stations. MEE air quality standards tighten VOC capture requirements at petrochemical complexes. Yangtze River Delta refineries in Shanghai and Ningbo upgrade vapor collection networks under provincial enforcement campaigns.
Saudi Arabia
Gas processing facilities at Ghawar and Safaniya fields deploy cryogenic recovery for rich natural gas streams. The country's national petroleum regulator mandates flare gas recovery to minimize methane emissions. Jubail Industrial City petrochemical complexes integrate vapor recovery with sulfur recovery units.
Canada
Alberta oil sands upgraders and SAGD facilities capture diluent vapors from bitumen processing. Environment and Climate Change Canada regulations align with EPA stringency for cross-border terminal operations. Edmonton and Fort McMurray storage hubs drive modular system specifications for remote deployment.
Vapor Recovery Units Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated combustion technology providers commanding premium positions in refinery applications while regional fabricators compete on terminal and midstream projects. The vendor base organizes into three archetypes: full-service combustion houses with aftermarket service arms, membrane technology specialists with modular product platforms, and regional engineering contractors with local installation capabilities. Consolidation pressure favors players with predictive maintenance software integration, while technology licensing agreements accelerate geographic expansion without capital-intensive manufacturing footprints.
Among North American combustion technology providers, John Zink Hamworthy Combustion and Zeeco occupy positions anchoring the premium service tier through integrated flare and vapor recovery engineering capabilities. AEREON sits within the specialized membrane and adsorption segment, representing the technology-focused archetype that competes through process-specific expertise rather than full-scope project delivery.
| Leading Market Players |
|---|
| John Zink Hamworthy Combustion |
| Zeeco |
| Dover Corporation |
| Cimarron Energy Inc. |
| PETROGAS Systems |
| BORSIG Membrane Technology |
| AEREON |
| Cool Sorption A/S |
| Flogistix |
| Others |
Cost & Logistics Intelligence
Stainless steel and specialty alloy costs cascade through refrigerated condenser manufacturing, compressing margins at mid-tier fabricators while premium vendors in Texas and Louisiana absorb volatility through long-term refinery service contracts. Nickel price fluctuations propagate from mining concentrates through corrosion-resistant vessel production, stratifying procurement tiers between integrated combustion houses and regional engineering contractors.
Pricing Analysis
Capacity additions in the Gulf Coast are reshaping price floors for membrane skid systems as modular fabricators compete for Permian Basin pipeline contracts. Three-tier pricing structure across premium, standard, and economy levels separates predictive maintenance-bundled offerings from pure hardware transactions. Price differentiation hinges on EPA certification tier and after-sales monitoring integration. Cost compression in standard-tier refrigerated units is intensifying because compressor supply concentration extends delivery timelines. Terminal operators in Texas exhibit highest price sensitivity; integrated refiners in California demonstrate lowest, prioritizing uptime guarantees over capital expenditure.
Supply Chain Analysis
Freight costs from German membrane module suppliers to US midstream projects add 8-12 percent to landed equipment costs, favoring domestic skid assembly operations in Houston and Baton Rouge. Manufacturing concentrates in the United States, Germany, and China. Production draws from nickel-bearing stainless steels, polymeric hollow-fiber membranes, and refrigeration compressor packages. Single-source vulnerability for high-capacity compressor units creates procurement bottlenecks during refinery turnaround seasons. Distribution runs through authorized EPC contractors and direct refinery engineering channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in predictive maintenance subscription layers, where remote monitoring capabilities transform one-time equipment sales into recurring revenue streams with superior retention economics.
For Market Incumbents: Extend aftermarket service penetration through predictive analytics integration that locks in multi-year refinery maintenance contracts. Consolidate membrane technology capabilities through targeted capability acquisitions to defend against modular specialists. Anchor positions in Texas and Louisiana refinery clusters through EPA compliance engineering expertise that emerging competitors cannot replicate quickly.
For New Entrants and Emerging Players: Biogas upgrading facilities represent an underserved buyer archetype with siloxane removal requirements that established hydrocarbon-focused vendors have neglected. Target anaerobic digestion plant operators in agricultural regions with standardized skid-mounted membrane systems. Pursue carbon capture integration partnerships with amine-based CO2 capture developers to position vapor recovery upstream of emerging decarbonization infrastructure.
For Investors and Strategic Acquirers: Consolidation pressure builds where predictive maintenance software capabilities determine contract renewal rates and customer lifetime value. The five-to-ten-year viability window favors vendors with integrated digital service platforms over pure hardware manufacturers. Acquisition targets should demonstrate membrane technology expertise or captive biogas application experience. Watch for EPA NESHAP benzene limit enforcement intensity as the inflection signal for refinery capital cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Remote monitoring subscriptions transform hardware vendors into recurring revenue businesses with superior customer retention. |
| Membrane Technology Licensing Agreement | Modular specialists accelerate geographic expansion without capital-intensive manufacturing footprints in new regions. |
| Biogas Application Vertical Expansion | Anaerobic digestion plant operators create demand beyond traditional hydrocarbon processing sectors. |
| Carbon Capture Integration Partnership | Upstream vapor recovery positioning captures value from amine-based CO2 capture system deployments. |
| Refinery Cluster Service Consolidation | Centralized recovery systems under EPA NESHAP compliance drive multi-year engineering contracts. |
Research Approach
Direct dialogue with refinery maintenance directors, terminal operations managers, EPC project engineers, and aftermarket service heads grounded qualitative insights in operational realities. Secondary validation drew from EPA enforcement databases, OSHA process safety incident reports, FERC facility filings, and midstream capital expenditure disclosures. Bottom-up equipment procurement tracking and top-down regulatory mandate sizing were triangulated to anchor volume estimates.
Bottom-up modeling aggregated individual project specifications across natural gas processing, fuel storage terminal, and petrochemical application segments. Top-down analysis scaled regulatory mandate coverage against facility counts and upgrade cycles. Segmentation dimensions included product type, technology, application, and end-user maintenance sophistication. CAGRs were derived from regulatory deadline clustering and replacement cycle compression observed across the analysis window. Forecast inputs incorporated membrane adoption curves and predictive maintenance penetration assumptions.
Underlying measurement precision varies by segment; fuel storage terminal procurement carries tighter precision than emerging biogas applications due to established EPA reporting requirements. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
Power Transmission Tower Market
Transmission and Distribution
High Voltage Direct Current (HVDC) Transmission System Market
Transmission and Distribution
South America City Gas Distribution Market
Transmission and Distribution
Electrical Substation Management Market
Transmission and Distribution
Transmission and Distribution Fault Detection Market
Transmission and Distribution
Pipeline Monitoring System Market
Transmission and Distribution
Wireless Power Transmission Market
Transmission and Distribution
Global Virtual Pipeline Systems Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
Fixed Series Compensation Market
Transmission and Distribution
Electrical Transmission Azimuth Thruster Market