
 Asia-Pacific Compressor Oil Market | 2026-2036
Asia-Pacific Compressor Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Compressor Oil Market Insights
Aftermarket service revenue is reconfiguring margin capture across the Asia-Pacific compressor oil value chain. Shell leverages its synthetic lubricant technology leadership to command premium positioning in high-temperature industrial applications. Sinopec anchors supply security through captive base oil production and extensive domestic distribution infrastructure. FUCHS specializes in tailor-made compressor formulations for food-grade and pharmaceutical manufacturing environments.
Compressor oil comprises refined petroleum or synthetic base stocks fortified with antioxidant, anti-wear, and demulsifier additives, formulated to ISO viscosity grades typically between VG 32 and VG 100 to manage heat rejection and seal protection in positive-displacement and dynamic compression equipment. Synthetic oil variants command expanding share as manufacturers prioritize extended drain intervals and energy-efficiency gains in rotary screw and centrifugal systems. Industrial compressors represent the dominant application segment, while refrigeration-grade formulations face rising technical barriers from fluorinated gas phase-down regulations. Bio-based alternatives occupy a niche position constrained by oxidation stability limitations and higher unit costs.
Japan's METI enforces stringent energy conservation standards for factory equipment that elevate lubricant thermal performance benchmarks. China's MEE implements dual carbon goals that pressure industrial operators to reduce compressor energy consumption through advanced lubricant selection. India's BIS maintains lubricant quality certification protocols that filter substandard imports from regional supply channels. Stakeholders must monitor regulatory divergence across these frameworks when configuring product portfolios and localization investments.
Market Dynamics
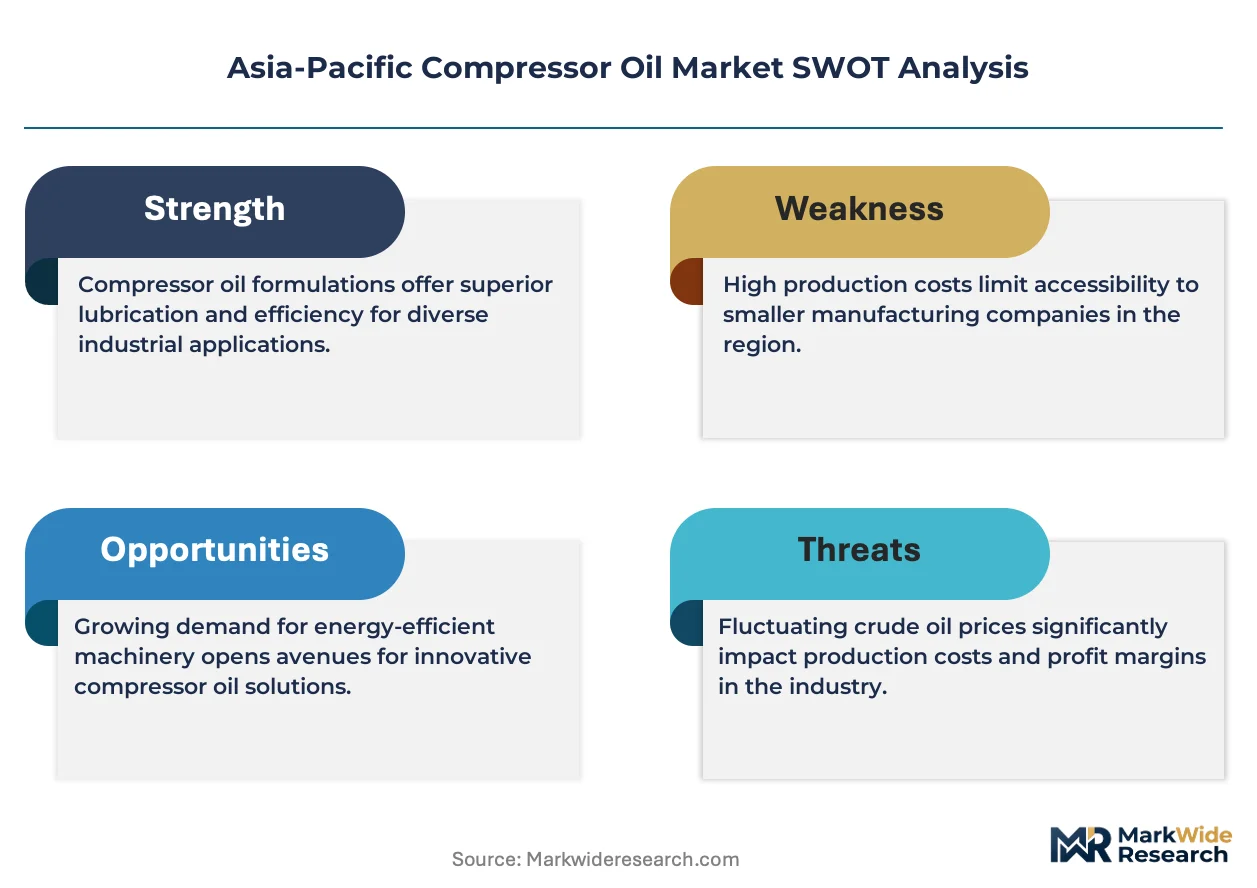
Japan's METI energy-efficiency mandates are compressing lubricant thermal performance thresholds across industrial compressor fleets, forcing reformulation cycles and supplier qualification renewals throughout the Asia-Pacific supply base.
Growth Catalysts
- India's western manufacturing corridor:Industrial clusters from Gujarat to Maharashtra are expanding compressed air infrastructure for automotive and textile processing, pulling ISO VG 68 and VG 100 formulations into high-volume consumption.
- China's dual carbon goals:MEE enforcement of industrial energy intensity targets pressures plant operators toward synthetic lubricants with extended drain intervals and lower friction coefficients.
- Refrigeration compressor retrofits:Fluorinated gas phase-down regulations under the Kigali Amendment are accelerating lubricant changeouts in cold chain logistics facilities across Australia and Southeast Asia.
Market Restraints
- Group III base oil supply concentration:Asia-Pacific refining capacity for high-viscosity index stocks clusters in South Korea and Singapore, exposing formulators to feedstock allocation risk during turnarounds.
- Bio-based oxidation stability ceiling:Vegetable-derived esters face thermal degradation thresholds below 120°C that disqualify them from high-pressure rotary screw applications.
- BIS certification timelines:India's mandatory lubricant quality testing protocols extend product registration cycles by four to six months, filtering opportunistic imports from unqualified regional traders.
Strategic Opportunities
- Indonesia's emerging food processing belt:Halal-certified compressor lubricant demand is outpacing domestic formulation capability, creating entry points for ASEAN-registered suppliers with NSF H1 registrations.
- Pharmaceutical cleanroom specifications:GMP Annex 1 revisions in Japan and South Korea are mandating oil-free compressor verification protocols that favor advanced synthetic formulations with particle count guarantees.
- Digital oil monitoring integration:IoT sensor deployment in Thai and Vietnamese manufacturing parks enables predictive drain interval optimization, converting lubricant supply into performance-contracting relationships.
Industry Challenges
- Cross-grade inventory complexity:Distributor networks must stock eight to twelve ISO viscosity variants across mineral, PAO, and polyol ester chemistries to cover fragmented industrial end-use specifications.
- Used oil collection infrastructure gaps:Reverse logistics for spent compressor lubricants remains underdeveloped outside Japan and Australia, complicating environmental compliance for multi-site operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Compressor Oil Market |
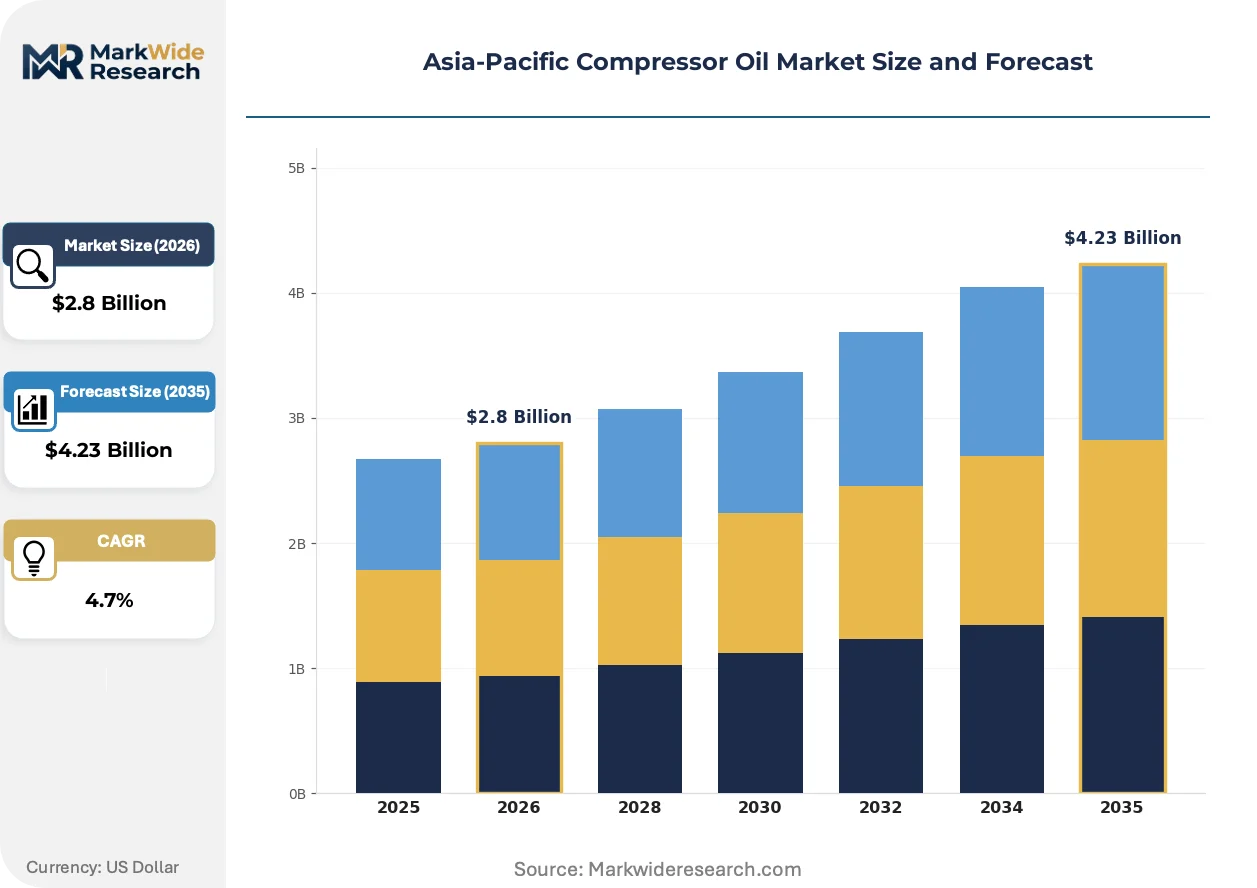
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Mineral Oil, Synthetic Oil, Bio-based Oil, Semi-Synthetic Oil Application: Industrial Compressors, Automotive Compressors, Refrigeration, Air Conditioning Viscosity Grade: ISO VG 32, ISO VG 46, ISO VG 68, ISO VG 100 End User: Manufacturing, Automotive, Energy, HVAC |
| Companies Covered | Indian Oil Corporation Limited, Shell, Chevron Corporation, Total, ExxonMobil Corporation, FUCHS, China Petrochemical Corporation (Sinopec), Klüber Lubrication, HP Lubricants, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Compressor Oil Market Trends and Innovations
Synthetic lubricant chemistry advances and digital monitoring integration are compressing traditional maintenance cycles while elevating thermal performance benchmarks across Asia-Pacific industrial operations.
Polyalkylene glycol (PAG) formulations with inherent deposit control and water solubility are penetrating food-grade and pharmaceutical compressor applications in Japan and Australia. Major dairy processors and API manufacturers are specifying these chemistries for rotary screw systems operating above 90°C discharge temperatures. Mineral oil-based alternatives with lower thermal stability are rendering obsolete in these critical hygiene segments.
China's GB standards for industrial energy consumption are tightening permissible compressor specific power ratios, indirectly elevating lubricant viscosity selection and additive package requirements. Plant engineers in Jiangsu and Zhejiang provinces are recalibrating oil specifications to squeeze fractional efficiency gains from rotary equipment. Synthetic PAO and ester-based products are capturing specification upgrades that mineral oils cannot satisfy.
Service unbundling is fragmenting traditional distributor relationships as end-users separate lubricant supply from compressor OEM maintenance contracts. Independent fluid analysis laboratories in India and Southeast Asia are capturing condition-monitoring revenue that distributors previously monopolized. This pattern is most pronounced in Maharashtra's automotive component clusters, where procurement teams negotiate direct lubricant supply agreements while retaining separate technical service providers.
Asia-Pacific Compressor Oil Market Segmentation
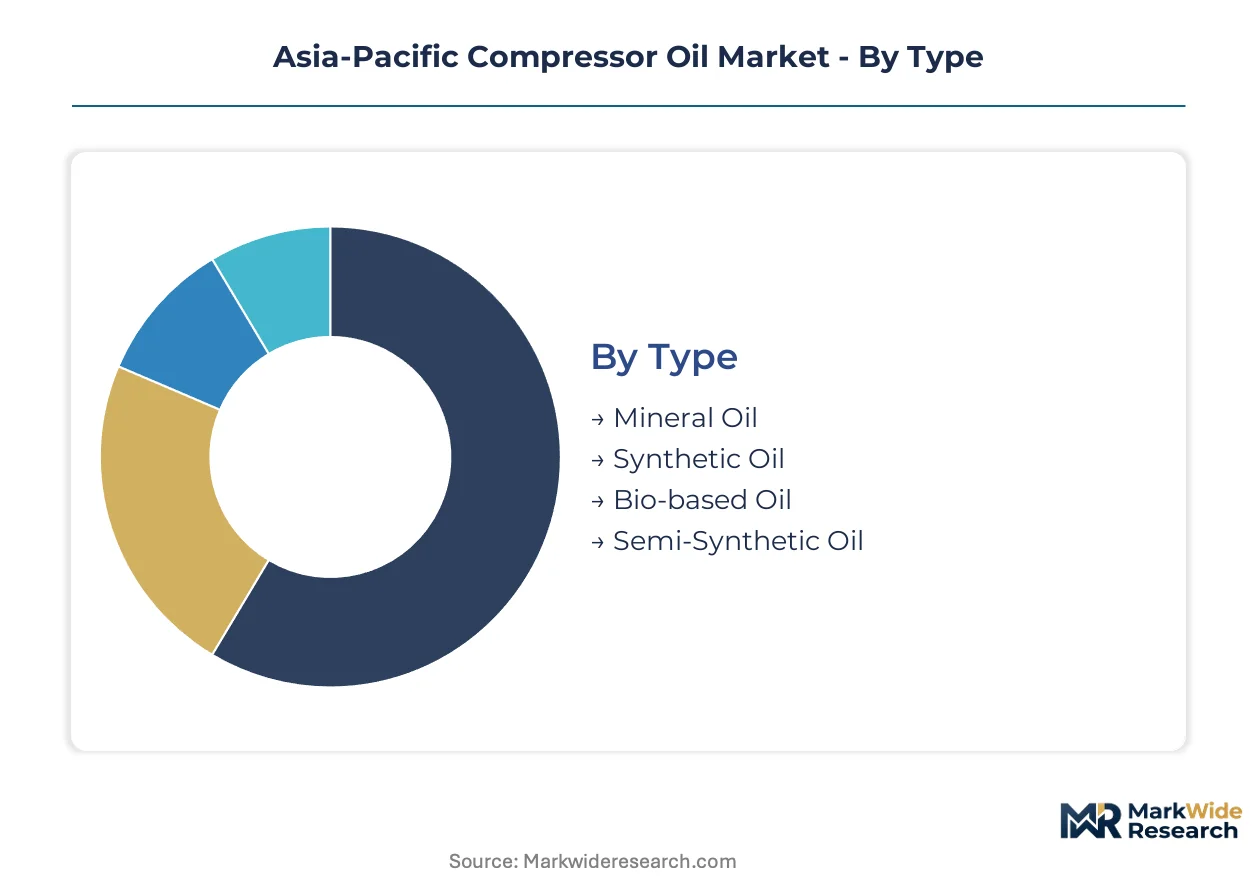
Compressor oil segmentation in Asia-Pacific reflects divergent technical requirements across industrial infrastructure maturity levels. Formulation chemistry, viscosity specification, and end-use certification standards create distinct procurement tiers that suppliers must navigate simultaneously.
Type:
Use-case spectrum spans from cost-sensitive mineral formulations to precision-engineered synthetics demanded by METI efficiency mandates.
- Synthetic Oil:Polyalphaolefin and polyol ester base stocks deliver thermal stability above 120°C for rotary screw compressors in Japan's automotive component plants. Jiangsu province manufacturers specify these formulations to meet MEE dual carbon energy intensity targets.
- Mineral Oil:Refined petroleum distillates with additive packages dominate high-volume consumption in India's western manufacturing corridor from Gujarat to Maharashtra, where cost-per-liter procurement governs selection for general industrial compressed air systems.
- Semi-Synthetic Oil:Blended formulations balance drain interval extension against unit cost premiums for mid-tier operators in Thailand and Vietnam.
- Bio-based Oil:Vegetable-derived esters occupy niche positions in food-grade applications across Indonesia's emerging halal processing belt, constrained by oxidation stability ceilings below high-pressure rotary thresholds.
Established volume favors mineral oil; emerging adoption favors synthetic oil.
Application:
Equipment category determines additive package intensity and thermal performance certification requirements.
- Industrial Compressors:Positive-displacement and dynamic compression systems in manufacturing plants require ISO VG 68 and VG 100 formulations with antioxidant and anti-wear chemistries. China's expanding fleet maintenance programs pull these specifications into high-volume consumption across Shandong and Guangdong provinces.
- Refrigeration:Cold chain logistics facilities under Kigali Amendment fluorinated gas phase-down regulations face lubricant changeout cycles for retrofit compressor systems. Australian and Southeast Asian operators specify polyalkylene glycol compatibility with new refrigerant chemistries.
- Automotive Compressors:Climate control and pneumatic systems in vehicle assembly plants demand specialized formulations with seal compatibility for variable displacement compressors.
- Air Conditioning:Commercial building HVAC infrastructure in South Korea and Japan specifies low-viscosity ISO VG 32 and VG 46 grades for scroll and reciprocating compressor architectures.
Industrial compressors anchor current procurement volumes; refrigeration retrofits are climbing the fastest through regulatory compliance deadlines.
Viscosity Grade:
ISO classification governs heat rejection capacity and film strength across operating temperature ranges.
- ISO VG 68:Mid-range viscosity dominates rotary screw compressor specifications in India's automotive component clusters, balancing flow characteristics against seal protection under continuous duty cycles.
- ISO VG 100:Higher viscosity formulations command specification in high-pressure reciprocating systems and aging compressor fleets where bearing clearances have widened through operational wear.
- ISO VG 46:Lower viscosity grades penetrate centrifugal compressor applications in Japanese pharmaceutical cleanrooms where energy efficiency metrics override film thickness margins.
- ISO VG 32:Lightest viscosity category serves high-speed dynamic compression equipment and seasonal air conditioning systems with moderate thermal loads.
ISO VG 68 maintains procurement dominance; ISO VG 46 gains share fastest through centrifugal system specification upgrades.
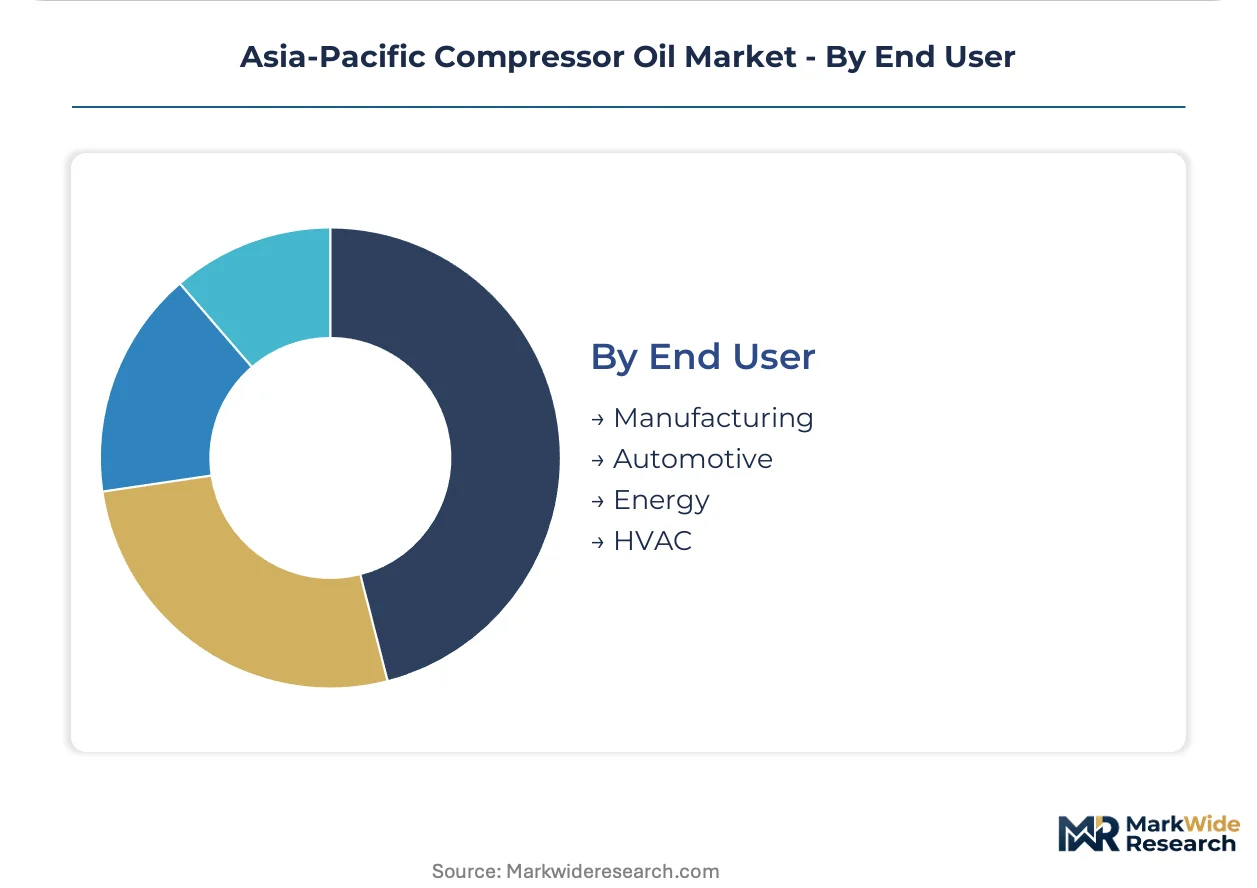
End User:
Customer type dictates certification requirements, volume contracting structures, and technical service intensity.
- Manufacturing:Discrete and process industries from Maharashtra to Zhejiang specify compressor oils through direct procurement agreements unbundled from OEM maintenance contracts, with independent fluid analysis laboratories capturing condition-monitoring revenue.
- HVAC:Commercial building operators and facility management contractors prioritize energy efficiency certifications aligned with METI mandates and China's GB standards for industrial energy consumption.
- Automotive:Vehicle assembly plants and tier suppliers demand just-in-time lubricant delivery synchronized with production schedules, with quality protocols filtering substandard imports through BIS certification requirements.
- Energy:Power generation and oil and gas operations specify fire-resistant formulations for high-risk environments, with procurement governed by enterprise-level supply agreements rather than spot market purchases.
Manufacturing commands absolute volume; HVAC shows steepest specification upgrade trajectory through regulatory efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's synthetic lubricant specifications diverge sharply from India's mineral-oil dominance, creating a consumption-mix split that suppliers must navigate simultaneously across the region.
China
Jiangsu and Zhejiang manufacturers specify PAO and ester-based formulations to satisfy MEE dual carbon energy intensity targets. GB standards for industrial energy consumption tighten permissible compressor specific power ratios, elevating lubricant viscosity selection requirements. Shandong and Guangdong provinces anchor expanding fleet maintenance programs that pull ISO VG 68 and VG 100 formulations into high-volume consumption.
India
Gujarat-to-Maharashtra industrial clusters drive ISO VG 68 and VG 100 demand for automotive and textile processing compressed air infrastructure. BIS certification protocols extend product registration cycles by four to six months, filtering substandard imports from regional supply channels. Maharashtra's automotive component clusters unbundle procurement from OEM maintenance contracts, with independent fluid analysis laboratories capturing condition-monitoring revenue.
Japan
Kanto and Kansai automotive component plants demand polyalphaolefin and polyol ester base stocks delivering thermal stability above 120°C. METI energy conservation standards for factory equipment elevate lubricant thermal performance benchmarks, forcing reformulation cycles throughout the supply base. Pharmaceutical cleanrooms in Osaka and Nagoya specify ISO VG 46 grades for centrifugal compressors where energy efficiency metrics override film thickness margins.
South Korea
Seoul Capital Area commercial building operators prioritize low-viscosity ISO VG 32 and VG 46 grades for scroll and reciprocating HVAC compressor architectures. GMP Annex 1 revisions mandate oil-free compressor verification protocols favoring advanced synthetic formulations with particle count guarantees. Busan-Ulsan manufacturing zones specify just-in-time lubricant delivery synchronized with automotive production schedules.
Indonesia
Halal-certified compressor lubricant demand from emerging food processing belts outpaces domestic formulation capability. NSF H1 registrations create entry points for ASEAN-registered suppliers with pharmaceutical-grade manufacturing credentials. Java-based dairy processors and API manufacturers specify PAG formulations for rotary screw systems operating above 90°C discharge temperatures.
Asia-Pacific Compressor Oil Market Competitive Landscape
Capability concentration sits with synthetic formulation specialists; scale advantage sits with integrated petrochemical majors. The Asia-Pacific compressor oil market structures around three tiers: multinational lubricant technology leaders with premium positioning, national oil companies leveraging captive base oil production, and regional formulators serving cost-sensitive industrial corridors. Strategic moves center on unbundling service relationships from lubricant supply and deploying IoT-enabled condition monitoring to convert transactional sales into performance contracts.
Within the integrated petrochemical tier, China Petrochemical Corporation (Sinopec) anchors supply security through domestic refining infrastructure. Shell and FUCHS occupy positions at the synthetic formulation end, with Shell exemplifying technology leadership in high-temperature industrial applications and FUCHS representing specialization in food-grade and pharmaceutical manufacturing environments.
| Leading Market Players |
|---|
| Indian Oil Corporation Limited |
| Shell |
| Chevron Corporation |
| Total |
| ExxonMobil Corporation |
| FUCHS |
| China Petrochemical Corporation (Sinopec) |
| Klüber Lubrication |
| HP Lubricants |
| Others |
Pricing and Supply Chain Analysis
Group III base oil supply concentration in South Korea and Singapore exposes formulators to feedstock allocation risk during turnarounds, compressing margin spreads between synthetic premium tiers and mineral economy grades while forcing distributors toward multi-source qualification strategies.
Pricing Analysis
Long-term offtake agreements dominate procurement between multinational formulators and integrated refiners, insulating premium synthetic tiers from spot volatility while spot purchases govern mineral oil transactions in India's western manufacturing corridor. Price differentiation separates ISO VG 100 synthetic formulations with METI thermal certification from uncertified mineral alternatives through energy-efficiency performance guarantees. Cost compression in semi-synthetic mid-tiers is intensifying because automotive component clusters unbundle lubricant supply from OEM service contracts. Manufacturing procurement teams in Maharashtra and Gujarat exhibit highest price sensitivity, while Japanese pharmaceutical cleanrooms demonstrate lowest sensitivity due to GMP Annex 1 compliance mandates.
Supply Chain Analysis
Upstream feedstock dependency on high-viscosity index base stocks centers on South Korean and Singaporean refining complexes, with secondary sourcing from Thai aromatics plants. Formulation chemistry draws from polyalphaolefin imports, domestic ester production in China, and antioxidant additive packages from Japanese specialty chemical suppliers. Single-source vulnerability concentrates in PAO supply chains serving Japan's automotive component sector. Distribution runs through authorized distributor networks with technical service capabilities, bypassing commodity traders in premium synthetic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific compressor oil demand sits at early-cycle expansion driven by China's dual carbon retrofit mandates accelerating synthetic specification upgrades across Jiangsu and Zhejiang manufacturing bases.
For Market Incumbents: Entrench synthetic formulation leadership through captive base oil backward integration into South Korean or Singaporean refining assets, and secure NSF H1 registrations ahead of Indonesia's food processing belt expansion. Emerging halal-certified lubricant demand from Java-based dairy processors threatens unregistered suppliers with exclusion from procurement shortlists.
For New Entrants and Emerging Players: Indonesia's halal processing corridor offers the most penetrable white-space for ASEAN-registered suppliers with existing pharmaceutical-grade credentials. Target pharmaceutical cleanroom specifications in Osaka and Nagoya where GMP Annex 1 revisions mandate particle count guarantees that incumbent mineral oil suppliers cannot satisfy. Lead with digital oil monitoring integration to convert transactional sales into performance-contracting relationships.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors synthetic formulation specialists with established METI certification pathways. Long-term viability hinges on positioning ahead of refrigeration compressor retrofit cycles under Kigali Amendment deadlines. Watch for BIS certification timeline acceleration as the inflection signal indicating India's import filtering intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil | Sinopec's captive refining infrastructure anchors supply security against South Korean turnaround disruptions. |
| NSF H1 Registration Acquisition | Halal-certified food-grade positioning unlocks Java dairy processor procurement channels ahead of domestic competition. |
| IoT-Enabled Condition Monitoring Deployment | Thai manufacturing park sensor networks convert lubricant supply into predictive maintenance performance contracts. |
| GMP Annex 1 Compliance Investment | Particle count guarantees secure pharmaceutical cleanroom specifications in Osaka and Nagoya facilities. |
| Long-term Supply Agreement with Refiners | Offtake contracts with Singaporean complexes insulate synthetic tier margins from spot feedstock volatility. |
Research Methodology
Operator-level perspectives from plant maintenance directors, OEM procurement teams, aftermarket service heads, and fluid analysis laboratory managers anchored the qualitative base. Primary interviews combined with secondary validation from customs trade data, BIS certification registries, METI energy efficiency filings, and SEC 10-K disclosures from listed lubricant formulators. Bottom-up consumption modeling triangulated against top-down refining capacity assessments across the analysis window.
Scenario-bracketing framed low, base, and high cases around MEE enforcement intensity for dual carbon targets and BIS certification throughput capacity. Segmentation dimensions spanned formulation chemistry, ISO viscosity grade, end-use equipment category, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating compressor fleet expansion rates and synthetic substitution coefficients. Industry-specific inputs included Kigali Amendment refrigeration retrofit timelines and METI mandate implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese national oil companies or accelerated BIS certification automation would shift outcomes. Cross-checking against IEA industrial energy intensity benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Portable Air Compressor Market
Compressors
Positive Displacement Gas Compressor Market
Compressors
Centrifugal Compressors Market
Compressors
Positive-Displacement Hydrogen Compressor Market
Compressors
Tandem Piston Compressors Market
Compressors
Rental Air Compressors Market
Compressors
Air and Gas Compressor Market
Compressors
Oil and Gas Industry Gas Compressor Market
Compressors
Reciprocating Air Compressor Market
Compressors
Industrial Air Compressor Market
Compressors
Compressor Rental Market
Compressors
Turbocompressor Market
Compressors
Reciprocating Hydrogen Compressor Market
Compressors
PAG Compressor Oil Market
Compressors
North America Centrifugal Compressor Market
Compressors
Centrifugal Air Compressor Market