
 Portable Compressor Market | 2026-2036
Portable Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Compressor Market Analytics
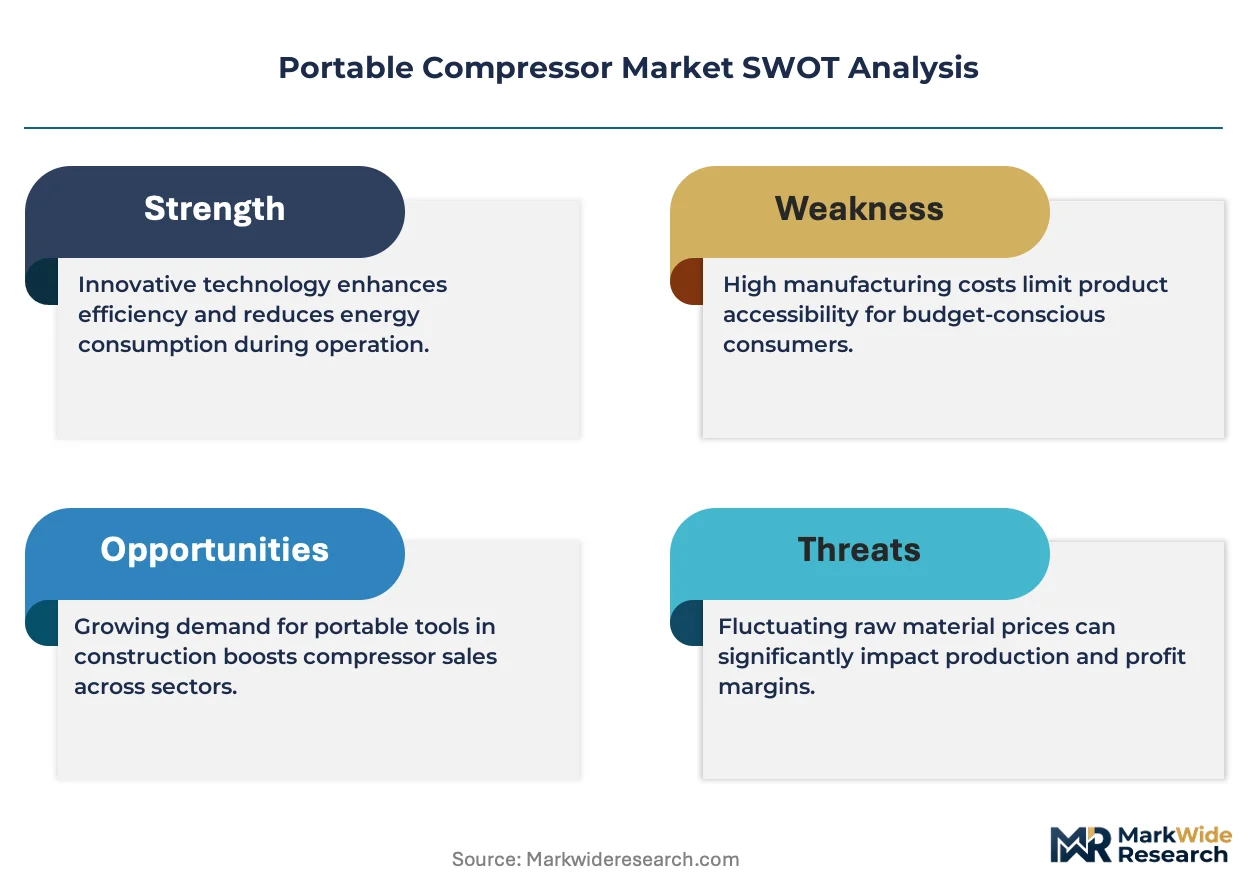
Aluminum is rebalancing portable compressor frame economics as manufacturers substitute cast-iron housings to cut weight and improve transportability on remote job sites. Atlas Copco leverages its rotary screw technology leadership to sustain premium positioning in European rental fleets. Ingersoll Rand anchors North American demand through extensive distributor networks serving construction contractors. ELGi Equipments dominates cost-competitive segments in South Asia with localized manufacturing scale.
A portable compressor is a self-contained, mobile positive-displacement or dynamic machine that pressurizes ambient air to deliver compressed air at discharge pressures typically spanning 100–250 psi, powering pneumatic tools, spray systems, and process equipment across industrial and commercial settings. Rotary screw compressors lead product type revenue due to continuous-duty reliability in construction and manufacturing applications, while oil-free variants capture fastest growth from food processing and electronics cleanroom demand. Contractors represent the largest end user segment by fleet volume, though industrial operators command superior per-unit margins through specification-driven procurement.
EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe compel diesel engine redesigns, elevating electric compressor competitiveness in urban construction zones. China's GB emission standards and India's CEA efficiency directives further fragment compliance requirements across manufacturing footprints. Stakeholders must monitor battery energy density improvements and fast-charging infrastructure deployment to assess when electric architectures displace conventional powertrains in heavy-duty portable applications.
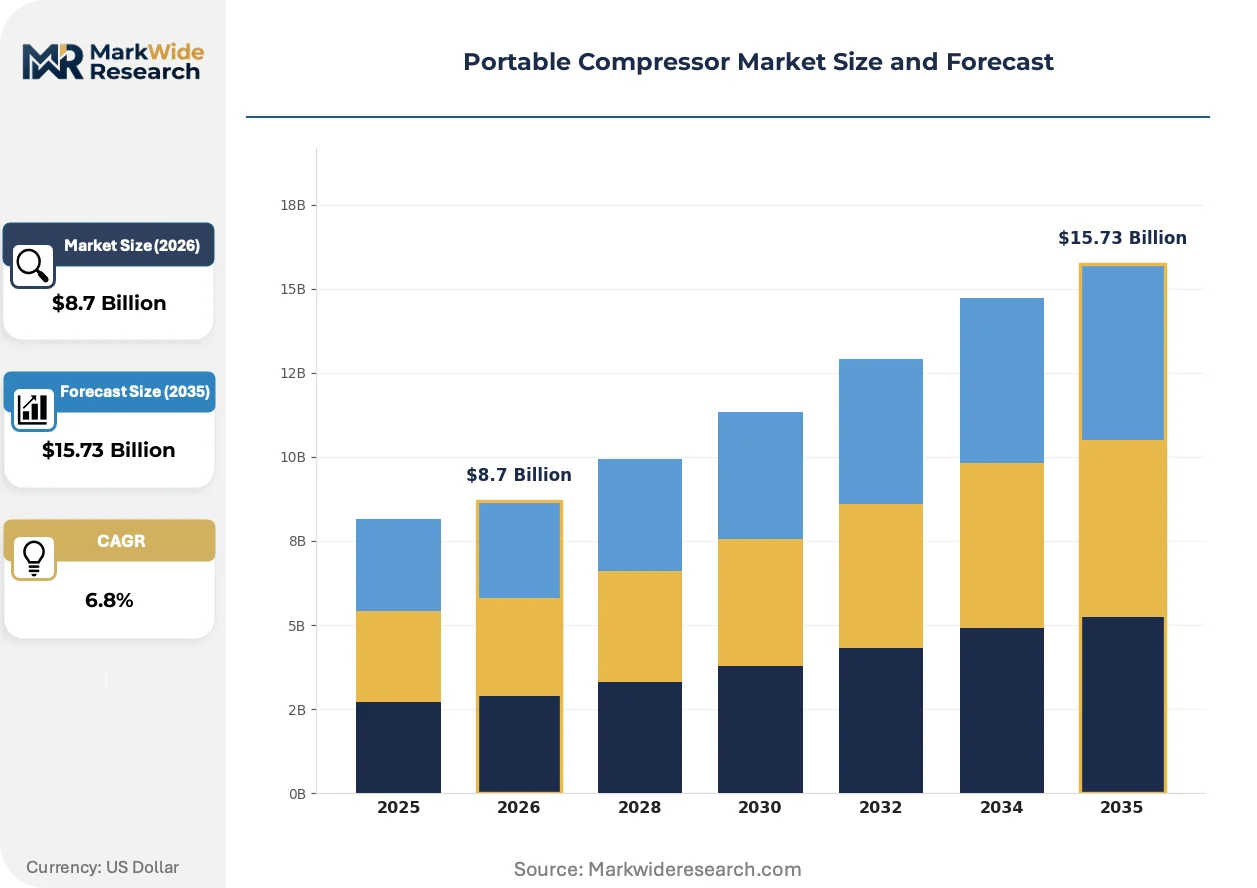
Market Dynamics
EPA Tier 4 Final emission standards are compressing diesel-powered portable compressor economics while elevating electric alternatives across urban construction zones. Aluminum frame substitution and battery energy density improvements are simultaneously reshaping product architecture and procurement criteria.
Growth Catalysts
- Construction Fleet Modernization:United States contractors are replacing aging diesel units to comply with EPA Tier 4 Final standards, accelerating procurement cycles for compliant equipment.
- GB Standards Compliance:China's emission directives are forcing provincial infrastructure fleets toward cleaner powertrains, sustaining replacement demand across municipal construction markets.
- Lithium-Ion Battery Maturation:Improved energy density is extending runtime for electric portable compressors, eroding the historical performance gap with conventional diesel units.
Market Restraints
- Diesel Engine Redesign Costs:EPA Tier 4 Final and EU Stage V compliance requirements are elevating bill-of-materials costs for engine suppliers, compressing margins on mid-range portable units.
- China Supply Concentration:Critical rare earth processing and battery cell manufacturing cluster in Chinese industrial zones, exposing downstream assemblers to geopolitical supply disruption risks.
- Electric Range Limitations:Battery-powered portable compressors face runtime constraints on remote job sites lacking grid access or fast-charging infrastructure, preserving diesel dependence in rural applications.
Strategic Opportunities
- India Infrastructure Buildout:CEA efficiency directives and national highway expansion are creating fleet procurement windows for cost-optimized electric and diesel-electric hybrid portable compressors.
- Food Processing Cleanrooms:Oil-free compressor architectures are capturing specification-driven replacement cycles in pharmaceutical and electronics manufacturing facilities requiring ISO 8573 Class 0 air quality.
- Rental Channel Digitization:Telematics-enabled fleet management platforms are allowing equipment rental companies to monetize utilization data and optimize compressor deployment across dispersed job sites.
Industry Challenges
- Tier 4 Engine Technician Scarcity:EPA-mandated aftertreatment systems require specialized diagnostic capabilities that distributor service networks struggle to staff across secondary construction markets.
- Multi-Jurisdiction Certification Burden:Manufacturers face divergent testing protocols across EPA, EU Stage V, and China's GB standards, elongating product launch timelines and engineering validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Compressor Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Free Compressors, Reciprocating Compressors, Rotary Screw Compressors, Centrifugal Compressors Application: Construction, Automotive, Manufacturing, Home Improvement End User: Contractors, DIY Enthusiasts, Industrial Operators, Service Providers Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Sullair, ELGi Equipments, Atlas Copco, Rotair, Chicago Pneumatic, Ingersoll Rand, Doosan Portable Power, Gardner Denver, Kaeser Kompressoren, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Compressor Market Evolving Landscape
Electrification architectures and lightweight materials are restructuring portable compressor competitive dynamics. Regulatory emission ceilings and shifting procurement economics are compressing technology adoption timelines across construction and industrial verticals.
Permanent magnet motor technology paired with variable speed drives is overtaking conventional fixed-speed induction motor designs in premium portable compressor segments. Municipal contractors and industrial maintenance departments are specifying these configurations for partial-load efficiency gains. The technology is overtaking legacy architectures by reducing fuel consumption and enabling quieter operation in noise-restricted urban zones.
EU Stage V non-road emission regulations are compelling diesel engine redesigns with selective catalytic reduction and diesel particulate filter integration. These aftertreatment additions are elevating unit costs and maintenance complexity for European construction fleets. Rental companies in Germany and France are responding by accelerating electric compressor pilot programs and renegotiating fleet procurement specifications with OEMs.
Telematics-enabled predictive maintenance contracts are displacing traditional break-fix service arrangements in North American rental channels. Equipment lessors are bundling compressor uptime guarantees with remote diagnostics, shifting revenue toward recurring service streams. This model is most visible in United States metropolitan construction markets where fleet utilization transparency justifies premium pricing for guaranteed availability.
Portable Compressor Market Segmentation
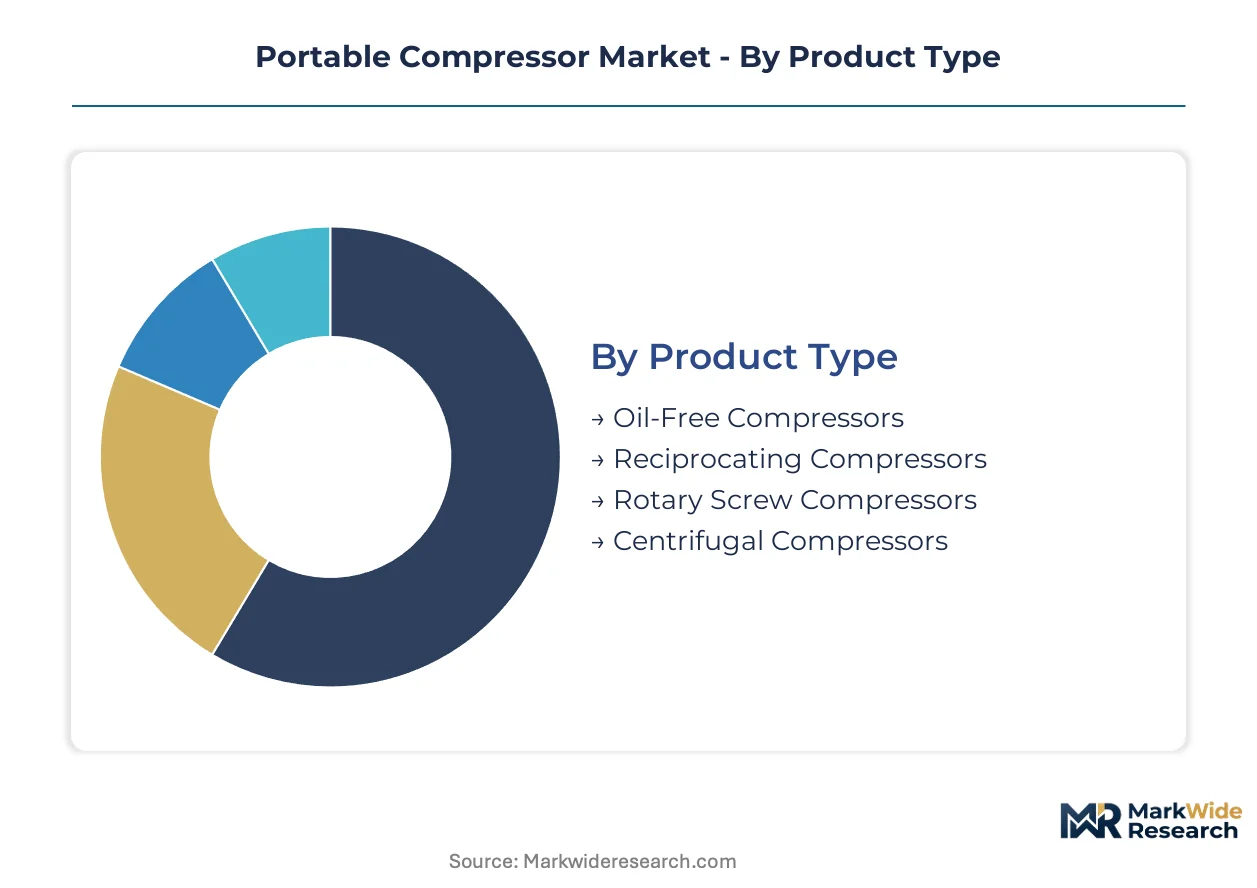
Portable compressor procurement patterns diverge sharply between fleet-scale construction buyers and intermittent-use residential customers. Product architecture, powertrain selection, and channel preference all fracture across these usage profiles.
Product Type:
Volume concentrates in rotary screw configurations for continuous-duty job sites, while premium margins attach to oil-free architectures serving contamination-sensitive applications.
- Rotary Screw Compressors:Positive-displacement units with intermeshing helical rotors deliver pulsation-free airflow for pneumatic tool banks and spray systems. Construction contractors in the United States specify these for multi-shift operations on highway and commercial building projects, prioritizing uptime reliability over capital cost.
- Oil-Free Compressors:These units eliminate lubricant contamination risk through dry-running rotors or water-injected compression. Food processors and electronics manufacturers in Germany and Japan mandate ISO 8573 Class 0 air quality, driving specification premiums that offset higher manufacturing complexity.
- Reciprocating Compressors:Piston-driven units dominate residential and light commercial segments where intermittent duty cycles and lower price points align with DIY enthusiast budgets.
- Centrifugal Compressors:Dynamic compression technology serves high-volume, steady-state industrial processes where energy efficiency at scale outweighs portability requirements.
Mature deployment sits with rotary screw compressors. Newer deployment is concentrated in oil-free architectures.
Application:
Cost tier stratification separates specification-driven industrial procurement from price-sensitive residential replacement cycles.
- Construction:Fleet operators deploy portable compressors for pneumatic nailers, impact wrenches, and concrete finishing tools across dispersed job sites. EPA Tier 4 Final compliance costs are accelerating electric unit pilots in California and New York metropolitan zones.
- Manufacturing:Plant maintenance departments specify oil-free and rotary screw units for production line air supply, capturing superior per-unit margins through performance guarantees and service bundling.
- Automotive:Body shops and tire service centers favor compact reciprocating units for intermittent spray painting and inflation tasks.
- Home Improvement:Retail-channel reciprocating compressors serve residential woodworking and hobbyist applications where portability and first-cost dominate selection criteria.
Specification intensity peaks in manufacturing. Volume scale concentrates in construction.
End User:
Customer type determines whether procurement flows through capital equipment budgets or discretionary retail expenditure.
- Contractors:Fleet managers negotiate multi-unit procurement with rental companies and OEM distributors, prioritizing total cost of ownership metrics including fuel consumption and maintenance intervals.
- Industrial Operators:Plant engineers specify compressors against process air quality standards, accepting premium pricing for guaranteed uptime and predictive maintenance contracts.
- Service Providers:Mobile repair technicians balance weight constraints against runtime requirements when selecting portable units for roadside and field service applications.
- DIY Enthusiasts:Price-sensitive residential buyers purchase through retail channels, responding to horsepower and tank capacity specifications with limited technical evaluation.
Recurring revenue potential sits with industrial operators. Transaction velocity concentrates with DIY enthusiasts.
Distribution Channel:
Channel selection tracks end-user sophistication and service requirements across the customer base.
- Distributors:Construction equipment dealers maintain field service capabilities and parts inventories that support contractor fleet requirements across secondary United States markets.
- Direct Sales:OEM account teams engage industrial operators for specification-driven procurement, embedding compressors within integrated facility air system designs.
- Online Retail:E-commerce platforms capture DIY enthusiast and small contractor demand through comparative specifications and delivery logistics.
- Specialty Stores:Home improvement retailers serve residential replacement cycles with immediate availability and in-store product comparison.
Service attachment rates peak through distributors. Transaction friction is lowest through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates portable compressor procurement through provincial infrastructure buildouts, while the United States and Germany anchor premium equipment demand through contractor fleet modernization and emission compliance cycles.
United States
Construction contractors drive fleet replacement across highway and commercial building projects. EPA Tier 4 Final standards compress diesel unit economics and elevate electric alternatives in California and New York metropolitan zones. Houston and Dallas-Fort Worth anchor distributor networks serving secondary construction markets.
China
Provincial infrastructure buildouts sustain fleet expansion across municipal construction markets. GB emission standards force cleaner powertrain adoption in Beijing-Tianjin-Hebei and Yangtze River Delta industrial clusters. Shanghai and Shenzhen concentrate manufacturing scale for cost-competitive export production.
Germany
Rental companies accelerate electric compressor pilots in response to EU Stage V compliance costs. Selective catalytic reduction and diesel particulate filter integration elevate maintenance complexity for construction fleets. Munich and Stuttgart anchor precision engineering capabilities for premium rotary screw production.
India
National highway expansion and CEA efficiency directives create procurement windows for cost-optimized equipment. State-level infrastructure tenders concentrate demand in Maharashtra and Gujarat manufacturing corridors. Mumbai and Ahmedabad host localized assembly operations serving South Asian markets.
Japan
Electronics manufacturers mandate ISO 8573 Class 0 air quality specifications for cleanroom operations. METI efficiency standards drive oil-free compressor adoption in semiconductor fabrication facilities. Osaka and Nagoya anchor precision component supply chains for contamination-sensitive applications.
Portable Compressor Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale aluminum frame production and battery-integrated architectures. The vendor base separates into three tiers: premium technology specialists, scale-driven cost optimizers, and regional fabricators serving protected domestic markets. Strategic archetypes include full-line diversified industrials, compressor-focused pure-plays, and rental channel specialists. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players extending service networks into secondary construction markets and adding electric variants to diesel-heavy product lines.
Among diversified industrial conglomerates, Atlas Copco AB and Ingersoll Rand Inc. occupy positions exemplifying premium-tier technology leadership and extensive North American distribution reach respectively. ELGi Equipments Limited represents the cost-optimized manufacturing archetype with South Asian production scale. These three anchors illustrate how competitive positioning fragments across technology specialization, channel density, and manufacturing geography rather than consolidating around unified global standards.
| Leading Market Players |
|---|
| Sullair |
| ELGi Equipments |
| Atlas Copco |
| Rotair |
| Chicago Pneumatic |
| Ingersoll Rand |
| Doosan Portable Power |
| Gardner Denver |
| Kaeser Kompressoren |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between ISO 8573 Class 0 oil-free systems and standard rotary screw units manifests in divergent pricing power and supplier concentration patterns. Premium oil-free architectures command specification-driven margins through contamination-sensitive electronics and pharmaceutical buyers, while commodity rotary screw production gravitates toward aluminum frame assemblers in China and India serving cost-optimized construction fleets.
Pricing Analysis
Volume-margin splits separate construction contractor fleet procurement from industrial operator specification buying. Three-tier pricing structure across premium oil-free, standard rotary screw, and economy reciprocating levels reflects certification grade and after-sales bundling intensity. Cost compression in mid-range diesel units intensifies because EPA Tier 4 Final aftertreatment investments elevate bill-of-materials without proportional performance gains. DIY enthusiasts through retail channels exhibit highest price sensitivity; industrial maintenance departments accepting predictive maintenance contracts show lowest.
Supply Chain Analysis
Rare earth magnet supply rests on Chinese processing clusters and South Korean battery cell manufacturing for electric portable compressor motor assemblies. Aluminum frame extrusions and lithium-ion battery packs constitute critical input dependencies alongside precision-machined rotary screw air ends. Single-source vulnerability concentrates in permanent magnet rare earth processing, exposing downstream OEMs to export restriction risks. Distribution runs through construction equipment dealer networks with embedded field service capabilities across secondary United States markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Emission compliance cost escalation is forcing consolidation across mid-tier diesel compressor assemblers lacking electric transition capital.
For Market Incumbents: Hedge diesel exposure by accelerating electric architecture R&D partnerships with battery cell suppliers. Atlas Copco and Ingersoll Rand should deepen backward integration into permanent magnet motor production to secure supply against Chinese rare earth export controls. Capacity addition in India and Vietnam manufacturing corridors captures cost-optimized demand from provincial infrastructure buildouts while distancing from single-country supply concentration. For New Entrants and Emerging Players: E-commerce direct-to-contractor channels offer lowest friction entry points for lightweight electric portable compressors targeting residential renovation and small commercial maintenance segments. Food processing cleanroom specifications present the most penetrable white-space given incumbent focus on construction volume. Telematics-enabled rental fleet partnerships provide differentiated go-to-market positioning against established distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with electric-focused pure-plays given lithium-ion energy density improvements and fast-charging infrastructure deployment as valuation catalysts. Long-term viability favors manufacturers with demonstrated aluminum frame production scale and battery-integrated architecture certification. Battery energy density thresholds crossing diesel runtime parity represent the critical signal to watch for electric displacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Architecture Certification | EPA and EU Stage V compliance costs position battery-integrated designs for urban construction zone penetration. |
| Aluminum Frame Manufacturing Scale-Up | Weight reduction for transportability addresses remote job site logistics constraints across provincial Chinese markets. |
| Predictive Maintenance Service Bundling | Telematics-enabled uptime guarantees shift rental channel revenue toward recurring streams in United States metropolitan zones. |
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with Chinese processors mitigate permanent motor cost volatility for premium rotary screw production. |
| Oil-Free Cleanroom Specification Capture | ISO 8573 Class 0 certification investment unlocks pharmaceutical and semiconductor fabrication facility replacement cycles. |
Research Methodology
Document review covered customs trade databases, EPA and EU emission compliance filings, and construction equipment rental fleet disclosures, complemented by interviews with plant engineers at industrial compressor installations, procurement leads at United States contractor fleets, aftermarket service heads at European rental companies, and technical R&D directors at aluminum frame manufacturers. Secondary validation drew from SEC 10-K equipment segment disclosures, China customs export statistics, and Japan METI efficiency standard documentation. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segment-level projections across product type, powertrain architecture, end-user category, and regional regulatory cluster fed into analytical framework development over the projection horizon. CAGRs derived from regression analysis of historical fleet replacement cycles against emission standard implementation timelines. Industry-specific forecast inputs included lithium-ion battery cost curves and provincial Chinese infrastructure tender award patterns.
The model holds under stable emission enforcement and battery chemistry cost decline assumptions; deviation in rare earth export restrictions or construction lending contraction would shift volume trajectories. A small set of triggers including fast-charging infrastructure deployment pace and Tier 4 technician training program expansion warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Positive-Displacement Hydrogen Compressor Market
Compressors
Compressed Air Filtration and Dryer System Market
Compressors
Liquid Ring Compressors Market
Compressors
Centrifugal Compressors Market
Compressors
Tandem Piston Compressors Market
Compressors
Automotive Compressors Market
Compressors
North America Air Compressor Market
Compressors
Oil-Free Air Compressor Market
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Oil Filled Air Compressor Market
Compressors
Centrifugal Air Compressor Market
Compressors
PAG Compressor Oil Market
Compressors
Positive Displacement Gas Compressor Market
Compressors
Chlorine Compressors Market
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Hydrogen Compressor Market