
 Scroll Compressor Market | 2026-2036
Scroll Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Scroll Compressor Market Analysis
A shift from single-source to multi-source component procurement is pivoting how scroll compressor assemblers manage motor and casting supply. Panasonic sustains in-house production of hermetic scroll sets across its Japanese and Malaysian plants. Copeland LP anchors North American aftermarket service networks through direct contractor channels. Ingersoll Rand differentiates via oil-free scroll variants for medical and laboratory air systems.
A scroll compressor employs two interleaved spiral-shaped scrolls—one fixed, one orbiting—to compress refrigerant or air through progressive volume reduction, typically achieving discharge pressures up to 30 bar with near-isentropic efficiency. Its primary purpose centers on vapor compression cycles for cooling, heating, and industrial air delivery. Air conditioning compressors still occupy the largest revenue pool across product types, though heat pump compressors represent the fastest-expanding category amid building electrification mandates. Variable speed technology leads in premium segment margin capture, while fixed speed units dominate replacement demand in cost-sensitive residential cooling applications.
The US EPA SNAP program and the EU F-Gas Regulation are tightening allowable global warming potential thresholds for refrigerants, forcing scroll compressor redesigns around lower-GWP working fluids. China's GB standards through SAMR enforce minimum energy performance ratios that favor inverter-driven scroll architectures in domestic HVAC products. OEMs and contractors must monitor refrigerant chemistry transitions and regional efficiency tier migrations to avoid stranded inventory and compliance gaps.
Market Dynamics
Heat pump electrification mandates are forcing scroll compressor OEMs to redesign displacement volumes and pressure ratios for R-32 and R-454B refrigerant chemistries, compressing development cycles and supplier qualification timelines.
Growth Catalysts
- EU F-Gas Regulation phase-down:The tightening GWP thresholds are accelerating replacement demand for lower-carbon refrigerant-compatible scroll architectures across European residential retrofits.
- China's eastern manufacturing clusters:Concentrated HVAC production in Jiangsu and Zhejiang provinces is generating procurement pull for high-volume inverter scroll compressor contracts.
- Variable speed drive integration:Widespread adoption of permanent magnet motors is expanding addressable efficiency tiers in premium residential and light commercial cooling systems.
Market Restraints
- Copper and rare earth price volatility:Magnet materials and winding conductors account for substantial bill-of-materials exposure, squeezing margin stability at fixed-price contract OEMs.
- Japanese and Malaysian supply concentration:Hermetic scroll set production clusters in specific East Asian manufacturing zones create geographic risk for European and North American assemblers.
- Rotary compressor substitution:Cost-optimized rotary architectures are capturing share in sub-3HP residential cooling segments where scroll efficiency premiums do not justify price gaps.
Strategic Opportunities
- US Inflation Reduction Act heat pump incentives:Federal tax credits and state rebate programs are stimulating residential electrification retrofits requiring cold-climate scroll compressor specifications.
- Data center liquid cooling integration:Precision cooling OEMs are specifying oil-free scroll variants for secondary loop compression in hyperscale facility thermal management.
- Refrigerant chemistry convergence:A2L mildly flammable working fluid adoption is creating white space for scroll designs with enhanced leak detection and charge minimization features.
Industry Challenges
- Refrigerant safety certification timelines:A2L compatibility testing under updated UL 60335-2-40 protocols is extending product launch schedules by 12-18 months for North American market entry.
- Orbital scroll machining precision:Tightening tolerances for involute profile accuracy require capital-intensive grinding equipment upgrades at casting and forging suppliers.
- Legacy HVAC system integration:Retrofit compatibility with existing R-410A infrastructure complicates field deployment of next-generation refrigerant scroll units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scroll Compressor Market |
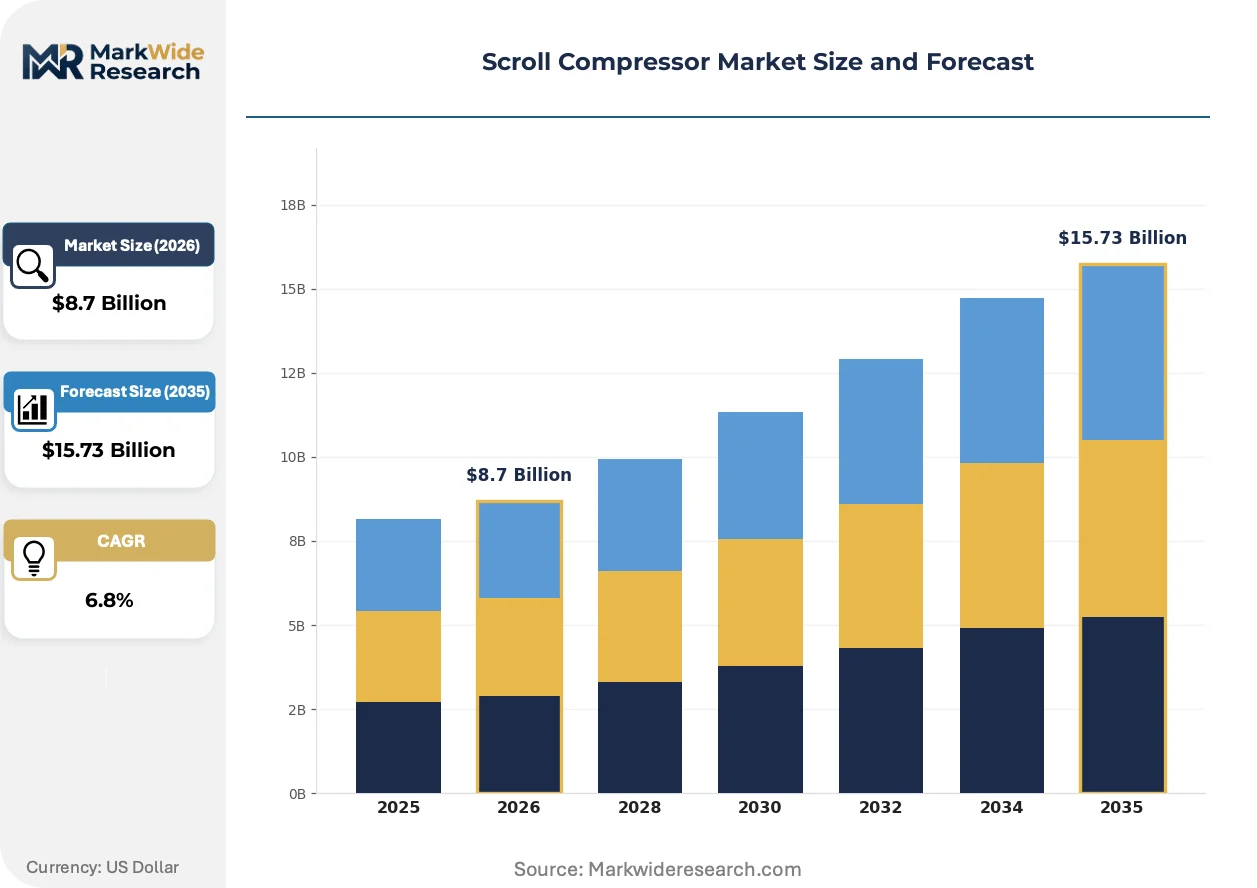
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigeration Compressors, Air Conditioning Compressors, Heat Pump Compressors, Chillers Application: Residential Cooling, Commercial Refrigeration, Industrial Cooling, Automotive HVAC Technology: Variable Speed, Fixed Speed, Digital Scroll, Inverter Technology End User: Manufacturers, Contractors, OEMs, End Consumers |
| Companies Covered | Danfoss, Kaeser Compressors, Atlas Copco AB, Panasonic, LG Electronics, Copeland LP, Mitsui Seiki Kogyo, Air Squared, Inc, Ingersoll Rand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scroll Compressor Market Emerging Trajectories
Digital twin simulation and AI-driven predictive maintenance are reshaping how scroll compressor performance is validated and monitored across the product lifecycle, compressing development feedback loops and shifting service revenue models.
Advanced orbital scroll profile optimization software is automating the geometric refinement process that previously required manual CAD iteration and physical prototyping cycles. Japanese HVAC OEMs are deploying these tools to reduce time-to-market for cold-climate heat pump variants. The technology is automating the trade-off between volumetric efficiency and manufacturing tolerance feasibility that has historically constrained scroll design freedom.
The US EPA SNAP program and EU F-Gas Regulation are synchronizing refrigerant phase-down schedules, creating transatlantic alignment on A2L and hydrocarbon working fluid timelines. Equipment manufacturers must now certify scroll compressors for dual refrigerant compatibility to avoid stranded inventory in either jurisdiction. Commercial rooftop and VRF segments are responding fastest, with residential split-system certification lagging by approximately one product cycle.
Building automation system integration is elevating compressor specification authority from mechanical contractors to controls integrators and energy service companies. Traditional wholesale distribution channels are losing specification influence as performance contracting and guaranteed energy savings models capture commercial new construction and deep retrofit projects. This shift is most pronounced in German and Dutch commercial building markets where energy performance certificates drive procurement criteria.
Scroll Compressor Market Segmentation
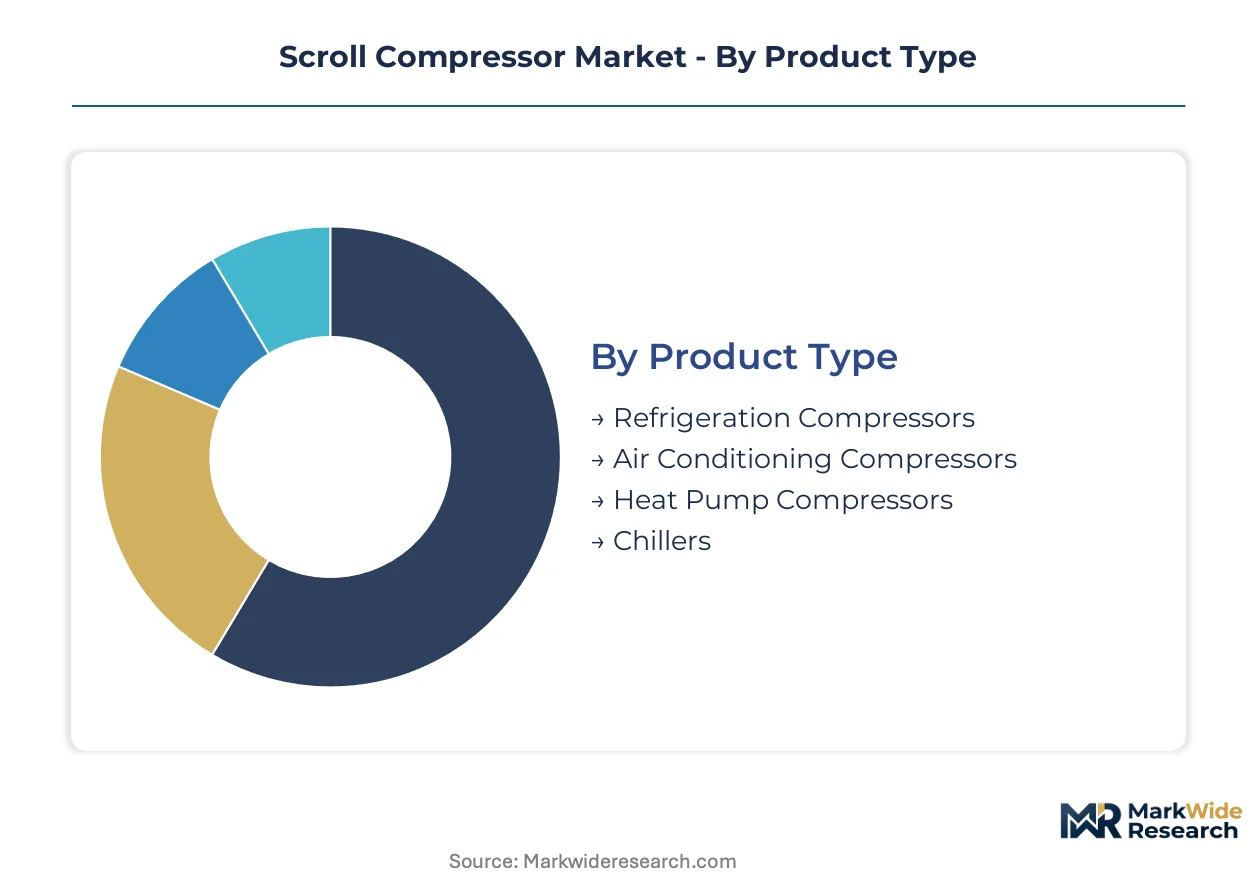
Scroll compressor procurement decisions split across technical specifications, refrigerant compatibility requirements, and channel access patterns. Understanding how buyers prioritize across these dimensions reveals where margin pools concentrate and which technology transitions command premium pricing.
Product Type:
Buyers select product types based on thermal load profiles, refrigerant chemistry constraints, and system integration complexity.
- Air Conditioning Compressors:These units dominate residential and light commercial cooling with discharge pressures optimized for R-410A and transitioning R-32 chemistries. Demand clusters in China's Jiangsu and Zhejiang manufacturing corridors where HVAC OEMs source high-volume inverter-compatible scroll sets for domestic and export markets.
- Heat Pump Compressors:Designed for reversible vapor compression cycles with expanded operating maps for low-ambient heating. European residential retrofits under the EU F-Gas Regulation phase-down are pulling displacement volumes and pressure ratios tailored for R-454B and R-32 working fluids.
- Refrigeration Compressors:Lower displacement variants for commercial cold chain applications with evaporating temperature ranges down to -40°C.
- Chillers:Higher capacity scroll arrays for process cooling and building thermal management in light commercial segments.
Air conditioning compressors lead on scale; heat pump compressors lead on momentum.
Application:
Application selection tracks building stock vintage, energy code stringency, and contractor installation capacity.
- Residential Cooling:Split-system and packaged unit deployments where fixed-speed scrolls dominate replacement demand and inverter drives capture new construction premium tiers. The US Inflation Reduction Act rebates are accelerating heat pump conversions that require cold-climate scroll specifications.
- Commercial Refrigeration:Supermarket display cases, walk-in coolers, and food service equipment where leak detection integration matters for A2L refrigerant compliance.
- Industrial Cooling:Process chillers and manufacturing facility thermal management with oil-free scroll variants specified for clean air requirements.
- Automotive HVAC:Electric vehicle thermal management systems where scroll compressors compete with electric-driven alternatives for cabin and battery conditioning.
Residential cooling commands volume concentration; commercial refrigeration shows steepest expansion trajectory from cold chain infrastructure buildout.
Technology:
Technology choice reflects efficiency tier positioning and controls integration depth.
- Variable Speed:Permanent magnet motor drives with modulated capacity matching thermal load curves, capturing premium margins in energy performance contracting models. China's GB standards through SAMR enforce minimum energy performance ratios that favor these architectures in domestic HVAC products.
- Inverter Technology:Frequency-controlled drives with soft-start capability reducing electrical infrastructure stress, specified in Japanese and South Korean residential markets with high electricity tariffs.
- Fixed Speed:On/off cycling compressors dominating cost-sensitive replacement demand where efficiency premiums do not justify price gaps.
- Digital Scroll:Unloading mechanisms for stepped capacity control in light commercial applications without full variable speed electronics.
Fixed speed retains replacement volume dominance; variable speed gains share fastest from building electrification mandates.
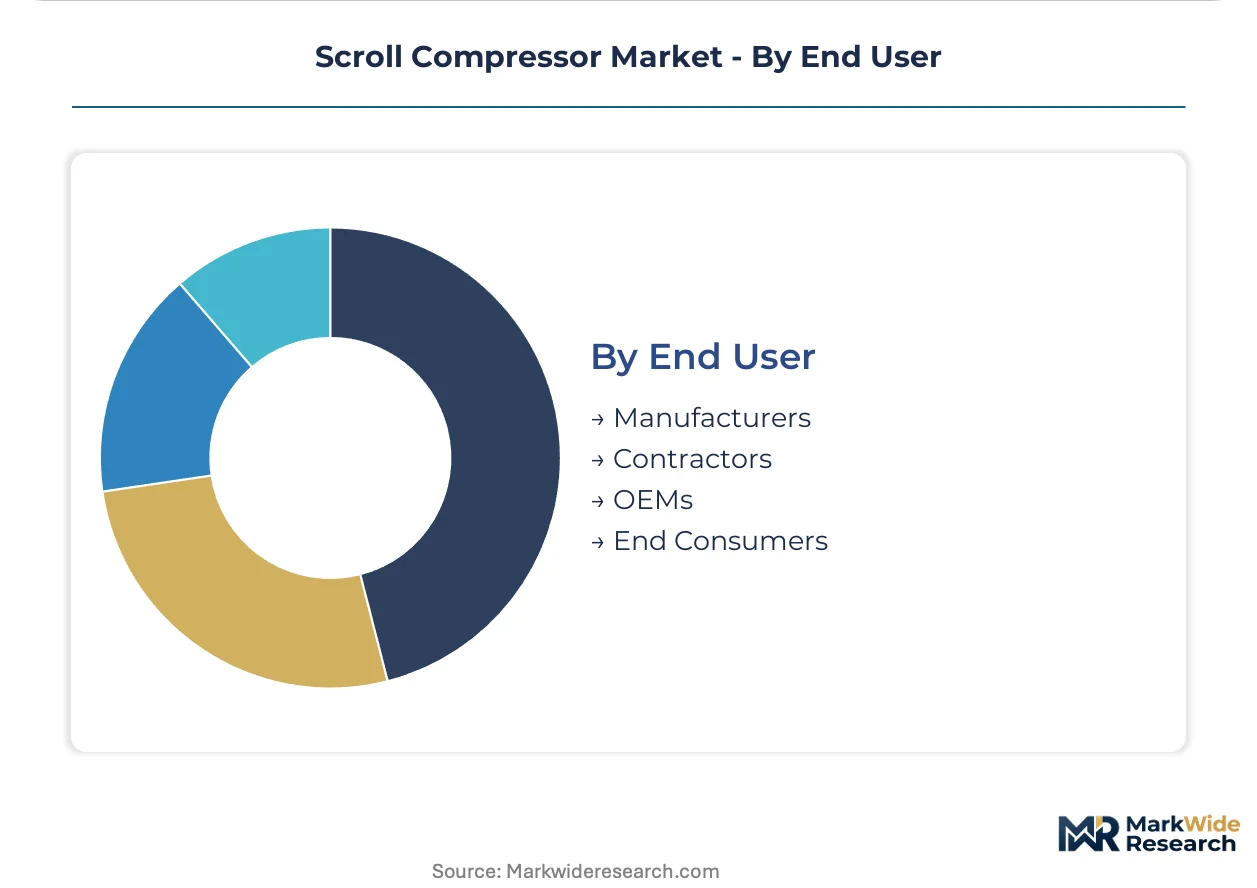
End User:
End user category determines specification authority and procurement channel structure.
- OEMs:Original equipment manufacturers with direct compressor qualification programs, volume contracts, and refrigerant transition roadmaps synchronized with their product platforms. Panasonic sustains in-house hermetic scroll production for captive supply.
- Contractors:Installation and service providers influencing replacement demand through aftermarket distribution, with specification authority shifting to controls integrators in performance contracting models.
- Manufacturers:Component and subsystem assemblers sourcing scroll sets for integration into larger climate systems.
- End Consumers:Residential and small commercial buyers with limited technical specification input, primarily price-responsive in emergency replacement scenarios.
OEMs anchor procurement volume; contractors represent the fastest-growing specification influence from service revenue model expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor scroll compressor procurement pull through concentrated HVAC manufacturing corridors serving domestic and export demand clusters.
China
Domestic HVAC OEMs in Jiangsu and Zhejiang provinces drive high-volume inverter scroll compressor contracts. GB standards through SAMR enforce minimum energy performance ratios favoring variable speed architectures. Suzhou and Hangzhou manufacturing clusters coordinate component sourcing for both residential cooling and heat pump production lines.
United States
Residential electrification retrofits under the Inflation Reduction Act stimulate cold-climate heat pump scroll specifications. The EPA SNAP program tightens refrigerant global warming potential thresholds for equipment certification. Texas and southeastern states concentrate contractor distribution networks for aftermarket replacement demand.
Germany
Building automation integration elevates compressor specification authority toward energy service companies in commercial retrofit markets. The EU F-Gas Regulation accelerates lower-GWP refrigerant transition timelines for scroll architectures. The Rhine-Ruhr industrial corridor hosts precision cooling OEMs specifying oil-free variants for laboratory applications.
Japan
Hermetic scroll set production sustains captive supply chains across domestic and Malaysian plant networks. METI efficiency standards and high electricity tariffs reinforce inverter technology penetration in residential markets. Nagoya and Osaka manufacturing zones concentrate orbital scroll machining precision capabilities.
India
Commercial refrigeration infrastructure buildout drives demand for lower displacement scroll variants in supermarket and cold chain applications. BIS energy efficiency labeling creates tiered procurement criteria for imported and domestically assembled compressors. Gujarat and Maharashtra industrial corridors attract HVAC component manufacturing investments from East Asian suppliers.
Scroll Compressor Market Vendor Landscape
Global majors compete with regional champions across refrigerant transition roadmaps and inverter technology integration depth. The vendor base clusters around three strategic tiers: integrated HVAC OEMs with captive scroll production, dedicated compressor specialists with multi-refrigerant certification capabilities, and industrial air system providers with oil-free specialization. Dominant competitive moves include backward integration into permanent magnet motor supply and geographic expansion through regional assembly joint ventures.
Within the integrated OEM tier, Panasonic exemplifies captive hermetic scroll production across East Asian manufacturing networks. Among dedicated compressor specialists, Copeland LP occupies a position anchored in North American aftermarket service channels, while Ingersoll Rand represents the oil-free specialization archetype for medical and laboratory air systems. These three companies illustrate how competitive positioning diverges across refrigerant compatibility breadth, channel access patterns, and end-use application focus.
| Leading Market Players |
|---|
| Danfoss |
| Kaeser Compressors |
| Atlas Copco AB |
| Panasonic |
| LG Electronics |
| Copeland LP |
| Mitsui Seiki Kogyo |
| Air Squared, Inc |
| Ingersoll Rand |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up compressor specialists anchor tiered pricing discipline through captive motor supply and long-term OEM offtake agreements, while sovereign-backed producers in East Asia leverage state-supported rare earth access to undercut margin structures in export markets. This ownership-financing bifurcation creates divergent supply behaviors: buyout-backed firms prioritize price realization through aftermarket service bundling, whereas state-linked manufacturers absorb input volatility to secure volume share in China's Jiangsu and Zhejiang manufacturing corridors.
Pricing Analysis
Input-cost pass-through from copper and neodymium magnet exposure dominates margin management, with contract structures indexing raw material baskets to LME and rare earth spot benchmarks. Pricing stratifies across premium inverter-driven, standard fixed-speed, and economy rotary-substitute tiers, with certification grade under UL 60335-2-40 and GB standards creating measurable price premiums. Cost compression in the fixed-speed tier is intensifying because rotary compressor substitution captures sub-3HP residential cooling share. OEM procurement teams exhibit lowest price sensitivity, while emergency replacement contractors face acute margin pressure from spot copper volatility.
Supply Chain Analysis
Direct-to-OEM channels handle high-volume inverter scroll demand from China's Jiangsu and Zhejiang HVAC manufacturing clusters, while aftermarket distribution networks serve North American contractor replacement markets through regional warehousing nodes. Geographic supply concentration centers on Japan, Malaysia, and China for hermetic scroll set fabrication, with precision orbital machining capabilities concentrated in Nagoya and Osaka industrial zones. Raw material dependencies draw from Chilean copper cathode, Chinese rare earth magnet processing, and Japanese electrical steel laminations. Single-source vulnerability in Malaysian hermetic assembly plants creates geographic risk for European and North American OEM qualification timelines. Distribution runs through authorized wholesaler networks in mature markets and direct factory relationships in China's eastern manufacturing provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scroll compressor market functions as a regulatory compounder, with the EU F-Gas Regulation's GWP phase-down schedule and the US EPA SNAP program synchronizing demand pull for lower-carbon refrigerant-compatible architectures across transatlantic residential retrofit cycles.
For Market Incumbents: To counter rotary compressor substitution in sub-3HP residential cooling segments, accelerate backward integration into permanent magnet motor supply and establish captive rare earth magnet sourcing through offtake agreements with Chinese processors. Expand cold-climate heat pump certification portfolios under A2L protocols to defend specification authority as the US Inflation Reduction Act rebates stimulate electrification retrofits. Prioritize dual-refrigerant compatibility testing to avoid stranded inventory during the R-410A to R-32/R-454B transition window. For New Entrants and Emerging Players: Capture white space in oil-free scroll variants for data center liquid cooling and medical air systems, where Ingersoll Rand's specialization leaves room for price-competitive alternatives. Target India's commercial refrigeration infrastructure buildout through BIS-certified lower-displacement variants for supermarket and cold chain applications. Pursue joint venture assembly partnerships with Gujarat and Maharashtra industrial corridor investors to circumvent tariff exposure on fully-finished compressor imports. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap specialists with A2L certification gaps but established orbital scroll machining capabilities, as refrigerant transition timelines compress strategic optionality. Long-term viability over the projection horizon hinges on dual-refrigerant platform readiness and inverter technology integration depth. Monitor UL 60335-2-40 certification completion rates as the inflection signal for North American market access timing.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Refrigerant Platform Development | Prevents stranded inventory as EU F-Gas and US EPA SNAP timelines synchronize A2L adoption. |
| Permanent Magnet Motor Backward Integration | Reduces exposure to Chinese rare earth price volatility through captive magnet sourcing. |
| Cold-Climate Heat Pump Certification | Captures US Inflation Reduction Act rebate-driven demand for low-ambient heating performance. |
| Regional Assembly Joint Venture | Localizes production in India's Gujarat corridor to serve commercial refrigeration infrastructure buildout. |
| Oil-Free Scroll Specialization | Addresses data center liquid cooling specifications from hyperscale facility thermal management OEMs. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's HVAC OEM procurement directors, compressor aftermarket service network managers, refrigerant regulatory affairs specialists, and orbital scroll machining equipment suppliers. Secondary validation drew from EPA SNAP program filings, EU F-Gas Regulation implementation guidance, SAMR GB standard enforcement notices, and customs trade data for compressor component flows. Bottom-up demand modeling triangulated against top-down manufacturing capacity assessments across Japanese, Malaysian, and Chinese production facilities.
Granularity-level modeling operated at product type, refrigerant chemistry compatibility tier, technology architecture, and end-user channel dimensions, with additional disaggregation by regional efficiency standard cluster. CAGRs were derived from installed base replacement cycles, building electrification policy intensity scoring, and refrigerant phase-down schedule compliance timelines. Forecast inputs incorporated inverter penetration trajectories in China's domestic HVAC market and cold-climate heat pump specification adoption rates under US federal incentive programs.
Raw material price spikes, A2L safety certification delays, and rotary compressor technology advancement are the dominant revision risks to base-case demand assumptions. Forecasts reflect documented assumptions regarding refrigerant chemistry convergence timelines and regional efficiency tier migrations. Periodic stress-testing of base assumptions against actual certification completion rates and OEM platform launch schedules is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Asia-Pacific Centrifugal Compressor Market
Compressors
Bus Compressor Market
Compressors
North America Centrifugal Compressor Market
Compressors
Russia Reciprocating Compressor Market
Compressors
Gas Compressors Market
Compressors
Oil-Free Air Compressor Market
Compressors
Air and Gas Compressor Market
Compressors
Rental Air Compressors Market
Compressors
LNG Compressor Market
Compressors
Centrifugal Air Compressor Market
Compressors
Reciprocating Compressor Market
Compressors
Compressed Air Filtration and Dryer System Market
Compressors
Oil Filled Air Compressor Market
Compressors
CNG Compressor Market
Compressors
Europe Centrifugal Compressor Market
Compressors
Compressed Air Lubricators Market