
 Oil Filled Air Compressor Market | 2026-2036
Oil Filled Air Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Filled Air Compressor Market Intelligence
ISO 8573-1 Class 0 and Class 1 oil carryover specifications is reorganizing procurement priorities across process industries. Atlas Copco AB leverages its rotary screw technology leadership to anchor premium positions in food and pharmaceutical-grade installations. ELGi Equipment Limited specializes in cost-optimized reciprocating systems that dominate India's aftermarket channels. Kaeser Kompressoren SE sustains German engineering credibility through direct-drive configurations serving automotive OEM lines.
An oil filled air compressor is a positive-displacement or dynamic machine that uses lubricating oil to seal compression chambers, dissipate heat, and reduce mechanical wear, typically achieving discharge pressures from 100 to 250 psig depending on stage configuration. Its primary purpose is delivering continuous or intermittent compressed air for pneumatic tools, process automation, and material handling in heavy industrial environments. Rotary screw systems capture the largest volume pool due to their duty-cycle efficiency in 24/7 manufacturing plants, while variable speed drive technology claims the fastest expansion trajectory as facilities pursue load-matched energy consumption. Centrifugal compressors occupy the high-flow, oil-lubricated niche above 500 horsepower where marginal efficiency gains justify capital intensity.
EPA air quality standards and OSHA workplace noise regulations in the United States compel fleet replacements and acoustic enclosure investments, while EU Ecodesign directives and F-Gas Regulation in Europe mandate efficiency benchmarking and refrigerant-compatible lubricant formulations. China's GB standards and MIIT energy-labeling programs enforce compressor performance tiers that filter import eligibility and domestic procurement. Stakeholders must weigh regulatory compliance timelines against technology refresh cycles when allocating capital across belt-drive legacy assets and direct-drive upgrade paths.
Market Dynamics
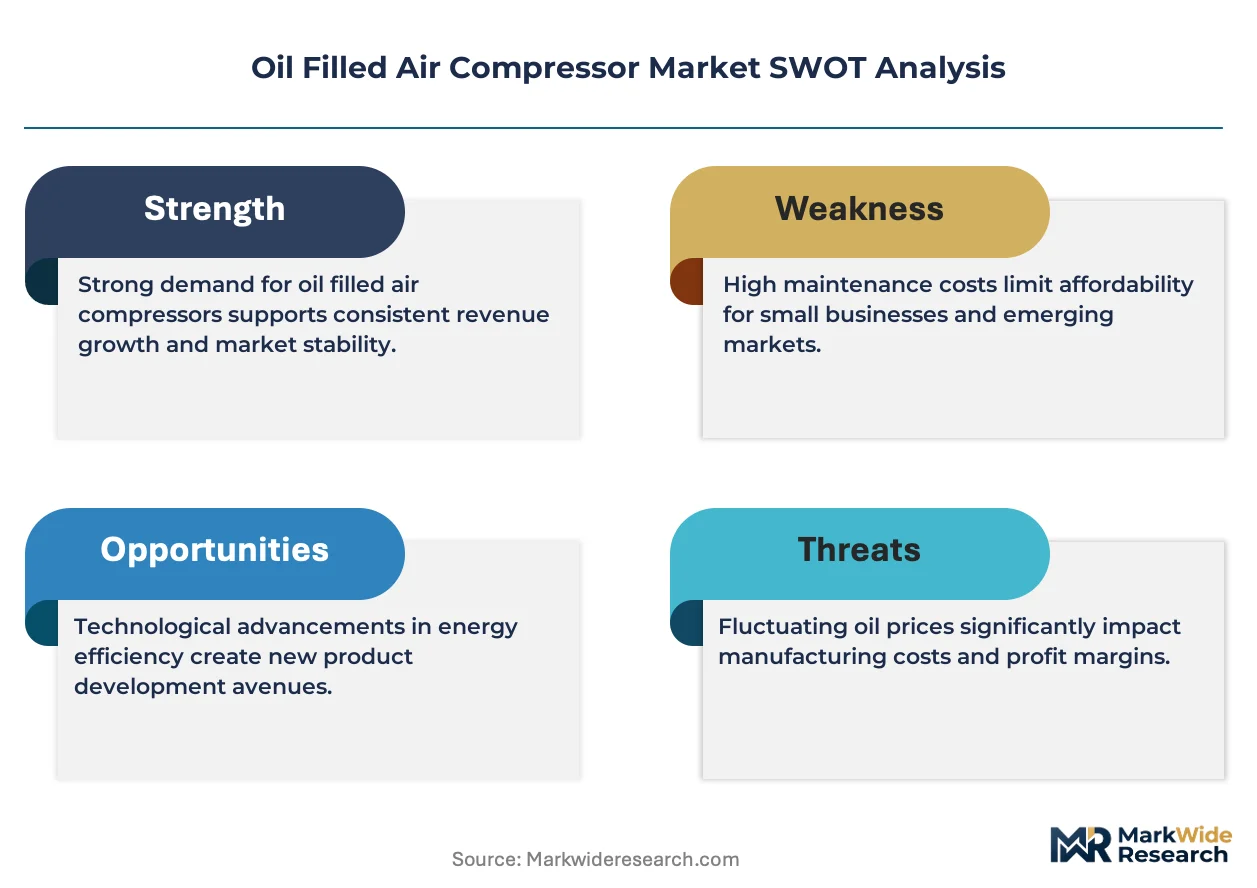
Variable speed drive technology is compressing payback periods for energy-intensive rotary screw installations, forcing incumbent fleet operators to accelerate replacement timelines ahead of regulatory phase-outs.
Growth Catalysts
- India's BIS energy standards:Tightening efficiency mandates in manufacturing corridors are disqualifying legacy belt-drive units from public procurement pools and large industrial tenders.
- Automotive OEM lines:Direct-drive configurations are capturing specification wins as German and Japanese automakers demand continuous-duty reliability for robotic welding and paint shop operations.
- Variable speed drive integration:Load-matched energy consumption is cutting electricity costs by double-digit percentages in 24/7 process plants, accelerating retrofit demand.
Market Restraints
- Lubricant formulation constraints:EU F-Gas Regulation compatibility requirements are narrowing supplier pools for refrigerant-grade compressor oils, inflating input costs.
- Foundry capacity concentration:Cast iron and aluminum housing production clusters in eastern China create vulnerability to regional power rationing and environmental compliance shutdowns.
- Permanent magnet motor substitution:Oil-free turbo compressor technology is eroding addressable market in pharmaceutical clean rooms and semiconductor fabs.
Strategic Opportunities
- Southeast Asian manufacturing zones:Vietnam and Indonesia's industrial park expansions lack established aftermarket service networks, creating first-mover channel advantages.
- Food-grade Class 0 certification:ISO 8573-1 compliance is becoming a tender prerequisite for dairy processing and beverage bottling lines, segmenting premium pricing tiers.
- Industrial IoT convergence:Predictive maintenance algorithms married to compressor telemetry are enabling subscription revenue models that decouple service from hardware margins.
Industry Challenges
- Compressed air system integration:Facility engineers lack cross-training in pneumatic network optimization, delaying VSD retrofit commissioning and eroding projected energy savings.
- ISO 8573-1 Class 0 certification timelines:Third-party validation bottlenecks are stretching qualification cycles to 18-24 months, freezing product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Filled Air Compressor Market |
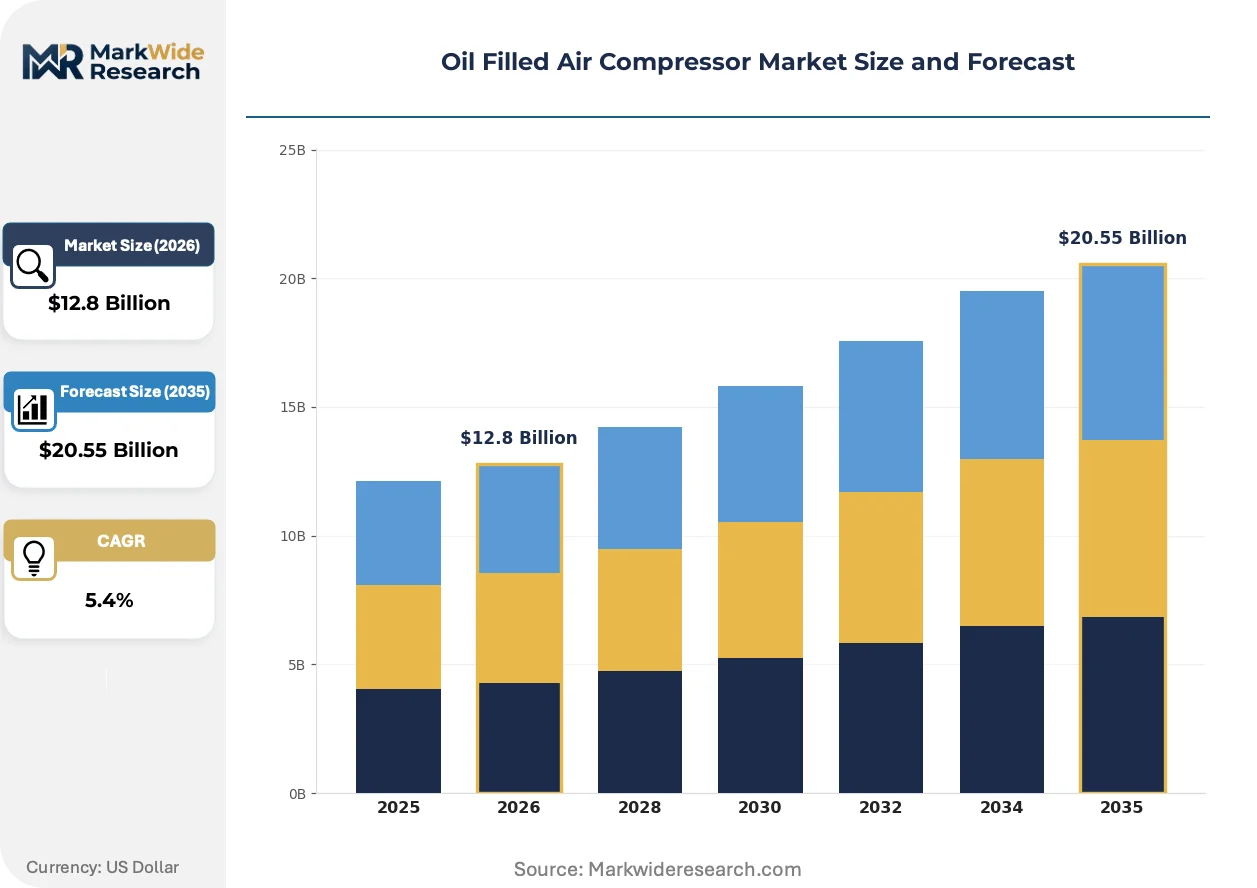
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.55 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reciprocating, Rotary Screw, Centrifugal, Axial, Scroll Technology: Variable Speed Drive, Fixed Speed, Direct Drive, Belt Drive, Oil Lubricated Application: Manufacturing Plants, Construction Sites, Mining Operations, Agricultural Processing, Textile Production End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Facility Maintenance, Equipment Rental Services |
| Companies Covered | Sullair LLC, ELGi Equipment Limited, Atlas Copco AB, BOGE Kompressoren Otto Boge GmbH & Co. KG, Quincy Compressor LLC, Ingersoll Rand Inc., Shanghai Kaishan Compressor Co., Ltd., Kobelco Compressors Americas, LLC, Kaeser Kompressoren SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Filled Air Compressor Market Strategic Shifts & Innovations
Digital compressor monitoring and predictive service models are restructuring aftermarket economics, compressing traditional parts-and-labor revenue while opening recurring software streams.
Permanent magnet synchronous motor technology is supplanting conventional induction drives in mid-range rotary screw systems. Food and pharmaceutical processors are specifying PM-equipped units for their part-load efficiency advantages. The technology is supplanting legacy fixed-speed configurations in facilities running multiple shift patterns, collapsing the total cost of ownership gap that previously favored cheaper induction alternatives.
China's MIIT energy-labeling programs are enforcing compressor performance tiers that filter import eligibility. Domestic procurement pools now exclude units below designated efficiency thresholds, forcing multinational suppliers to localize production or surrender volume. Process industries in the Yangtze River Delta are responding by consolidating fleets under single-source direct-drive contracts to simplify compliance documentation.
Buying committees are unbundling compressor hardware from lifecycle service contracts. Large manufacturing groups are separating capital procurement from energy performance guarantees, pressuring OEMs to compete on kilowatt-hour metrics rather than upfront price. This pattern is most visible in German automotive supplier parks, where shared service centers negotiate fleet-wide compressed air as a utility rather than equipment purchase.
Oil Filled Air Compressor Market Segmentation
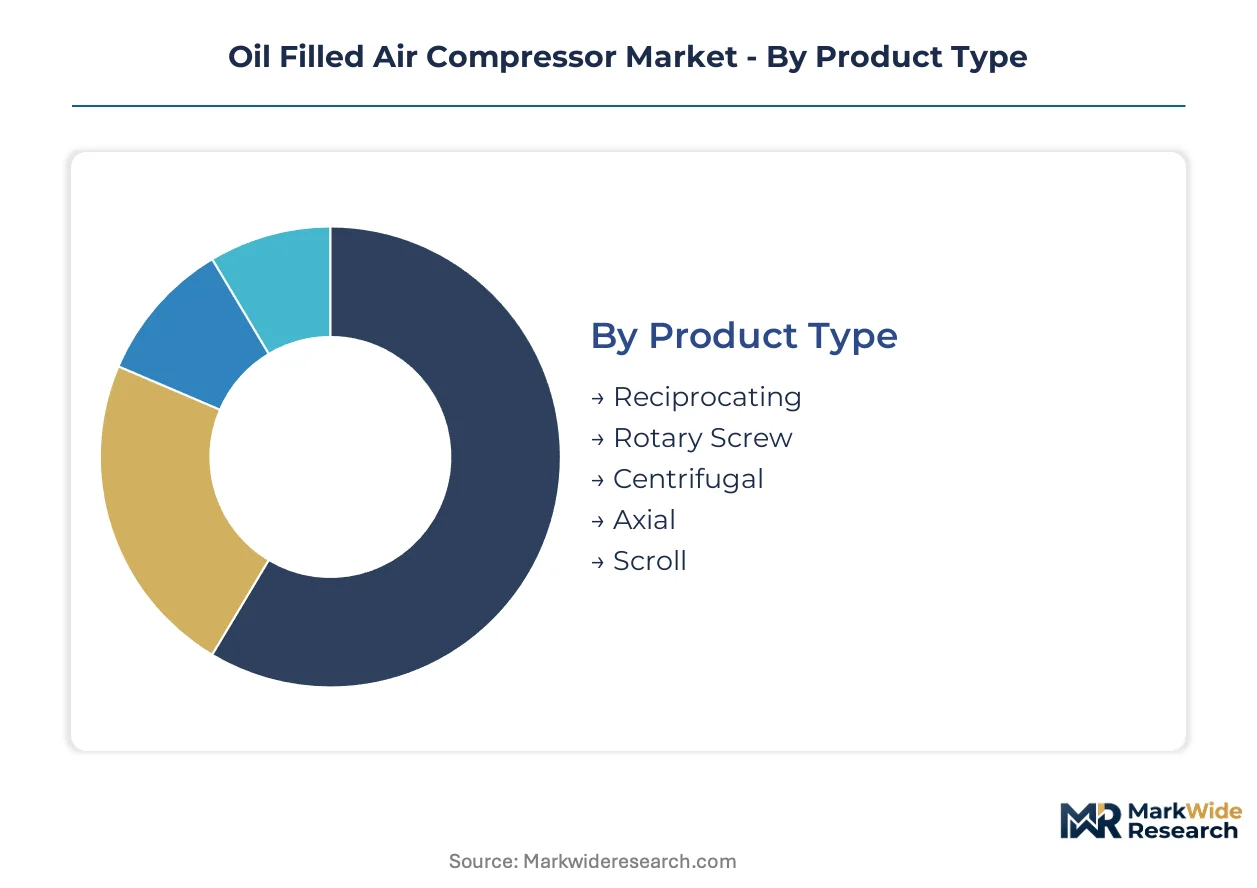
Segmentation in oil filled air compressors reveals how technology choices, duty cycles, and procurement channels partition margin pools. Buyers optimize across capital intensity, energy efficiency mandates, and service accessibility rather than selecting on upfront cost alone.
Product Type:
Margin concentration follows duty-cycle intensity and aftermarket attachment rates rather than unit volume.
- Rotary Screw:These positive-displacement units use intermeshing helical rotors with oil injection for sealing and cooling, achieving continuous-duty operation at 100-200 psig discharge pressures. Demand clusters in China's Yangtze River Delta manufacturing corridors where MIIT energy-labeling programs enforce fleet upgrades toward direct-drive configurations. The segment commands premium pricing through integrated VSD packages that cut electricity consumption by double-digit percentages in 24/7 process plants.
- Reciprocating:Piston-driven compression chambers deliver intermittent-duty output up to 250 psig through single or multi-stage configurations, with oil lubrication reducing ring and cylinder wear. ELGi Equipment Limited dominates India's aftermarket channels with cost-optimized cast iron designs that survive dusty foundry environments and irregular maintenance schedules. The technology retains specification wins in small automotive repair shops and agricultural processing stations where capital constraints override efficiency metrics.
- Centrifugal:Dynamic compression through radial impellers achieves oil-lubricated flows above 500 horsepower, serving high-volume petrochemical and steel mill applications.
- Axial:Multi-stage bladed rotors generate extreme pressure ratios in specialized process gas and refinery hydrogen circulation duties.
- Scroll:Orbiting spiral mechanisms provide oil-lubricated compression for medical and laboratory air systems requiring pulsation-free output.
Rotary Screw holds installed capacity across heavy manufacturing. Reciprocating is rotating up the share rankings in cost-sensitive emerging markets.
Technology:
Technology selection determines energy performance certification tiers and eligibility for public procurement pools.
- Variable Speed Drive:Inverter-controlled motor speed matches compressed air output to real-time demand, eliminating unload losses that plague fixed-speed operation. German automotive OEM lines specify VSD-equipped rotary screw units for robotic welding and paint shop continuity, with load-matched consumption justifying 20-30% electricity savings against legacy induction motor alternatives. The technology faces integration complexity as facility engineers lack cross-training in pneumatic network optimization, delaying commissioning and eroding projected returns.
- Direct Drive:Coupling the compression element directly to the motor shaft eliminates belt maintenance and transmission losses, improving reliability in continuous-duty environments. Kaeser Kompressoren SE sustains specification wins through this configuration in automotive supplier parks where shared service centers negotiate kilowatt-hour performance guarantees rather than equipment purchases.
- Fixed Speed:Constant motor operation at rated RPM provides lowest first cost for intermittent-duty applications with stable demand profiles.
- Belt Drive:Flexible coupling between motor and compression element enables speed ratio adjustment but introduces maintenance burden and efficiency losses.
- Oil Lubricated:Conventional mineral or synthetic lubricant injection remains baseline for general industrial service outside food and pharmaceutical clean rooms.
Direct Drive anchors premium positioning in automotive OEM specifications. Variable Speed Drive is climbing the fastest as electricity costs dominate total ownership economics.
Application:
Application segmentation tracks industrialization intensity and regulatory enforcement geography.
- Manufacturing Plants:Continuous pneumatic power for automation, material handling, and process control dominates compressor deployment by value. India's BIS energy standards are disqualifying legacy belt-drive units from public procurement pools and large industrial tenders, forcing accelerated replacement timelines ahead of regulatory phase-outs. The segment concentrates demand in Vietnam and Indonesia's expanding industrial park zones where established aftermarket service networks remain underdeveloped.
- Construction Sites:Mobile and semi-permanent installations power pneumatic tools, shotcrete application, and drilling operations in infrastructure expansion corridors.
- Mining Operations:Underground and surface extraction sites require explosion-proof configurations with robust filtration for dust-laden intake air.
- Agricultural Processing:Grain handling, irrigation, and livestock operations use smaller reciprocating units with intermittent duty cycles.
- Textile Production:Air-jet weaving and spinning operations demand oil-free or Class 0 certified compressed air to prevent fabric contamination.
Manufacturing Plants holds installed capacity across Asia-Pacific industrial corridors. Textile Production is gaining share fastest as ISO 8573-1 compliance becomes tender prerequisite.
End User:
End user channel structure determines pricing power and service contract attachment.
- Aftermarket Providers:Independent distributors and service contractors dominate India's replacement parts and rebuild market, with ELGi Equipment Limited leveraging cost-optimized reciprocating designs to anchor channel loyalty. The segment captures margin through lubricant and filter consumables rather than unit sales, with compressed air system integration expertise scarce among facility maintenance staff.
- OEMs:Original equipment manufacturers specify compressor subsystems for integrated machinery packages, demanding performance documentation for regulatory compliance.
- Vehicle Assemblers:Automotive production lines negotiate fleet-wide compressed air as utility service with kilowatt-hour guarantees.
- Facility Maintenance:In-house engineering teams manage aging installed base with reactive repair patterns rather than predictive replacement.
- Equipment Rental Services:Short-term deployment models favor portable reciprocating and small rotary screw units with rapid deployment capabilities.
Aftermarket Providers holds installed capacity across India's service infrastructure. Vehicle Assemblers is expanding most quickly as outcome-based procurement models spread from German automotive supplier parks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cast iron and aluminum housing production clusters in eastern China concentrate foundry capacity for compressor manufacturing, creating geographic vulnerability to regional power rationing and environmental compliance shutdowns. Demand dispersion follows industrialization corridors where automotive OEM lines and process manufacturing anchor compressed air infrastructure.
China
Yangtze River Delta manufacturing corridors drive specification wins for direct-drive rotary screw systems serving 24/7 process plants. MIIT energy-labeling programs enforce compressor performance tiers that filter import eligibility and domestic procurement pools. Shanghai and Suzhou industrial parks consolidate fleets under single-source contracts to simplify compliance documentation.
United States
EPA air quality standards and OSHA workplace noise regulations compel fleet replacements across aging manufacturing infrastructure. Automotive supplier parks in Michigan and Ohio negotiate kilowatt-hour performance guarantees rather than equipment purchases. Gulf Coast petrochemical clusters sustain demand for high-horsepower centrifugal configurations.
Germany
EU Ecodesign directives and F-Gas Regulation mandate efficiency benchmarking and refrigerant-compatible lubricant formulations. Baden-Württemberg automotive OEM lines specify VSD-equipped units for robotic welding continuity. Bavarian industrial zones anchor aftermarket service networks for compressed air as utility service models.
India
BIS energy standards disqualify legacy belt-drive units from public procurement pools and large industrial tenders. Maharashtra and Gujarat manufacturing corridors accelerate replacement timelines ahead of regulatory phase-outs. Tamil Nadu textile processors specify Class 0 certified systems as ISO 8573-1 compliance becomes tender prerequisite.
Japan
METI efficiency programs and JIS standards anchor specification requirements for automotive and electronics manufacturing. Kansai region semiconductor fabs drive demand for oil-lubricated scroll systems in laboratory air applications. Chubu industrial corridor maintains installed base of fixed-speed reciprocating units in small-scale metal fabrication.
Oil Filled Air Compressor Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium positioning and volume penetration operate on separate vectors. The vendor base spans multinational engineering conglomerates with integrated VSD portfolios and regional specialists dominating aftermarket channels through cost-optimized cast iron designs. Three archetypes define competitive positioning: direct-drive engineering specialists, reciprocating volume manufacturers, and integrated compressed air service providers. Dominant competitive moves include geographic localization to satisfy MIIT and BIS procurement eligibility, plus unbundling of hardware from lifecycle energy performance guarantees.
Among European-based engineering groups, Atlas Copco AB and Kaeser Kompressoren SE exemplify the direct-drive premium tier, occupying positions where automotive OEM specifications demand continuous-duty reliability. ELGi Equipment Limited represents the cost-optimized reciprocating archetype, anchoring aftermarket channel loyalty in India's dusty foundry environments through cast iron durability. Chinese fabricators including Shanghai Kaishan Compressor Co., Ltd. sit within the domestic procurement tier, leveraging MIIT compliance localization to capture Yangtze River Delta manufacturing corridor demand.
| Leading Market Players |
|---|
| Sullair LLC |
| ELGi Equipment Limited |
| Atlas Copco AB |
| BOGE Kompressoren Otto Boge GmbH & Co. KG |
| Quincy Compressor LLC |
| Ingersoll Rand Inc. |
| Shanghai Kaishan Compressor Co., Ltd. |
| Kobelco Compressors Americas, LLC |
| Kaeser Kompressoren SE |
| Others |
Cost & Logistics Intelligence
Fourteen-week casting lead times for compressor housings concentrate pricing power with eastern Chinese foundries capable of sustaining production through environmental compliance windows. This inventory compression tightens margin flexibility for European and Indian assemblers who cannot absorb input volatility without passing cost through to tender bids.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across oil-lubricated compressor portfolios, separating refrigerant-compatible synthetic formulations from mineral oil baselines. Three-tier pricing structure across premium direct-drive VSD packages, standard fixed-speed rotary screw units, and economy reciprocating configurations reflects certification grade and after-sales bundling intensity. Cost compression in mid-range belt-drive segments is intensifying because India's BIS standards disqualify legacy configurations from public procurement pools. Small automotive repair shops and agricultural processors exhibit highest price sensitivity, while German automotive OEM lines negotiate kilowatt-hour performance guarantees that decouple capital cost from total ownership economics.
Supply Chain Analysis
China and India anchor cast iron and aluminum housing fabrication for compressor manufacturing, with eastern Chinese foundry clusters supplying precision-machined blocks to multinational assembly plants. Production draws from high-purity copper winding wire, rare-earth permanent magnet materials, and synthetic lubricant base stocks. Single-source vulnerability concentrates in rare-earth magnet supply chains tethered to Chinese processing capacity. Distribution runs through OEM direct sales for large manufacturing accounts, independent aftermarket distributors for replacement parts, and equipment rental services for mobile construction deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation of automotive OEM procurement under shared service centers has shifted bargaining power toward buyers who negotiate compressed air as utility service rather than equipment purchase. Fragmentation among India's small-scale manufacturing facilities preserves pockets of supplier leverage in cost-optimized reciprocating segments.
For Market Incumbents: Compound direct-drive engineering credibility through permanent magnet motor integration to defend against oil-free turbo compressor substitution in pharmaceutical clean rooms. Anchor channel control in Yangtze River Delta manufacturing corridors through MIIT-compliant localized assembly. Prioritize ISO 8573-1 Class 0 certification investment to capture dairy processing and beverage bottling premium tiers before validation bottlenecks freeze product launches. For New Entrants and Emerging Players: ISO 8573-1 Class 0 certification fast-track opens specification wins in Tamil Nadu textile processing where compliance has become tender prerequisite. Target Vietnam and Indonesia industrial park expansions lacking established aftermarket service networks for first-mover channel advantages. Deploy Industrial IoT predictive maintenance algorithms as subscription revenue model to decouple service margins from hardware pricing pressure. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance infrastructure play because efficiency mandates across India BIS, China MIIT, and EU Ecodesign create sustained replacement demand regardless of industrial cycle timing. Acquisition target archetype: regional reciprocating specialists with cast iron foundry integration and dense aftermarket service footprints. Watch for MIIT energy-labeling tier upgrades as inflection indicator accelerating domestic procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive casting supply insulates margin from eastern Chinese environmental compliance shutdowns. |
| VSD Technology Platform Standardization | Load-matched energy consumption aligns with German automotive kilowatt-hour performance guarantees. |
| ISO 8573-1 Class 0 Certification Investment | Third-party validation unlocks dairy processing and beverage bottling premium pricing tiers. |
| Industrial IoT Predictive Maintenance Launch | Subscription algorithms transform aftermarket economics from parts-and-labor to recurring software streams. |
| Southeast Asian Channel Expansion | Vietnam and Indonesia industrial park presence captures demand ahead of established service network saturation. |
Research Approach
A spread of perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads converged on the working assumptions driving this analysis. Primary interviews across these stakeholder roles combined with customs trade data, MIIT energy-labeling program disclosures, BIS standard documentation, and SEC manufacturing filings. Bottom-up unit economics triangulated against top-down industrial energy consumption patterns.
Segmentation dimensions modeled include compressor product type, drive technology configuration, application intensity, and end-user channel structure across the projection horizon. CAGRs derived from installed base turnover rates, regulatory compliance timelines, and efficiency technology adoption curves. Forecast inputs incorporate BIS and MIIT phase-out schedules plus VSD retrofit penetration assumptions.
Decision-makers should treat outputs as directional under sustained industrial electricity pricing and stable foundry capacity utilization; material deviation would warrant model refresh. Supply disruption in rare-earth magnet processing or accelerated F-Gas lubricant formulation restrictions could compress technology transition timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Air and Gas Compressor Market
Compressors
Compressor Wheel Market
Compressors
Middle East and Africa Booster Compressor Market
Compressors
Regenerative Blowers Market
Compressors
Axial Compressor Market
Compressors
Liquid Ring Compressors Market
Compressors
Portable Compressor Market
Compressors
Reciprocating Air Compressor Market
Compressors
Asia-Pacific Booster Compressor Market
Compressors
Air Compressor Market
Compressors
Oil and Gas Industry Gas Compressor Market
Compressors
High Speed Blowers Market
Compressors
Europe Compressor Market
Compressors
Root Blower Market
Compressors
Asia-Pacific Compressor Oil Market
Compressors
Positive-Displacement Hydrogen Compressor Market