
 PAG Compressor Oil Market | 2026-2036
PAG Compressor Oil Market Size, Share, and Industry Trends Forecast 2026-2036
PAG Compressor Oil Market Analytics
Aftermarket service revenue is tilting from commodity lubricant sales toward fluid analysis programs and scheduled change-out contracts. ExxonMobil leverages its captive base of industrial accounts to bundle compressor oils with predictive maintenance services. Klüber Lubrication anchors its position through application engineering support for food-grade and high-pressure CO2 compressor systems. FUCHS Petrolub competes on formulation flexibility, maintaining regional blending capacity that reduces lead times for customized viscosity grades.
Polyalkylene glycol compressor oil comprises synthesized alkylene oxide polymers engineered for thermal stability across wide temperature ranges, typically formulated with viscosity indices exceeding 180 and pour points below -40°C to protect rotary screw and reciprocating compressors under extreme operating conditions. The product type dimension shows polyalkylene glycol and synthetic oil formulations capturing margin pools as mineral oil retreats to price-sensitive legacy equipment. Within end users, industrial machinery and HVAC applications lead volume absorption, while refrigeration-driven demand accelerates fastest as ammonia and CO2 systems displace hydrofluorocarbon architectures.
EPA refrigerant management rules under Section 608 constrain compressor oil selection by tying leak repair mandates to compatible lubricant chemistry, while the EU F-Gas Regulation phases down fluorinated gas quotas and redirects specification activity toward lower-GWP refrigerant pairings. China's GB standards for refrigeration safety and lubricant interchangeability add a third compliance layer for multinational suppliers. Stakeholders must monitor how refrigerant transition timelines in each jurisdiction recalibrate product registration priorities and reformulation roadmaps.
Market Dynamics
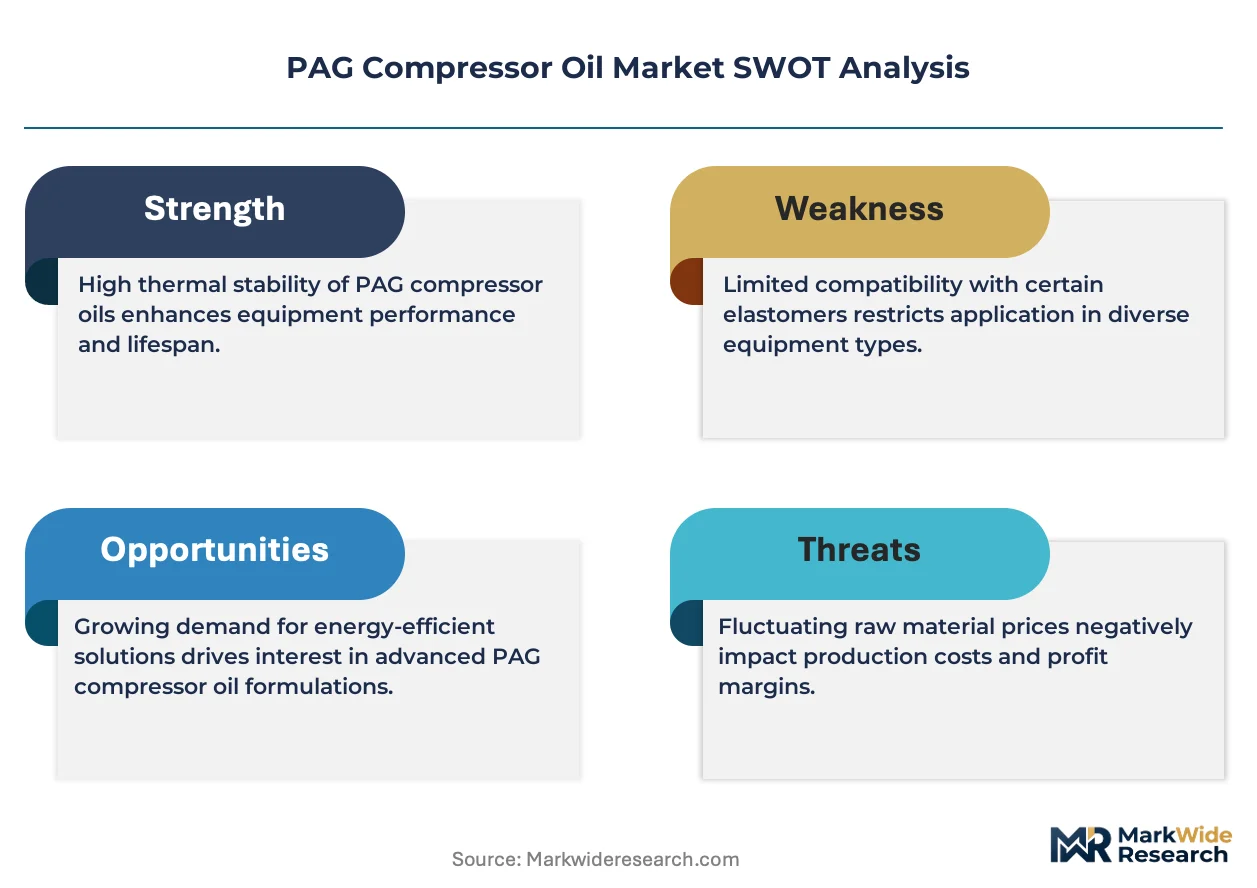
Refrigerant chemistry transitions under EPA Section 608 and the EU F-Gas Regulation are forcing wholesale reformulation of compressor lubricant portfolios, with blenders racing to certify PAG grades compatible with lower-GWP alternatives.
Growth Catalysts
- HVAC Retrofit Cycles:Aging chiller fleets in the United States and Germany require synthetic lubricant upgrades to maintain efficiency under tighter leak-repair mandates.
- EU F-Gas Regulation:Quota reductions on fluorinated gases redirect specification activity toward ammonia and CO2 systems that demand specialized PAG formulations.
- China Cold-Chain Buildout:Refrigerated warehousing and pharmaceutical logistics corridors absorb elevated PAG volumes for screw compressors in temperature-controlled environments.
Market Restraints
- Feedstock Concentration:Ethylene oxide and propylene oxide supply clusters in the US Gulf Coast and Middle East expose blenders to petrochemical price volatility and force majeure risk.
- Technical Limitation:PAG chemistry exhibits limited miscibility with mineral oil residuals, complicating retrofits of legacy R-22 systems without full flushing protocols.
- Regulatory Friction:China's GB standards for lubricant interchangeability create registration bottlenecks that delay product launches by 12-18 months versus OECD timelines.
Strategic Opportunities
- CO2 Transcritical Systems:High-pressure refrigeration architectures in European supermarkets and food processing plants require viscosity-stabilized PAG grades that command formulation premiums.
- India Cold-Chain Incentives:PLI scheme allocations for integrated cold-chain infrastructure create first-mover positioning for synthetic lubricant suppliers in an underpenetrated market.
- Predictive Maintenance Bundling:Fluid analysis programs and scheduled change-out contracts displace spot lubricant sales, locking in multi-year offtake with industrial machinery operators.
Industry Challenges
- Tribology Talent Scarcity:Formulation chemists with expertise in refrigerant-lubricant miscibility and elastomer compatibility command premium compensation and constrain R&D velocity.
- Certification Timeline Compression:OEM approvals for new refrigerant-lubricant pairings require extended compressor durability testing that delays revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PAG Compressor Oil Market |
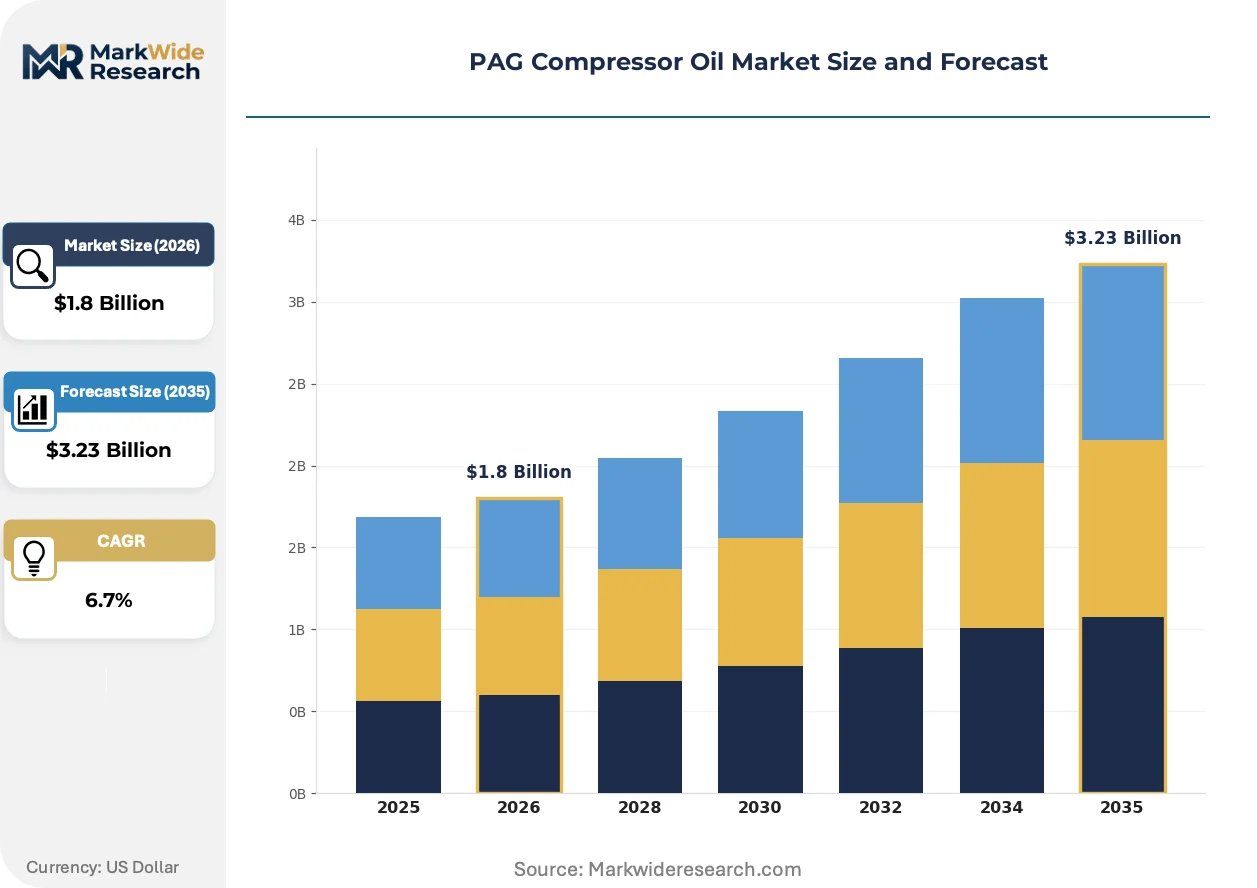
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyalkylene Glycol, Synthetic Oil, Mineral Oil, Biodegradable Oil End User: Automotive, Marine, HVAC, Industrial Machinery Application: Refrigeration, Compressors, Air Conditioning, Heat Pumps Packaging Type: 55-Gallon Drums, Kegs, Pails, Bulk Totes |
| Companies Covered | BASF, Petro-Canada Lubricants, ExxonMobil, AMSOIL, Castrol, Idemitsu Kosan, Klüber Lubrication, Chevron, FUCHS Petrolub, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PAG Compressor Oil Market Evolving Landscape
Digital instrumentation and connected compressor systems are generating real-time lubricant condition data that reshapes how buyers specify, procure, and consume PAG formulations across industrial asset bases.
Smart sensor arrays embedded in rotary screw compressors are digitizing oil analysis by transmitting viscosity degradation, acid number elevation, and moisture ingress metrics directly to maintenance platforms. Food processors and pharmaceutical manufacturers with validated cold-chain requirements are adopting these systems fastest. The resulting data streams compress traditional laboratory analysis cycles and enable condition-based drain intervals that extend oil life.
The EU F-Gas Regulation's stepped quota reductions through 2030 are mandating refrigerant transitions that invalidate incumbent lubricant specifications. Industrial refrigeration contractors in Germany and the Netherlands are stockpiling PAG grades certified for R-513A and R-1234ze pairings ahead of service season peaks. Blenders with pre-registered product portfolios capture specification lock-in before smaller competitors complete compatibility testing.
Fluid-as-a-service contracting is displacing spot lubricant purchases among multi-site industrial operators. ExxonMobil and FUCHS Petrolub are anchoring multi-year agreements that bundle PAG supply with predictive analytics and scheduled change-out labor. This model concentrates most visibly in the United States, where facility managers face EPA refrigerant management audit exposure and prioritize compliance outsourcing over procurement autonomy.
PAG Compressor Oil Market Segmentation
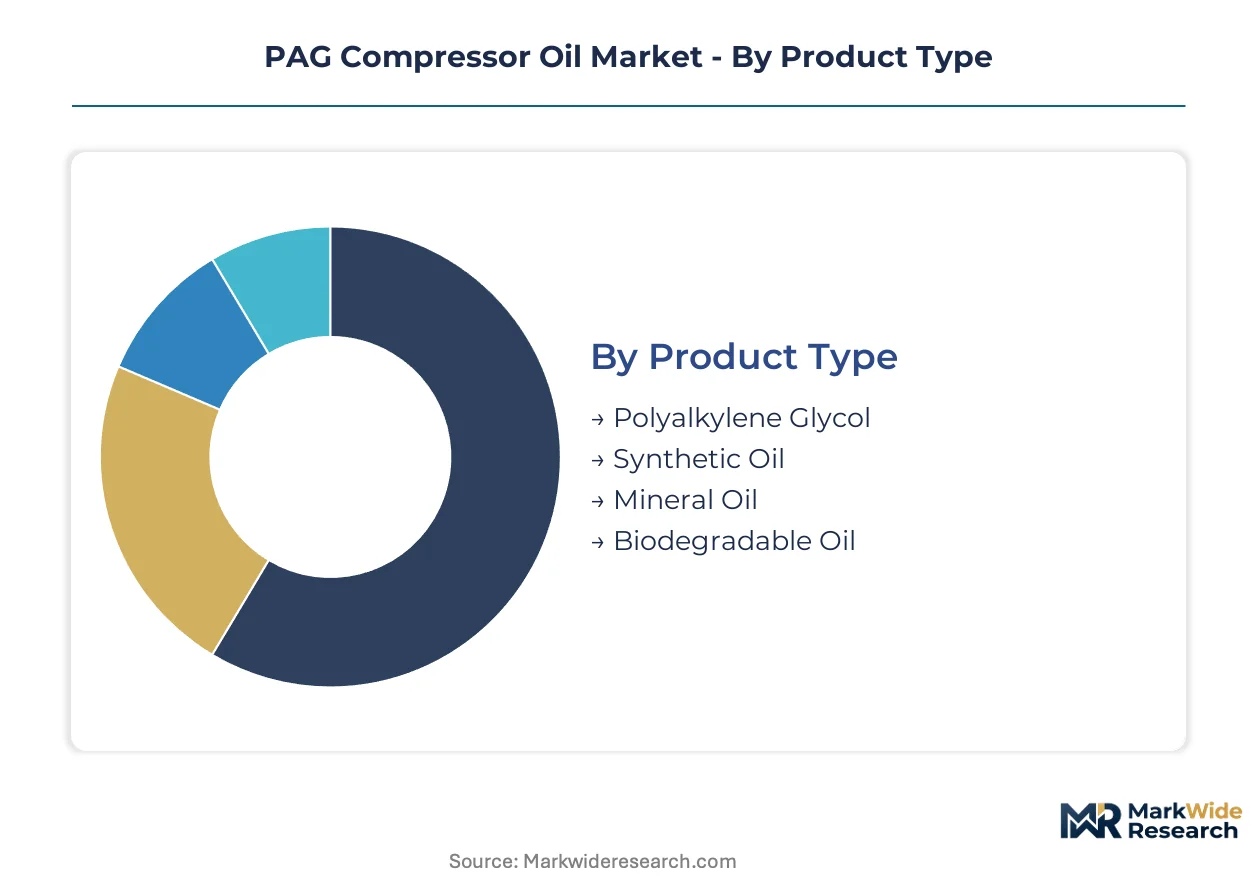
Segmentation in the PAG compressor oil market reveals how refrigerant chemistry transitions and equipment specifications fragment demand across incompatible formulation requirements. Procurement patterns diverge sharply between legacy mineral oil maintenance and synthetic upgrade cycles.
Product Type:
The use-case spectrum spans from price-sensitive legacy equipment maintenance to precision-formulated systems operating under extreme thermal and pressure conditions.
- Polyalkylene Glycol:Synthesized alkylene oxide polymers engineered for thermal stability across wide temperature ranges, typically formulated with viscosity indices exceeding 180. Demand concentrates in China's manufacturing corridor where HVAC retrofit cycles and cold-chain infrastructure buildouts absorb elevated volumes for screw compressors.
- Synthetic Oil:Formulated base stocks including diesters and polyol esters optimized for specific refrigerant pairings. Industrial machinery operators in Germany and the United States are expanding procurement as EPA refrigerant management rules and the EU F-Gas Regulation tighten compliance requirements.
- Mineral Oil:Refined petroleum distillates retaining cost advantage for legacy R-22 and R-134a systems approaching end-of-life.
- Biodegradable Oil:Ester-based formulations targeting environmental discharge scenarios in marine and sensitive ecological zones.
The dominant share belongs to Polyalkylene Glycol, while Synthetic Oil is closing the gap fastest.
End User:
Cost tier stratification separates commodity maintenance accounts from premium specification-driven procurement.
- Industrial Machinery:Rotary screw and reciprocating compressors in continuous-process manufacturing. Food processors and pharmaceutical manufacturers with validated cold-chain requirements are adopting smart sensor arrays fastest.
- HVAC:Chiller fleets and commercial building climate systems. Aging installations in the United States and Germany require synthetic lubricant upgrades to maintain efficiency under tighter leak-repair mandates.
- Automotive:Vehicle air conditioning compressors transitioning refrigerant chemistry.
- Marine:Refrigeration and air conditioning systems aboard cargo vessels and offshore platforms.
Industrial Machinery commands the largest procurement volumes, though HVAC is gaining share fastest through building efficiency retrofit mandates.
Application:
Volume concentration tracks refrigerant transition timelines and equipment replacement cycles across installed bases.
- Refrigeration:Cold-chain warehousing, food processing, and pharmaceutical logistics. The EU F-Gas Regulation's stepped quota reductions are mandating transitions that invalidate incumbent lubricant specifications, with contractors stockpiling certified grades ahead of service peaks.
- Compressors:General industrial compressed air and process gas applications.
- Air Conditioning:Commercial and residential climate control systems.
- Heat Pumps:Heating and cooling systems in building decarbonization programs.
Refrigeration holds the leading position, while Heat Pumps are climbing the fastest on building electrification incentives.
Packaging Type:
Supply concentration in regional blending capacity shapes delivery economics and minimum order structures.
- 55-Gallon Drums:Standard industrial unit for multi-site operators and service contractors. Fluid-as-a-service contracting is displacing spot purchases among these accounts.
- Bulk Totes:Continuous-process manufacturers with centralized lubricant storage and automated dispensing systems.
- Kegs:Smaller maintenance operations and specialty applications.
- Pails:Single-system service calls and emergency replenishment scenarios.
55-Gallon Drums retain the dominant procurement format, yet Bulk Totes are expanding most quickly among multi-site industrial operators consolidating supply agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States absorb specification premiums with minimal price elasticity, while procurement teams in India and Southeast Asia negotiate aggressively on per-liter costs. China's state-mandated infrastructure buildouts create volume concentration that overrides spot-price sensitivity.
United States
Industrial machinery operators in the Midwest and Gulf Coast petrochemical corridors are expanding synthetic formulation procurement as EPA Section 608 refrigerant management rules tighten leak-repair mandates. The EPA's phasedown of hydrofluorocarbons under the AIM Act redirects specification activity toward lower-GWP refrigerant pairings. Houston and Chicago anchor the densest concentrations of screw compressor fleets undergoing lubricant upgrade cycles.
Germany
Food processors and pharmaceutical manufacturers in Bavaria and North Rhine-Westphalia are stockpiling PAG grades certified for CO2 transcritical systems ahead of EU F-Gas Regulation quota reductions. The EU F-Gas Regulation's stepped cuts through 2030 invalidate incumbent lubricant specifications. Industrial refrigeration contractors in the Ruhr Valley and Munich manufacturing belt absorb elevated volumes for ammonia and CO2 compressor retrofits.
China
HVAC retrofit cycles and cold-chain infrastructure buildouts in the Yangtze River Delta and Pearl River Delta absorb elevated PAG volumes for screw compressors in temperature-controlled environments. China's GB standards for refrigeration safety and lubricant interchangeability add compliance layers that delay product launches by 12-18 months versus OECD timelines. Shanghai and Shenzhen manufacturing clusters drive procurement concentration for synthetic formulations.
India
PLI scheme allocations for integrated cold-chain infrastructure create first-mover positioning for synthetic lubricant suppliers in an underpenetrated market. The country's national food safety regulator mandates temperature integrity standards that accelerate pharmaceutical logistics corridor development. Maharashtra and Gujarat cold-chain hubs absorb initial PAG volumes as retrofit cycles begin.
Japan
Precision manufacturing facilities in the Kanto and Kansai regions specify high-viscosity-index PAG formulations for rotary screw compressors operating under extreme thermal conditions. METI's energy efficiency standards for industrial equipment tighten allowable operating tolerances. Tokyo and Osaka industrial clusters prioritize predictive maintenance bundling over spot lubricant purchases.
PAG Compressor Oil Market Competitive Landscape
Capability concentration sits with specialized blenders possessing refrigerant-lubricant miscibility expertise; scale advantage sits with integrated petrochemical majors with captive alkylene oxide feedstock access. The market structures around three tiers: global majors with full synthetic portfolios, regional blenders with formulation flexibility, and niche specialists in food-grade or high-pressure CO2 systems. Strategic moves concentrate on predictive maintenance service bundling and regional blending capacity expansion to compress lead times for customized viscosity grades.
Within the integrated majors tier, ExxonMobil and FUCHS Petrolub exemplify scale-driven positioning through industrial account bases and multi-year fluid-as-a-service contracting. Klüber Lubrication occupies a specialist position anchored in application engineering support. BASF, Idemitsu Kosan, and Petro-Canada Lubricants represent regional-heavy configurations with feedstock integration advantages. Castrol, Chevron, and AMSOIL sit within the diversified lubricant portfolio tier, leveraging cross-product industrial relationships.
| Leading Market Players |
|---|
| BASF |
| Petro-Canada Lubricants |
| ExxonMobil |
| AMSOIL |
| Castrol |
| Idemitsu Kosan |
| Klüber Lubrication |
| Chevron |
| FUCHS Petrolub |
| Others |
Value Network & Pricing Analysis
Feedstock concentration in the US Gulf Coast and Middle East petrochemical corridors exposes blenders to ethylene oxide and propylene oxide price volatility, compressing margin spreads between premium synthetic formulations and commodity mineral oil alternatives while forcing supply chain restructuring toward regional blending capacity.
Pricing Analysis
Aftermarket service revenue from fluid analysis programs and scheduled change-out contracts drives lifetime value more than spot lubricant sales. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified synthetic grades from regional blender formulations and legacy mineral oil maintenance. Pricing pressure stems from China's GB standards registration bottlenecks that delay product launches and extend competitor lead times. Industrial machinery operators in Germany and the United States absorb specification premiums with minimal price elasticity, while procurement teams in India negotiate aggressively on per-liter costs.
Supply Chain Analysis
Export-control regimes on advanced alkylene oxide polymerization catalysts limit technology transfer to regional blenders in India and Southeast Asia. Supply concentrates in the United States, Germany, and China, with feedstock dependencies on ethylene oxide, propylene oxide, and specialized additive packages. Single-source vulnerability runs through catalyst suppliers concentrated in German and Japanese chemical conglomerates. Distribution runs through regional blending facilities that compress lead times for customized viscosity grades demanded by HVAC retrofit contractors and cold-chain infrastructure developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists with expertise in refrigerant-lubricant miscibility and elastomer compatibility command premium compensation, constraining R&D velocity and consolidating advantage with incumbents who have already built specialist teams.
For Market Incumbents: Entrench position by expanding captive alkylene oxide feedstock access through backward integration into petrochemical partnerships, and accelerate certification timelines for CO2 transcritical system formulations before EU F-Gas Regulation quota reductions invalidate incumbent specifications. Defend against emerging regional blenders by locking multi-year fluid-as-a-service contracts with industrial machinery operators facing EPA refrigerant management audit exposure. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated cold-chain infrastructure market by targeting PLI scheme beneficiaries in Maharashtra and Gujarat with economy-tier synthetic formulations. Focus initial go-to-market efforts on pharmaceutical logistics corridors where national food safety regulator mandates accelerate temperature integrity standards. Avoid head-to-head competition with integrated majors in China's manufacturing corridor where state-mandated infrastructure buildouts create volume concentration that overrides spot-price sensitivity. For Investors and Strategic Acquirers: The market sits at a refrigerant-transition phase that favors specialized blenders with pre-registered product portfolios over diversified lubricant portfolios lacking refrigerant-lubricant miscibility expertise. Long-term viability hinges on formulation flexibility for lower-GWP refrigerant pairings rather than scale advantages in mineral oil production. Watch OEM approval timelines for new refrigerant-lubricant pairings as the inflection indicator; extended compressor durability testing delays revenue recognition and separates acquisition targets with established certification libraries from those facing 12-18 month registration gaps.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkylene Oxide Feedstock | Captive supply of ethylene oxide and propylene oxide insulates margin compression from Gulf Coast petrochemical volatility. |
| Regional Blending Capacity Expansion | Localized formulation facilities in Germany and China compress lead times for customized viscosity grades demanded by HVAC contractors. |
| Predictive Maintenance Service Bundling | Fluid analysis programs and scheduled change-out contracts displace spot sales and lock multi-year offtake with industrial operators. |
| CO2 Transcritical System Certification | Pre-registered portfolios for high-pressure refrigeration architectures capture specification lock-in before EU F-Gas quota reductions. |
| Application Engineering Investment | Specialist support for food-grade and ammonia compressor systems anchors premium positioning in pharmaceutical logistics corridors. |
Research Methodology
Cross-validation between primary interviews with formulation chemists, industrial maintenance directors, and HVAC service contractors and secondary sources including customs trade data, SEC filings of integrated petrochemical majors, and refrigeration industry association reports anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down market sizing from alkylene oxide consumption disclosures and compressor equipment installation databases.
Calibration against historical refrigerant transition timelines and lubricant specification change-out cycles shapes the analytical framework across the projection horizon. Segmentation dimensions include product type tier, end-use industry, refrigerant pairing compatibility, and regional regulatory cluster. CAGRs derive from equipment replacement cycle analysis and cold-chain infrastructure investment trajectories, with specific inputs from EPA Section 608 enforcement patterns and EU F-Gas Regulation stepped quota reduction schedules.
Sensitivities concentrate around refrigerant chemistry transition acceleration, feedstock price volatility in ethylene oxide markets, and China's GB standards enforcement intensity. Forecasts reflect assumptions on OEM approval timeline compression and contractor stockpiling behavior ahead of service season peaks. Material shifts in EPA refrigerant management rule enforcement or EU F-Gas Regulation quota reduction schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Stationary Air Compressor Market
Compressors
Turbocompressor Market
Compressors
USA Scroll Compressor Market
Compressors
Centrifugal Air Compressor Market
Compressors
North America Compressor Market
Compressors
Reciprocating Compressor Market
Compressors
Rotary Lobe Compressor Market
Compressors
Compressor Rental Market
Compressors
North America Hydrogen Compressor Market
Compressors
Scroll Compressor Market
Compressors
Compressor Wheel Market
Compressors
Russia Reciprocating Compressor Market
Compressors
Chlorine Compressors Market
Compressors
Positive Displacement Gas Compressor Market
Compressors
Asia-Pacific Compressor Oil Market
Compressors
Booster Compressor Market