
 Ready-To-Eat Food Market | 2026-2036
Ready-To-Eat Food Market Size, Share, and Industry Trends Forecast 2026-2036
Ready-To-Eat Food Market Intelligence
The bundling of main courses with complementary side dishes into single-purchase meal kits is consolidating consumer choice toward value-added convenience. This product strategy simplifies meal planning for busy individuals and families. Nestlé leverages its extensive global distribution network to offer a wide array of ethnic and regional cuisines in this format. In contrast, Conagra Brands specializes in the frozen packaged meals category, focusing on taste and texture preservation through advanced freezing technologies.
Ready-to-eat food refers to commercially prepared food items that are pre-cooked, packaged, and ready for consumption with minimal or no further preparation. These products often utilize technologies like high-pressure processing (HPP) or retort canning to ensure microbial safety and extend shelf life without refrigeration. The primary purpose is to provide immediate, convenient meal solutions. Packaged Meals and Sandwiches currently command the largest share of the market, while Snack Packs, designed for on-the-go consumption, represent the fastest-growing product type.
The regulatory environment is shaped by agencies like the US FDA, which mandates strict food safety and labeling protocols. In Europe, the EFSA governs food additives and allergen declarations, impacting ingredient formulation. Similarly, China's SAMR enforces GB standards for food production and quality control. These regulations collectively influence market access and require manufacturers to adhere to stringent quality and transparency standards. Stakeholders must now navigate the dual challenge of meeting these compliance demands while adapting to consumer preferences for sustainable packaging.
Market Dynamics
The ready-to-eat food market's current structure is defined by the convergence of enabling food technologies, such as high-pressure processing, and a pronounced consumer shift toward health-conscious convenience, particularly within dense urban centers across developing economies.
Growth Catalysts
- Modified Atmosphere Packaging:This technology extends the shelf life and preserves the sensory qualities of perishable ready-meals without requiring freezing or heavy preservatives, thereby expanding distribution reach and reducing food waste for retailers.
- Urban Lifestyle Transformation:Rapid urbanization and rising disposable incomes in countries like India and Vietnam are creating a large consumer base of time-poor office workers who prioritize convenience in meal planning.
- Food Safety Standardization:Regulations like the FSSAI framework in India and GB standards in China, while stringent, build consumer confidence in packaged foods, legitimizing the category and driving adoption away from unorganized food vendors.
Market Restraints
- Input Cost Volatility:Manufacturers face margin pressure from unpredictable price fluctuations in key agricultural commodities, including specific vegetables, proteins, and grains, which are difficult to pass on to price-sensitive consumers.
- Cold Chain Infrastructure Gaps:The requirement for an unbroken cold chain for many fresh and frozen ready-to-eat products presents a significant logistical and cost barrier, especially in emerging markets with underdeveloped infrastructure.
- Regulatory Divergence:Navigating disparate and often conflicting food additive and labeling regulations between major blocs, such as the US FDA and the European EFSA, increases compliance costs and complexity for global brands.
Strategic Opportunities
- Plant-Based and Functional Foods:There is significant white space for ready-to-eat meals specifically formulated for health-conscious niches, such as high-protein, low-carbohydrate, or plant-based options catering to specific dietary lifestyles.
- Direct-to-Consumer (DTC) Models:Subscription-based meal delivery services offer a channel to bypass traditional retail, build direct customer relationships, and gather valuable data on consumer preferences for rapid product development.
- Expansion into Tier-Two Cities:As major metropolitan markets become saturated, significant growth potential exists in the less-penetrated tier-two and tier-three cities of large emerging economies like Brazil and Indonesia.
Industry Challenges
- Packaging Sustainability:Manufacturers face intense pressure from consumers and regulators to transition away from single-use plastics, yet finding food-safe, cost-effective, and scalable sustainable packaging alternatives remains a major technical hurdle. *Sensory Quality at Scale: Maintaining consistent taste, texture, and appearance across millions of units is a persistent operational challenge, particularly for complex, multi-component meals that undergo thermal processing.
- Allergen Management Complexity:The rising prevalence of food allergies requires exceptionally strict production protocols to prevent cross-contamination, adding significant cost and operational complexity to manufacturing processes, governed by rules like those from the EFSA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready-To-Eat Food Market |
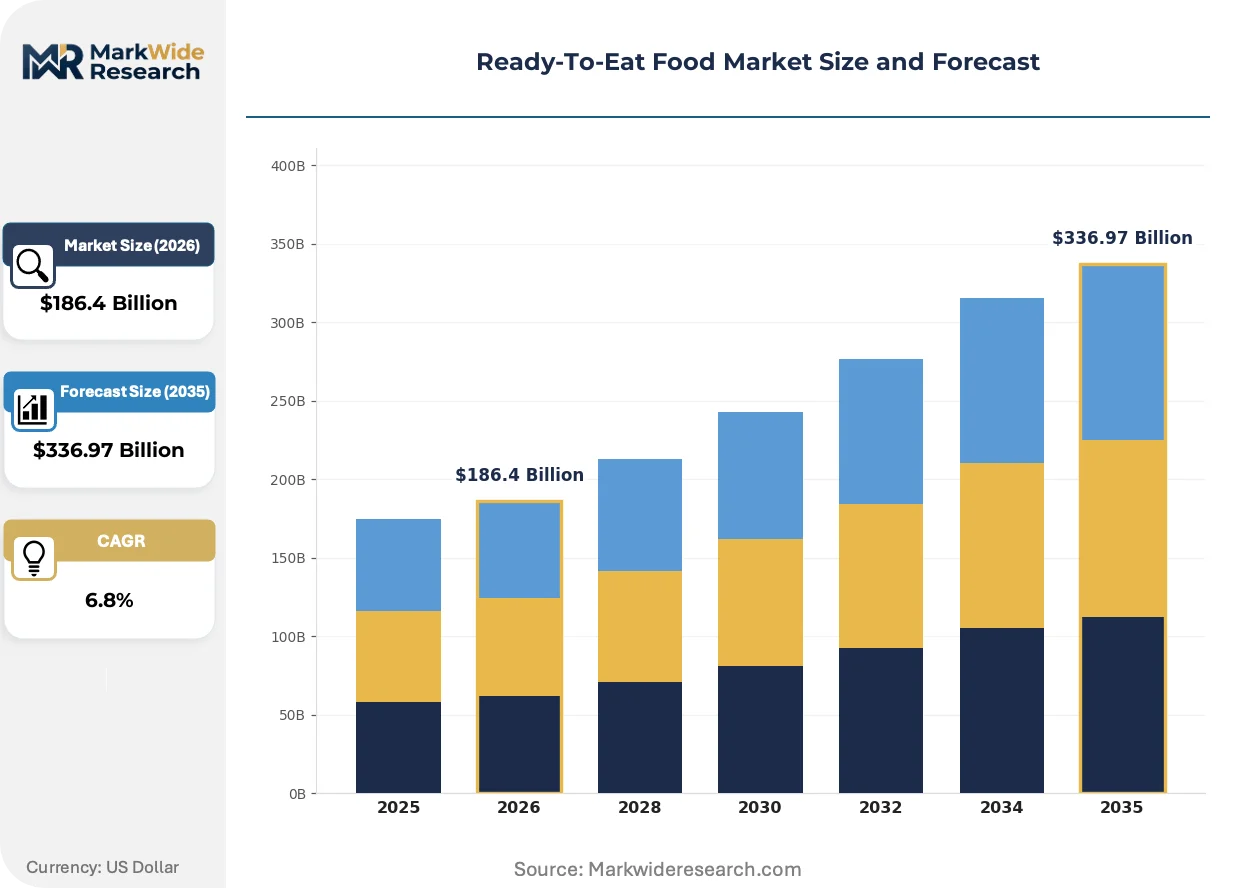
| Market Size in 2026 | $186.4 Billion |
| Market Size in 2035 | $336.97 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packaged Meals, Soups, Salads, Sandwiches, Snack Packs Packaging Type: Plastic Trays, Vacuum Sealed Bags, Tetra Packs, Aluminum Containers, Glass Jars Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Shops, Foodservice Outlets Customer Type: Office Workers, Students, Travelers, Fitness Enthusiasts, Seniors |
| Companies Covered | Nestlé, Conagra Brands, General Mills, The Kraft Heinz Company, Tyson Foods, Nomad Foods, McCain Foods, Unilever, Bakkavor Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready-To-Eat Food Market Strategic Shifts & Innovations
The market is actively responding to the dual demands for heightened convenience and greater nutritional transparency. This is driving innovation in both production-line technology and product formulation, forcing a re-evaluation of traditional recipes and packaging formats to meet new consumer and regulatory expectations.
Advanced vision systems integrated with artificial intelligence are a key technological development. These systems utilize high-speed cameras and machine learning algorithms to identify and remove imperfections or foreign objects on a production line. Food manufacturers are adopting this capability to enhance food safety and product consistency. This technology is automating the quality control process, reducing reliance on manual inspection and enabling higher throughput with lower error rates.
A global regulatory push toward mandatory Front-of-Pack Nutrition Labeling (FOPNL) is impacting product development. Systems like the Nutri-Score in several European countries provide consumers with a simple, color-coded summary of a product's nutritional quality. This forces manufacturers to reformulate products to achieve a better score, often by reducing salt, sugar, and saturated fat content. The packaged meals and snack segments are most affected, redesigning recipes to align with public health goals and consumer preference for healthier options.
Consumer preferences are shifting from generic international meal types toward authentic, hyper-regional cuisines. This trend is disrupting the market for standardized ready-meals, creating demand for products that offer specific and nuanced flavor profiles, such as a Goan vindaloo versus a generic "Indian curry." This is most visible in culturally diverse urban centers in the United Kingdom and Australia, where consumers actively seek novel and authentic food experiences through convenient formats.
Ready-To-Eat Food Market Segmentation
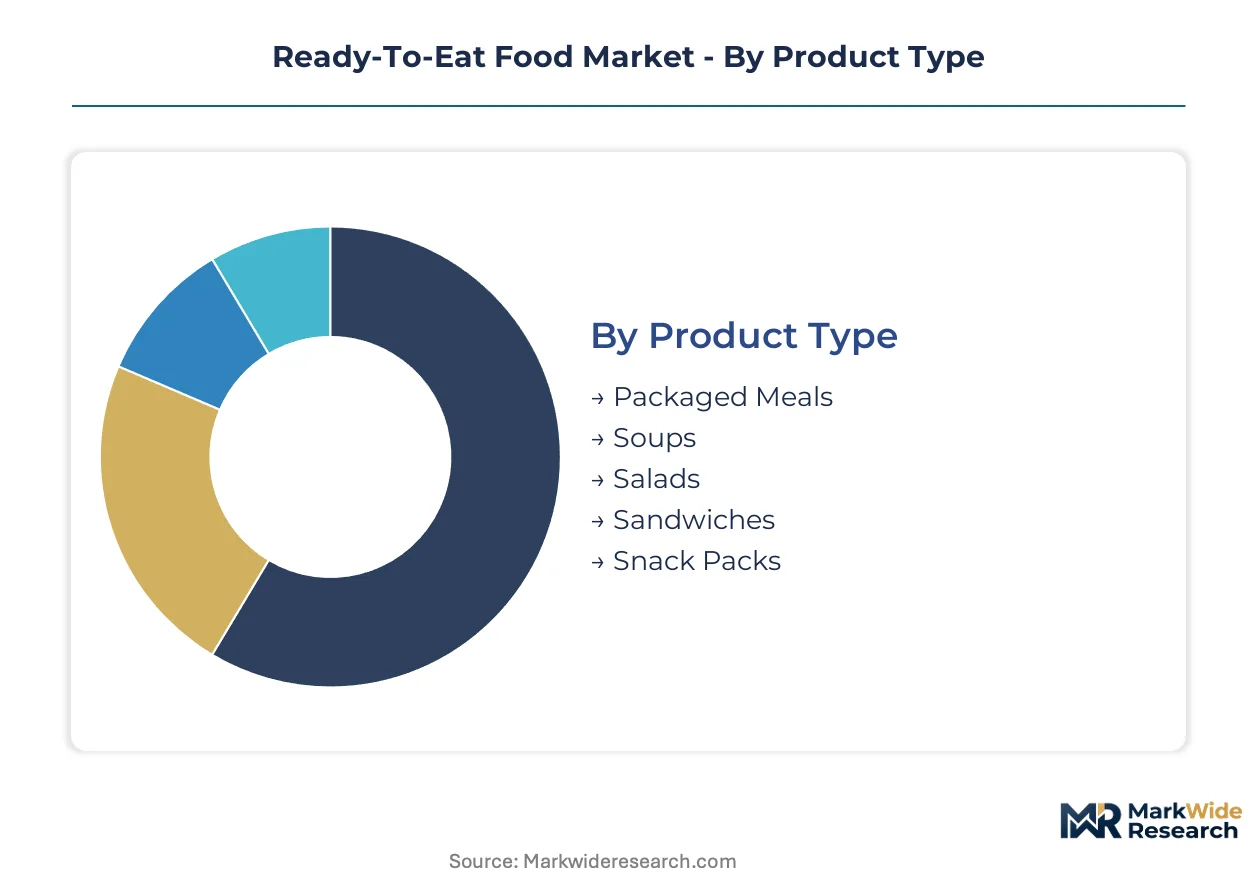
Market segmentation provides a critical framework for understanding the diverse needs of consumers and the varied product offerings within the ready-to-eat food sector. Analyzing these distinct categories allows manufacturers to tailor product development, packaging strategies, and distribution channels to specific market demands. This granular view helps identify underserved niches and areas of high growth potential.
Product Type:
The product type segmentation delineates how ready-to-eat offerings function within consumer diets, from complete meal replacements to supplementary snack components.
- Packaged Meals:These are comprehensive, pre-cooked meals often including a main course and side dishes, requiring minimal heating before consumption. Demand for packaged meals concentrates in urban centers across India and Southeast Asia, driven by the convenience sought by time-constrained office workers.
- Snack Packs:Designed for immediate, on-the-go consumption, snack packs typically include smaller portions of various food items like nuts, cheese, or fruit. These products see rapid expansion in markets with high commuter populations, catering to impulsive purchases and convenience needs.
- Soups:Commercially prepared liquid food items, often requiring heating, available in various flavors and formats.
- Salads:Pre-washed and pre-cut vegetable and protein combinations, typically requiring no heating and ready for immediate consumption.
- Sandwiches:Prepared bread-based items with various fillings, offering a quick and portable meal solution.
Volume placements concentrate in Packaged Meals; Snack Packs show the most rapid growth.
Packaging Type:
Packaging type differentiation often reflects varying cost structures and preservation needs across the product portfolio, impacting shelf life and consumer convenience.
- Plastic Trays:These rigid, often microwaveable containers are widely used for single-serving ready meals, offering convenience and visual appeal. Demand is strong in developed markets where microwave ownership is high, facilitating quick meal preparation.
- Vacuum Sealed Bags:This packaging method removes air to extend shelf life and preserve food quality, commonly used for meats, seafood, and some prepared meals. The technology supports longer distribution distances, particularly for perishable items in regions with developing cold chain infrastructure.
- Tetra Packs:Multi-layered carton packaging primarily used for liquid or semi-liquid ready-to-eat products like soups and broths, offering extended shelf stability.
- Aluminum Containers:Lightweight and recyclable, these containers are suitable for products requiring baking or reheating in conventional ovens.
- Glass Jars:Offering transparency and perceived premium quality, glass jars are used for items like preserves, sauces, and some ready-to-eat desserts.
The adoption patterns in packaging reflect a balance between material cost, shelf-life requirements, and consumer convenience.
Distribution Channel:
The distribution channel segmentation highlights the diverse points of consumer access, influencing product visibility and purchasing patterns across different demographics.
- Supermarkets:Large retail stores offering a wide assortment of products, serving as a primary channel for bulk purchases and regular grocery shopping. Supermarkets maintain significant market share for ready-to-eat foods, leveraging their extensive reach and ability to offer competitive pricing.
- Online Retailers:E-commerce platforms that allow consumers to order ready-to-eat products for home delivery, providing unparalleled convenience. This channel is experiencing substantial expansion in densely populated urban areas, driven by digital adoption and busy consumer lifestyles.
- Convenience Stores:Small retail outlets offering a limited range of everyday items, catering to immediate consumption needs and impulse purchases.
- Specialty Shops:Niche retailers focusing on specific product categories, often emphasizing organic, gourmet, or ethnic ready-to-eat options.
- Foodservice Outlets:Establishments like cafes, delis, and institutional cafeterias that serve ready-to-eat items for on-premises consumption or takeaway.
While traditional retail outlets maintain significant reach, digital platforms are capturing a growing share of consumer transactions.
Customer Type:
The customer type segmentation illustrates specific demographic and lifestyle needs that drive demand for tailored ready-to-eat solutions, reflecting diverse dietary preferences.
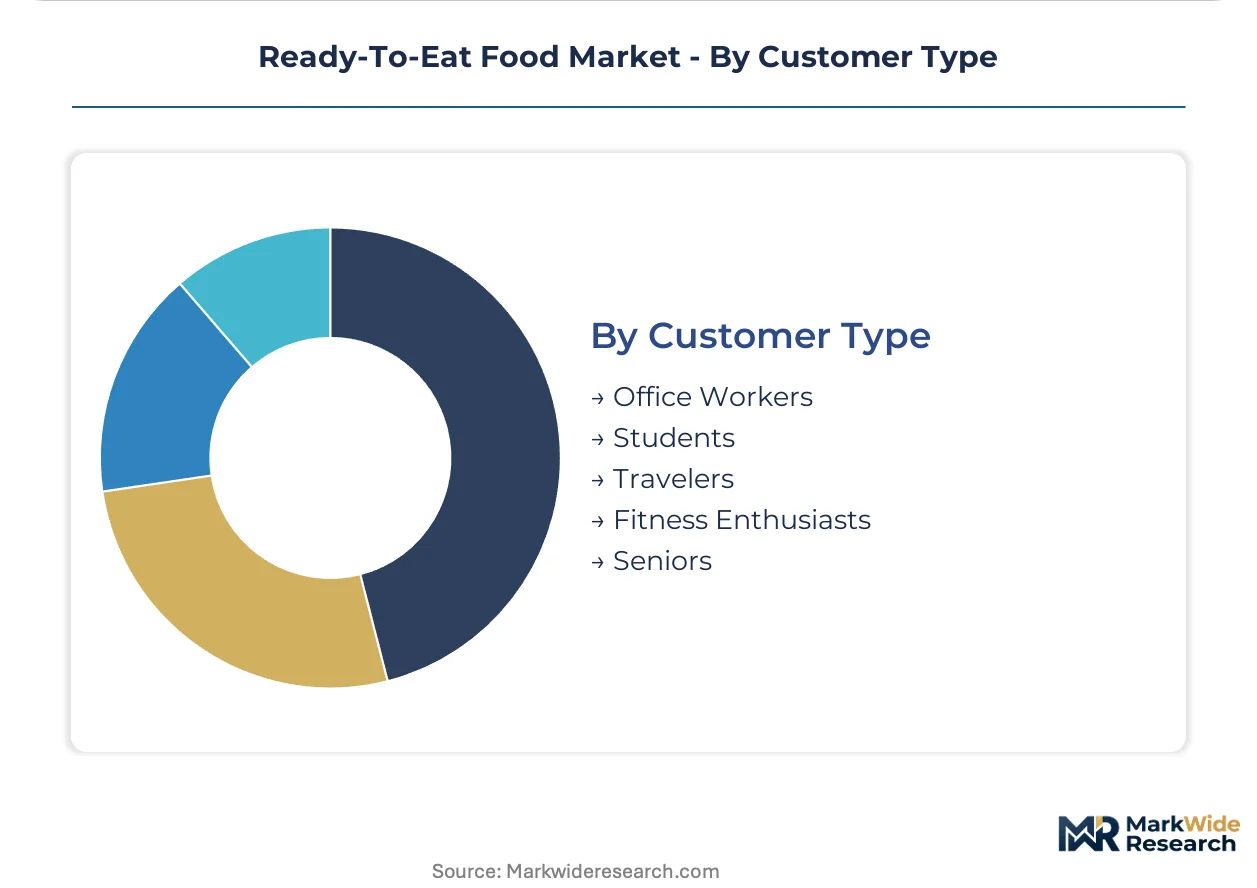
- Office Workers:Individuals employed in office environments who often have limited time for meal preparation during workdays. This segment drives demand for quick, convenient, and portable meal solutions, particularly in major metropolitan areas with high employment density.
- Fitness Enthusiasts:Consumers focused on health and physical well-being, seeking ready-to-eat options that align with specific dietary goals like high protein or low carbohydrate. This niche is growing in markets with rising health consciousness, supported by specialized product formulations.
- Students:Young individuals often living away from home, prioritizing affordable and easy-to-prepare meal options.
- Travelers:Individuals on the move, requiring portable and non-perishable food items suitable for consumption in various settings.
- Seniors:Older adults who may seek easily digestible, nutritionally balanced, and simple-to-prepare meals.
Urban professionals represent a core demographic, yet specialized dietary requirements are opening new avenues for growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global ready-to-eat food consumption significantly outpaces localized production in many developing economies. Manufacturers leverage advanced food technologies to bridge this gap, distributing convenience products across vast distances. This creates a complex interplay between demand centers and supply chain capabilities.
India
India's burgeoning urban population and increasing disposable incomes drive strong demand for convenient packaged meals. The FSSAI framework legitimizes the category, building consumer confidence in commercially prepared foods. Major metropolitan areas like Bengaluru and Mumbai see significant concentration of office workers seeking quick meal solutions.
China
China's rapid urbanization fuels a substantial market for ready-to-eat options, driven by convenience needs. The SAMR enforces stringent GB standards, ensuring product quality and safety for consumers. Cities within the Pearl River Delta, such as Shenzhen, exhibit concentrated demand from busy professionals.
United States
American consumers increasingly seek convenient and health-conscious ready-to-eat meals due to demanding work schedules. The US FDA mandates comprehensive food safety and labeling regulations, impacting product formulations. Urban centers like Chicago and Boston drive demand for high-protein and low-carbohydrate meal kits.
United Kingdom
British consumers in diverse urban centers increasingly demand authentic, hyper-regional ready-to-eat cuisines. EFSA guidelines, relevant across Europe, govern ingredient formulations and allergen declarations. London's multicultural landscape fosters strong demand for specific ethnic and nuanced flavor profiles.
Vietnam
Vietnamese urban centers, particularly Ho Chi Minh City, see rising demand for convenience foods from a growing middle class. The country's national food safety regulations build consumer trust in packaged meal solutions. Hanoi's expanding office worker demographic prioritizes quick and accessible meal options.
Ready-To-Eat Food Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the ready-to-eat food market. This structure combines large-scale generalists with agile innovators targeting niche dietary preferences and health-conscious consumers. Strategic archetypes include global food giants, regional frozen meal specialists, and emerging direct-to-consumer meal kit providers. Capacity expansion through new product lines and portfolio diversification into plant-based options are primary competitive moves.
On the global scale-driven end, Nestlé represents a multinational conglomerate leveraging extensive distribution networks for a wide array of ethnic and regional cuisines. Conagra Brands exemplifies a specialist in the frozen packaged meals category, focusing on taste and texture preservation through advanced freezing technologies. Unilever also occupies a position as a diversified consumer goods giant with significant stakes in the ready-to-eat food sector. These entities anchor different segments of the market, from convenience-driven staples to specialized dietary solutions.
| Leading Market Players |
|---|
| Nestlé |
| Conagra Brands |
| General Mills |
| The Kraft Heinz Company |
| Tyson Foods |
| Nomad Foods |
| McCain Foods |
| Unilever |
| Bakkavor Foods |
| Others |
Cost & Logistics Intelligence
The Bloomberg Agriculture Subindex, tracking key agricultural commodities, directly influences ready-to-eat food production costs, cascading into distinct pricing tiers across the market. This volatility creates margin pressure for manufacturers and affects consumer pricing.
Pricing Analysis
Margin tightening across the standard ready-to-eat food segment reflects persistent input cost volatility for key agricultural commodities like grains and proteins. The dominant pricing model remains per-unit transactional, often stratified across premium, standard, and economy tiers. Price differentiation stems from brand premium and customization levels for specialized dietary needs. Students and seniors typically exhibit the highest price sensitivity, while fitness enthusiasts prioritize specific formulations over cost.
Supply Chain Analysis
Logistics costs are significantly impacted by cold chain infrastructure gaps, particularly in emerging markets like India and Vietnam. Geographic supply concentration for key ingredients like specific vegetables and grains often centers in agricultural hubs across China and India. Raw material dependencies include proteins and various grains, which face unpredictable price fluctuations. A primary supply chain risk is the vulnerability of the cold chain, crucial for perishable products. Distribution runs predominantly through supermarkets and online retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ready-to-eat food market is undergoing a technology-transition phase, with modified atmosphere packaging (MAP) replacing traditional preservation methods to extend shelf life and quality.
For Market Incumbents: To counter intense pressure from consumers and regulators for sustainable packaging, incumbents must accelerate investment in novel, food-safe alternatives. Portfolio diversification into plant-based and functional food options captures health-conscious niches. Strategic capacity additions in high-growth urban centers, particularly in Southeast Asia, strengthen distribution networks. Focusing R&D efforts on advanced vision systems integrated with AI enhances quality control at scale.
For New Entrants and Emerging Players: Launch via direct-to-consumer (DTC) subscription models to bypass traditional retail channels and build direct customer relationships. Target the underpenetrated tier-two cities in large emerging economies like Brazil and Indonesia for expansion. Focus product development on authentic, hyper-regional cuisines to meet demand for nuanced flavor profiles. Capturing the on-the-go snack pack segment with health-conscious formulations offers a strong entry point.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists in India, leveraging their localized supply chains and FSSAI compliance. The long-term viability of the ready-to-eat market remains robust due to an enduring consumer shift toward convenience and health-conscious options. Acquisition targets include firms with advanced modified atmosphere packaging technology or strong plant-based product portfolios. A key signal to watch is the global regulatory alignment on front-of-pack nutrition labeling standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding production capacity in Vietnam enables market penetration in Southeast Asia's growing urban centers. |
| Plant-Based Product Launch | Introducing new plant-based meal kits addresses health-conscious consumer demand and dietary trends. |
| DTC Channel Development | Building direct-to-consumer platforms gathers valuable preference data and bypasses traditional retail. |
| Sustainable Packaging R&D | Investing in eco-friendly packaging solutions meets consumer and regulatory pressure for reduced plastic. |
| AI-Powered Quality Control | Implementing advanced vision systems with AI enhances food safety and product consistency at scale. |
Research Approach
Document review covered government food safety reports, company annual filings, and academic studies, complemented by interviews with industry stakeholders. Primary research involved discussions with food technologists, supply chain managers, brand managers, and retail buyers across global markets. Secondary data sources included US FDA reports, EFSA guidelines, China's SAMR GB standards, and Nielsen retail audit data. This approach facilitated both bottom-up and top-down triangulation of market insights.
Quantitative market projections were developed using a robust analytical framework across the analysis window. The model integrated segmentation dimensions including product type, packaging type, distribution channel, customer type, and regional regulatory frameworks. Compound annual growth rates were derived by extrapolating historical growth trends and incorporating anticipated market dynamics. Key industry-specific inputs included urbanization rates and disposable income growth in emerging economies.
Commodity price volatility, regulatory divergence, and sustainable packaging innovation are the dominant revision risks for market forecasts. These projections reflect assumptions regarding future economic conditions and technological advancements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Canned Legumes Market
Packaged Foods
Packaged Food Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Freekeh Market
Packaged Foods
Reduced Fat Packaged Food Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Packaged Corn on the Cob Market
Packaged Foods
Morning Goods Market
Packaged Foods
Club Store Packs Market
Packaged Foods
Bangladesh Instant Noodles Market
Packaged Foods
Wet Pet Food Market
Packaged Foods
Japan Packaged Food Products Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
Dehydrated and Dried Beans Market
Packaged Foods
Canned Soup Market
Packaged Foods
Pasta and Noodles Market