
 Frozen French Fries Market | 2026-2036
Frozen French Fries Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen French Fries Market Analytics
Flash-freezing and precision-cutting automation is fragmenting production economics across the frozen french fries value chain. McCain Foods Limited leverages its vertically integrated seed-to-freezer network to sustain cost leadership in North American contract foodservice. Lamb Weston Holdings Inc anchors its competitive position through dedicated processing capacity aligned with quick-service restaurant specifications. J.R. Simplot Company differentiates via proprietary potato varieties bred for specific fry textures and oil-absorption profiles.
Frozen french fries are par-fried potato strips, typically blanched at 80–85°C then flash-fried at 170–190°C before rapid freezing to −18°C, engineered for consistent texture and extended shelf stability in commercial and home kitchens. The regular cut segment dominates volume through its compatibility with diverse frying equipment and menu applications across quick-service and casual dining channels. Shoestring formats are capturing share in fast-casual and delivery-optimized operations where faster cook times reduce throughput pressure. The bulk packaging category serves institutional foodservice and quick-service restaurant commissaries, while branded retail pouches compete on convenience and portion control in supermarket channels.
The FDA enforces nutrition labeling and pathogen-control standards for frozen potato products under FSMA preventive controls, while the USDA Agricultural Marketing Service grades raw potato inputs for processing quality. The EU Green Deal's Farm to Fork strategy pressures European processors to document carbon intensity and water stewardship across agricultural sourcing. EFSA guidance on acrylamide mitigation in fried foods is reshaping frying protocols and raw-material selection criteria. Stakeholders must monitor how divergent trans-Atlantic regulatory timelines on clean-label thresholds and Scope 3 emissions disclosure will reshape sourcing geography and capital deployment priorities.
Market Dynamics
Flash-freezing automation and precision-cutting robotics are compressing production economics across the frozen french fries value chain, forcing mid-scale processors to consolidate or exit as capital requirements rise.
Growth Catalysts
- Quick-service restaurant westernization in Southeast Asia:Chains across Indonesia, Vietnam, and the Philippines are expanding frozen potato procurement as local menus adopt Western formats and cold-chain infrastructure matures.
- FSMA preventive controls:The FDA's updated pathogen-control standards for frozen potato products are accelerating facility upgrades that improve throughput consistency and reduce spoilage rates.
- Precision agriculture adoption:Potato processors are deploying sensor-guided irrigation and predictive yield modeling to secure uniform tuber sizing for automated cutting lines.
Market Restraints
- Input cost volatility in edible oils:Sunflower and palm oil price swings directly compress fryer-margin economics for processors lacking long-term supply contracts.
- Supply concentration in specialized fryer equipment:A handful of European and North American manufacturers dominate high-capacity continuous fryer systems, creating procurement bottlenecks for capacity expansions.
- Acrylamide mitigation technical limits:EFSA guidance on reducing acrylamide in fried foods has pushed processors toward lower-temperature frying protocols that extend cook times and reduce line throughput.
Strategic Opportunities
- Underpenetrated cold-chain expansion in Indonesia:Provincial cities outside Jakarta and Surabaya lack frozen distribution density, creating first-mover advantage for processors establishing regional blast-freezing depots.
- Air-fryer optimized product formats:Shoestring and crinkle-cut varieties engineered for rapid crisping in domestic air-fryer appliances are capturing shelf space in retail channels.
- EU Green Deal Farm to Fork carbon documentation:Processors investing in Scope 3 emissions tracking across agricultural sourcing will secure preferential placement with European quick-service restaurant chains facing disclosure mandates.
Industry Challenges
- Automation engineering talent scarcity:Facilities struggle to recruit technicians capable of maintaining vision-guided cutting systems and cryogenic freezing tunnels.
- Legacy ERP integration with IoT sensor networks:Real-time fryer temperature and moisture monitoring systems require costly middleware development to interface with established inventory management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen French Fries Market |
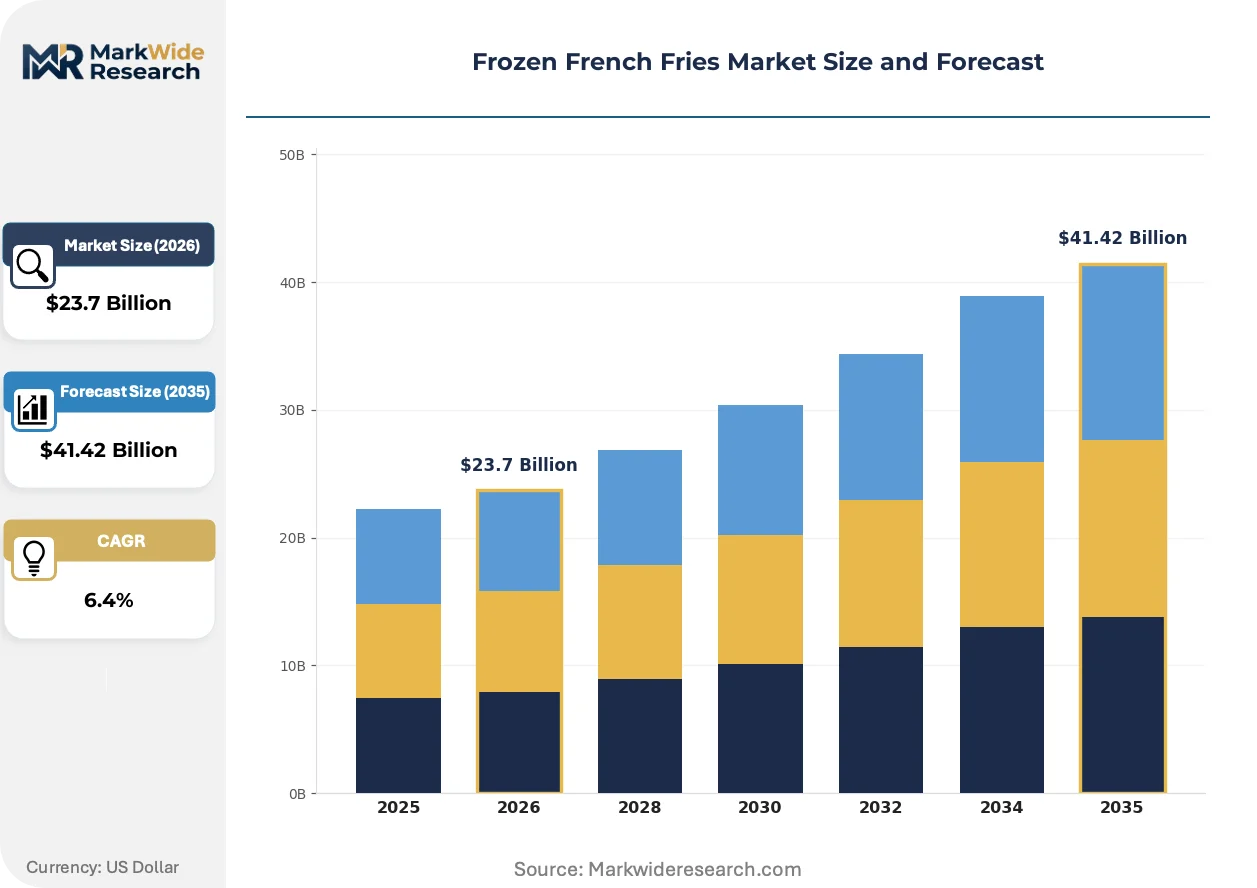
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $41.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Crinkle Cut, Shoestring, Waffle End User: Restaurants, Fast Food Chains, Retail, Food Service Packaging Type: Bags, Boxes, Bulk, Pouches Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Direct Sales |
| Companies Covered | McCain Foods Limited, Lamb Weston Holdings Inc, J.R. Simplot Company, Aviko B.V., Farm Frites International B.V., Cavendish Farms, Agristo NV, The Kraft Heinz Co, Bart's Potato Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen French Fries Market Evolving Landscape
Processing technology and regulatory disclosure requirements are converging to reshape how frozen french fries are manufactured, labeled, and procured across foodservice and retail channels.
High-speed optical sorting systems equipped with hyperspectral imaging are replacing manual defect removal on processing lines. Quick-service restaurant commissaries and large-scale foodservice distributors are adopting these systems at accelerating rates. Human inspection stations are rendering obsolete as labor costs rise and consistency demands tighten.
The EU Green Deal's Farm to Fork strategy is mandating documented carbon intensity and water stewardship across agricultural supply chains. European processors must now trace emissions from seed selection through freezing, reshaping supplier qualification criteria. Frozen potato products destined for EU quick-service restaurant chains face the most stringent verification timelines.
Direct procurement relationships between quick-service restaurant chains and processors are displacing traditional foodservice distributor intermediaries. Chains are negotiating volume commitments in exchange for dedicated processing capacity and customized cut specifications. This pattern is most visible in Southeast Asia where Western fast-food expansion outpaces mature distribution infrastructure.
Frozen French Fries Market Segmentation
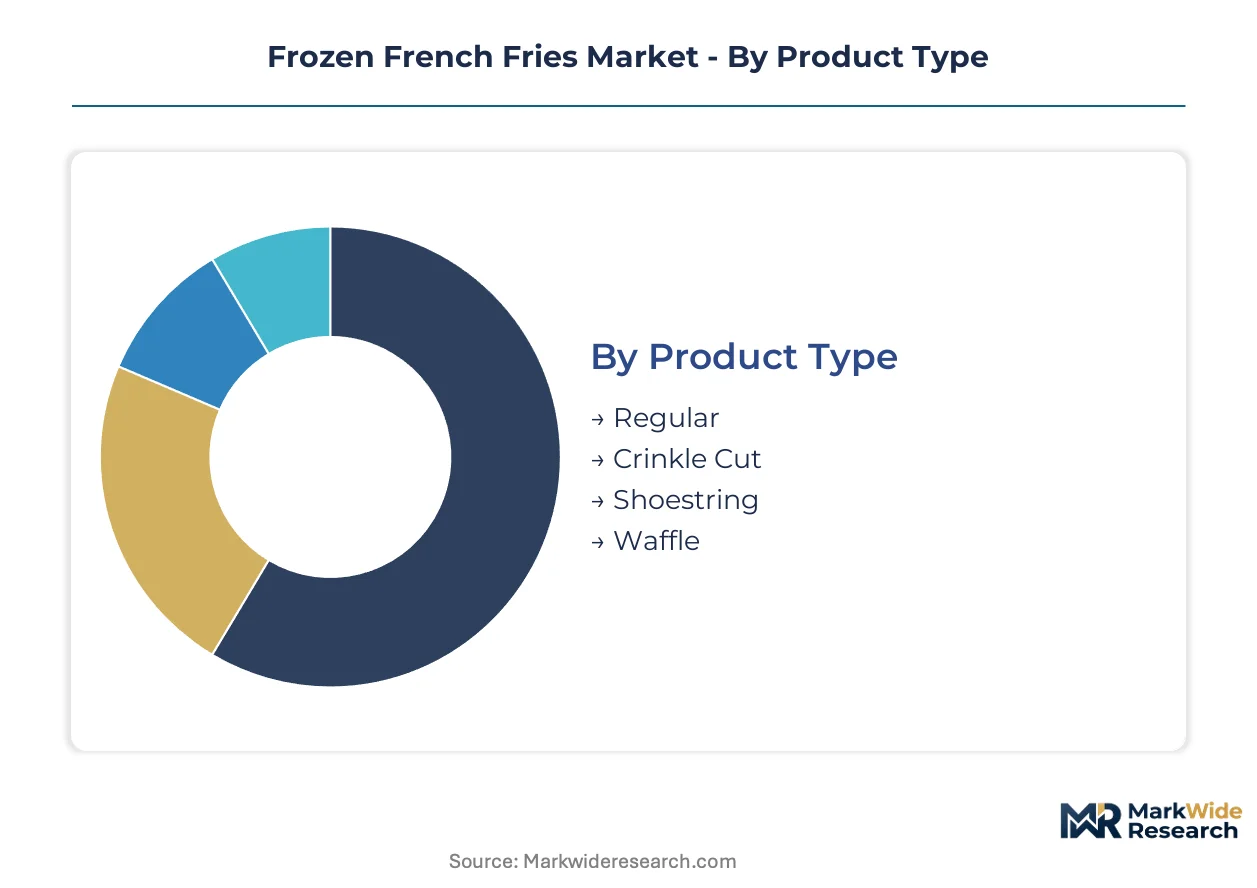
Segmentation in frozen french fries reveals how processing specifications, packaging economics, and channel access determine profitability across distinct buyer workflows. Cut geometry and thermal performance requirements vary sharply between quick-service commissaries and home air-fryer usage.
Product Type:
Cut specifications span a functional spectrum from high-volume frying efficiency to textured mouthfeel differentiation in premium casual dining.
- Regular:Straight-cut strips with uniform cross-section optimize throughput in continuous fryer systems. Quick-service chains in Indonesia and Vietnam specify this format for compatibility with automated salting and bagging equipment.
- Shoestring:Thin-cut profiles reduce cook times by 30-40% versus standard cuts, aligning with delivery-optimized operations where speed determines customer satisfaction scores. Fast-casual chains across the Philippines are converting fryer lines to accommodate this format.
- Crinkle Cut:Wavy-edge geometry increases surface area for crisping while maintaining structural integrity during transport from central kitchens.
- Waffle:Grid-cut patterns target premium positioning in casual dining and retail novelty segments where plate presentation justifies higher price points.
The dominant share belongs to Regular, while Shoestring is closing the gap fastest.
End User:
Buyer concentration varies by order frequency, specification tolerance, and contract duration across institutional and consumer-facing channels.
- Fast Food Chains:Volume buyers negotiate dedicated processing capacity with precise texture and oil-absorption specifications. Chains expanding across Southeast Asia require suppliers to maintain blast-freezing depots within 200 kilometers of regional distribution centers.
- Restaurants:Independent operators prioritize flexibility in portion sizing and delivery frequency over price optimization, accepting modest premiums for smaller case quantities.
- Food Service:Institutional buyers such as school districts and hospital systems emphasize shelf stability and nutritional compliance under FDA labeling mandates.
- Retail:Supermarket and e-commerce channels compete on convenience formats, driving demand for resealable pouches and air-fryer optimized cooking instructions.
Fast Food Chains command the largest procurement volumes, though Retail is expanding most quickly as home cooking appliance penetration deepens.
Packaging Type:
Packaging economics separate high-velocity institutional flows from value-added consumer convenience.
- Bulk:Unbranded poly-lined totes serve quick-service commissaries and institutional foodservice with minimal handling overhead. Cold-chain infrastructure in provincial Indonesian cities outside Jakarta favors this format for cost-efficient distribution.
- Pouches:Resealable retail bags with high-barrier films extend home freezer shelf life while enabling portion control. Air-fryer cooking instructions printed on packaging are becoming standard for this format.
- Bags:Intermediate sizing targets small-restaurant and catering segments requiring mobility without full bulk commitment.
- Boxes:Rigid corrugated formats protect product integrity in e-commerce fulfillment where last-mile handling stress exceeds retail distribution.
Bulk maintains volume leadership, though Pouches are gaining share fastest as retail channel expansion outpaces foodservice growth in emerging markets.
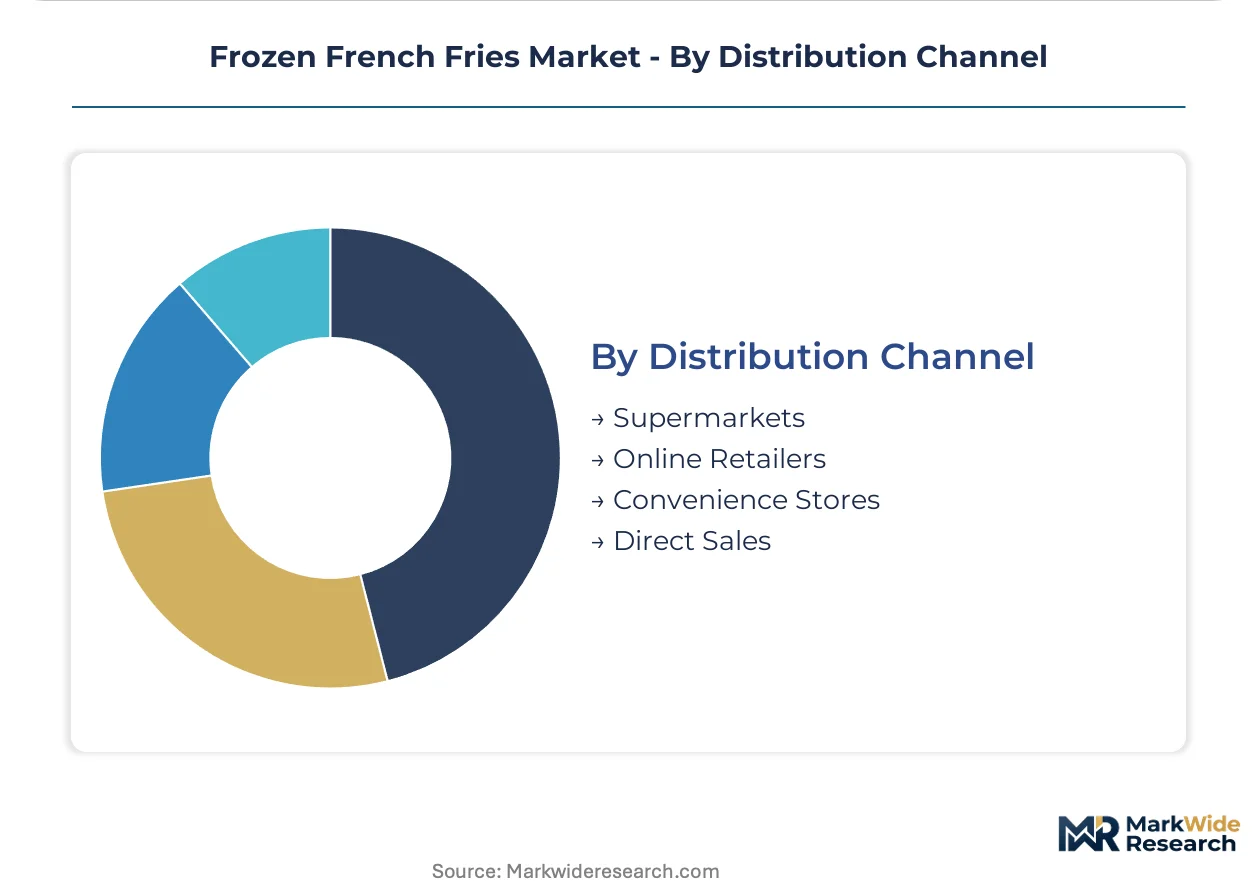
Distribution Channel:
Channel selection reflects cold-chain maturity and buyer preference for direct procurement versus intermediary relationships.
- Direct Sales:Quick-service chains in Southeast Asia are bypassing traditional distributors to negotiate volume commitments directly with processors, securing customized cut specifications and dedicated capacity.
- Supermarkets:Brick-and-retail grocers compete on private-label placement and promotional pricing, requiring suppliers to maintain regional warehouse inventory positions.
- Online Retailers:E-commerce platforms demand packaging formats optimized for parcel shipping, including insulated box liners and dry-ice compatibility for home delivery.
- Convenience Stores:Small-format retail in urban Vietnam and the Philippines favors single-serve and small-family pack sizes for immediate consumption.
Direct Sales captures the highest value per ton, while Online Retailers are climbing the fastest as delivery infrastructure matures in secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant chains in Indonesia, Vietnam, and the Philippines are driving procurement volumes as cold-chain infrastructure matures in secondary cities. Buyers in these markets negotiate directly with processors for dedicated capacity and customized cut specifications.
Indonesia
Western fast-food expansion in Surabaya and Bandung is outpacing frozen distribution density, creating first-mover opportunities for regional blast-freezing depots. The country's national food safety agency enforces pathogen-control standards aligned with international import requirements. Provincial cities outside Jakarta favor bulk poly-lined totes for cost-efficient distribution to emerging quick-service commissaries.
Vietnam
Urban convenience stores in Ho Chi Minh City and Hanoi are accelerating demand for single-serve and small-family pack sizes. The Ministry of Health implements nutritional labeling mandates for prepared foods sold through modern retail channels. Da Nang and Can Tho are emerging as cold-chain consolidation points for Mekong Delta potato sourcing.
Philippines
Fast-casual chains are converting fryer lines to accommodate shoestring formats that reduce cook times for delivery-optimized operations. The Food and Drug Administration monitors acrylamide levels in fried products under processed food safety protocols. Cebu and Davao are building out freezer capacity to support quick-service restaurant growth outside Metro Manila.
United States
Contract foodservice buyers leverage dedicated processing capacity with precise texture and oil-absorption specifications. The FDA's updated Nutrition Facts labeling requirements for prepared foods are pressuring reformulation toward reduced sodium and trans-fat profiles. Idaho and Washington potato-growing regions supply vertically integrated processors with proprietary varieties bred for specific fry performance.
Netherlands
European quick-service restaurant chains face the EU Green Deal's Farm to Fork verification timelines for carbon intensity documentation. The EFSA guides acrylamide mitigation protocols that reshape frying temperatures and raw-material selection. Rotterdam and Amsterdam anchor distribution networks serving Northern European markets with stringent Scope 3 emissions disclosure requirements.
Frozen French Fries Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The market structure concentrates around vertically integrated seed-to-freezer networks and dedicated processing specialists. Three archetypes dominate: backward-integrated agricultural processors, equipment-aligned capacity specialists, and proprietary variety breeders. Competitive moves center on direct procurement relationships displacing distributor intermediaries, and precision agriculture investments securing uniform tuber sizing for automated lines.
Within the integrated processor tier, McCain Foods Limited and Lamb Weston Holdings Inc exemplify channel-controlling positions through captive supply networks and dedicated capacity alignment. J.R. Simplot Company occupies a specialist position emphasizing proprietary breeding programs. These three entities represent distinct competitive vectors: agricultural integration at scale, equipment-locked processing commitment, and germplasm-controlled product differentiation.
| Leading Market Players |
|---|
| McCain Foods Limited |
| Lamb Weston Holdings Inc |
| J.R. Simplot Company |
| Aviko B.V. |
| Farm Frites International B.V. |
| Cavendish Farms |
| Agristo NV |
| The Kraft Heinz Co |
| Bart's Potato Company |
| Others |
Value Network & Pricing Analysis
Undercapacity in Southeast Asian blast-freezing infrastructure drives divergent pricing behavior: processors with captive cold-chain assets extract premiums from quick-service chains desperate for supply security, while spot-market buyers absorb volatility from Indonesian provincial distribution gaps.
Pricing Analysis
Cost-plus contracts indexed to edible oil futures dominate procurement between North American processors and quick-service chains, insulating fryer-margin economics from sunflower and palm oil price swings. Price differentiation hinges on volume scale and dedicated capacity allocation, with institutional foodservice buyers commanding standard tiers and retail pouch formats carrying convenience premiums. Pricing pressure intensifies downward in bulk totes serving Indonesian provincial cities where local cold-chain gaps force spot-market sourcing. Fast-food chains exhibit lowest price sensitivity due to menu-standardization requirements, while independent restaurants negotiate aggressively on case quantities.
Supply Chain Analysis
Export-control restrictions on high-capacity continuous fryer systems from European and North American manufacturers constrain capacity expansion timelines for Southeast Asian processors seeking to capture westernizing quick-service demand. Supply concentrates in the United States, the Netherlands, and Belgium for specialized processing equipment and germplasm, while raw potato sourcing draws from Idaho, Washington, and the Netherlands' seed potato networks. Single-source vulnerability in fryer equipment procurement creates procurement bottlenecks during facility upgrades. Distribution runs through direct sales relationships displacing traditional foodservice intermediaries, particularly in Indonesia, Vietnam, and the Philippines where chains negotiate volume commitments for customized cut specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as air-fryer optimized formats and provincial Indonesian cold-chain gaps create viable entry niches beneath integrated processor dominance.
For Market Incumbents: Pre-empt specialist encroachment by locking in dedicated processing capacity with expanding Southeast Asian quick-service chains through multi-year volume commitments. Defend margin position by backward integration into precision agriculture deployments securing uniform tuber sizing for automated cutting lines, neutralizing the automation engineering talent scarcity threatening throughput consistency. For New Entrants and Emerging Players: Establish a beachhead in air-fryer optimized shoestring and crinkle-cut retail pouches where incumbent focus on foodservice bulk leaves shelf space contested. Target provincial Indonesian cities outside Jakarta and Surabaya with regional blast-freezing depots capturing first-mover advantage before cold-chain density matures. Pursue direct procurement relationships with fast-casual Philippine chains converting fryer lines to delivery-optimized formats. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cryogenic freezing tunnel and vision-guided cutting system deployments, favoring scaled operators with existing automation engineering benches. Long-term viability over the next decade rests on Scope 3 emissions tracking capabilities securing preferential placement with European quick-service chains facing EU Green Deal disclosure mandates. Monitor EFSA acrylamide mitigation protocol revisions as inflection signals for frying temperature adjustments that reshape line throughput economics.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Deployment | Sensor-guided irrigation secures uniform tuber sizing for automated cutting lines at Lamb Weston and McCain facilities. |
| Regional Blast-Freezing Depot Buildout | Provincial Indonesian cities outside Jakarta lack frozen distribution density, creating first-mover capture opportunities. |
| Air-Fryer Optimized Product Development | Shoestring varieties engineered for rapid crisping capture expanding retail shelf space in supermarket channels. |
| Scope 3 Emissions Tracking Investment | Carbon documentation across agricultural sourcing secures preferential placement with European quick-service chains. |
| Direct Procurement Relationship Negotiation | Volume commitments with Southeast Asian chains displace traditional foodservice distributor intermediaries. |
Research Methodology
The analysis maps cut specification segments, packaging format tiers, and distribution channel structures, each validated through plant managers at processing facilities, procurement leads at quick-service chains, cold-chain logistics operators, and retail category buyers. Primary interviews triangulate with secondary sources including FDA FSMA guidance documents, USDA Agricultural Marketing Service grading standards, EU Green Deal Farm to Fork strategy papers, EFSA acrylamide mitigation guidance, and SEC 10-K filings from publicly traded processors. Bottom-up volume modeling across individual facility capacities reconciles with top-down demand aggregation from quick-service restaurant expansion announcements.
Assumptions held fixed include prevailing FDA labeling mandates, EU carbon disclosure timelines, and Southeast Asian cold-chain infrastructure buildout rates; variables tested include edible oil price volatility scenarios and automation adoption curves. Segmentation dimensions span cut geometry, end-user channel, packaging format, and distribution mode, with regional regulatory clusters modeled separately. CAGRs derive from installed capacity expansion schedules cross-referenced with quick-service restaurant procurement forecasts, incorporating fryer-margin sensitivity to input cost swings and throughput constraints from lower-temperature acrylamide mitigation protocols.
Macroeconomic conditions sit as an overlay; deviation in Indonesian rupiah stability, Vietnamese dong exchange rates, or EU carbon border adjustment implementation would shift the trajectory. Cross-checking against quick-service restaurant capital expenditure disclosures and cold-chain infrastructure investment databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Dehydrated Food Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
Dehydrated Potato Products Market
Processed and Frozen Foods
Icebreakers Market
Processed and Frozen Foods
South America RTE Food Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Frozen Processed Meat Market
Processed and Frozen Foods
Freeze Dried Vegetables Market
Processed and Frozen Foods
Frozen-Cooked Ready Meals Market
Processed and Frozen Foods
South America Freeze Dried Products Market
Processed and Frozen Foods
Taiyaki Ice Cream Market
Processed and Frozen Foods
Kimchi Market
Processed and Frozen Foods
Frozen Cheese Market
Processed and Frozen Foods
Freeze Dried Melt Market
Processed and Frozen Foods
North America Frozen Desserts Market