
 Global Gluten-Free Breakfast Cereals Market | 2026-2036
Global Gluten-Free Breakfast Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gluten-Free Breakfast Cereals Market Foresight
Australia is narrowing its gluten-free oat processing capacity gap through dedicated milling infrastructure in Victoria and New South Wales. General Mills leverages its supply chain scale to secure certified gluten-free grain streams across North American facilities. Kellogg Company anchors its competitive stance through R&D intensity focused on extruded flake textures that replicate conventional cereal mouthfeel. Nature's Path Foods differentiates via organic-gluten-free dual certification that commands shelf space in premium channels.
Gluten-free breakfast cereals comprise grain-based formulations processed to eliminate wheat, barley, and rye proteins while retaining structural integrity through alternative binders and extrusion parameters. Manufacturers typically achieve sub-20 ppm gluten thresholds using segregated facilities, validated cleaning protocols, and enzymatic degradation steps to meet clinical safety standards for celiac patients. Flakes and granola categories dominate current revenue pools due to established consumer familiarity and broader distribution penetration, while puffs and clusters represent faster-growing segments as texture innovation attracts younger demographics and athlete-oriented buyers. Stand-up pouch packaging gains traction among online retailers seeking reduced shipping cube and shelf-ready presentation.
The FDA enforces its gluten-free labeling rule through facility audits and product testing requirements that shape formulation decisions and capital allocation for US-market entrants. EFSA coordinates with national bodies including Germany's BfR to harmonize maximum gluten thresholds across EU member states, creating a dual compliance burden for exporters. Australia's FSANZ mandates explicit allergen declarations that influence label design and consumer communication strategies. Stakeholders must monitor evolving Codex Alimentarius revisions and emerging grain-adjacent protein regulations that could redefine permissible ingredient boundaries.
Market Dynamics
Segregated milling infrastructure is compressing the cost premium between certified gluten-free oats and conventional grains, forcing manufacturers to rebuild sourcing networks around dedicated supply chains rather than shared facilities.
Growth Catalysts
- Celiac Diagnosis Expansion:Germany's BfR and Australia's TGA have streamlined diagnostic protocols, expanding the clinical patient pool requiring certified products. Retailers in Sydney and Melbourne now allocate expanded shelf space to sub-20 ppm formulations.
- FDA Gluten-Free Labeling Rule:The enforcement mechanism mandates facility audits and product testing that lock in formulation standards. US-market entrants must allocate capital to validated cleaning protocols and enzymatic degradation steps.
- Extrusion Texture Engineering:Advanced screw configurations and die designs now replicate conventional flake mouthfeel without wheat gluten. Athlete-oriented buyers and younger demographics are migrating toward these improved sensory profiles.
Market Restraints
- Certified Oat Supply Concentration:Victoria and New South Wales host Australia's limited dedicated gluten-free oat milling capacity. Crop rotation requirements and field segregation protocols constrain volume expansion.
- Input Cost Volatility:Sorghum and millet prices fluctuate with drought cycles in the US Great Plains and Argentine Pampas. Alternative grain procurement requires multi-origin hedging strategies.
- Cross-Contamination Liability:Shared transport and storage infrastructure for conventional grains creates persistent detection risk. Insurance premiums for sub-20 ppm certification have climbed substantially.
Strategic Opportunities
- Stand-Up Pouch Channel Expansion:E-commerce fulfillment networks favor reduced shipping cube and shelf-ready presentation. Direct-to-consumer platforms bypass traditional retail slotting fee structures.
- Organic-Gluten-Free Dual Certification:Premium channel buyers in Germany and the United States pay measurable premiums for combined USDA Organic and certified gluten-free labeling. This positioning secures placement in natural food cooperatives and specialty grocers.
- Puffs and Clusters Texture Innovation:Younger demographics and athlete-oriented buyers are migrating toward these faster-growing segments. Extruded protein-fortified formats open adjacent positioning in sports nutrition aisles.
Industry Challenges
- Segregated Facility Capex Requirements:Greenfield gluten-free production lines demand dedicated extruders, conveyors, and packaging equipment. Retrofitting existing plants triggers extended downtime and revenue loss.
- Multi-Jurisdiction Label Compliance:EFSA's harmonization efforts with Germany's BfR, Australia's FSANZ explicit allergen declarations, and FDA audit requirements create divergent specification sheets. SKU proliferation strains inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gluten-Free Breakfast Cereals Market |
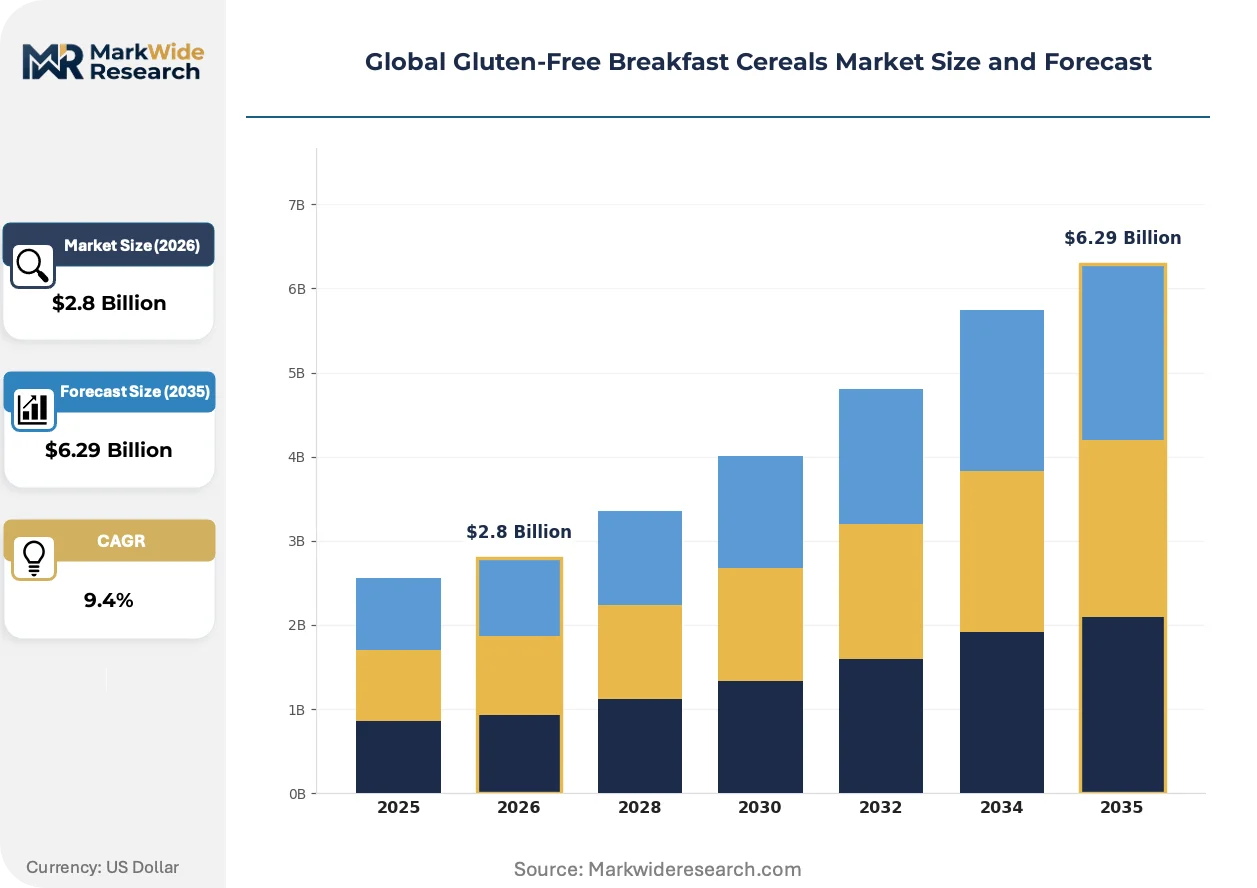
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Puffs, Granola, Muesli, Clusters Packaging Type: Box, Bag, Plastic Container, Stand-up Pouch, Carton Sales Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores, Specialty Shops Customer Type: Children, Adults, Athletes, Health-conscious Consumers, Seniors |
| Companies Covered | General Mills, Kellogg Company, Nestle, Bob’s Red Mill Natural Foods, Nature's Path Foods, Purely Elizabeth, Hometown Food Company, Quaker Oats Company, Barbara’s, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gluten-Free Breakfast Cereals Market Shifts & Advancements
Digital traceability systems and enzymatic processing advances are compressing the cost-quality trade-off that has historically limited gluten-free cereal penetration beyond the celiac-diagnosed population.
Near-infrared spectroscopy paired with blockchain ledgering is digitizing origin verification for certified gluten-free grain streams. Large-format retailers in the United States and Germany are mandating this transparency layer for supplier qualification. The technology is compressing audit timelines from weeks to hours while reducing third-party certification costs.
EFSA's coordination with national bodies to harmonize maximum gluten thresholds is tightening specification convergence across EU member states. Exporters face dual compliance burdens as Germany's BfR maintains stricter interpretive guidance than southern European regulators. Flake and granola categories with established EU distribution are absorbing the bulk of reformulation costs.
Athlete-oriented buyers are compressing purchase cycles toward protein-fortified clusters and puffs with clean-label positioning. Sports nutrition channels and specialized e-commerce platforms are displacing conventional grocery as the primary discovery venue. This rotation is most visible in Australia, where Melbourne-based subscription services now capture substantial recurring revenue from performance-focused consumers.
Global Gluten-Free Breakfast Cereals Market Segmentation
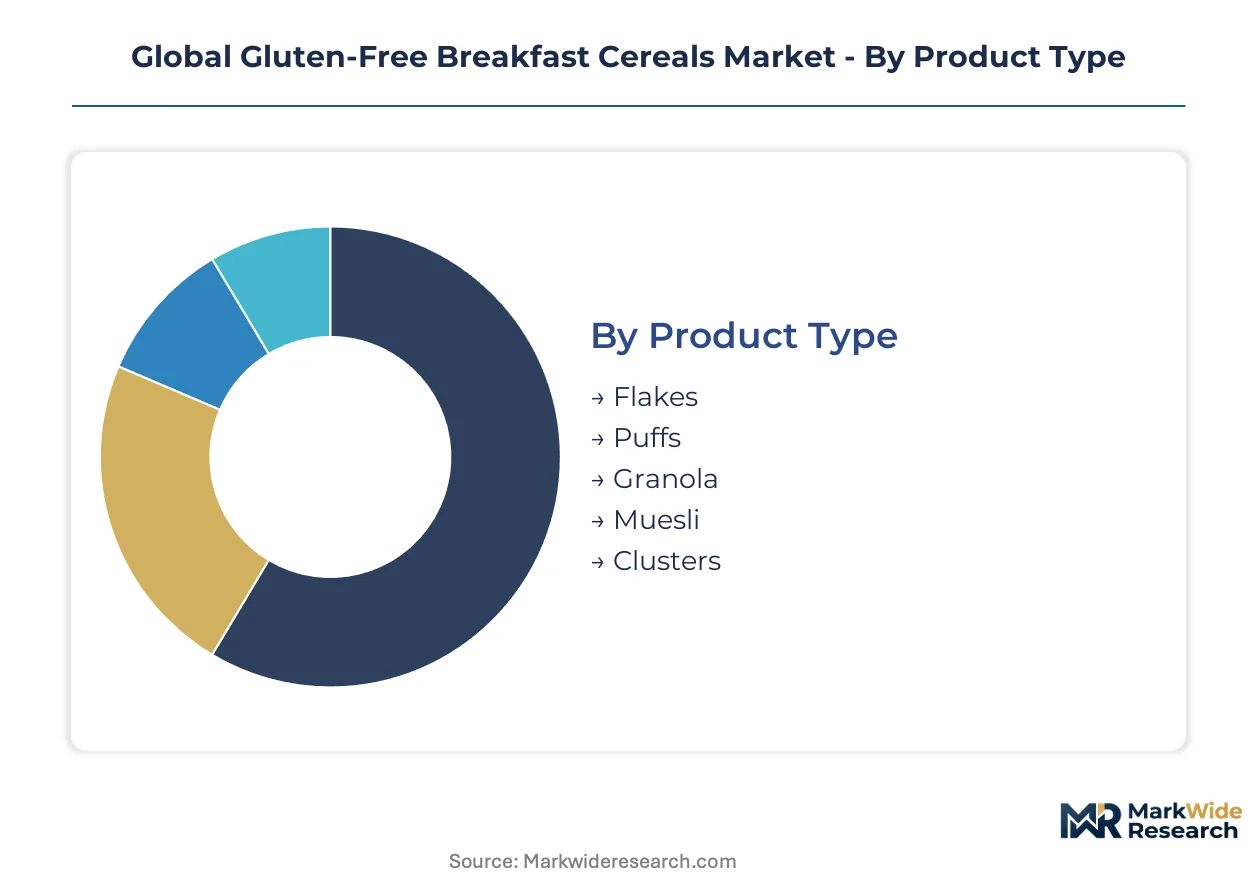
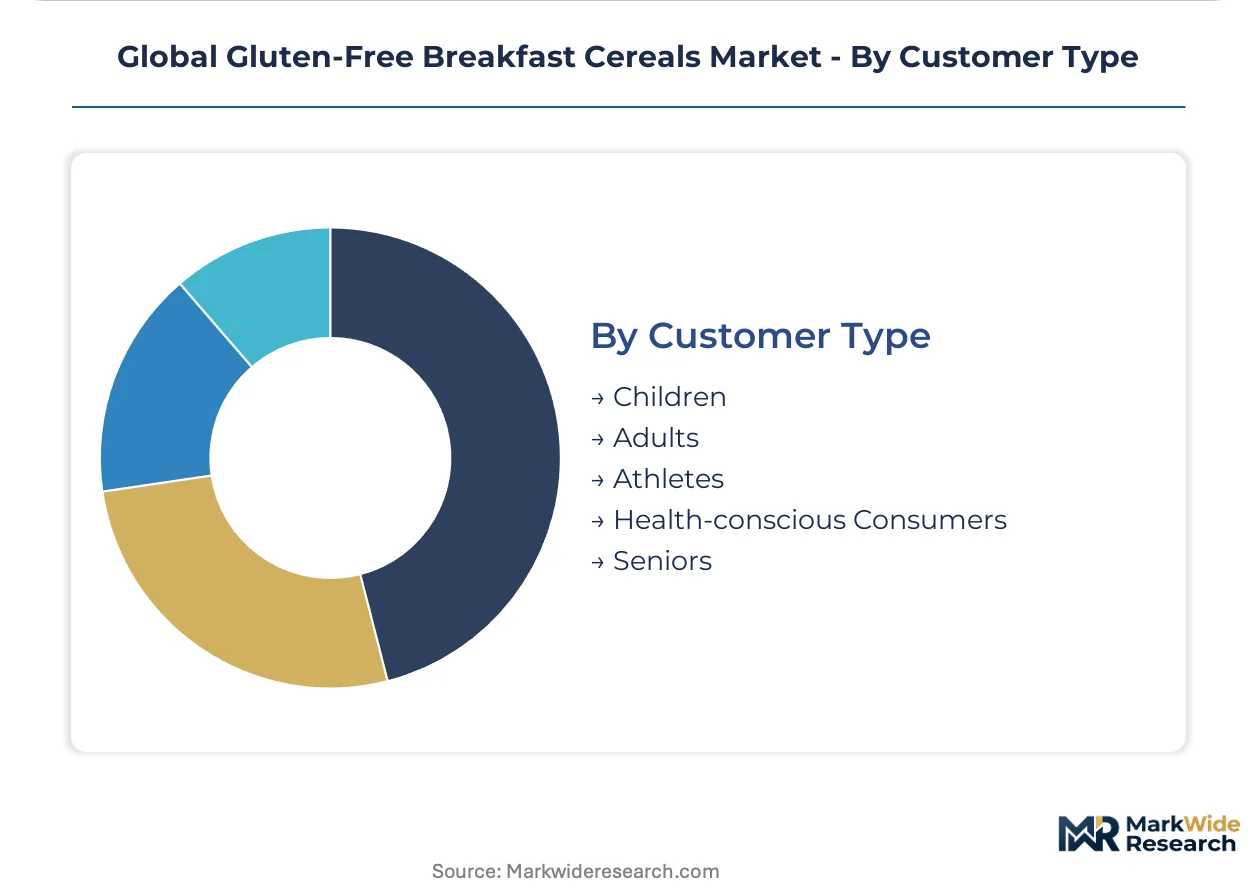
Segmentation in the gluten-free breakfast cereals market reveals distinct demand pockets shaped by sensory preference, channel access, and health motivation. Manufacturers configure formulation, packaging, and positioning strategies around these divides to capture price premiums and secure retail placement.
Product Type:
Mature formats anchor revenue while engineered textures unlock incremental volume among experience-seeking buyers.
- Flakes:Extruded grain sheets bound with modified starches and hydrocolloid systems to replicate wheat-based structural integrity. Demand concentrates in Germany and the United States where established brands have secured permanent shelf sets in conventional grocery. FDA gluten-free labeling compliance has locked in sub-20 ppm thresholds as the baseline specification.
- Puffs:High-expansion extrudates with aerated cellular structures achieved through specialized die configurations and moisture control. Australia's athlete-oriented subscription services in Melbourne and Sydney are driving fastest uptake for protein-fortified variants targeting sports nutrition channels.
- Granola:Baked clusters of certified gluten-free oats, nuts, and binders requiring segregated milling infrastructure. Victoria and New South Wales processing capacity constraints limit supply elasticity.
- Muesli:Unbaked blends of gluten-free grains, dried fruits, and seeds with minimal processing. German health food cooperatives favor organic-gluten-free dual certification variants.
- Clusters:Agglomerated bite-sized formats with binding syrups and texture-modified inclusions. Younger demographics in US coastal metros are migrating toward these portable formats.
Flakes retain volume leadership; Puffs hold the steepest expansion curve.
Packaging Type:
Cost-to-serve economics and channel-specific handling requirements dictate format selection across the value chain.
- Box:Paperboard cartons with inner liner bags dominating conventional retail shelf presentation. US supermarkets and German mass-market chains mandate this format for planogram compliance and stacking efficiency.
- Bag:Flexible film pouches offering lower unit economics for value-tier positioning. Australian discount channels and US club stores utilize multi-serve bag formats for volume-oriented shoppers.
- Plastic Container:Rigid PET or PP vessels with resealable closures for extended freshness claims. Premium positioning in US specialty grocers and German organic retailers supports price premiums.
- Stand-up Pouch:Gusseted flexible packaging with zipper closures optimized for reduced shipping cube and shelf-ready presentation. E-commerce fulfillment networks favor this format for direct-to-consumer logistics efficiency.
- Carton:Sustainable fiber-based alternatives to conventional boxes gaining traction in European markets with packaging waste regulations. German retailers are piloting these for environmental credential differentiation.
Box formats dominate retail throughput; Stand-up Pouch is expanding most quickly in digital channels.
Sales Channel:
Customer acquisition economics and margin structure vary sharply across physical and digital touchpoints.
- Supermarkets:High-velocity conventional grocery with slotting fee barriers and planogram-driven assortment decisions. US and German chains allocate expanded shelf space to certified gluten-free sections.
- Health Food Stores:Specialty retail with educated staff and organic-gluten-free dual certification focus. Australian independent retailers in Melbourne and Sydney cluster these products in dedicated allergen-free zones.
- Online Retailers:Direct-to-consumer platforms and marketplace aggregators bypassing traditional retail economics. Subscription services are capturing recurring revenue from performance-focused Australian consumers.
- Convenience Stores:Impulse-oriented limited assortment with single-serve and grab-and-go formats. US urban locations are testing gluten-free cereal bars as adjacent category extensions.
- Specialty Shops:Celiac-focused boutiques and natural food cooperatives with diagnostic community ties. German cooperatives maintain strict supplier qualification around EFSA threshold compliance.
Supermarkets retain volume leadership; Online Retailers are climbing the fastest.
Customer Type:
Health motivation spectrum ranges from clinical necessity to lifestyle optimization, shaping formulation intensity and price tolerance.
- Children:Pediatric celiac patients and parents seeking school-safe options driving fortified, palatable formats. US and German regulatory frameworks for child-targeted nutrition claims constrain marketing approaches.
- Adults:Broadest segment spanning diagnosed celiac, gluten sensitivity, and discretionary wellness buyers. Australian and US metropolitan markets show highest concentration of non-diagnosed wellness-motivated purchasers.
- Athletes:Performance-oriented consumers demanding protein-fortified, low-glycemic formulations. Melbourne-based subscription services and US sports nutrition channels are displacing conventional grocery for this cohort.
- Health-conscious Consumers:Wellness-motivated buyers without clinical diagnosis seeking perceived digestive benefits. German organic retailers capture this segment through dual certification premiums.
- Seniors:Aging populations with emerging celiac diagnosis and texture-modified requirements. US healthcare channel partnerships are exploring institutional formats for this demographic.
Adults retain volume leadership; Athletes are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container terminals anchor European gluten-free grain import flows, while Union Pacific's dedicated grain corridors connect US Plains oat production to West Coast processing clusters.
United States
Health-conscious consumers in coastal metros drive certified gluten-free granola purchases through direct-to-consumer channels. The FDA enforces gluten-free labeling through facility audits and product testing mandates. Minneapolis-St. Paul hosts General Mills' supply chain operations securing certified grain streams across North American facilities.
Germany
German health food cooperatives expand shelf space for organic-gluten-free dual certification variants. EFSA coordinates with Germany's BfR to harmonize maximum gluten thresholds across EU member states. Berlin-Brandenburg retailers pilot sustainable fiber-based carton packaging for environmental credential differentiation.
Australia
Melbourne-based subscription services capture substantial recurring revenue from athlete-oriented buyers seeking protein-fortified clusters. FSANZ mandates explicit allergen declarations influencing label design strategies. Victoria and New South Wales processing infrastructure narrows the gluten-free oat milling capacity gap through dedicated facilities.
Canada
Health Canada maintains strict gluten-free threshold alignment with Codex Alimentarius revisions shaping formulation standards. Toronto and Vancouver specialty grocers allocate expanded sections to certified sub-20 ppm formulations. Prairie Province oat growers develop segregated field protocols for export-grade certified grain supply.
Global Gluten-Free Breakfast Cereals Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and processing technology supply. The vendor base spans multinational food conglomerates with dedicated gluten-free divisions and mid-scale organic specialists with dual certification positioning. Three archetypes dominate: supply chain scale operators, organic-gluten-free dual certifiers, and athlete-oriented texture innovators. Competitive moves concentrate on segregated facility capex deployment and e-commerce channel expansion bypassing traditional retail slotting economics.
Within the scale-operator tier, General Mills and Kellogg Company occupy positions anchored by North American milling infrastructure and extrusion R&D intensity. Nature's Path Foods exemplifies the dual-certification archetype commanding premium shelf space in natural food cooperatives. Bob's Red Mill Natural Foods represents heritage-positioned specialists with vertically integrated grain sourcing.
| Leading Market Players |
|---|
| General Mills |
| Kellogg Company |
| Nestle |
| Bob's Red Mill Natural Foods |
| Nature's Path Foods |
| Purely Elizabeth |
| Hometown Food Company |
| Quaker Oats Company |
| Barbara's |
| Others |
Supply & Pricing Matrix
Single-source dependency on Victoria and New South Wales milling infrastructure compresses pricing tier spreads while forcing supply chain consolidation around dedicated gluten-free oat corridors rather than shared grain handling networks.
Pricing Analysis
Volume-discount tiering structures separate organic-gluten-free dual certification premiums from standard certified formulations and value-tier private label alternatives. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with German health food cooperatives and US coastal metros absorbing the steepest premiums. Cost compression in the economy tier is intensifying because Australian discount channels and US club stores are consolidating procurement around multi-serve bag formats. Athlete-oriented buyers through Melbourne subscription services show the least price sensitivity, while German mass-market chains and Australian discount channels exhibit the highest.
Supply Chain Analysis
Contract manufacturing concentration sits with General Mills' North American milling network and Kellogg Company's extrusion R&D facilities, with secondary capacity at Nature's Path Foods' dedicated organic-gluten-free plants. Geographic supply concentrates in the United States, Germany, and Australia, with raw material dependencies on certified gluten-free oats from Prairie Province growers, sorghum from the US Great Plains, and millet from Argentine Pampas. Single-source vulnerability in Victoria and New South Wales oat milling creates persistent detection risk for cross-contamination. Distribution runs through Union Pacific's dedicated grain corridors connecting Plains production to West Coast processing clusters, with final-mile e-commerce fulfillment bypassing traditional retail slotting economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story where athlete-oriented subscription services and protein-fortified texture formats are accelerating penetration beyond the clinically diagnosed population into discretionary wellness segments.
For Market Incumbents: Pre-empt private label encroachment by locking exclusive supply agreements with Prairie Province oat growers and accelerating segregated facility capex deployment ahead of FDA audit requirement tightening. Vertical integration into certified gluten-free grain sourcing secures margin position against commodity volatility in sorghum and millet markets. For New Entrants and Emerging Players: Melbourne-based athlete-oriented subscription services represent the most penetrable entry point for protein-fortified cluster formats displacing conventional grocery discovery. German health food cooperatives seeking organic-gluten-free dual certification variants offer secondary white-space with measurable premium capture. Direct-to-consumer platform launch bypasses supermarket slotting fee barriers and shelf-ready presentation requirements. For Investors and Strategic Acquirers: FDA gluten-free labeling rule enforcement reshapes the acquisition landscape toward targets with validated cleaning protocols and enzymatic degradation capabilities already operational. Long-term viability centers on segregated facility infrastructure rather than shared-line retrofitting. The signal to watch is FSANZ explicit allergen declaration harmonization with EFSA thresholds, which would trigger SKU consolidation among multi-jurisdiction exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Segregated Facility Capex Deployment | Greenfield gluten-free production lines with dedicated extruders and conveyors lock in FDA sub-20 ppm compliance ahead of audit tightening. |
| Direct-to-Consumer Channel Launch | Stand-up pouch formats optimized for reduced shipping cube bypass supermarket slotting fees and capture recurring subscription revenue. |
| Organic-Gluten-Free Dual Certification | USDA Organic combined with certified gluten-free labeling secures permanent shelf sets in German health food cooperatives and US specialty grocers. |
| Protein-Fortified Texture Innovation | Extruded protein-fortified clusters and puffs open adjacent positioning in sports nutrition aisles and Melbourne-based athlete subscription services. |
| Certified Grain Stream Integration | Backward integration into Prairie Province oat grower partnerships with segregated field protocols secures export-grade certified supply against Victoria capacity constraints. |
Research Methodology
Operator-level perspectives from brand managers at multinational food conglomerates, category buyers at US and German retail chains, supply planners at certified gluten-free milling facilities, and channel sales heads at natural food cooperatives anchored the qualitative base. Primary interviews combined with secondary validation from FDA gluten-free labeling rule documentation, EFSA harmonization guidance, FSANZ allergen declaration standards, and Nielsen retail audit data. Bottom-up and top-down triangulation cross-checked volume assumptions against grain procurement disclosures and extrusion capacity utilization.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions modeling product type, packaging format, sales channel, and customer health motivation spectrum. CAGRs derived from historical certified gluten-free oat consumption patterns, celiac diagnosis rate trajectories in Germany and Australia, and athlete-oriented buyer migration toward sports nutrition channels. Forecast inputs incorporated extrusion texture engineering adoption curves and stand-up pouch e-commerce penetration rates.
Stress conditions across sorghum and millet drought-cycle volatility, FDA audit enforcement intensity, and EFSA threshold harmonization timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on segregated facility capex deployment schedules and subscription service customer acquisition economics. Quarterly review of certified oat milling capacity utilization in Victoria and New South Wales, protein-fortified format sell-through rates in Australian sports nutrition channels, and German cooperative shelf space allocation shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Jams and Spreads Market
Packaged Foods
US Canned Foods Market
Packaged Foods
Canned Pasta Market
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
Food and Beverages Market
Packaged Foods
Injectable Cocoa Fillings Market
Packaged Foods
Ready Meal Trays Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Protein Packed Foods Market
Packaged Foods
Wet Pet Food Market
Packaged Foods
Tortilla Market
Packaged Foods
Instant Noodles Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
Canned Goods Market
Packaged Foods
Organic Energy Bar Market